
 Industrial Diesel Turbocharger Market | 2026-2036
Industrial Diesel Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Diesel Turbocharger Market Outlook
Scarce turbocharger aerodynamicist talent is redrawing competitive boundaries across the industrial diesel segment. BorgWarner Inc leverages its in-house compressor wheel casting expertise to anchor supply agreements with European power generation OEMs. Cummins Inc sustains vertical integration from turbine housing machining to full system calibration, controlling cost structures that competitors struggle to match. Garrett Motion Inc specializes in electrically assisted architectures, positioning its portfolio for hybridized industrial powertrains.
An industrial diesel turbocharger is a forced induction device that compresses intake air to 2-4 bar absolute pressure before it enters the combustion chamber, raising engine power density without proportional displacement growth. Its primary industrial purpose is to enable heavy-duty diesel engines to meet stringent emissions standards while maintaining torque output for mining haul trucks, marine propulsion, and stationary gensets. Variable geometry turbochargers command the largest product type share because their adjustable vane angles optimize boost across the full load spectrum of construction vehicles and agricultural equipment. Electrically assisted turbochargers represent the fastest-growing technology segment, as their integrated motor generators eliminate turbo lag in intermittent-load applications like oil & gas fracturing pumps. Charge air cooling sits at the center of margin pools, since intercooler efficiency directly determines whether engines can run higher compression ratios without thermal knock.
EPA Tier 4 Final and EU Stage V emissions frameworks mandate particulate matter and NOx limits that force engine builders to adopt higher-pressure turbocharging with exhaust gas recirculation integration. China's MIIT enforces GB 20891 fuel consumption standards for non-road mobile machinery, accelerating local demand for variable nozzle turbochargers with precision electronic actuators. Japan's METI promotes carbon neutrality roadmaps that incentivize turbo efficiency improvements in marine and power generation sectors. Stakeholders must monitor how tightening NOx corridors in multiple jurisdictions reshape R&D allocation between mechanical wastegate simplicity and electronically controlled variable geometry complexity.
Market Dynamics
Variable geometry turbocharger architectures are forcing a recalibration of supplier capabilities across the industrial diesel segment, as precision electronic actuation replaces mechanical wastegate simplicity in mining haul trucks and marine propulsion systems.
Growth Catalysts
- EPA Tier 4 Final:Particulate matter and NOx limits in the US mandate higher-pressure turbocharging with exhaust gas recirculation integration, accelerating fleet retrofits in construction and agriculture.
- China's GB 20891:MIIT fuel consumption standards for non-road mobile machinery push local manufacturers toward variable nozzle turbochargers with precision electronic actuators.
- Marine rebuild cycles:Power generation and propulsion engine overhaul demand in Germany's Rhine-Ruhr corridor concentrates procurement for high-boost systems.
Market Restraints
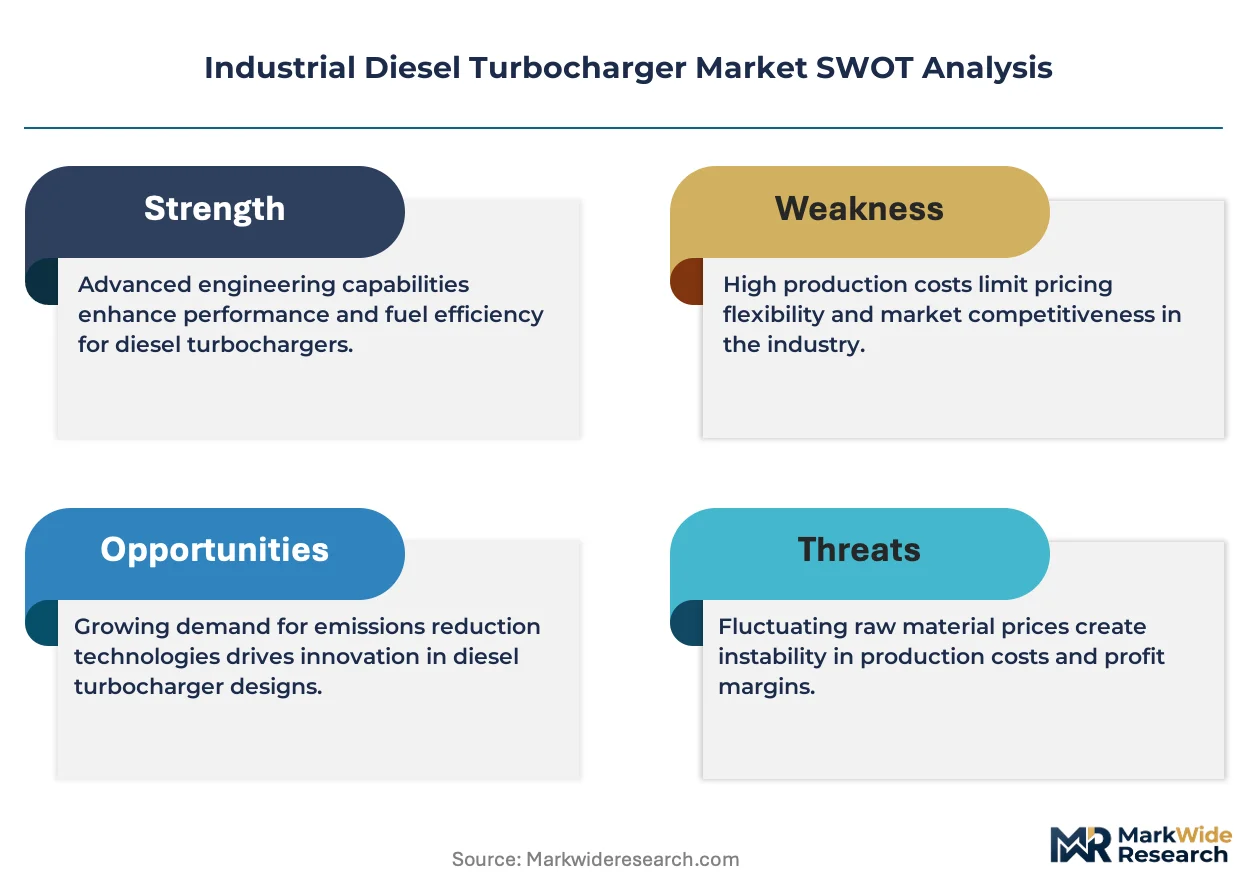
- Aerodynamicist talent scarcity:Compressor wheel design expertise concentrates within a handful of engineering clusters, constraining supplier expansion.
- Inconel superalloy pricing:Turbine housing material costs fluctuate with aerospace sector demand, pressuring margin structures for mid-tier manufacturers.
- EU Stage V compliance friction:The regulation's real-driving emissions testing protocols extend certification timelines by 8-14 months for new turbocharger architectures.
Strategic Opportunities
- Electrically assisted turbochargers:Hybridized industrial powertrains in oil and gas fracturing pumps eliminate turbo lag during intermittent load cycles.
- Australia mining retrofits:Tier 4 Final compliance deadlines for open-pit haul truck fleets create concentrated demand for high-boost system upgrades.
- Japan METI carbon neutrality roadmaps:Efficiency improvement incentives in marine and stationary power generation sectors favor advanced turbocharger adoption.
Industry Challenges
- Thermal management integration:Intercooler efficiency requirements for higher compression ratios demand coordinated engineering across engine and turbocharger suppliers.
- Electronic actuator calibration:Variable geometry vane angle precision requires software competencies that mechanical turbocharger specialists lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Diesel Turbocharger Market |
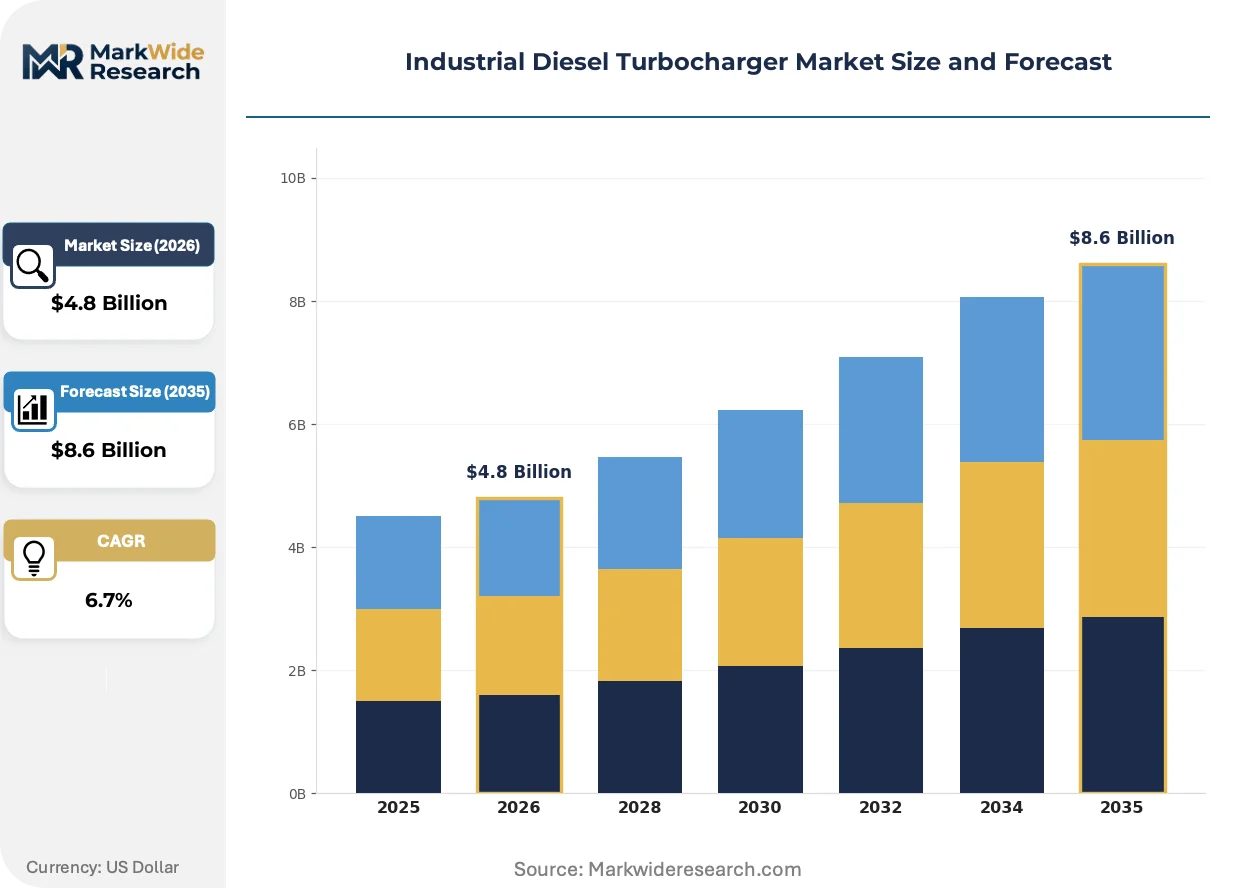
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Turbo, Twin Turbo, Variable Geometry Turbocharger, Electrically Assisted Turbocharger End User: Heavy Machinery, Agricultural Equipment, Marine Vessels, Construction Vehicles Application: Power Generation, Transportation, Oil & Gas, Mining Technology: Variable Nozzle, Wastegate Turbocharger, Exhaust Gas Recirculation, Charge Air Cooling |
| Companies Covered | Cummins Inc, BorgWarner Inc, Honeywell International Inc, Mitsubishi Heavy Industries Ltd, IHI Corporation, Garrett Motion Inc, ABB Ltd, Continental AG, Napier Turbochargers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Diesel Turbocharger Market Strategic Shifts
Electrification of turbocharger architectures is compressing the traditional mechanical supply base while opening new margin pools in motor-generator integration and thermal management systems.
Electrically assisted turbochargers combine high-speed motor generators with conventional turbine-compressor layouts to eliminate lag during transient load conditions. Mining operators in Chile and Australia are specifying these systems for haul truck applications where altitude and load variability strain conventional boost response. This architecture is displacing pure mechanical turbos in intermittent-duty industrial segments where torque response determines equipment productivity.
China's MIIT is tightening enforcement of GB 20891 fuel consumption limits through expanded testing protocols for off-road diesel equipment. The regulation forces domestic engine builders to abandon fixed-geometry turbochargers in favor of electronically controlled variable nozzle designs. Agricultural equipment manufacturers in Shandong and Jiangsu provinces are accelerating supplier qualification timelines to meet the 2026 compliance window.
Aftermarket procurement for charge air cooling systems is fragmenting as power generation operators unbundle intercooler replacement from full turbocharger rebuilds. Independent service providers in Germany's industrial corridor are capturing margin previously held by OEM distribution networks. This pattern is most visible in marine engine maintenance, where ship operators in Hamburg and Rotterdam ports now source intercoolers through specialized thermal management distributors rather than integrated turbocharger suppliers.
Industrial Diesel Turbocharger Market Segmentation
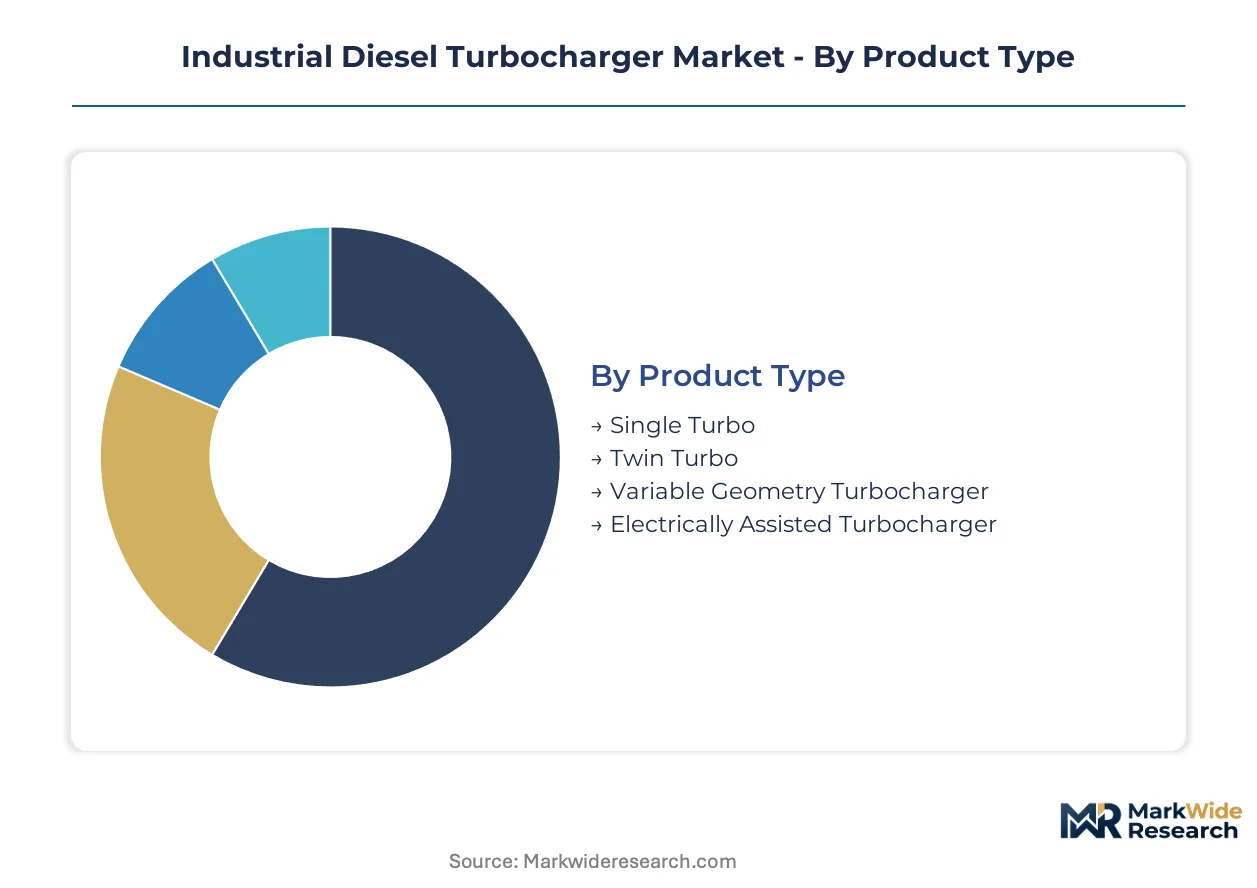
Turbocharger segmentation in industrial diesel applications determines procurement channel strategy, with OEM direct sales dominating high-complexity variable geometry systems while aftermarket distributors capture replacement cycles in mature mechanical architectures. Understanding how product complexity, end-use duty cycles, and regional regulatory pressures fragment demand enables suppliers to align engineering resources with margin concentration points.
Product Type:
Channel strategy diverges sharply between electronically actuated systems requiring OEM calibration partnerships and mechanical designs flowing through independent distributors.
- Variable Geometry Turbocharger:Adjustable vane angles optimize boost pressure across load spectrums from idle to peak output. Mining haul trucks in Australia's Pilbara region and Chile's Atacama operations specify these systems to meet Tier 4 Final emissions mandates without sacrificing altitude performance.
- Electrically Assisted Turbocharger:Integrated motor-generator architectures eliminate turbo lag during transient load conditions. Oil and gas fracturing pump operators in North American shale basins are specifying these for intermittent-duty cycles where torque response determines equipment productivity.
- Single Turbo:Fixed-geometry mechanical designs serve cost-sensitive stationary power generation in emerging markets where emissions enforcement remains limited.
- Twin Turbo:Sequential or parallel compressor arrangements address high-boost requirements in marine propulsion systems above 2,000 kW output.
Variable geometry turbochargers dominate installed base across regulated markets. Electrically assisted architectures are where expansion concentrates as hybridized industrial powertrains gain specification.
End User:
Customer type determines pricing tolerance and service bundling, with marine operators accepting premium lifecycle contracts while construction fleets prioritize acquisition cost.
- Heavy Machinery:Mining haul trucks and material handlers above 350 kW require high-boost systems with integrated exhaust gas recirculation. Fleet operators in Germany's Rhine-Ruhr corridor are accelerating rebuild cycles for Stage V compliance.
- Construction Vehicles:Excavators and wheel loaders face intermittent load profiles favoring rapid spool-up characteristics. China's construction equipment manufacturers in Shandong province are qualifying variable nozzle suppliers for GB 20891 fuel consumption compliance.
- Marine Vessels:Propulsion and auxiliary genset applications demand salt-air corrosion resistance and extended service intervals.
- Agricultural Equipment:Seasonal duty cycles and price-sensitive owner-operators sustain demand for mechanical wastegate simplicity in lower-horsepower segments.
Heavy machinery commands the highest per-unit system values. Construction vehicles are expanding most quickly as China's infrastructure stimulus accelerates equipment replacement.
Application:
Application context dictates thermal management requirements and regulatory exposure, with stationary power generation facing localized emissions enforcement while mobile equipment confronts transnational standards.
- Power Generation:Stationary diesel gensets for backup and prime power require sustained high-load efficiency. Data center operators in Frankfurt and Amsterdam are specifying advanced intercooling for Tier 4 Final and Stage V compliance in critical infrastructure.
- Mining:Open-pit haul trucks operate at altitude with severe dust exposure. Australian operators are retrofitting high-boost systems to extend fleet life against Tier 4 Final deadlines.
- Transportation:Rail and heavy-haul trucking applications prioritize fuel efficiency over absolute power density.
- Oil & Gas:Fracturing and drilling equipment faces extreme load transients favoring electrically assisted turbo response.
Power generation maintains the largest cumulative installed capacity. Mining represents the steepest expansion trajectory as fleet retrofit deadlines concentrate demand.
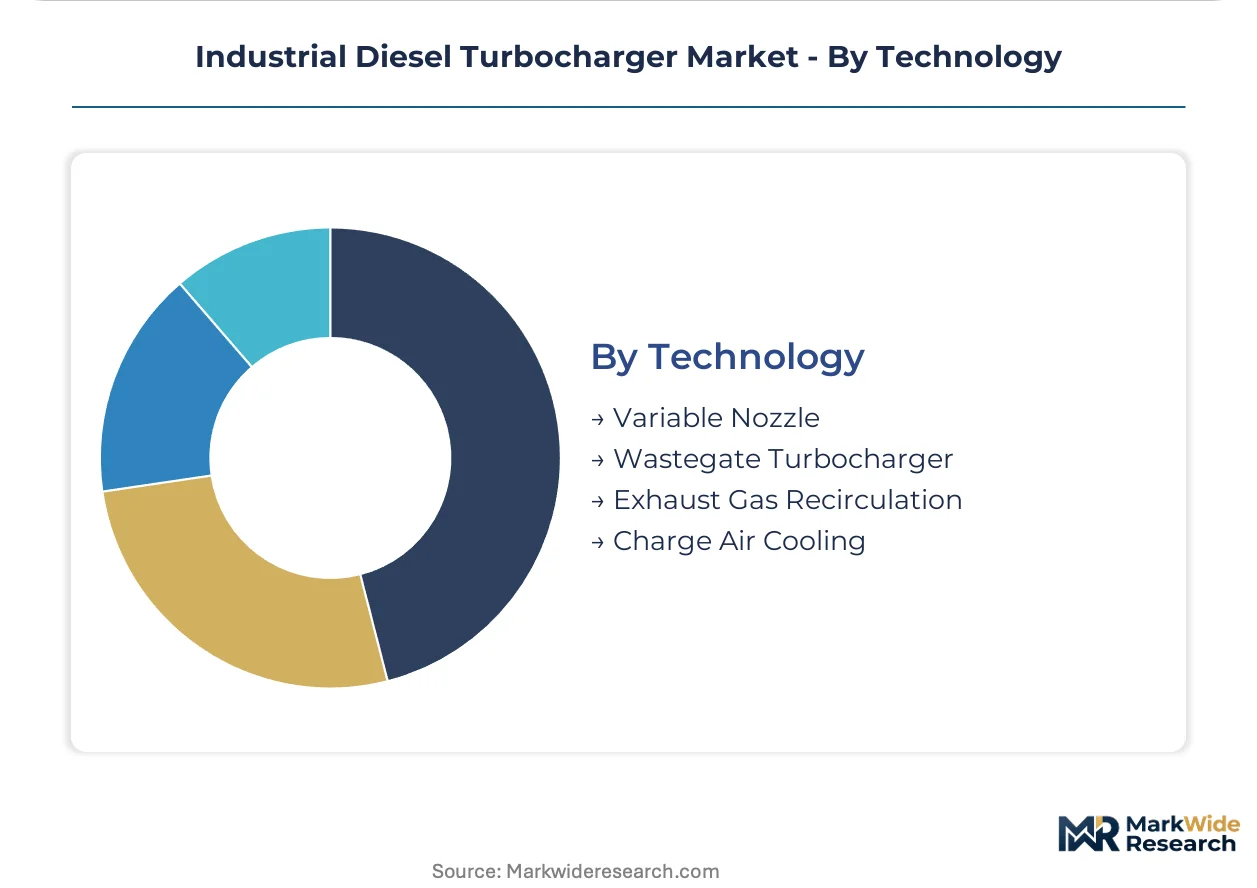
Technology:
Technology selection tracks regulatory stringency, with electronic actuation and thermal management systems commanding premium positioning as emissions corridors tighten.
- Variable Nozzle:Precision vane angle control enables optimal turbine geometry across engine speed ranges. China's MIIT is mandating this architecture for non-road mobile machinery through expanded GB 20891 testing protocols.
- Charge Air Cooling:Intercooler efficiency determines compression ratio limits and thermal knock margins. Independent service providers in Germany's industrial corridor are unbundling intercooler replacement from full turbocharger rebuilds.
- Wastegate Turbocharger:Mechanical bypass valves retain cost advantage in applications below current emissions thresholds.
- Exhaust Gas Recirculation:Integrated turbo-EGR systems address NOx reduction requirements in EPA and EU regulated markets.
Variable nozzle technology dominates new equipment specification in regulated jurisdictions. Charge air cooling is where aftermarket margin pools are restructuring as procurement fragments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia deploys turbocharger technology for altitude-compensated mining haulage, while Germany concentrates procurement around marine propulsion rebuilds and China's construction equipment sector drives variable geometry adoption for fuel efficiency mandates.
United States
Oil and gas fracturing operators in the Permian Basin specify electrically assisted turbochargers for intermittent load cycles. EPA Tier 4 Final enforcement accelerates fleet retrofits in construction and agriculture. Houston and Oklahoma City anchor procurement for high-boost systems serving shale extraction.
Germany
Marine engine rebuild cycles in the Rhine-Ruhr corridor concentrate demand for precision-machined turbine housings. EU Stage V real-driving emissions protocols extend certification timelines for new architectures. Hamburg and Bremen ports drive aftermarket procurement for salt-air corrosion-resistant systems.
China
Construction equipment manufacturers in Shandong and Jiangsu provinces qualify variable nozzle suppliers for GB 20891 compliance. MIIT fuel consumption testing protocols now cover expanded off-road machinery categories. Beijing-Tianjin-Hebei industrial clusters accelerate supplier audits ahead of 2026 deadlines.
Australia
Open-pit mining operators in the Pilbara region retrofit high-boost systems to extend haul truck fleet life. Tier 4 Final compliance deadlines for existing equipment concentrate demand through 2027. Perth engineering services clusters support rapid field installation of altitude-compensated turbocharger packages.
Japan
Marine and stationary power generation sectors pursue efficiency improvements under METI carbon neutrality roadmaps. Precision electronic actuator manufacturing concentrates in Nagoya industrial corridors. Osaka shipyards specify advanced thermal management integration for auxiliary genset applications.
Industrial Diesel Turbocharger Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling captive casting and machining capabilities that mid-scale competitors cannot replicate. The structure rewards backward integration into compressor wheel foundry operations and precision turbine housing production. Two dominant archetypes prevail: full-system integrators managing calibration through final assembly, and component specialists capturing margin in charge air cooling and electronic actuation. Competitive moves concentrate on technology licensing partnerships and geographic expansion through distributor qualification programs.
Among North American-integrated manufacturers, Cummins Inc and Garrett Motion Inc exemplify divergent strategic positioning within the full-system tier. Cummins Inc anchors its competitive stance through captive supply of machined turbine housings and in-house calibration protocols. Garrett Motion Inc occupies a position emphasizing electrically assisted architectures for hybridized powertrain applications. Japanese industrial conglomerates including Mitsubishi Heavy Industries Ltd and IHI Corporation represent the precision-manufacturing archetype, with their positioning reflecting long-cycle marine and power generation expertise.
| Leading Market Players |
|---|
| Cummins Inc |
| BorgWarner Inc |
| Honeywell International Inc |
| Mitsubishi Heavy Industries Ltd |
| IHI Corporation |
| Garrett Motion Inc |
| ABB Ltd |
| Continental AG |
| Napier Turbochargers Ltd |
| Others |
Value Chain & Pricing Dynamics
Ninety-day compressor wheel foundry lead times in Germany's Rhine-Ruhr corridor concentrate pricing power among suppliers with captive casting capabilities, while spot procurement for Inconel turbine housings exposes mid-tier manufacturers to aerospace sector demand fluctuations. Long-term offtake agreements for precision-machined components anchor cost predictability for integrated OEMs, whereas project-based purchasing dominates aftermarket rebuild cycles where mining operators unbundle intercooler replacement from full system procurement.
Pricing Analysis
Long-term offtake contracts dominate variable geometry turbocharger procurement between European power generation OEMs and integrated suppliers, while spot purchasing prevails in aftermarket charge air cooling segments. Price differentiation rests on electronic actuator calibration complexity and EPA Tier 4 Final certification grade, with mechanical wastegate architectures facing cost compression from Chinese manufacturers qualifying for GB 20891 compliance. Fleet operators in Australia's Pilbara region exhibit highest price sensitivity due to concentrated retrofit deadlines, while marine propulsion customers in Hamburg and Bremen accept premium lifecycle contracts for salt-air corrosion-resistant systems.
Supply Chain Analysis
Strategic stockpiling of Inconel superalloy ingots characterizes tier-one supplier behavior, contrasting with just-in-time inventory practices among aftermarket distributors serving fragmented agricultural equipment demand. Manufacturing concentration centers on Germany for precision turbine housing machining, Japan for electronic actuator production, and China for variable nozzle casting operations. Raw material dependencies include nickel-based superalloys for turbine wheels, aluminum alloys for compressor housings, and rare-earth elements for high-speed motor generators in electrically assisted architectures. Single-source vulnerability in precision vane angle sensor supply creates structural risk for variable geometry system delivery. Distribution runs through OEM direct channels for high-complexity systems and independent thermal management specialists for unbundled intercooler replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial diesel turbocharger incumbents face substitution pressure from electrified industrial powertrains and battery-electric mining equipment, requiring defensive repositioning around hybrid integration capabilities and thermal management expertise.
For Market Incumbents: Consolidate electronic actuator calibration competencies through acquisition of specialized software engineering firms, defending against Garrett Motion's electrically assisted architecture lead. Deepen backward integration into compressor wheel foundry operations to match BorgWarner's captive casting cost structures. Prioritize certification investment for EPA Tier 4 Final and EU Stage V compliance to maintain OEM direct channel access against emerging Chinese competitors.
For New Entrants and Emerging Players: Aftermarket service unbundling in Germany's marine engine corridor presents white-space opportunity where independent thermal management distributors capture intercooler replacement margin previously held by integrated suppliers. Target Australia's Tier 4 Final retrofit deadline concentration with rapid field installation capabilities for altitude-compensated high-boost systems. Pursue qualification partnerships with Shandong province construction equipment manufacturers facing accelerated GB 20891 compliance timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrically assisted turbocharger architectures as motor-generator integration and high-speed bearing technologies demand specialized manufacturing equipment. Five-to-ten year viability favors suppliers with hybrid powertrain calibration partnerships and precision electronic actuation capabilities. Acquisition target archetype: mid-scale component specialists with charge air cooling expertise and established distributor relationships in Germany's industrial corridor. Monitor Japan METI carbon neutrality roadmap implementation as signal for marine and stationary power generation efficiency investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Actuator Calibration Partnership | Variable geometry vane precision requires software competencies that mechanical specialists lack. |
| Backward Integration into Compressor Wheel Foundry | Captive casting capabilities anchor supply agreements with European power generation OEMs. |
| Electrically Assisted Architecture Development | Motor-generator integration eliminates turbo lag in oil and gas fracturing pump applications. |
| Aftermarket Service Unbundling | Independent intercooler replacement captures margin from integrated OEM distribution networks. |
| China GB 20891 Supplier Qualification | MIIT fuel consumption testing protocols accelerate variable nozzle adoption in construction equipment. |
Study Parameters
Initial hypotheses were tested against primary input from turbocharger system engineers, mining fleet maintenance directors, marine propulsion procurement managers, and power generation OEM technical leads, then refined through secondary validation. Bottom-up triangulation combined trade data from customs filings, EPA certification databases, and MIIT fuel consumption test records with top-down macroeconomic indicators for industrial capital equipment investment. Secondary sources included SEC 10-K disclosures from listed suppliers, EU Stage V regulatory impact assessments, and Japan METI carbon neutrality roadmap documentation.
Variance decomposition across product type, end-user segment, application context, and regional regulatory cluster shaped the analytical framework for volume and value outputs over the projection horizon. CAGRs were derived from segment-level demand modeling incorporating fleet replacement cycles, emissions compliance deadlines, and technology substitution elasticities. Industry-specific forecast inputs included mining haul truck altitude performance requirements and marine engine rebuild cycle timing in Northern European ports.
Forecasts assume regulatory continuity in EPA Tier 4 Final, EU Stage V, and China GB 20891 regimes; material policy shifts would require re-modeling. Specific risks include Inconel superalloy price volatility from aerospace demand competition and electronic actuator supply concentration in Japanese manufacturing corridors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Modular Belt Drive Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Automotive Water Pump Market
Powertrain
Gasoline Turbochargers Market
Powertrain
LNG Engine Market
Powertrain
Racing Clutches Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Engines Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Automotive Brake Booster Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Torque Limiter Market