
 Hybrid Powertrain Systems Market | 2026-2036
Hybrid Powertrain Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Powertrain Systems Market Analytics
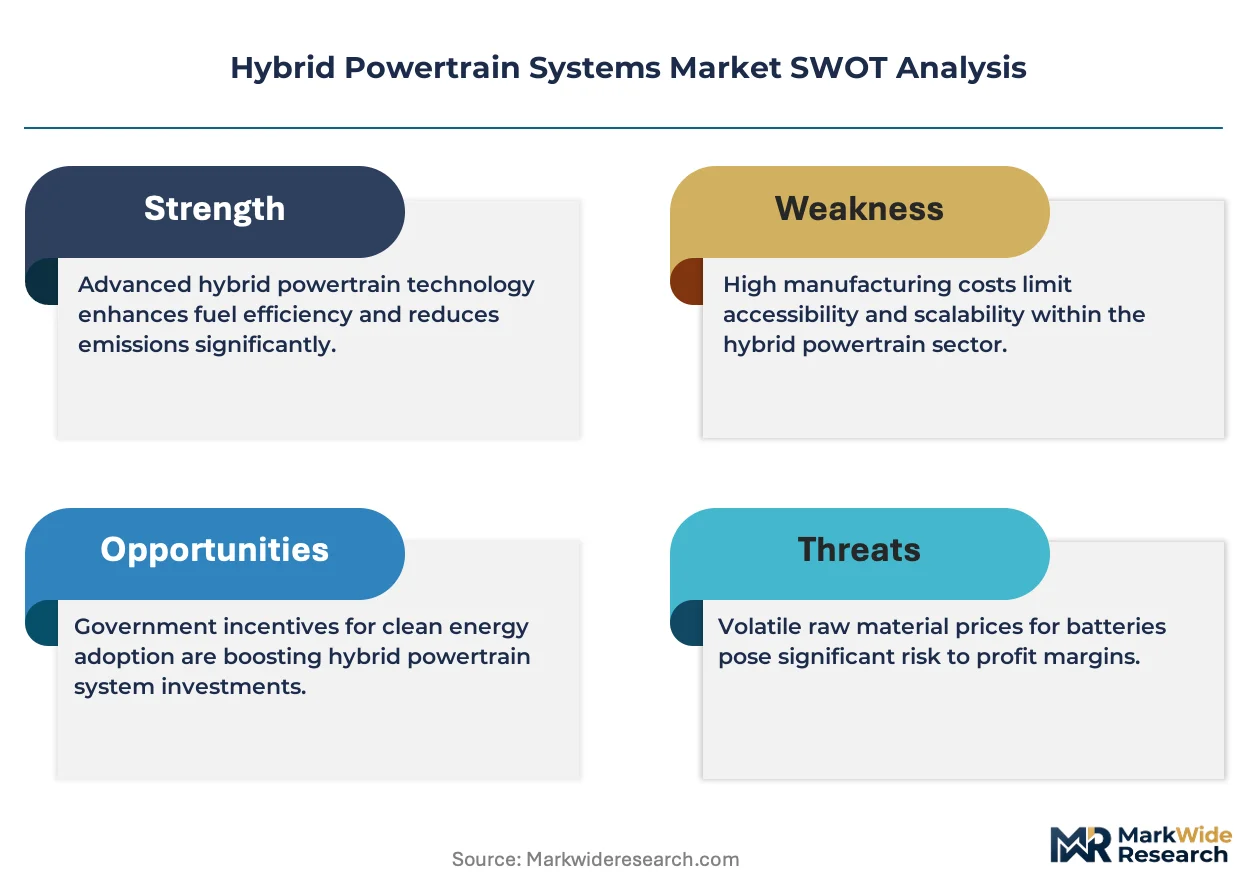
A capital-intensity divergence between integrated OEMs and component suppliers is bifurcating competitive dynamics in hybrid powertrain development. Toyota Motor Corporation leverages its two-decade Prius manufacturing heritage to sustain process leadership in nickel-metal hydride and lithium-ion battery pack integration. Robert Bosch GmbH anchors the European supply base with modular hybrid system architectures that it controls across multiple OEM programs. Hyundai Motor Company differentiates through dedicated hybrid transmission platforms that span its Kia and Genesis brand portfolios.
Hybrid powertrain systems combine an internal combustion engine with one or more electric motors, a traction battery, and a power-split or clutch-controlled transmission to optimize torque delivery and recapture kinetic energy through regenerative braking. The primary commercial purpose is reducing fuel consumption and tailpipe emissions without requiring external charging infrastructure dependency. Plug-in hybrid architectures are capturing disproportionate engineering investment as OEMs balance zero-emission urban compliance with long-range flexibility. Parallel hybrid configurations dominate commercial vehicle applications where sustained highway loads favor mechanical driveline efficiency. Regenerative braking technology leads the component margin pool due to its integration complexity and software-dependent calibration requirements.
The EPA tailpipe standards and the EU Green Deal fleet CO2 mandates are forcing powertrain diversification across all vehicle weight classes. NHTSA fuel economy rules and China's MIIT new-energy vehicle credit system create divergent certification pathways that OEMs must navigate simultaneously. Stakeholders must monitor how battery chemistry cost curves and combustion engine downsizing limits reshape the economic viability of mild versus full hybrid architectures.
Market Dynamics
Fleet CO2 mandates from the EU Green Deal and China's MIIT credit system are forcing powertrain diversification across vehicle weight classes, compressing development cycles and supplier consolidation timelines.
Growth Catalysts
- EU Green Deal fleet targets:Binding CO2 reduction requirements for commercial vehicle fleets are accelerating hybrid drivetrain procurement across European logistics operators.
- China MIIT new-energy vehicle credit system:Domestic OEMs must accumulate NEV credits through hybrid and electric production, creating guaranteed offtake for powertrain suppliers.
- Regenerative braking integration:Software-dependent calibration requirements for kinetic energy recovery are expanding engineering budgets and component margins.
Market Restraints
- Lithium-ion cell cost volatility:Raw material price swings for cathode minerals compress margin visibility for battery pack integrators.
- Japanese supplier concentration:Critical power-split transmission patents and manufacturing capacity cluster with a narrow base of incumbent producers.
- EPA tailpipe standard uncertainty:Shifting federal vehicle emission timelines in the United States create planning friction for multi-year platform investments.
Strategic Opportunities
- India commercial vehicle electrification:The country's PLI scheme for automotive components offers cost-offset pathways for hybrid system localization.
- Power-to-thermal convergence:Integration of battery thermal management with cabin heating systems opens new subsystem bundling potential.
- German KBA type-approval streamlining:Accelerated certification pathways for plug-in hybrid variants reduce time-to-market for modular architectures.
Industry Challenges
- Power electronics skill scarcity:Shortages of engineers proficient in inverter control algorithms and motor-generator matching constrain development throughput.
- Multi-homologation complexity:Simultaneous compliance with NHTSA fuel economy rules, EPA tailpipe standards, and EU WLTP testing cycles fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Powertrain Systems Market |
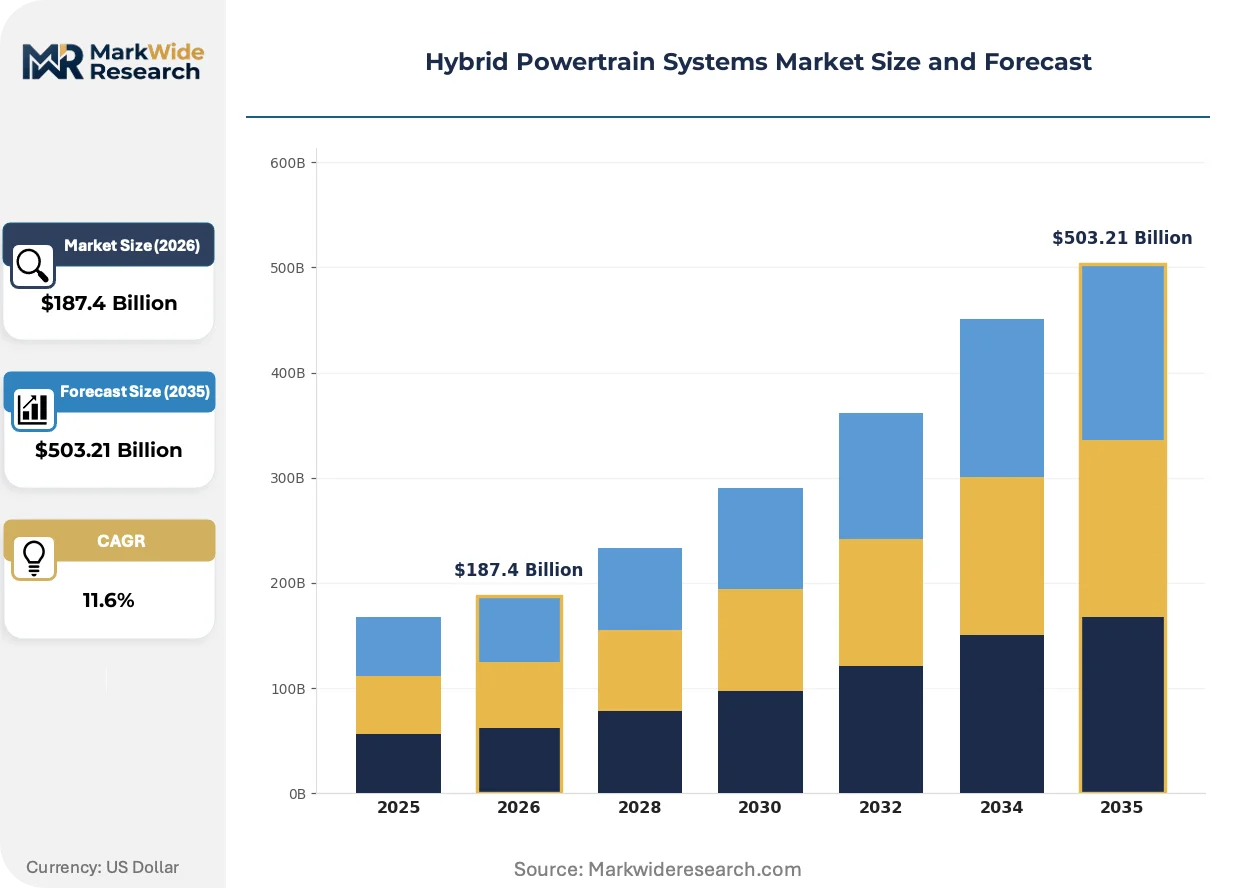
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Series Hybrid, Parallel Hybrid, Plug-in Hybrid, Mild Hybrid Technology: Battery Electric, Internal Combustion Engine, Fuel Cell, Regenerative Braking End User: OEMs, Automotive Manufacturers, Aftermarket Providers, Transportation Sector Application: Passenger Vehicles, Commercial Vehicles, Public Transport, Off-Road Vehicles |
| Companies Covered | Toyota Motor Corporation, Honda Motor, Hyundai Motor Company, Robert Bosch GmbH, Nissan Motor, Mitsubishi Motors, MAHLE GmbH, Ford Motor Company, General Motors Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Powertrain Systems Market Evolving Landscape
Powertrain architecture decisions are increasingly driven by the intersection of battery chemistry cost curves and combustion engine downsizing limits, reshaping competitive positioning across mild, full, and plug-in hybrid categories.
Silicon carbide power semiconductors are replacing silicon IGBTs in inverter modules to cut switching losses and enable higher motor speeds. Tier-1 suppliers are qualifying these devices for volume hybrid programs. This transition is decomposing the traditional cost advantage of established silicon-based supply chains.
China's dual carbon goals and MEE enforcement protocols are tightening industrial emission benchmarks beyond automotive into upstream battery material refining. Domestic OEMs face parallel pressure from MIIT production quotas and provincial air quality mandates. Suppliers with captive cell production in China must now navigate dual compliance layers.
Commercial fleet procurement is consolidating around total cost of ownership models that weight residual value against fuel savings over duty cycles. Large logistics operators in Germany and Japan are bypassing traditional dealer networks for direct powertrain supplier negotiations. This pattern is most pronounced in long-haul trucking segments where highway load profiles favor parallel hybrid mechanical efficiency.
Hybrid Powertrain Systems Market Segmentation
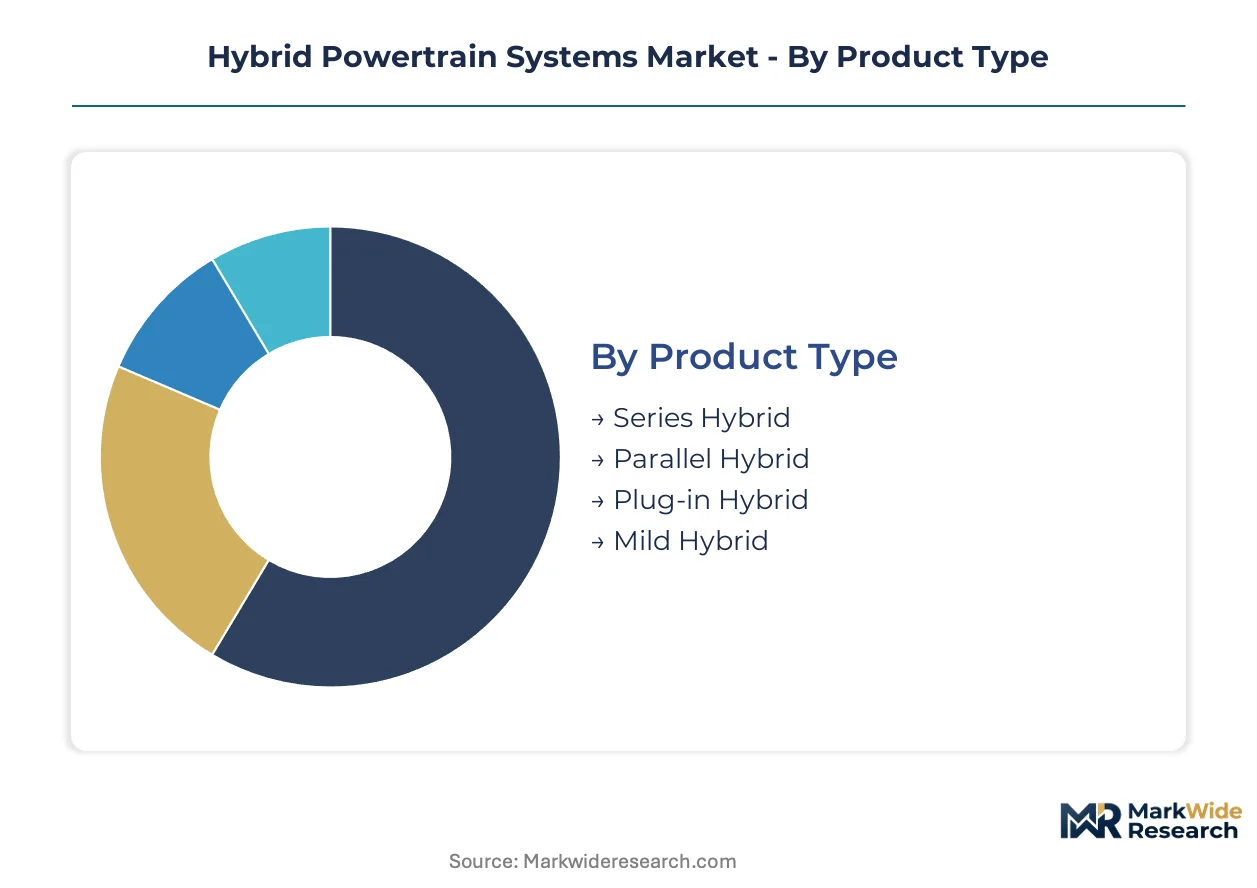
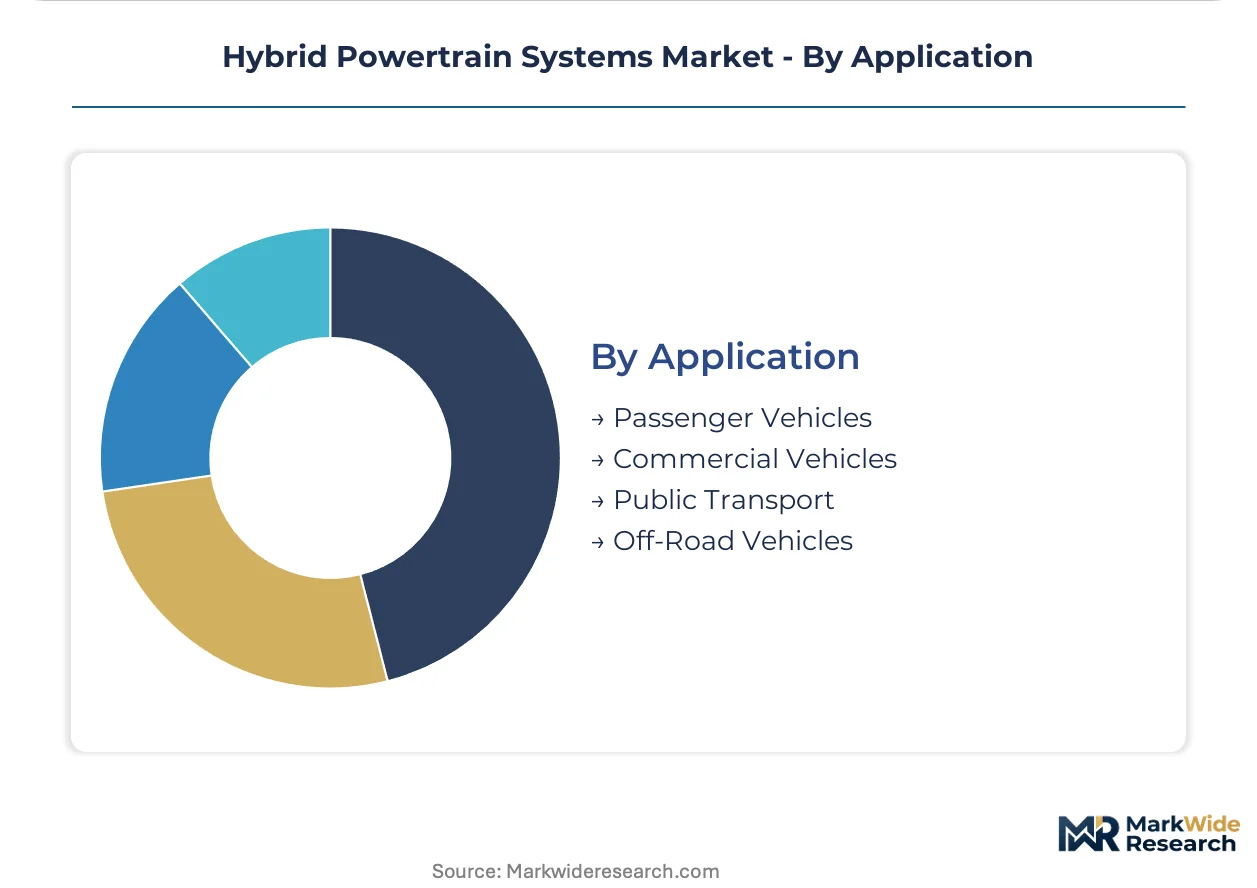
Powertrain architecture decisions determine margin capture across battery chemistry, thermal management, and control software layers. Segmentation clarity exposes where engineering investment concentrates and which customer procurement patterns favor modular versus integrated system sourcing.
Product Type:
Margin pools concentrate in power-split transmission integration and battery pack thermal management, with architecture complexity driving tiered supplier pricing power.
- Series Hybrid:The internal combustion engine functions exclusively as a generator, decoupling engine speed from wheel speed for optimized thermal efficiency. Demand clusters in urban bus fleets across China and Japan where stop-start duty cycles maximize regenerative braking recovery. Range-extender anxiety mitigation drives procurement from municipal transport authorities.
- Parallel Hybrid:Mechanical coupling allows both engine and electric motor to drive wheels simultaneously, preserving highway efficiency. German long-haul logistics operators favor this configuration for sustained autobahn cruising where direct mechanical paths minimize energy conversion losses. Fleet TCO models weight residual engine value against fuel savings.
- Plug-in Hybrid:Expanded battery capacity enables significant electric-only range before combustion engagement. Chinese MIIT credit system compliance creates guaranteed offtake for OEMs balancing zero-emission urban mandates with intercity flexibility.
- Mild Hybrid:48-volt belt-driven starter-generators provide torque assist without full electric propulsion. Cost-sensitive compact vehicle segments in India leverage this architecture for minimal regulatory compliance investment.
The dominant share belongs to Parallel Hybrid, while Plug-in Hybrid is closing the gap fastest.
Technology:
Cost tier stratification separates premium silicon carbide inverter designs from legacy silicon IGBT implementations across volume production programs.
- Battery Electric:Lithium-ion cell chemistry dominates traction energy storage, with nickel-manganese-cobalt cathodes capturing premium passenger vehicle applications. Cell cost volatility from raw material price swings compresses margin visibility for pack integrators serving multi-year OEM contracts.
- Internal Combustion Engine:Downsized turbocharged gasoline and compression-ignition diesel engines pair with electrification for thermal efficiency gains. Japanese and German engineering centers lead combustion optimization for hybrid-specific duty cycles.
- Fuel Cell:Proton exchange membrane stacks convert hydrogen to electricity for extended-range commercial applications. South Korean OEM deployment concentrates in heavy-duty trucking corridors with established hydrogen refueling infrastructure.
- Regenerative Braking:Software-dependent calibration requirements for kinetic energy recovery expand engineering budgets and component margins. Control algorithm sophistication differentiates Tier-1 supplier competitiveness.
Regenerative Braking commands the widest margin spread, while Battery Electric expands most quickly across new vehicle platforms.
End User:
Customer type determines procurement complexity, with direct OEM integration favoring long-term partnerships and aftermarket channels rewarding rapid fulfillment flexibility.
- OEMs:Integrated manufacturers like Toyota and Hyundai captive-source powertrain components across multi-brand portfolios. In-house production of battery packs and transmissions insulates margin capture from supplier pricing power.
- Automotive Manufacturers:Volume producers without captive hybrid technology rely on modular system sourcing from Tier-1 suppliers. Robert Bosch GmbH anchors European supply with architecture reuse across multiple OEM programs.
- Aftermarket Providers:Retrofit specialists serve aging fleet segments with cost-optimized component replacements. Service network density constrains geographic expansion beyond established metropolitan clusters.
- Transportation Sector:Fleet operators bypass dealer networks for direct powertrain negotiations based on total cost of ownership models. Large German and Japanese logistics consolidators drive specification standardization.
OEMs retain the deepest integration share, while the Transportation Sector is gaining procurement influence fastest through fleet-scale direct contracting.
Application:
Volume concentration varies sharply by duty cycle, with urban stop-start patterns favoring series architectures and sustained highway loads rewarding parallel mechanical efficiency.
- Passenger Vehicles:Compact through full-size sedans and SUVs represent the highest unit volume deployment. Chinese domestic brands leverage MIIT credit accumulation for regulatory compliance across mass-market segments.
- Commercial Vehicles:Light, medium, and heavy-duty trucks prioritize payload preservation and range certainty. European Union Green Deal fleet CO2 mandates accelerate hybrid drivetrain procurement across logistics operators.
- Public Transport:Urban bus and coach applications maximize regenerative braking recovery through predictable stop-start routes. Municipal procurement in China and Germany specifies hybrid compliance for clean air zone access.
- Off-Road Vehicles:Construction, agriculture, and mining equipment hybridizes for fuel cost reduction in remote operations. Duty cycle variability challenges standardized powertrain sizing.
Passenger Vehicles hold the dominant volume position, while Commercial Vehicles demonstrate the steepest expansion trajectory under tightening fleet emission regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys hybrid powertrains predominantly for fleet compliance accumulation, while Germany and Japan prioritize long-haul mechanical efficiency and captive manufacturing integration respectively.
China
Domestic OEMs accumulate MIIT new-energy vehicle credits through mass-market hybrid production quotas. Provincial air quality mandates from MEE enforcement protocols tighten industrial emission benchmarks for upstream battery material refining. The Yangtze River Delta cluster concentrates cell production and power-split transmission assembly for domestic brand supply.
Germany
Long-haul logistics operators favor parallel hybrid configurations for sustained autobahn cruising efficiency. The EU Green Deal fleet CO2 mandates accelerate direct procurement negotiations bypassing traditional dealer networks. The Stuttgart engineering corridor anchors combustion optimization centers for hybrid-specific duty cycles.
Japan
Two decades of nickel-metal hydride manufacturing heritage sustain process leadership in battery pack integration. METI industrial policy supports domestic supply chain concentration for critical power-split transmission patents. The Toyota City manufacturing cluster retains captive production of hybrid system components across multi-brand portfolios.
United States
EPA tailpipe standard uncertainty creates planning friction for multi-year platform investments across OEM engineering centers. NHTSA fuel economy rules establish divergent certification pathways from European WLTP testing cycles. The Detroit metropolitan area hosts powertrain diversification programs across light and medium-duty truck segments.
South Korea
Proton exchange membrane fuel cell deployment concentrates in heavy-duty trucking corridors with established hydrogen refueling infrastructure. Domestic OEMs balance zero-emission urban mandates with intercity flexibility through plug-in hybrid engineering investment. The Busan-Ulsan industrial belt anchors dedicated hybrid transmission platform production spanning brand portfolios.
Hybrid Powertrain Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hybrid powertrain development. Integrated OEMs capture margin through captive battery pack and transmission production, while Tier-1 suppliers compete on modular architecture reuse across multiple programs. Three archetypes dominate: heritage integrators with manufacturing scale, modular system architects controlling cross-OEM supply, and dedicated transmission platform specialists. Competitive moves concentrate on backward integration into cell production and strategic partnerships for power electronics sourcing.
Within the heritage integrator tier, Toyota Motor Corporation exemplifies two-decade manufacturing scale in battery chemistry integration. Robert Bosch GmbH anchors the modular system architect position across European OEM supply chains. Hyundai Motor Company occupies the dedicated platform specialist role with transmission architectures spanning captive brand portfolios.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Honda Motor |
| Hyundai Motor Company |
| Robert Bosch GmbH |
| Nissan Motor |
| Mitsubishi Motors |
| MAHLE GmbH |
| Ford Motor Company |
| General Motors Company |
| Others |
Value Network & Pricing Analysis
EU Green Deal fleet CO2 mandates gate both supplier qualification and price differentiation simultaneously, as compliance-certified powertrain architectures command premium positioning against uncertified alternatives while raw material volatility compresses margin visibility across contract tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between OEMs and battery pack integrators, insulating volume buyers from lithium-ion cathode mineral volatility while spot-market exposure punishes smaller fleet operators. Price differentiation rests on NEV credit accumulation rates under China's MIIT system and silicon carbide inverter certification tiers. Cost compression in mild hybrid architectures is intensifying because 48-volt system commoditization erodes engineering premiums. Fleet operators in Germany and Japan demonstrate lowest price sensitivity due to TCO-model procurement, while Indian compact vehicle segments exhibit highest sensitivity to upfront powertrain premiums.
Supply Chain Analysis
Strategic stockpiling of nickel-manganese-cobalt cathode precursors prevails among Japanese and South Korean cell producers, contrasting with just-in-time power electronics sourcing from German and Taiwanese semiconductor foundries. Manufacturing gravity centers on China, Japan, and Germany for power-split transmissions, traction battery assembly, and combustion optimization respectively. The supply chain draws from Chilean lithium, Indonesian nickel, and DRC cobalt for cathode chemistry. Single-source vulnerability concentrates in Japanese power-split transmission patents. Distribution runs through captive OEM integration for integrated manufacturers and modular Tier-1 supply for volume producers without hybrid heritage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain architecture fragmentation creates niche opportunities as fleet operators bypass dealer networks for direct supplier negotiations, splintering procurement concentration across multiple sourcing channels.
For Market Incumbents: Consolidate backward integration into cell production to insulate margin capture from cathode mineral volatility, while locking long-term offtake agreements with German and Japanese logistics operators to defend against emerging modular system architects. Captive transmission manufacturing in the Yangtze River Delta and Toyota City clusters anchors supply security against Korean dedicated-platform competition. For New Entrants and Emerging Players: Aftermarket thermal management retrofit services represent an under-served layer where incumbent OEMs cede margin to third-party service networks. Target Indian commercial vehicle electrification under PLI cost-offset pathways, and pursue German KBA type-approval streamlining for plug-in hybrid variants as the fastest certification route. Go-to-market leverage rests on power-to-thermal subsystem bundling for aging European bus fleets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon carbide inverter qualification programs, favoring acquirers with patient capital deployment capacity. Target mid-cap power electronics specialists with captive SiC device sourcing relationships as acquisition archetypes. The signal to watch is EPA tailpipe standard resolution, which would de-risk multi-year platform investment planning friction.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode mineral offtake secures MIIT credit compliance for Chinese OEM volume programs. |
| Backward Integration | In-house cell production insulates Toyota and Hyundai from supplier pricing power in lithium-ion packs. |
| Platform Standardization | Modular hybrid architectures enable Robert Bosch GmbH to reuse designs across multiple European OEM programs. |
| Software-Defined Vehicle Investment | Regenerative braking calibration algorithms differentiate Tier-1 supplier competitiveness in control systems. |
| Geographic Manufacturing Footprint | Stuttgart and Toyota City engineering corridors anchor combustion optimization for hybrid-specific duty cycles. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, fleet operations directors, and aftermarket service heads anchored the qualitative base. Primary interviews triangulated with secondary sources including vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and MIIT NEV credit accumulation records. Bottom-up segment sizing across powertrain architectures converged with top-down market reconciliation.
Sensitivity analysis tested forecast robustness across alternative battery chemistry cost curve trajectories and combustion engine downsizing limits over the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from segment-level unit economics and value-per-vehicle assumptions, with power electronics content mix and thermal management bundling rates as key forecast inputs.
Underlying assumptions cover MIIT credit system continuity and EU Green Deal fleet mandate enforcement, with deviation risk concentrated in EPA tailpipe standard uncertainty and lithium-ion raw material price volatility. Revision becomes warranted when regulatory compliance thresholds cross materially from baseline trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Train Market