
 Global Automotive Dyno Market | 2026-2036
Global Automotive Dyno Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Dyno Market Intelligence
The automotive industry's shift toward electrification, propelled by frameworks like the EU Green Deal and China's dual carbon goals, is realigning demand for specialized dynamometers. AVL List GmbH specializes in comprehensive powertrain testing systems for both internal combustion engines and electric drives. HORIBA Ltd. leverages its extensive instrumentation portfolio to offer integrated emission and performance measurement solutions. Meanwhile, SAKOR Technologies focuses on high-performance dynamometer systems tailored for hybrid and electric vehicle testing applications.
An automotive dynamometer is a device designed to measure an engine's or vehicle's force, torque, or power output under controlled conditions. These systems simulate road or race conditions, often incorporating load cells and data acquisition systems to capture precise performance metrics. Chassis dynamometers remain a core product type, but engine dynamometers are seeing renewed focus for R&D in new powertrain architectures. Within applications, performance testing and emission measurement continue to dominate procurement for regulatory compliance and product validation.
Regulatory bodies such as the US Environmental Protection Agency (EPA) and standards like Europe's upcoming Euro 7 define testing requirements. Compliance with these mandates, alongside ISO standards for testing protocols, directly influences the technical specifications required of dynamometers. Vendor selection increasingly depends on the ability to provide systems capable of accurately testing both traditional and electrified powertrains.
Market Dynamics
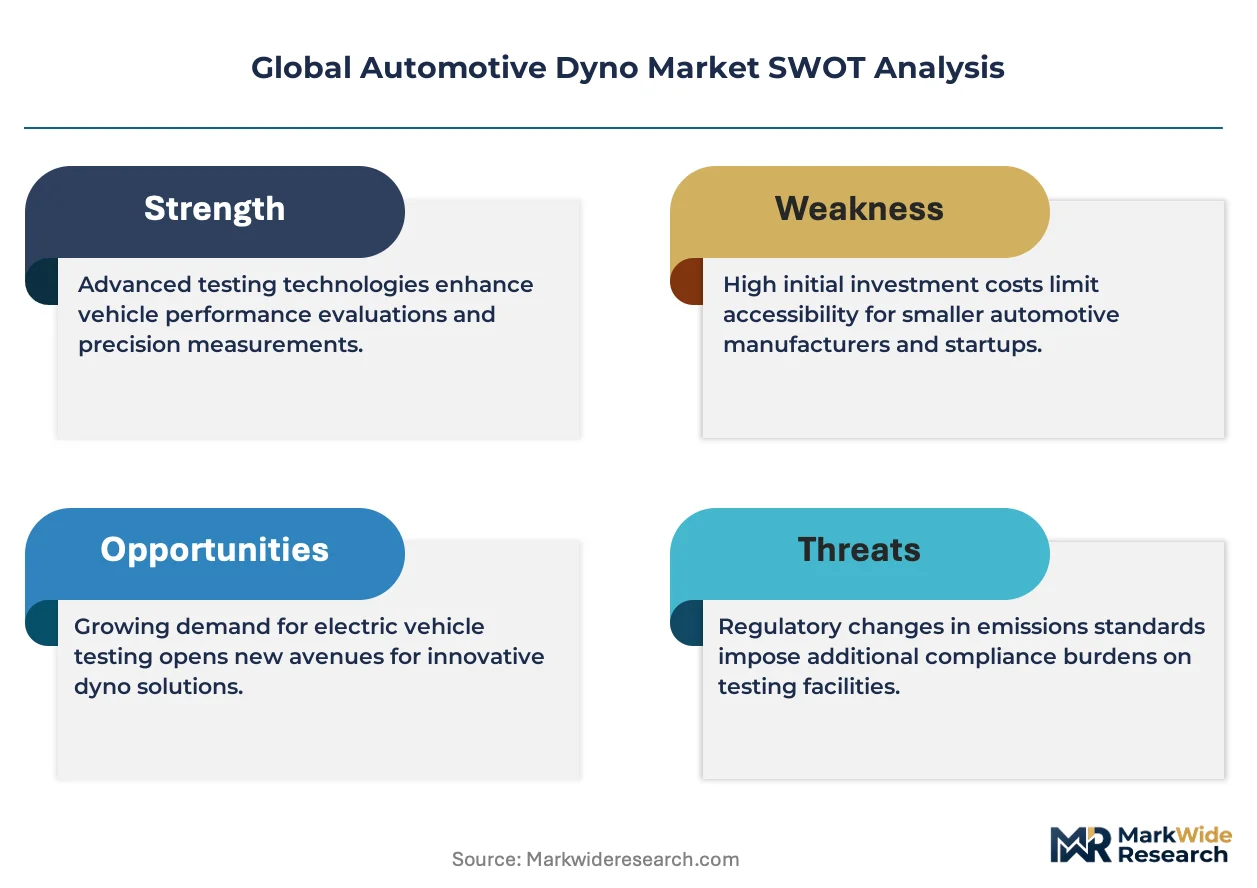
The central tension in the automotive dyno market is the simultaneous need to support advanced electric powertrain validation while also meeting stricter emissions testing mandates for legacy internal combustion engines, creating a bifurcated technology development path.
Growth Catalysts
- EV Powertrain Validation:Demand from EV makers for systems to test e-motor efficiency and battery performance under simulated loads drives investment in new dyno technology.
- Emissions Mandates:Regulations like the EU's Euro 7 and real-world driving emissions (RDE) testing compel automakers to acquire more sensitive and accurate chassis and engine dynamometers.
- Manufacturing in China:The country's vast automotive production and EV leadership, guided by dual carbon goals, creates a concentrated hub of demand for all dynamometer types.
Market Restraints
- High Capital Cost:The significant upfront investment for advanced systems, especially those with environmental chambers, remains a primary barrier for smaller Tier 1 suppliers and startups.
- Technical Integration Complexity:Linking modern dynamometers with vehicle-in-the-loop (VIL) simulations and legacy data systems requires specialized engineering talent that is scarce.
- Calibration Bottlenecks:Long setup times for new powertrain architectures, such as multi-motor electric vehicles, can delay critical R&D validation schedules.
Strategic Opportunities
- Mobile and Portable Systems:Developing smaller, transportable dynamometers for on-site fleet diagnostics and end-of-line quality checks addresses an underserved market segment.
- Hydrogen Powertrain Testing:A niche is emerging for dynamometers designed for the unique safety and measurement requirements of hydrogen fuel cells and combustion engines.
- Software as a Service (SaaS):Offering test cell automation and data analytics on subscription lowers adoption barriers and creates recurring revenue for vendors.
Industry Challenges
- Data Analysis Skill Gap:A shortage of technicians capable of interpreting complex, integrated data from powertrain, battery, and emissions tests limits the effective use of advanced dynamometer features.
- Legacy System Compatibility:Integrating new, high-frequency dynamometers with older test cell control hardware and software presents significant compatibility and performance challenges for established OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Dyno Market |
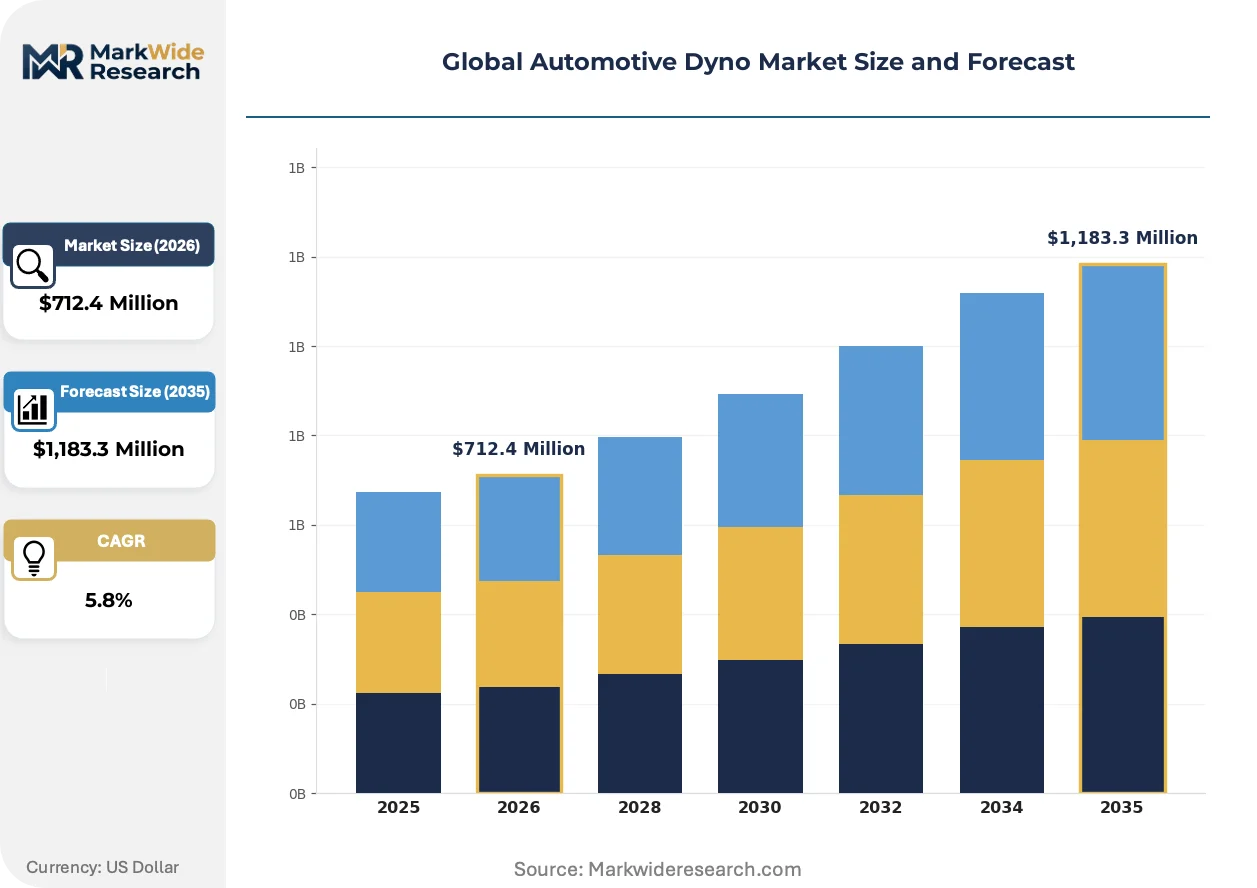
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,183.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chassis Dynamometer, Engine Dynamometer, Transmission Dynamometer, Eddy Current Dynamometer, Hydraulic Dynamometer Technology: Electromagnetic, Mechanical, Hydraulic, Eddy Current, Water Brake Application: Performance Testing, Emission Measurement, Durability Testing, Calibration, Research & Development, Quality Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Research Institutes, Testing Laboratories |
| Companies Covered | Dynojet Research, SAKOR Technologies, AVL List GmbH, Meidensha Corporation, Rototest, HORIBA Ltd., SuperFlow Technologies, Froude Hofmann, Mustang Advanced Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Dyno Market Strategic Shifts & Innovations
The market is transitioning from purely mechanical measurement devices to integrated, software-defined testing platforms. This evolution combines precise physical load simulation with sophisticated digital twin and data analysis capabilities, redefining product validation.
Integrated test benches allow testing individual components like e-motors or entire powertrain systems on a single hardware platform. R&D labs at automotive OEMs and major Tier 1 suppliers are the primary adopters. This approach is modularizing the test cell, enabling flexible reconfiguration for diverse powertrain types without requiring entirely new dedicated rigs.
Regulatory frameworks like the EU's Euro 7 standard mandate testing for non-exhaust particulates from brakes and tires, alongside extended powertrain durability assessments. This directly impacts chassis dynamometer design, requiring the integration of new particulate measurement systems and programming for longer test cycles. Vehicle manufacturers must adapt test protocols to ensure compliance.
A preference for test-as-a-service (TaaS) models is growing as an alternative to large capital expenditures on in-house equipment. This disrupts the traditional sales model, with third-party labs performing validation work previously done internally. The shift is most visible among EV startups in North America lacking extensive testing infrastructure.
Global Automotive Dyno Market Segmentation
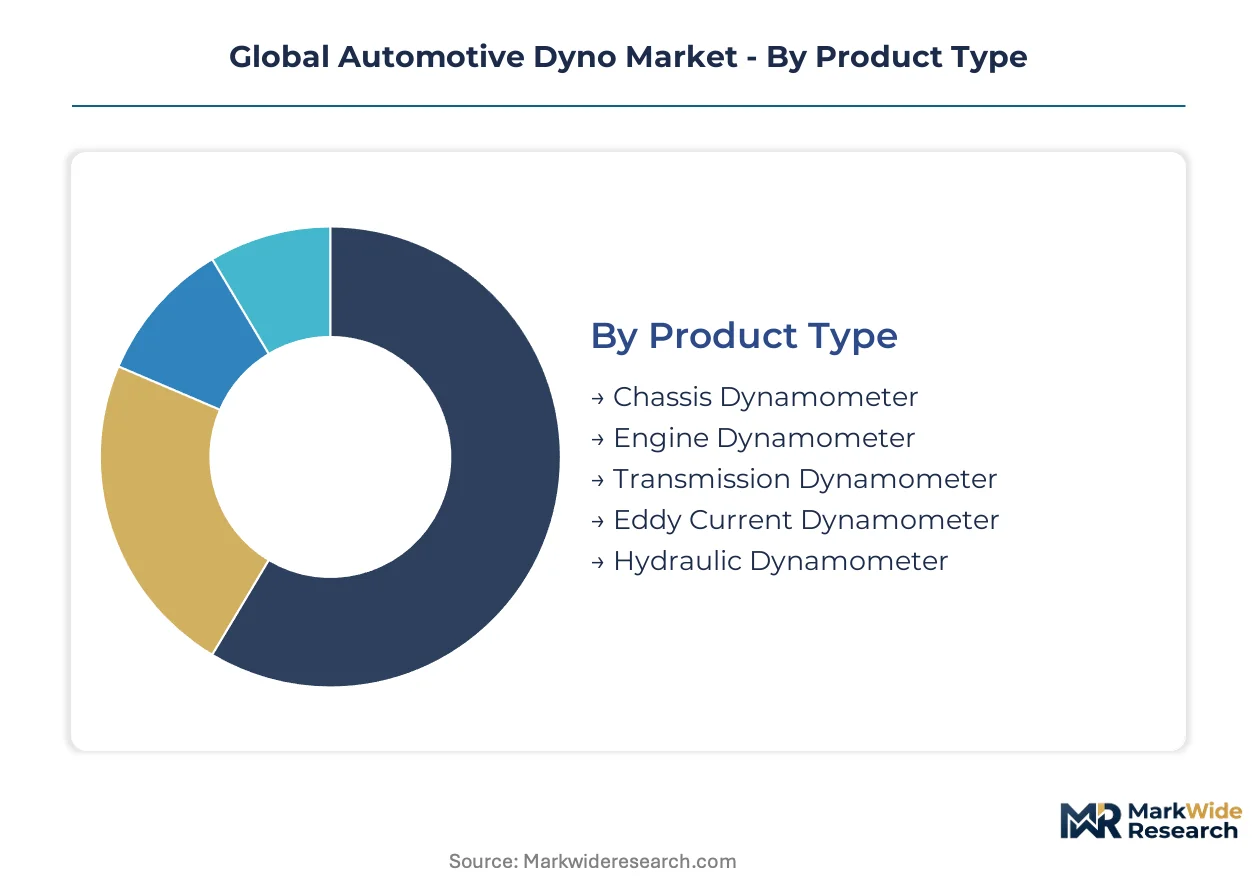
Understanding the automotive dyno market through segmentation reveals distinct demand patterns and technological requirements across various applications and user types. This granular analysis provides clarity on where investment in testing infrastructure is most concentrated, driven by evolving regulatory landscapes and powertrain innovations.
Product Type:
Certification burdens heavily influence procurement in the Product Type segment, dictating which dynamometer configurations are necessary for regulatory adherence.
- Chassis Dynamometer:These systems measure vehicle performance directly at the wheels, simulating road conditions for comprehensive testing. Demand concentrates in compliance testing for regulations like EU Euro 7 and US EPA standards, validating vehicle emissions and fuel economy.
- Engine Dynamometer:Engine dynamometers evaluate internal combustion engines and electric motors independently of the vehicle chassis. R&D departments at automotive OEMs increasingly use these for developing new powertrain architectures and optimizing performance before vehicle integration.
- Transmission Dynamometer:This specialized equipment assesses the efficiency and durability of gearboxes and driveline components under various load conditions.
- Eddy Current Dynamometer:Utilizing electromagnetic braking, these dynos provide precise load control for a wide range of engine and motor testing applications.
- Hydraulic Dynamometer:Hydraulic dynamometers offer robust, high-power absorption for heavy-duty engine and industrial equipment testing.
Chassis Dynamometer sits at the top of the volume ranking, with Engine Dynamometer climbing the fastest.
Technology:
The choice of dynamometer technology often reflects the required precision and dynamic range for specific testing applications.
- Electromagnetic:Electromagnetic dynamometers provide highly dynamic and precise load simulation, essential for transient testing of advanced electric powertrains. Demand for this technology is accelerating among EV startups and established OEMs in China for e-motor validation.
- Eddy Current:Eddy current technology offers a cost-effective and reliable method for absorbing power and applying controlled loads to engines and motors. These systems are widely adopted in performance tuning and quality control applications across various automotive segments.
- Mechanical:Mechanical dynamometers, often using friction brakes, serve as fundamental tools for basic load testing and calibration in educational and vocational settings.
- Hydraulic:Hydraulic systems absorb power through fluid resistance, providing high-torque capacity suitable for heavy-duty vehicle and industrial engine testing.
- Water Brake:Water brake dynamometers utilize water as a resistance medium, offering a simple and robust solution for high-power absorption in diverse testing environments.
Electromagnetic technology shows specialized expansion, while Hydraulic systems maintain a stable base in heavy-duty applications.
Application:
Customer types frequently drive demand for specific dynamometer applications, aligning with their core business objectives and regulatory needs.
- Performance Testing:This application quantifies an engine's or vehicle's power, torque, and speed characteristics under controlled conditions. Automotive OEMs and tuning houses in Germany rely on performance testing for product differentiation and marketing claims.
- Emission Measurement:Dynos are critical for quantifying pollutant output from internal combustion engines and hybrid systems to ensure regulatory compliance. Stricter mandates like EU Euro 7 drive procurement for advanced emission measurement capabilities in Europe.
- Durability Testing:This application assesses the long-term reliability and wear of powertrain components under simulated operational stresses.
- Calibration:Dynamometers are essential for fine-tuning engine control units (ECUs) and optimizing powertrain parameters for efficiency and driveability.
- Research & Development:R&D applications leverage dynos for exploring new technologies, validating prototypes, and optimizing future powertrain designs.
- Quality Control:Quality control uses dynamometers for end-of-line testing, ensuring manufactured engines and vehicles meet performance specifications.
The broadest adoption occurs in Performance Testing, with Research & Development showing specialized expansion.
End User:
Supply concentration for dynamometer systems is heavily influenced by the end-user's scale of operations and the complexity of their testing requirements.
- OEMs:Original Equipment Manufacturers integrate dynamometers into their R&D centers and production lines for comprehensive vehicle and powertrain validation. Major automotive manufacturers in Japan invest heavily in dyno facilities for new model development and regulatory compliance.
- Testing Laboratories:Independent and government-affiliated testing laboratories provide certification and validation services for automakers and suppliers. These labs, particularly in the US, require advanced dynos to meet EPA and CARB testing protocols.
- Tier-1 Suppliers:These suppliers utilize dynos for developing and validating components like transmissions, axles, and electric motors for automotive OEMs.
- Aftermarket Providers:Aftermarket companies use dynamometers for performance tuning, diagnostic services, and validating upgraded vehicle components.
- Vehicle Assemblers:Assemblers sometimes employ dynos for end-of-line quality checks and functional validation of completed vehicles.
- Research Institutes:Academic and private research institutes use dynamometers for fundamental studies in combustion, electrification, and vehicle dynamics.
While OEMs represent established demand, Testing Laboratories offer opportunities for new market entrants focusing on compliance services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive dynamometer market first scaled significantly alongside the rise of mass automotive production and the need for standardized performance validation. Testing requirements for internal combustion engines drove early innovation in load simulation and measurement. Today, the market expands rapidly due to electrification and stricter global emissions standards.
China
Demand for advanced dynamometers in China is driven by its extensive automotive manufacturing base and leadership in electric vehicle development. The country's dual carbon goals accelerate investment in EV powertrain testing capabilities. Major EV manufacturing hubs in Shanghai and Shenzhen are concentrating procurement for e-motor and battery performance validation.
Germany
German automotive OEMs and research institutes require sophisticated dynamometers for both traditional powertrain optimization and cutting-edge electric drive systems. Strict EU Euro 7 emissions standards compel investment in highly accurate chassis and engine dynamometers. Stuttgart and Munich remain centers for advanced automotive R&D, deploying integrated test benches for new vehicle architectures.
United States
The United States market sees demand from both established automakers and a growing number of EV startups for performance and regulatory compliance testing. EPA regulations for emissions and fuel economy necessitate advanced dynamometer systems. Detroit and California's Silicon Valley are key regions for dynamometer adoption, supporting both legacy and emerging powertrain validation efforts.
Japan
Japanese automotive manufacturers continue to invest in dynamometer technology for developing hybrid and electric vehicle powertrains. METI initiatives supporting next-generation vehicle technologies influence R&D spending on specialized testing equipment. Nagoya and Tokyo remain critical hubs for automotive engineering, driving demand for precision engine and chassis dynamometers.
India
India's automotive sector is expanding, with a rising focus on local manufacturing and EV adoption, increasing the need for dynamometer testing. PLI schemes and emission norms similar to Euro standards encourage investment in modern testing infrastructure. Chennai and Pune are emerging as significant automotive manufacturing and R&D centers, procuring dynamometers for product validation.
Global Automotive Dyno Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the automotive dynamometer market, creating a diverse competitive landscape. The market structure is moderately consolidated at the high-end, where specialized engineering firms offer complex integrated solutions. Strategic archetypes include full-service engineering providers, niche technology specialists, and component manufacturers. Companies primarily engage in strategic partnerships for technology co-development and targeted acquisitions to expand their portfolio.
Specialists in advanced powertrain testing like AVL List GmbH and HORIBA Ltd. represent comprehensive engineering and instrumentation capabilities. These companies occupy a position at the forefront of integrated test cell solutions, offering systems for both internal combustion engines and electric drives. SAKOR Technologies exemplifies a focus on high-performance dynamometer systems, particularly tailored for hybrid and electric vehicle testing applications.
| Leading Market Players |
|---|
| Dynojet Research |
| SAKOR Technologies |
| AVL List GmbH |
| Meidensha Corporation |
| Rototest |
| HORIBA Ltd. |
| SuperFlow Technologies |
| Froude Hofmann |
| Mustang Advanced Engineering |
| Others |
Cost & Logistics Intelligence
Precision electronic component costs, critical for modern dynamometer systems, influence the final pricing tiers for advanced testing solutions. These specialized inputs flow from a concentrated global supply base, impacting both manufacturing efficiency and downstream market competitiveness for dyno vendors.
Pricing Analysis
Project-based pricing models often dominate the automotive dynamometer market for complex integrated test cell solutions. Price differentiation stems from the level of customization required for specific powertrain architectures and the extent of after-sales service and software support. Pricing pressure stems from the high capital cost of advanced systems, particularly for smaller Tier 1 suppliers. Original Equipment Manufacturers (OEMs) exhibit lower price sensitivity for mission-critical R&D equipment, while independent testing laboratories seek more cost-effective, standardized solutions.
Supply Chain Analysis
Logistics costs for transporting large, heavy dynamometer equipment influence regional pricing and delivery schedules. Supply concentration for core dynamometer components centers on Germany, Japan, and China. The market relies on precision sensors, high-power electronics, and specialized steel alloys as critical inputs. Single-source vulnerability for highly specialized control software or rare earth magnets presents a structural risk. Distribution runs through direct sales channels to major OEMs and specialized distributors serving smaller research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, where lower labor costs in China for manufacturing can offset the high R&D investment required in Germany for advanced dynamometer technologies.
For Market Incumbents:
To counter the threat of niche EV testing startups and high capital costs, incumbents should deepen R&D into integrated software platforms for predictive maintenance and data analytics. Expanding global service networks, particularly in rapidly growing EV markets like China, will reinforce customer loyalty. Investing in certification for emerging standards like Euro 7 non-exhaust particulate testing offers a competitive lever. Strategic partnerships with AI and machine learning firms can enhance data analysis capabilities.
For New Entrants and Emerging Players:
Smaller Tier 1 suppliers and EV startups in North America represent an underserved buyer archetype for flexible testing solutions. Developing mobile and portable dynamometer systems for on-site diagnostics offers a white-space target. Offering Test-as-a-Service (TaaS) models lowers adoption barriers for capital-constrained entities. Focusing on specialized hydrogen powertrain testing equipment presents a niche market entry opportunity with a distinct go-to-market angle.
For Investors and Strategic Acquirers:
Consolidation pressure builds where technical integration complexity and high R&D investment create barriers to entry. The long-term viability of this market hinges on the continued shift towards electrification and hydrogen powertrains. Acquisition targets should include specialized software firms offering advanced data analysis or test cell automation solutions. Increased M&A activity focused on e-motor and battery testing capabilities signals an inflection point for strategic investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Test Platform Development | Enhances flexibility for diverse powertrain testing and integrates digital twin capabilities for OEMs. |
| Hydrogen Powertrain Testing R&D | Addresses emerging demand for specialized equipment catering to unique safety and measurement requirements. |
| Test-as-a-Service Expansion | Lowers capital expenditure barriers for EV startups and smaller Tier 1 suppliers in North America. |
| Global Service Network Enhancement | Ensures reliable support and maintenance for complex dynamometer systems across key automotive regions. |
| Acquisition of Data Analytics Specialists | Strengthens capabilities in interpreting complex test data and optimizing R&D validation schedules. |
Research Approach
Multiple input streams — primary interviews, industry reports, and regulatory filings — were reconciled to construct a comprehensive market view. This involved engaging OEM R&D heads, Tier 1 engineering managers, independent lab directors, and dynamometer manufacturers. Secondary data sources included automotive industry association publications, government emissions standards, patent databases, and company annual reports, triangulated for accuracy.
Historical market performance was cross-referenced with expert panel input to project future trends and market sizing. The analytical framework modeled segmentation across product type, technology, application, end-user, and regional EV adoption rates throughout the forecast period. Compound Annual Growth Rates (CAGRs) were derived from demand projections for new vehicle platforms and regulatory compliance timelines. Key industry-specific forecast inputs included EV production forecasts and anticipated regulatory compliance timelines.
Inputs from OEM investment plans and regulatory updates were available through the study window; gaps in long-term EV battery chemistry evolution introduce uncertainty bands. Forecasts reflect assumptions regarding technological adoption rates and global economic stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive PTC Heaters Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Engine Flush Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Automotive Water Pump Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Engine Tuner Market
Powertrain
Clutch Friction Plate Market
Powertrain
Fuel Pumps Market
Powertrain
Automotive Drivetrain Market
Powertrain
High Speed Engine Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Engine Rocker Arm Market
Powertrain
Fuel Injection Systems Market