
 Europe Electrically Powered Hydraulic Steering Market | 2026-2036
Europe Electrically Powered Hydraulic Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electrically Powered Hydraulic Steering Market Foresight
A widening capital-intensity gap between integrated and non-integrated suppliers is reorganizing competitive hierarchies in the Europe Electrically Powered Hydraulic Steering Market. ZF Friedrichshafen AG leverages its captive electronics and hydraulics divisions to control cost structures across the value chain. Robert Bosch GmbH sustains R&D intensity through dedicated steering-system labs in Stuttgart and Dresden. Continental AG anchors its position via manufacturing scale at plants in Germany and Romania.
Electrically powered hydraulic steering combines an electric motor with hydraulic actuation to deliver precise torque assistance while reducing parasitic engine load compared with conventional hydraulic systems. The architecture typically operates at 12V or 24V with brushless DC motors driving gerotor or vane-type pumps, enabling on-demand fluid pressure that cuts fuel consumption. Rack assist systems dominate volume among passenger vehicle applications due to packaging efficiency and modularity. Dual pinion technology leads growth in the premium segment by enabling variable steering ratios without mechanical complexity. Active steering configurations remain concentrated in high-end German OEM programs where software-defined road feel commands margin premiums.
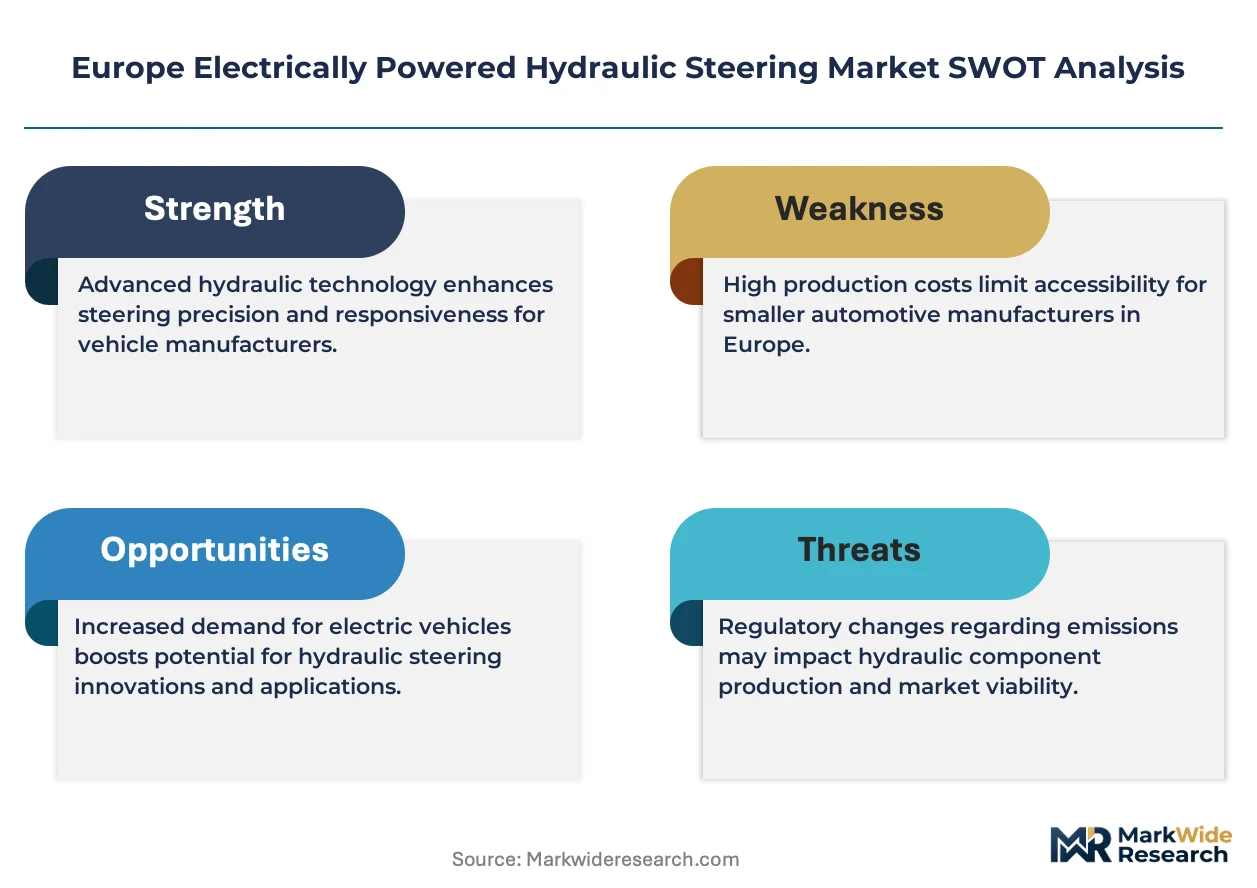
EU CO2 emission standards for heavy-duty vehicles, enforced through the European Commission's monitoring framework, are mandating steering-system efficiency gains that electrically powered hydraulic architectures satisfy. ECE R79 type approval governs steering equipment safety, while CE marking requirements ensure electromagnetic compatibility across member states. Stakeholders must monitor the EU Green Deal's evolving automotive CO2 targets and the F-Gas Regulation's potential restrictions on hydraulic fluids used in steering circuits.
Market Dynamics
The EU Green Deal's escalating CO2 reduction mandates for heavy-duty vehicles are compressing product development cycles across the Europe Electrically Powered Hydraulic Steering Market. Tier-1 suppliers must now validate integrated steering architectures against 2025 fleet-average targets while managing semiconductor allocation constraints.
Growth Catalysts
- ECE R79 type approval:Harmonized safety standards across EU member states reduce certification duplication for steering equipment manufacturers. German and French OEMs accelerate platform rollouts using this regulatory convergence.
- Rack assist technology:Packaging efficiency gains in passenger vehicle architectures drive volume preference. The modular design enables commonization across B-segment through E-segment vehicle programs.
- Poland and Romania:Manufacturing cost advantages attract steering-system component production from German tier-1 suppliers. These locations serve as export hubs for Eastern European vehicle assembly plants.
Market Restraints
- Semiconductor allocation volatility:Brushless DC motor controllers face extended lead times from foundry capacity constraints. Steering system suppliers compete with battery management and powertrain electronics for 40nm-90nm node supply.
- F-Gas Regulation restrictions:Potential phase-down of hydraulic fluids with high global warming potential threatens existing steering circuit designs. Reformulation timelines compress R&D budgets for fluid-compatible seal materials.
- Full electric power steering substitution:Steer-by-wire architectures eliminate hydraulic actuation entirely in next-generation premium vehicle platforms. This technology trajectory caps long-term addressable market for hybrid hydraulic-electric systems.
Strategic Opportunities
- Spain and Portugal:Commercial vehicle fleet renewal programs remain underpenetrated for electrically powered hydraulic steering. Iberian logistics operators face delayed compliance with EU CO2 monitoring frameworks.
- Active steering software licensing:Road-feel calibration algorithms represent untapped recurring revenue streams. German OEMs currently source these capabilities in-house or through exclusive supplier arrangements.
- 24V architecture migration:Heavy commercial vehicle electrification creates demand for higher-voltage steering systems. This convergence with mild-hybrid powertrains enables thermal management integration opportunities.
Industry Challenges
- Functional safety engineering talent:ISO 26262 ASIL-D certification expertise concentrates at established German suppliers. New market entrants face 18-24 month recruitment cycles for embedded software validation engineers.
- Legacy hydraulic system integration:Retrofit compatibility with existing truck and bus platforms requires maintaining dual architecture engineering teams. This parallel development strains R&D productivity metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electrically Powered Hydraulic Steering Market |
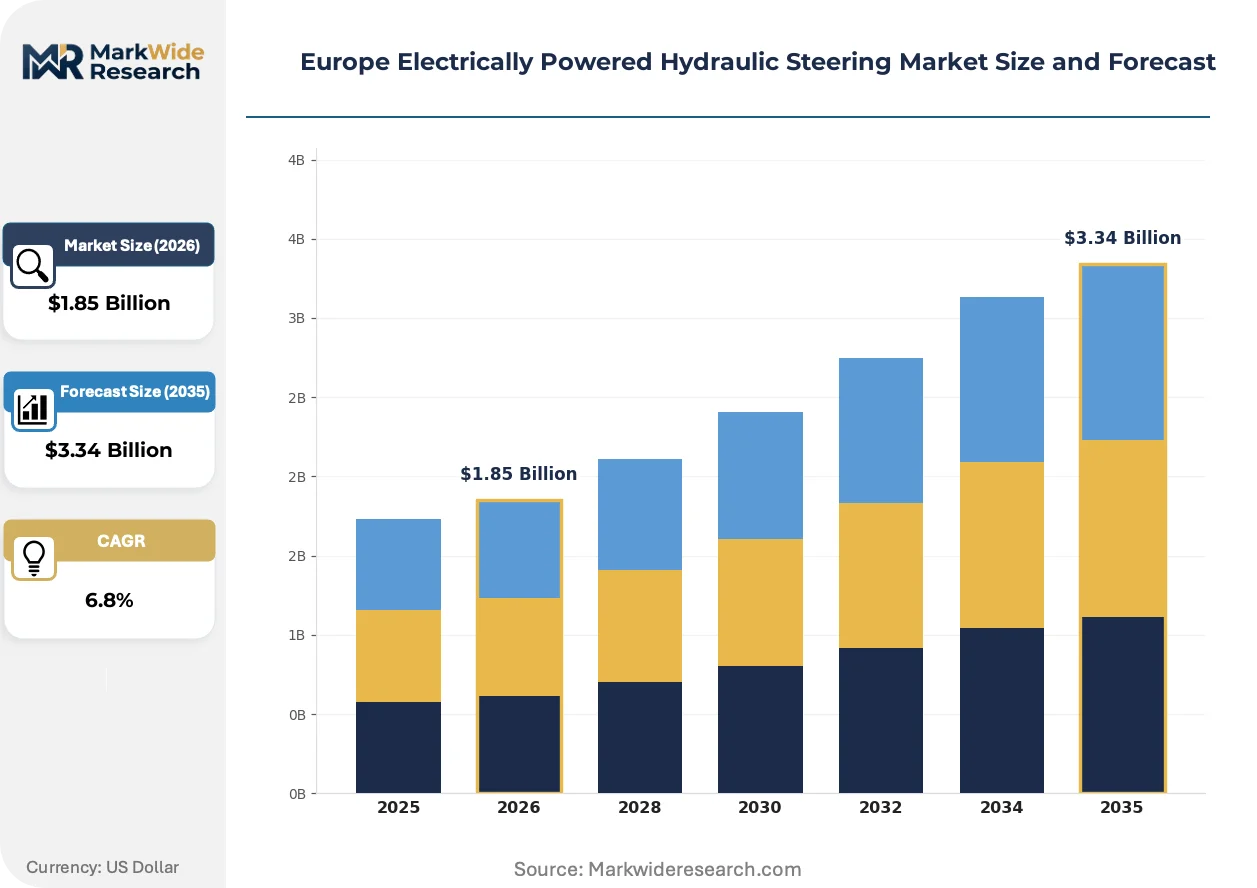
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Direct Drive, Others End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electric Power Steering, Dual Pinion Steering, Active Steering, Variable Ratio Steering Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Specialty Vehicles |
| Companies Covered | JTEKT Corporation, Nexteer Automotive Group, ZF Friedrichshafen AG, NSK Ltd, Robert Bosch GmbH, Continental AG, Hyundai Mobis, Valeo, Denso Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electrically Powered Hydraulic Steering Market Shifts & Advancements
Software-defined steering calibration is displacing hardware-centric torque mapping as the primary value creation mechanism. Tier-1 suppliers now compete on algorithmic road-feel differentiation rather than pump efficiency specifications alone.
Dual pinion rack assist architectures are displacing single-pinion designs in premium vehicle segments. German OEMs specify these systems for variable steering ratio programs. The technology enables speed-dependent rack travel without mechanical complexity. This displacement compresses margin structures for suppliers lacking in-house gear design capabilities.
EU F-Gas Regulation phase-down schedules are forcing hydraulic fluid reformulation across steering circuit suppliers. ECHA substance restriction proposals target perfluorinated compounds used in high-performance seals. Manufacturers in Germany and France accelerate bio-based synthetic fluid qualification programs. The regulatory pressure differential favors suppliers with captive chemical engineering resources.
Fleet procurement consolidation among European logistics operators is compressing steering system specification cycles. Large German and Dutch transport groups now mandate common steering architectures across multi-brand truck purchases. This buyer concentration shifts negotiation leverage toward volume-tier pricing structures. Tier-1 suppliers respond with modular platform strategies spanning light, medium, and heavy commercial vehicle classes.
Europe Electrically Powered Hydraulic Steering Market Segmentation
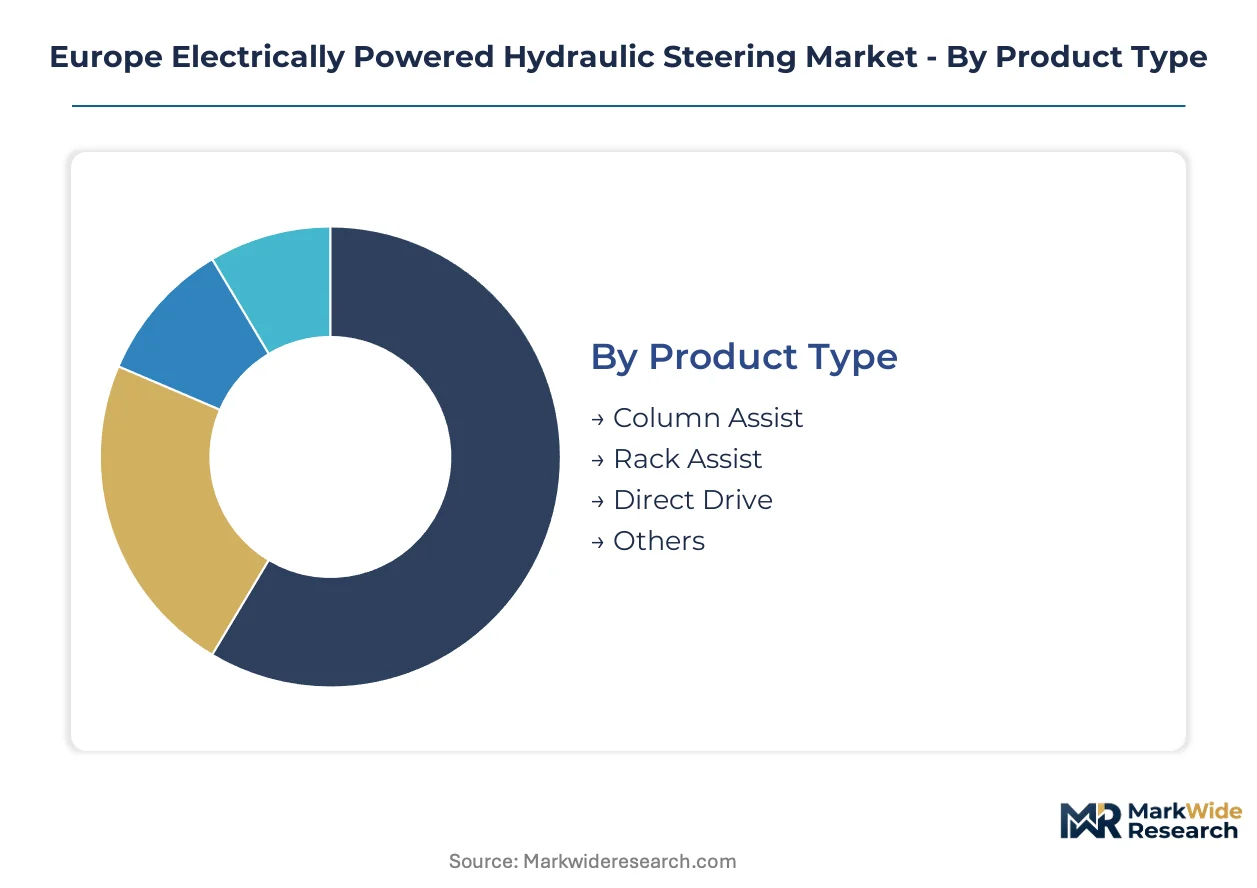
Segmentation in the Europe Electrically Powered Hydraulic Steering Market reveals how technology choices cascade through procurement hierarchies. OEMs and tier-1 suppliers source through fundamentally different validation cycles, creating distinct channel economics for each product category.
Product Type:
Rack assist systems flow predominantly through consolidated OEM direct contracts, while column assist and direct drive architectures see heavier tier-1 supplier intermediation.
- Column Assist:Integrates the electric motor and hydraulic pump directly onto the steering column shaft. German commercial vehicle OEMs specify these systems for cab-over-engine truck platforms where firewall packaging constraints dominate. ECE R79 certification cycles run shorter than rack-based alternatives, accelerating platform integration timelines.
- Rack Assist:Mounts the assist mechanism on the steering rack itself, enabling precise torque vectoring with reduced mechanical losses. Passenger vehicle programs across France and Italy concentrate demand here, driven by modularity requirements spanning B-segment through E-segment architectures. Dual pinion variants command specification premiums in premium German OEM lineups.
- Direct Drive:Eliminates intermediate mechanical linkages through high-torque brushless motors coupled directly to steering gear. Demand concentrates in heavy commercial vehicle electrification programs where 24V architecture migration enables thermal integration.
- Others:Includes pinion assist and recirculating ball variants serving specialty vehicle and retrofit applications. Aftermarket channels in Poland and Romania handle significant volume for legacy truck fleet upgrades.
By volume, rack assist leads. By growth pace, direct drive is climbing the fastest as heavy commercial vehicle electrification accelerates.
End User:
Cost tier stratification separates captive in-house production from outsourced procurement, with tier-1 suppliers occupying the mid-tier efficiency band.
- OEMs:German and French vehicle manufacturers maintain captive steering system engineering for flagship platforms. BMW, Mercedes-Benz, and Volkswagen Group source rack assist architectures through controlled supplier relationships with exclusive calibration rights. These programs emphasize software-defined road feel as a brand differentiation lever.
- Tier-1 Suppliers:ZF Friedrichshafen AG, Robert Bosch GmbH, and Continental AG dominate this channel, delivering validated subsystems to multiple OEM platforms. Their manufacturing scale across Germany and Romania enables cost structures that captive OEM production cannot match for mid-volume vehicle programs.
- Aftermarket Providers:Serve fleet operators seeking retrofit compliance with EU CO2 monitoring frameworks. Iberian logistics groups in Spain and Portugal represent underpenetrated demand concentration for column assist replacement units.
- Vehicle Assemblers:Contract manufacturers and niche vehicle producers source complete steering modules without in-house validation capabilities. Eastern European assembly plants rely heavily on this procurement channel.
OEMs capture the margin premium tier. Tier-1 suppliers are gaining share fastest as platform commonization pressures mount.
Technology:
Maturity curves separate established electric power steering architectures from emerging active steering configurations still concentrated in premium applications.
- Electric Power Steering:The baseline hybrid architecture combining brushless DC motors with hydraulic actuation. CE marking requirements and ECE R79 type approval have standardized validation protocols across EU member states, reducing certification friction for volume manufacturers.
- Dual Pinion Steering:Enables variable steering ratios through independent pinion engagement with the rack. German OEMs specify this technology for performance vehicle programs where speed-dependent rack travel enhances handling precision without mechanical complexity.
- Active Steering:Superimposes corrective torque through software-controlled motor intervention. Road-feel calibration algorithms represent the primary value creation mechanism, with German suppliers competing on algorithmic differentiation rather than hardware specifications alone.
- Variable Ratio Steering:Mechanical rack designs with varying tooth pitch achieve ratio changes without electronic intervention. Lower cost positioning serves economy passenger vehicle segments in Italy and Spain where electronic complexity is minimized.
Electric power steering dominates volume. Active steering shows the steepest expansion trajectory as software licensing models mature.
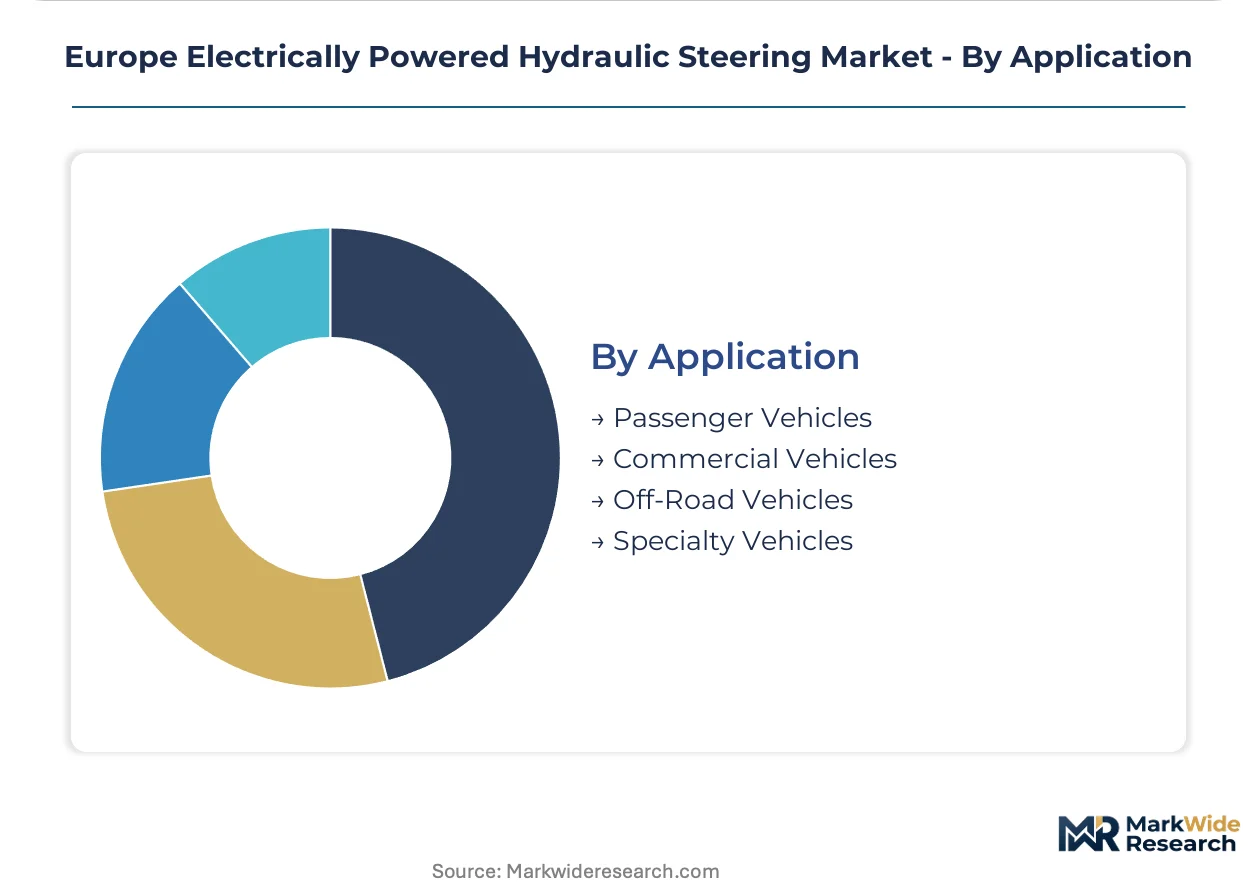
Application:
Customer type divergence splits passenger vehicle efficiency optimization from commercial vehicle regulatory compliance imperatives.
- Passenger Vehicles:Rack assist architectures prevail across German and French OEM lineups, with dual pinion systems penetrating premium segments. Packaging efficiency and NVH performance drive specification priorities.
- Commercial Vehicles:Heavy truck and bus fleets face EU Green Deal CO2 reduction mandates that electrically powered hydraulic steering satisfies through parasitic load reduction. Germany's logistics corridor generates concentrated demand for 24V-compatible systems.
- Off-Road Vehicles:Agricultural and construction equipment manufacturers in Germany and Italy specify high-torque column assist systems. ECHA substance restriction proposals on hydraulic fluids create reformulation pressure for seal compatibility.
- Specialty Vehicles:Includes emergency vehicles, military applications, and municipal fleets with customized steering requirements. Low volume, high customization characterizes this segment.
Passenger vehicles lead by volume. Commercial vehicles are expanding most quickly as fleet procurement consolidation accelerates specification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in electrically powered hydraulic steering systems favor German and French manufacturing bases serving Eastern European assembly operations. Component trade flows from Poland and Romania back to Western European OEM plants concentrate value capture in established supplier corridors. The EU Green Deal's CO2 mandates are redistributing production capacity toward regulatory compliance zones.
Germany
Heavy commercial vehicle fleets along the Rhine-Ruhr logistics corridor drive specification demand for 24V rack assist architectures. KBA type approval processes for steering equipment set validation benchmarks adopted across EU member states. Stuttgart and Dresden host concentrated R&D facilities where tier-1 suppliers develop integrated steering-electronics modules for premium OEM programs.
France
Paris-based logistics groups and Lyon manufacturing clusters generate parallel demand for column assist systems in cab-over-engine truck platforms. ANSM conformity assessment procedures align with ECE R79 harmonized standards, reducing certification friction for multi-market suppliers. The Auvergne-Rhône-Alpes region anchors production of hydraulic pump subassemblies serving both domestic and export channels.
Poland
Lower manufacturing costs attract steering component production from German tier-1 suppliers seeking cost structure optimization. CE marking requirements and EU Green Deal compliance obligations apply equally, creating regulatory parity with Western production sites. The Silesian automotive cluster has emerged as an export hub for rack assist systems supplying vehicle assembly plants across Eastern Europe.
Romania
Transylvanian manufacturing zones host expanded capacity for gerotor pump production and seal component fabrication. ECHA substance restriction monitoring affects hydraulic fluid formulation decisions for suppliers operating under REACH compliance frameworks. Timișoara and Cluj-Napoca industrial parks concentrate foreign direct investment from steering system manufacturers serving EU-wide distribution networks.
Spain
Iberian logistics operators face delayed compliance timelines with EU CO2 monitoring frameworks for heavy-duty fleets, creating retrofit demand concentration. The EU Green Deal's escalating targets are accelerating fleet renewal programs in Madrid and Barcelona corridors. Catalonia's automotive supplier base is expanding column assist refurbishment capacity for aftermarket compliance upgrades.
Europe Electrically Powered Hydraulic Steering Market Competitive Landscape
Concentration sits with diversified automotive suppliers possessing captive electronics and hydraulics capabilities. The market structure organizes around three strategic archetypes: integrated system houses controlling full value chains, modular component specialists, and regionally focused aftermarket distributors. Competitive maneuvering centers on manufacturing scale expansion in Eastern European cost corridors and algorithmic road-feel differentiation through software licensing arrangements.
Among Germany-based diversified suppliers, ZF Friedrichshafen AG, Robert Bosch GmbH, and Continental AG exemplify the integrated archetype. These entities anchor competitive positioning through manufacturing presence across multiple EU member states. Japanese specialists including JTEKT Corporation and NSK Ltd occupy positions emphasizing precision component engineering. The competitive terrain rewards backward integration into motor controller electronics and upstream control over hydraulic pump casting operations.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive Group |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Robert Bosch GmbH |
| Continental AG |
| Hyundai Mobis |
| Valeo |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day semiconductor lead times for brushless DC motor controllers concentrate pricing power with integrated German suppliers possessing captive electronics divisions, while tier-2 competitors absorb margin compression from foundry allocation volatility. This inventory tension cascades through procurement hierarchies, favoring suppliers with backward integration into pump casting and seal fabrication over modular assemblers exposed to spot-market component costs.
Pricing Analysis
The customization-premium spread between configured-to-order active steering calibrations and standard rack assist architectures widens as software-defined road feel commands recurring licensing revenue. Three-tier pricing structure across premium, standard, and economy levels separates algorithmic differentiation from commodity hydraulic hardware, with certification grade and volume scale as primary price differentiation drivers. Pricing pressure stems from fleet procurement consolidation among German and Dutch logistics operators demanding common architectures across multi-brand purchases. Tier-1 suppliers face greatest price sensitivity from vehicle assemblers in Eastern Europe, while OEM direct contracts retain lowest sensitivity due to captive engineering relationships.
Supply Chain Analysis
Germany and Romania anchor steering system manufacturing, with Poland serving as an export hub for rack assist subassemblies supplying Eastern European vehicle assembly plants. Raw material dependencies center on aluminum die castings for pump housings, specialized seal elastomers compatible with bio-based hydraulic fluids, and rare-earth magnets for brushless DC motors. Single-source vulnerability concentrates in 40nm-90nm semiconductor node supply for motor controllers, where steering system suppliers compete with battery management electronics for foundry capacity. Distribution runs through consolidated OEM direct channels for rack assist architectures, while column assist and direct drive systems see heavier tier-1 supplier intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where active steering software licensing and road-feel calibration subscriptions expand faster than hardware shipments, creating recurring revenue layers that decouple supplier economics from unit volume cyclicality.
For Market Incumbents: Consolidate manufacturing scale advantages in Romania and Poland while deepening backward integration into motor controller electronics to offset semiconductor allocation volatility. Defend against full electric power steering substitution by accelerating 24V architecture qualification for heavy commercial vehicle electrification programs. Prioritize captive chemical engineering resources to navigate ECHA substance restrictions on hydraulic fluid formulations. For New Entrants and Emerging Players: Lead with aftermarket retrofit solutions targeting Iberian logistics operators in Spain and Portugal facing delayed EU CO2 compliance timelines, where column assist replacement units address underpenetrated fleet renewal demand. Establish partnerships with Eastern European vehicle assemblers lacking in-house validation capabilities for complete steering module sourcing. Position around functional safety engineering talent scarcity by recruiting ISO 26262 ASIL-D certified embedded software validation engineers from established German supplier ecosystems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers seeking to divest non-core steering divisions amid portfolio rationalization pressures. Long-term viability hinges on software-defined differentiation capabilities rather than hydraulic hardware scale, favoring acquisition of algorithmic road-feel calibration specialists over commodity pump manufacturers. Watch for inflection signals in steer-by-wire platform announcements from premium German OEMs, which would accelerate technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Enables common rack assist architectures across B-segment through E-segment vehicle programs for German and French OEMs. |
| Software-Defined Vehicle Investment | Active steering calibration algorithms command margin premiums through recurring licensing revenue from road-feel differentiation. |
| Geographic Manufacturing Footprint | Expansion into Poland and Romania reduces cost structures while maintaining CE marking and ECE R79 regulatory parity. |
| Backward Integration into Electronics | Captive motor controller production insulates against 40nm-90nm semiconductor node allocation volatility affecting competitors. |
| Bio-Based Fluid Qualification | ECHA substance restriction compliance on hydraulic seals creates competitive moat for suppliers with in-house chemical engineering. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance managers at German and French logistics operators. Secondary validation drew from vehicle production databases, IHS Markit registration data, ECE R79 type approval filings, and EU Green Deal regulatory monitoring frameworks. Bottom-up unit volume estimates triangulated against top-down market sizing from trade flow analysis across German, Polish, and Romanian manufacturing clusters.
Across the analysis window, the forecasting framework modeled demand trajectories by vehicle class, propulsion architecture, steering system technology, and regional production cluster. CAGRs were derived from regression analysis of historical adoption curves applied to EU CO2 mandate compliance schedules and fleet procurement consolidation patterns. Industry-specific inputs included semiconductor lead time volatility indices and ECHA substance restriction timelines affecting hydraulic fluid reformulation cycles.
Forecasts assume regulatory continuity in EU Green Deal CO2 reduction mandates and ECE R79 type approval harmonization; material policy shifts or accelerated F-Gas Regulation phase-down schedules would require re-modeling of technology substitution rates. Recalibration cycles align with material shifts in semiconductor supply availability, OEM platform announcement schedules, and ECHA restriction proposal finalization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Steering Damper Market
Powertrain
Fuel Injection Systems Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Automotive Turbocharger Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Automotive Driveline Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Automotive PTC Heaters Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Automotive Variable Oil Pump Market