
 Engine Support Bar Market | 2026-2036
Engine Support Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Support Bar Market Analytics
Aluminum is restructuring product economics across the engine support bar landscape as shops seek lighter equipment without sacrificing load ratings. VEVOR leverages direct-to-channel distribution to capture home mechanic and independent garage segments at scale. OTC sustains its position through deep calibration partnerships with North American dealership service departments. TrelleborgVibracoustic anchors premium positioning by integrating polymer damping expertise into vibration-isolated support architectures.
An engine support bar is a structural lifting and bracing device, typically fabricated from steel or aluminum with welded cross-members and adjustable feet, designed to suspend or stabilize powertrain components during removal, installation, or underbody service operations. Adjustable support bars command the widest addressable footprint by accommodating multiple vehicle platforms with a single SKU, while heavy-duty variants capture concentrated margin pools from fleet maintenance and commercial truck applications. Carbon fiber remains nascent due to cost barriers but attracts motorsport and aerospace ground-support niches where mass reduction justifies premium outlays.
OSHA workplace safety mandates in the United States, CE marking requirements under EU machinery directives, and China's GB standards enforced by SAMR collectively dictate load-testing protocols, material traceability, and operator training documentation. Compliance with these frameworks determines market access for imports and shapes domestic manufacturer R&D priorities around certified welding and finite-element validation. Stakeholders must monitor evolving alloy specifications and regional enforcement intensity to align inventory and certification investments with where demand is structurally heading.
Market Dynamics
Aluminum alloy substitution is compressing product weight while OSHA workplace lifting mandates force load-rating recalibration across fabrication lines. This material-regulatory intersection is redrawing procurement criteria for commercial garages and OEM service facilities.
Growth Catalysts
- OSHA Ergonomic Standards:Updated workplace lifting limits in the United States are accelerating replacement cycles for steel-heavy legacy equipment.
- Electric Vehicle Powertrain Servicing:Battery pack removal procedures require stabilized underbody access, expanding addressable demand from independent repair chains.
- Aluminum Extrusion Advances:Heat-treatment improvements enable comparable load ratings at reduced mass, reshaping shop-floor equipment preferences.
Market Restraints
- Aluminum Price Volatility:LME spot fluctuations compress margin predictability for fabricators committed to alloy-intensive designs.
- Welding Certification Bottlenecks:ASME and AWS qualification timelines extend production lead times for certified structural assemblies.
- Used Equipment Circulation:Secondary market refurbishment extends functional life of steel-based units, delaying new-equipment purchases.
Strategic Opportunities
- India Aftermarket Expansion:Commercial vehicle parc growth and fragmented garage networks create first-mover positioning for standardized support systems.
- Lightweight Composite Convergence:Carbon fiber-reinforced polymer hybrid bars target motorsport ground support where mass reduction commands premium positioning.
- Direct-to-Shop E-Commerce:Bypassing traditional tool distributors captures margin and reduces inventory float for independent mechanics.
Industry Challenges
- Finite-Element Validation Expertise:Certified simulation capability scarcity constrains rapid product iteration for load-rated aluminum designs.
- Multi-Jurisdictional Certification:Concurrent OSHA, CE marking, and GB standard compliance extends time-to-market for unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Support Bar Market |
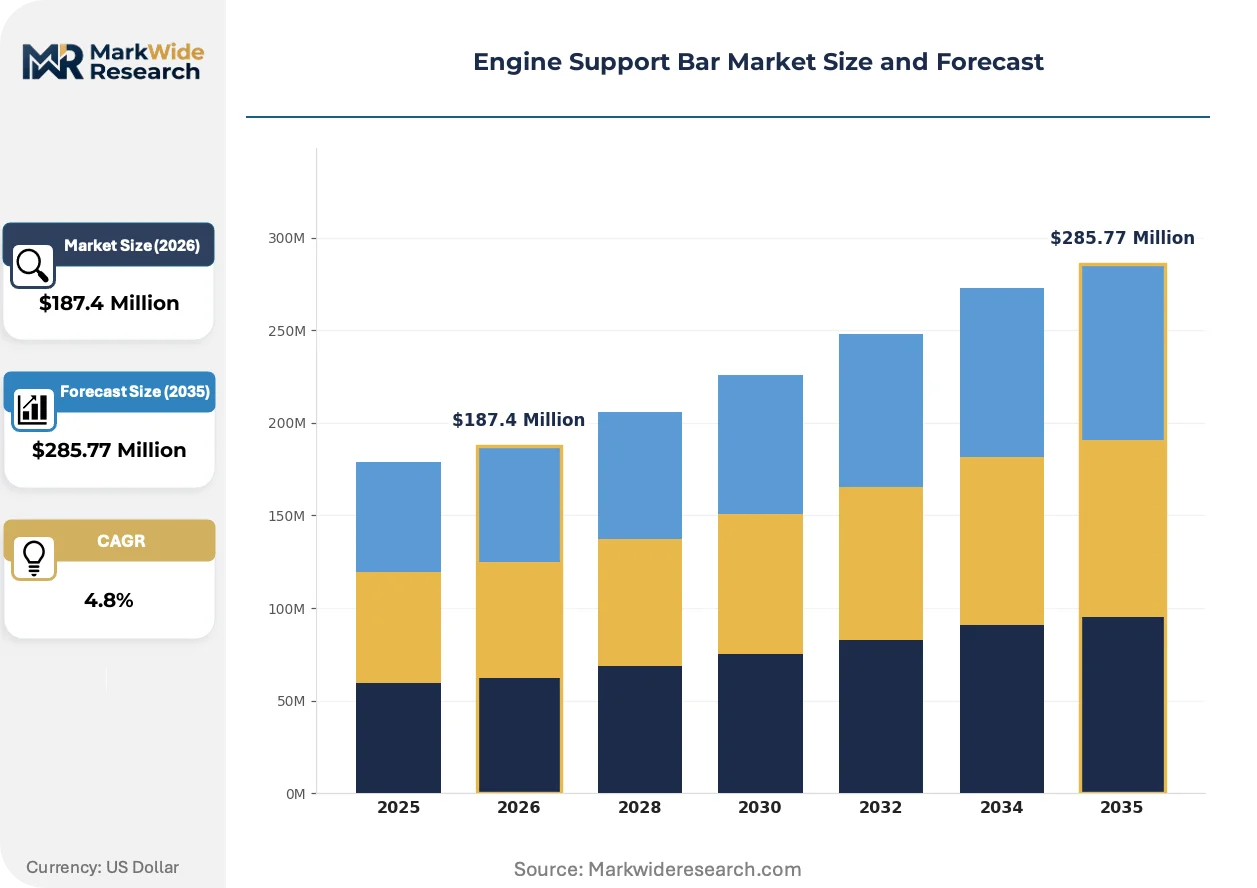
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Support Bars, Adjustable Support Bars, Fixed Support Bars, Heavy-Duty Support Bars Material: Steel, Aluminum, Composite, Carbon Fiber End User: Automotive Repair Shops, Home Mechanics, Industrial Maintenance, Vehicle Manufacturers Weight Capacity: Up to 1000 lbs, Up to 1500 lbs, Up to 2000 lbs, Others |
| Companies Covered | VEVOR, OTC, Kent-Moore, Carlyle, Harbor Freight, GSW Auto Parts, TrelleborgVibracoustic, ContiTech, Hutchinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Support Bar Market Evolving Landscape
Material science advances and regulatory load-documentation requirements are compressing traditional equipment refresh cycles. Fabricators now compete on validated weight reduction rather than nominal capacity claims.
Aluminum-magnesium alloy extrusions with T6 temper treatment deliver structural performance comparable to mild steel at approximately one-third density. Fleet maintenance operators in Germany and the United States are specifying these grades for portable support systems. This metallurgical shift is converging with polymer damping integration from vibration-isolation specialists, creating hybrid architectures that reduce transmitted load to shop-floor structures.
CE marking under EU machinery directives now mandates traceable weld documentation and third-party load testing for adjustable support mechanisms. Fabricators serving European aftermarket channels must maintain notified-body relationships and batch-level material certificates. Independent garage chains in France and Italy are prioritizing CE-compliant inventory to preempt liability exposure during workplace inspections.
Home mechanic segments are bypassing traditional tool distributors through manufacturer-direct digital channels, compressing price transparency and delivery expectations. VEVOR and similar direct-to-channel operators capture this flow with simplified SKUs and video-based setup documentation. This channel reconfiguration is most pronounced in the United States, where residential garage workshop investment accelerated post-2020.
Engine Support Bar Market Segmentation
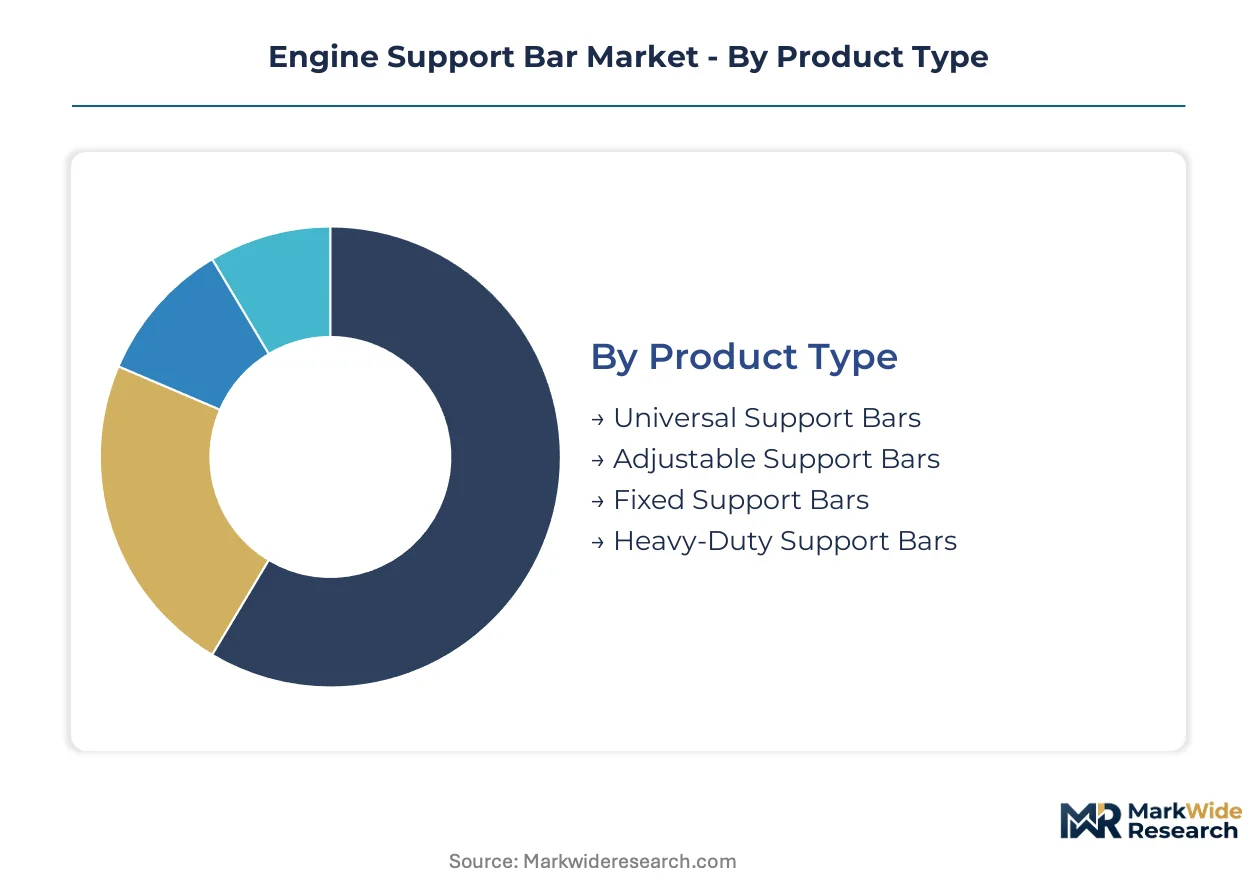
Equipment procurement decisions in the engine support bar market hinge on load certification requirements, shop-floor portability needs, and vehicle platform diversity. Segmentation reveals where fabricators can capture premium positioning versus where price competition dominates.
Product Type:
Buyer selection prioritizes SKU versatility against capital deployment constraints across commercial garage networks.
- Universal Support Bars:Single-frame designs accommodate multiple engine configurations through sliding cross-members and telescoping legs. Fleet maintenance operators in Germany favor these for standardized tool cribs serving mixed European and Asian vehicle parcs. OSHA load-documentation requirements are compressing procurement timelines as shops replace uncertified legacy equipment.
- Adjustable Support Bars:Modular architectures with pin-lock height adjustment and reversible yoke attachments dominate independent repair chain purchasing. These units command the widest addressable footprint by reducing inventory depth for multi-brand service facilities. Demand concentrates in the United States where dealership service departments prioritize platform flexibility for powertrain removal procedures.
- Fixed Support Bars:Welded rigid-frame constructions target dedicated assembly line installations at OEM facilities.
- Heavy-Duty Support Bars:Reinforced box-section designs serve commercial truck and off-highway equipment applications where load ratings exceed standard passenger vehicle requirements.
Adjustable support bars lead on scale; heavy-duty variants lead on momentum as commercial vehicle servicing expands.
Material:
Workplace ergonomics mandates and raw material cost exposure are redrawing fabrication priorities across production lines.
- Steel:Mild and high-strength low-alloy grades remain dominant in price-sensitive procurement channels and legacy fleet replacement cycles. Chinese commercial garage networks specify steel-intensive designs where capital constraints outweigh mass reduction benefits. ASME welding certification bottlenecks extend lead times for structural assemblies destined for regulated environments.
- Aluminum:6061-T6 and 6063-T6 extrusions deliver comparable yield strength to mild steel at approximately one-third density. United States automotive repair shops are specifying these grades under updated OSHA ergonomic lifting limits that restrict manual handling of equipment above threshold weights. Heat-treatment advances enable certified load ratings previously achievable only with steel architectures.
- Composite:Glass-reinforced polymer hybrid bars target corrosion-resistant applications in coastal and chemical exposure environments.
- Carbon Fiber:High-modulus prepreg layups serve motorsport ground support and aerospace maintenance where mass reduction justifies premium outlays.
Steel leads on installed base scale; aluminum leads on replacement cycle momentum as regulatory pressure intensifies.
End User:
Channel configuration and technical support requirements fragment demand across distinct purchasing workflows.
- Automotive Repair Shops:Multi-bay commercial facilities constitute the core revenue pool, with procurement decisions driven by insurance liability coverage and technician retention concerns. These buyers specify CE-marked or OSHA-compliant inventory to preempt workplace inspection penalties. Independent chains in France and Italy are consolidating supplier relationships to secure batch-level material traceability.
- Home Mechanics:Residential workshop investment accelerated post-2020 in the United States, with direct-to-channel operators capturing this flow through video-based setup documentation and simplified SKU offerings. Price transparency compresses margin but expands addressable volume for manufacturers with digital-native distribution.
- Industrial Maintenance:Manufacturing plant and logistics fleet facilities prioritize durability over portability for fixed-position powertrain service.
- Vehicle Manufacturers:OEM assembly plants specify custom-engineered support architectures integrated into production line automation.
Automotive repair shops lead on revenue concentration; home mechanics lead on channel expansion velocity.
Weight Capacity:
Load rating specifications directly correlate with end-use application severity and certification documentation requirements.
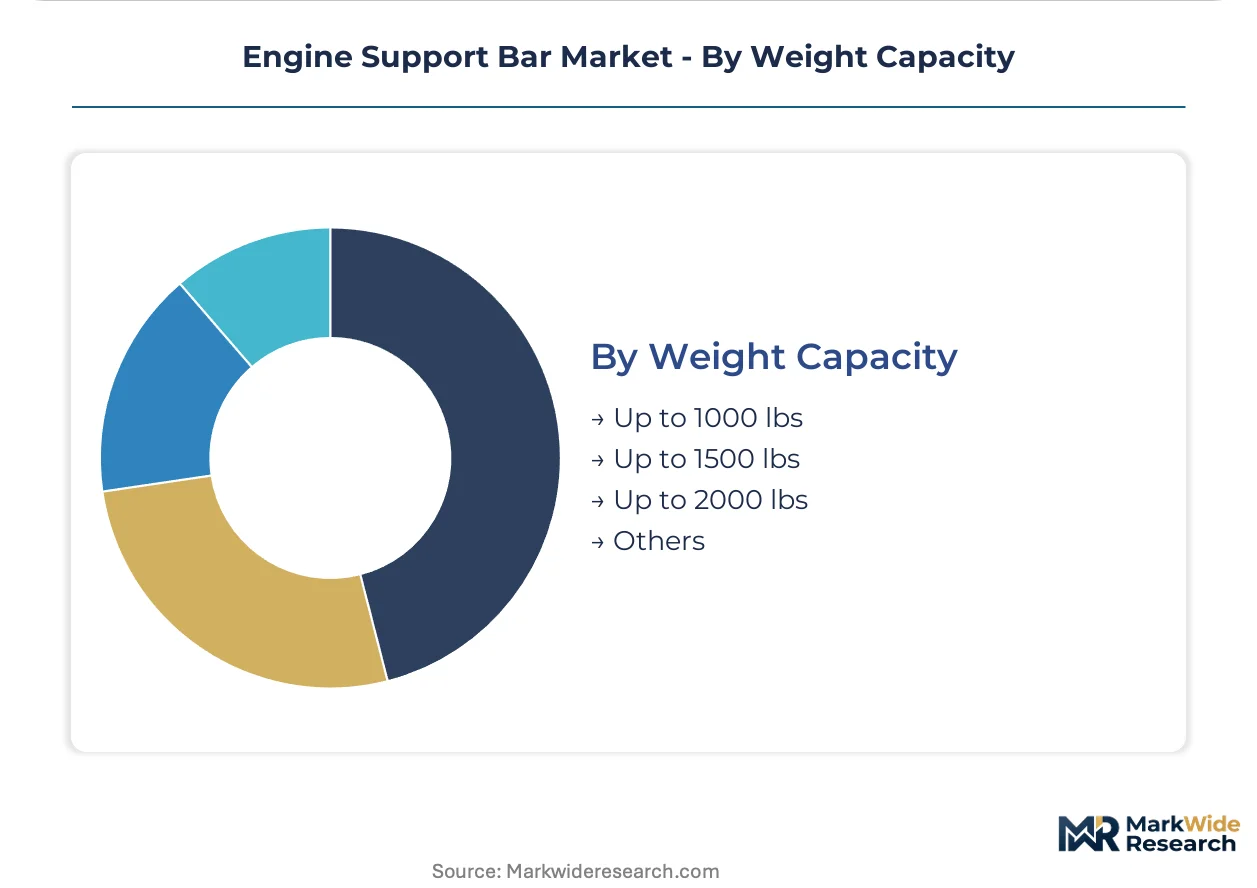
- Up to 1000 lbs:Passenger vehicle powertrain support dominates this tier, with compact cross-member designs targeting independent garage segments. These units face the most intense price competition from used equipment circulation and direct-to-channel imports.
- Up to 1500 lbs:Light commercial and performance vehicle applications drive specification in this intermediate band. United States dealership service departments prioritize these ratings for SUV and light truck powertrain removal where safety margins must accommodate technician positioning variability.
- Up to 2000 lbs:Heavy-duty commercial truck and specialty vehicle servicing requires these elevated ratings with reinforced leg structures.
- Others:Custom-engineered ratings above 2000 lbs serve mining equipment, rail, and aerospace ground support niches.
Up to 1000 lbs leads on unit volume; up to 1500 lbs leads on specification upgrading as vehicle mass increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive service corridors in the United States concentrate the densest procurement activity for engine support equipment, with commercial garage networks and OEM assembly facilities driving specification standards across the sector.
United States
Dealership service departments and independent repair chains account for concentrated demand as vehicle powertrain complexity rises. OSHA workplace lifting mandates accelerate replacement cycles for legacy steel-heavy equipment. Detroit's automotive service corridor anchors procurement volume for fleet maintenance operators standardizing tool cribs across mixed vehicle parcs.
Germany
Commercial vehicle parc expansion and stringent workplace safety enforcement shape equipment specifications. CE marking requirements under EU machinery directives mandate traceable weld documentation and third-party load testing. Stuttgart's automotive manufacturing cluster drives premium-tier demand for vibration-isolated support architectures integrated into OEM service workflows.
China
Domestic garage network densification and commercial vehicle fleet growth create procurement scale. GB standards enforced by SAMR dictate load-testing protocols and material traceability for structural lifting devices. Shanghai's Yangtze River Delta manufacturing belt concentrates fabrication capacity serving both domestic aftermarket and export channels.
India
Commercial vehicle parc growth and fragmented garage infrastructure generate first-mover positioning opportunities. BIS certification requirements shape product qualification timelines for structural equipment imports. Maharashtra's Pune-Nashik automotive corridor concentrates fleet maintenance facilities specifying standardized support systems for multi-brand servicing.
United Kingdom
Independent repair chain consolidation and insurance liability coverage requirements drive CE-marked inventory prioritization. Health and Safety Executive workplace inspection protocols enforce documented load ratings for powertrain lifting equipment. Birmingham's Midlands automotive service cluster anchors procurement for commercial garage networks seeking batch-level material traceability.
Engine Support Bar Market Competitive Landscape
Portfolio diversification dominates the current landscape as fabricators balance material substitution investments against certification documentation requirements. The vendor base spans three tiers: premium specialists integrating polymer damping expertise, mid-market generalists serving multi-brand repair chains, and direct-to-channel operators capturing home mechanic segments. Strategic archetypes include vibration-isolation technology licensors, aluminum extrusion specialists, and digital-native distributors. M&A activity and geographic expansion represent the dominant competitive moves as players seek regulatory compliance capabilities across OSHA, CE marking, and GB standard jurisdictions.
Among North American equipment specialists, OTC and Kent-Moore occupy positions within the premium-tier calibration-focused segment serving dealership service departments. VEVOR exemplifies the direct-to-channel archetype leveraging digital distribution to capture independent garage and residential workshop demand at scale. These three anchors illustrate how competitive positioning diverges across certification depth, channel configuration, and end-user technical support requirements.
| Leading Market Players |
|---|
| VEVOR |
| OTC |
| Kent-Moore |
| Carlyle |
| Harbor Freight |
| GSW Auto Parts |
| TrelleborgVibracoustic |
| ContiTech |
| Hutchinson |
| Others |
Value Network & Pricing Analysis
Dealership service departments and independent repair chains in the United States anchor procurement volume and compress pricing power toward certified-load documentation tiers. Cost pass-through from aluminum alloy volatility feeds directly into equipment refresh cycles as OSHA workplace mandates accelerate steel-to-aluminum substitution.
Pricing Analysis
Input-cost pass-through from LME aluminum spot movements dominates margin compression for fabricators committed to alloy-intensive designs. Three-tier pricing structure across premium, standard, and economy levels separates vibration-isolated architectures with polymer damping from basic welded-steel units and direct-to-channel imports. Pricing pressure stems from used equipment circulation extending functional life of legacy steel-based units. Home mechanics exhibit highest price sensitivity through digital-native channels, while OEM service facilities prioritize certification depth over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's GB standard enforcement and India's BIS certification timelines reshape sourcing for structural assemblies destined for regulated environments. Raw aluminum extrusion capacity concentrates in China, Germany, and the United States, with heat-treatment services clustering near automotive manufacturing corridors. Supply chains draw from 6061-T6 and 6063-T6 alloy stock, polymer damping components, and certified welding consumables. Single-source vulnerability sits with heat-treatment facilities qualified for structural load ratings. Distribution runs through traditional tool distributors serving commercial garages and direct-to-channel platforms capturing independent mechanics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where premium positioning in vibration-isolated architectures captures specification upgrading from commercial vehicle fleet operators. Demand is shifting toward certified aluminum designs as workplace ergonomic mandates displace uncertified legacy equipment.
For Market Incumbents: Cement calibration partnerships with North American dealership service departments to lock in specification-setting authority. Deepen polymer damping integration capabilities to defend margin pools against aluminum extrusion specialists entering from adjacent vibration-control markets. Prioritize ASME welding certification capacity additions to compress lead times for OSHA-compliant structural assemblies. For New Entrants and Emerging Players: Direct-to-channel e-commerce routes offer lowest barrier entry for capturing home mechanic segments with simplified SKUs and video-based setup documentation. Target India's fragmented commercial garage infrastructure where BIS certification requirements create qualification timelines that favor first-mover standardization. Pursue carbon fiber-reinforced polymer hybrid positioning for motorsport ground support niches where mass reduction commands premium pricing. For Investors and Strategic Acquirers: Tool distributors with calibration service networks are the most active acquirer in this space as channel control becomes decisive for specification influence. Long-term viability hinges on regulatory compliance capabilities spanning OSHA, CE marking, and GB standard jurisdictions. Acquisition target archetype: aluminum extrusion specialists with dormant welding certification capacity. Watch aluminum-magnesium alloy adoption rates in German fleet maintenance specifications as inflection indicator for material substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Welding Certification Investment | Compresses production lead times for OSHA-compliant structural assemblies serving regulated environments. |
| Polymer Damping Technology Licensing | Enables premium-tier positioning through vibration-isolated architectures integrated into OEM service workflows. |
| Direct-to-Channel E-Commerce Launch | Captures home mechanic demand with video-based setup documentation bypassing traditional tool distributors. |
| Aluminum Extrusion Capacity Expansion | Secures supply of 6061-T6 and 6063-T6 grades as workplace ergonomic mandates accelerate material substitution. |
| Multi-Jurisdictional Certification Program | Extends market access across OSHA, CE marking, and GB standard enforcement zones for unified product platforms. |
Research Methodology
Bottom-up automotive repair shop modeling reconciled against top-down aluminum extrusion capacity tracking forms the analytical core of this study. Primary interviews with maintenance directors at commercial garage chains, OEM procurement teams, aftermarket distributors, and welding certification auditors combined with secondary validation from OSHA enforcement records, CE marking databases, customs trade data, and automotive production statistics. Triangulation across these sources calibrated equipment replacement cycle assumptions and material substitution trajectories.
Historical trendline analysis of equipment refresh rates and regulatory compliance investments informed projection parameters across the analysis window. Segmentation dimensions modeled include product type architecture, material grade tier, end-user channel configuration, and regional regulatory cluster. CAGRs derived from weighted average of bottom-up demand build and top-down supply capacity constraints, incorporating aluminum price elasticity and certification timeline assumptions specific to structural lifting equipment.
The model assumes a particular technology adoption path; alternative pathways for carbon fiber-reinforced polymer hybrid architectures would alter the outlook if cost curves compress faster than projected. Forecasts reflect assumptions around OSHA enforcement intensity, LME aluminum volatility, and welding certification bottleneck resolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Engine Cylinder Liners Market
Powertrain
CNG Powertrain Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Car Oil Filter Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Automotive Drivetrain Market
Powertrain
Automotive Powertrain Components Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Half Shaft Market
Powertrain
Engines Market
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Asia Pacific Automotive Engine Market