
 Car Oil Filter Market | 2026-2036
Car Oil Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Car Oil Filter Market Analytics
Subscription-based fleet maintenance programs is rebalancing how car oil filters move through distribution channels. Mann+Hummel Group leverages its captive aftermarket network to sustain recurring revenue streams from commercial vehicle operators. Bosch Group anchors European supply through its dense service-center footprint. Donaldson Company competes in North American heavy-duty segments with specialized filtration engineering.
A car oil filter is a replaceable component that removes contaminants from engine lubricating oil through pleated cellulose, synthetic fiber, or glass fiber media rated to specific micron retention thresholds, preserving engine wear surfaces and extending operational life. Spin-on configurations still dominate installed base volumes, though cartridge designs are gaining share in newer passenger car platforms for reduced material waste. Synthetic fiber media commands premium positioning as OEMs tighten particle-efficiency specifications under longer drain intervals.
EPA tailpipe and emissions regulations in the United States, EU Green Deal automotive benchmarks, and China's MIIT fuel-consumption standards collectively tighten the performance envelope for filtration systems. California's Air Resources Board extends these requirements through state-level amendments that filter suppliers must certify against. Stakeholders should monitor how software-defined vehicle architectures alter maintenance-alert logic and filter-replacement timing.
Market Dynamics
Fleet operators in North America and Europe are consolidating maintenance spend into subscription contracts, compressing traditional wholesale distribution and forcing filter suppliers to build direct service relationships with commercial vehicle operators.
Growth Catalysts
- EU Green Deal automotive benchmarks:Tightening emissions thresholds in Europe mandate higher particle retention efficiency, accelerating replacement cycles for premium synthetic media filters in diesel and hybrid powertrains.
- Extended drain intervals:OEM specifications for 15,000+ mile oil change intervals require advanced glass fiber media capable of maintaining flow rates under thermal degradation, expanding addressable filter value per vehicle.
- China's MIIT fuel-consumption standards:Domestic automakers around Shanghai and Guangzhou are upgrading filtration systems to meet corporate average fuel economy mandates, pulling demand for low-pressure-drop designs.
Market Restraints
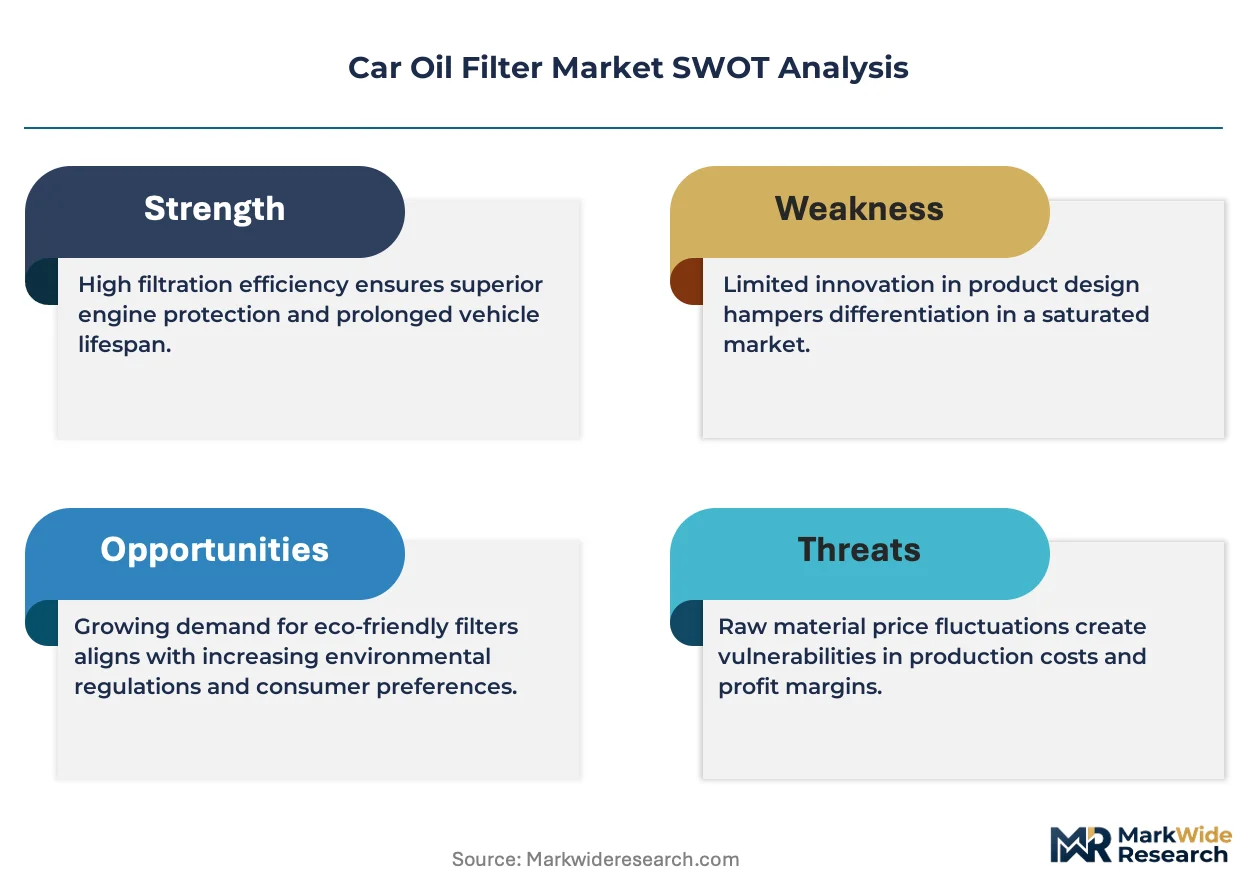
- Cellulose pulp input volatility:Filter media producers face margin pressure from fluctuating wood pulp prices tied to Brazilian and Indonesian supply disruptions, compressing economy-tier product profitability.
- Cartridge design transition costs:Tooling retooling for cartridge-type housings requires capital outlays that smaller Tier-2 suppliers cannot absorb, concentrating production among integrated system manufacturers.
- California Air Resources Board certification friction:State-level amendments to EPA baseline standards create dual compliance burdens for aftermarket suppliers lacking in-house testing infrastructure.
Strategic Opportunities
- Software-defined vehicle architectures:Predictive maintenance algorithms in connected powertrains enable condition-based filter replacement, creating data-service revenue streams for suppliers with telematics partnerships.
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive parts are drawing filter manufacturing investment toward Chennai and Pune industrial corridors.
- Closed-loop cartridge recovery programs:Regulatory pressure on industrial waste in Germany's manufacturing clusters is creating pull for returnable metal filter housings with replaceable media elements.
Industry Challenges
- Filter media engineering talent scarcity:Specialized knowledge in nanofiber layering and pleat geometry optimization concentrates among aging technical workforces in Stuttgart and Detroit engineering centers.
- Legacy fleet diagnostic incompatibility:Older commercial vehicles lack oil quality sensors, preventing adoption of predictive replacement models and forcing continued calendar-based maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Oil Filter Market |
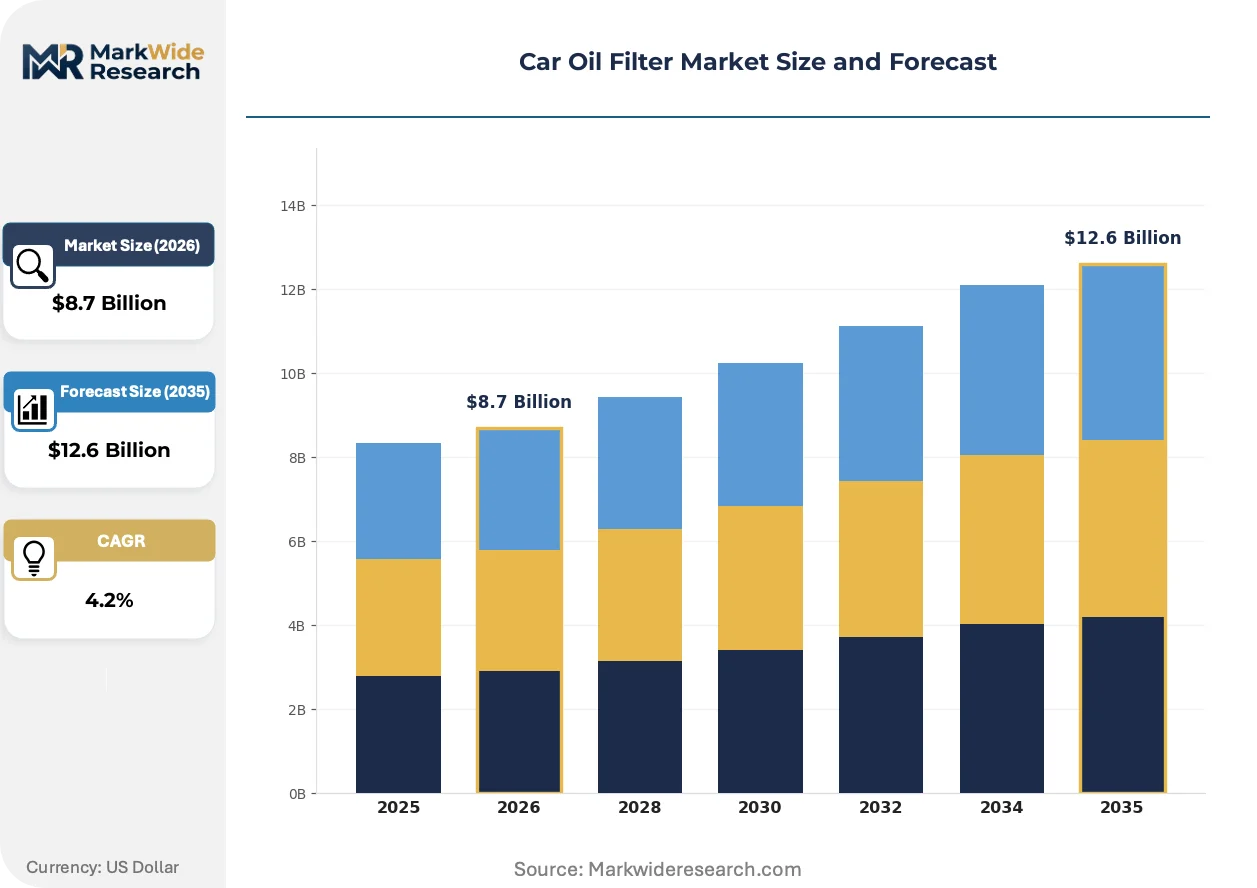
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin-on, Cartridge, Strainer, Bypass Material: Cellulose, Synthetic Fiber, Glass Fiber, Metal Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Trucks Maintenance Type: Scheduled, On-Demand, Preventive, Corrective |
| Companies Covered | Denso Corporation, Donaldson Company, Bosch Group, Hengst SE, Atmus Filtration Technologies, Mann+Hummel Group, Fram Group, ACDelco, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Oil Filter Market Evolving Landscape
Synthetic fiber media formulations and connected vehicle diagnostics are converging to redefine replacement timing logic, while regulatory pressure on particulate emissions intensifies specification tiers across OEM and aftermarket channels.
Glass fiber composite media is integrating with multi-layer cellulose substrates to achieve sub-20-micron retention ratings without flow restriction penalties. European premium passenger car platforms are adopting these formulations first. This convergence is integrating filter performance into broader powertrain thermal management strategies rather than treating filtration as an isolated component specification.
EPA tailpipe regulations combined with California's state-level amendments are tightening permissible oil consumption rates, which indirectly mandates lower bypass rates during cold-start viscosity spikes. Heavy-duty diesel applications face the steepest compliance ramps. Filter suppliers are responding with bypass valve recalibration and higher-capacity media packs certified to CARB durability protocols.
Commercial fleet operators are unbundling filter procurement from lube service contracts, creating direct sourcing relationships with manufacturers for high-volume scheduled replacements. Independent service centers in the US Midwest and German Ruhr region are losing share to captive distributor networks. This disintermediation is most visible among Class 8 truck operators running centralized maintenance depots across interstate corridors.
Car Oil Filter Market Segmentation
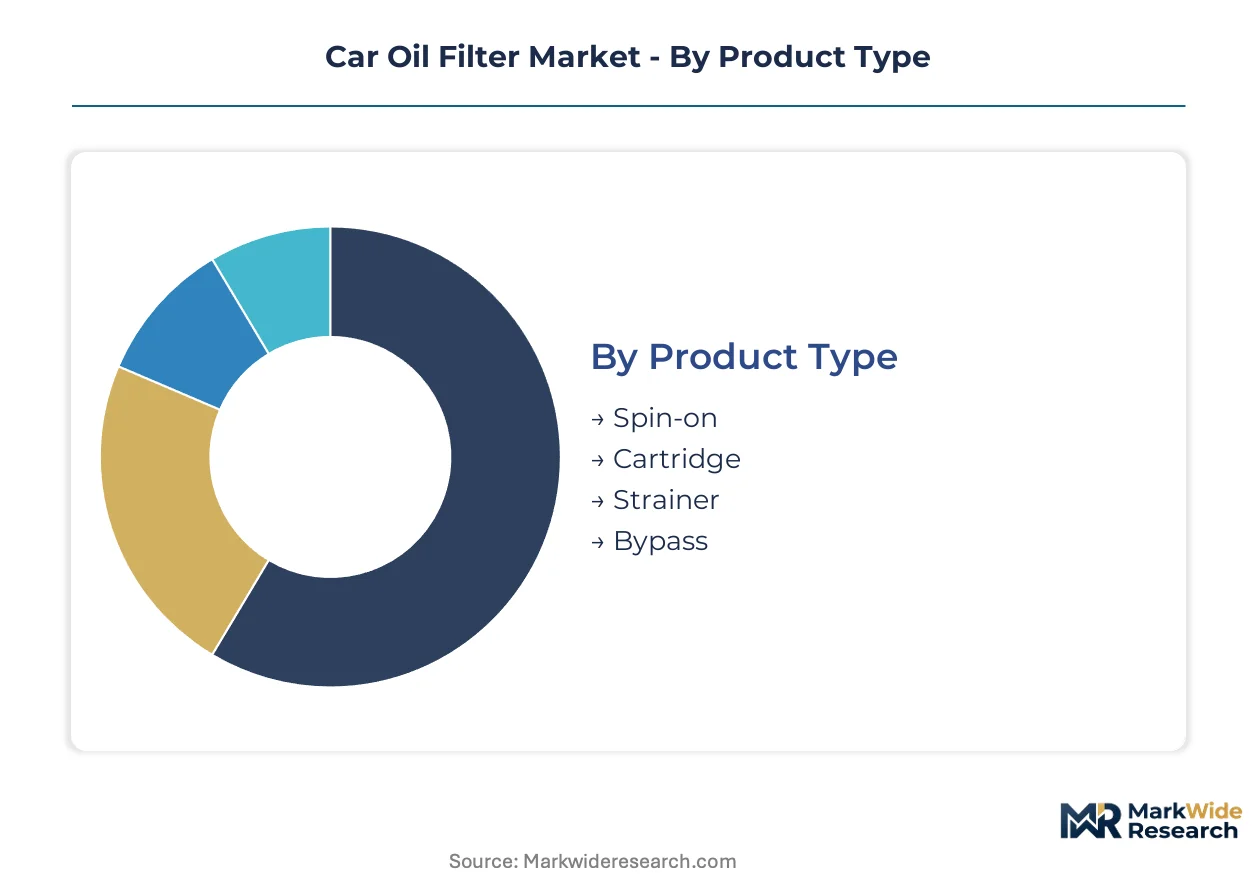
Filter buyers prioritize retention efficiency and service integration over unit cost alone. Segmentation reveals how material specifications and vehicle platform requirements reshape procurement patterns across OEM and aftermarket channels.
Product Type:
Fleet operators and independent service centers choose housing configurations based on tool compatibility and disposal economics.
- Spin-on:Self-contained steel canister with integrated bypass valve dominates legacy installed base across North American commercial fleets. Demand concentrates with Class 6-8 truck operators in Texas and Ohio running centralized maintenance depots, constrained by rising steel input costs and landfill disposal fees.
- Cartridge:Replaceable media element within permanent housing reduces material waste per service event. European OEM platforms around Stuttgart and Wolfsburg are mandating cartridge architectures for new passenger car designs, driven by EU packaging waste directives and corporate sustainability targets.
- Strainer:Coarse mesh screen for initial debris capture in suction lines sees residual demand from vintage vehicle restoration and industrial equipment crossover applications.
- Bypass:Secondary filtration loop handling 5-10% of total oil flow extends drain intervals in severe-service mining and construction equipment operating in Western Australia's Pilbara region.
Volume sits with spin-on configurations; growth tilts toward cartridge designs.
Material:
Media composition directly determines particle retention ratings, thermal degradation resistance, and pricing tier placement.
- Cellulose:Pleated wood pulp substrate treated with phenolic resin for structural rigidity under pressure differentials. Economy-tier aftermarket demand clusters with independent repair shops in Mexico and Southeast Asia, pressured by Brazilian pulp supply volatility and margin compression.
- Synthetic Fiber:Melt-blown polypropylene and polyester blends achieve 99% efficiency at 20 microns with lower flow restriction than cellulose. Premium passenger car platforms from Germany and Japan specify synthetic media for 15,000-mile drain intervals, expanding addressable value per vehicle.
- Glass Fiber:Borosilicate microfibers layered with cellulose support substrates reach sub-10-micron retention without permeability penalties. Heavy-duty diesel applications in California and the EU face steepest compliance ramps under tightened oil consumption regulations.
- Metal:Stainless steel mesh for reusable strainer elements and permanent cartridge housings. Germany's industrial clusters are piloting closed-loop recovery programs for returnable metal housings under regulatory pressure on manufacturing waste.
Synthetic fiber commands premium positioning; glass fiber composite formulations are climbing the fastest on emissions-driven specification upgrades.
Vehicle Type:
Platform duty cycles and engine architecture determine filter capacity requirements and replacement frequency.
- Passenger Cars:Compact spin-on and cartridge configurations sized for 4-6 liter sump capacities. China's domestic automakers around Shanghai and Guangzhou are upgrading to low-pressure-drop designs to meet MIIT fuel-consumption standards.
- Commercial Vehicles:High-capacity media packs with reinforced housings for 10-15 liter diesel engines. Fleet operators across US interstate corridors are consolidating procurement into direct manufacturer relationships, bypassing traditional wholesale distribution.
- SUVs:Intermediate form factors accommodating higher displacement engines and off-road debris loads. North American and Middle Eastern markets show concentration in premium synthetic media specifications.
- Trucks:Severe-service filtration for stop-start urban delivery and long-haul highway operation. Predictive maintenance algorithms in connected powertrains are enabling condition-based replacement timing for telematics-equipped Class 8 vehicles.
Commercial vehicles generate highest per-unit filter value; passenger car platforms show steepest expansion trajectory on electrification-transition service mix shifts.
Maintenance Type:
Service model economics determine whether filters move through subscription contracts, event-driven retail, or integrated OEM programs.
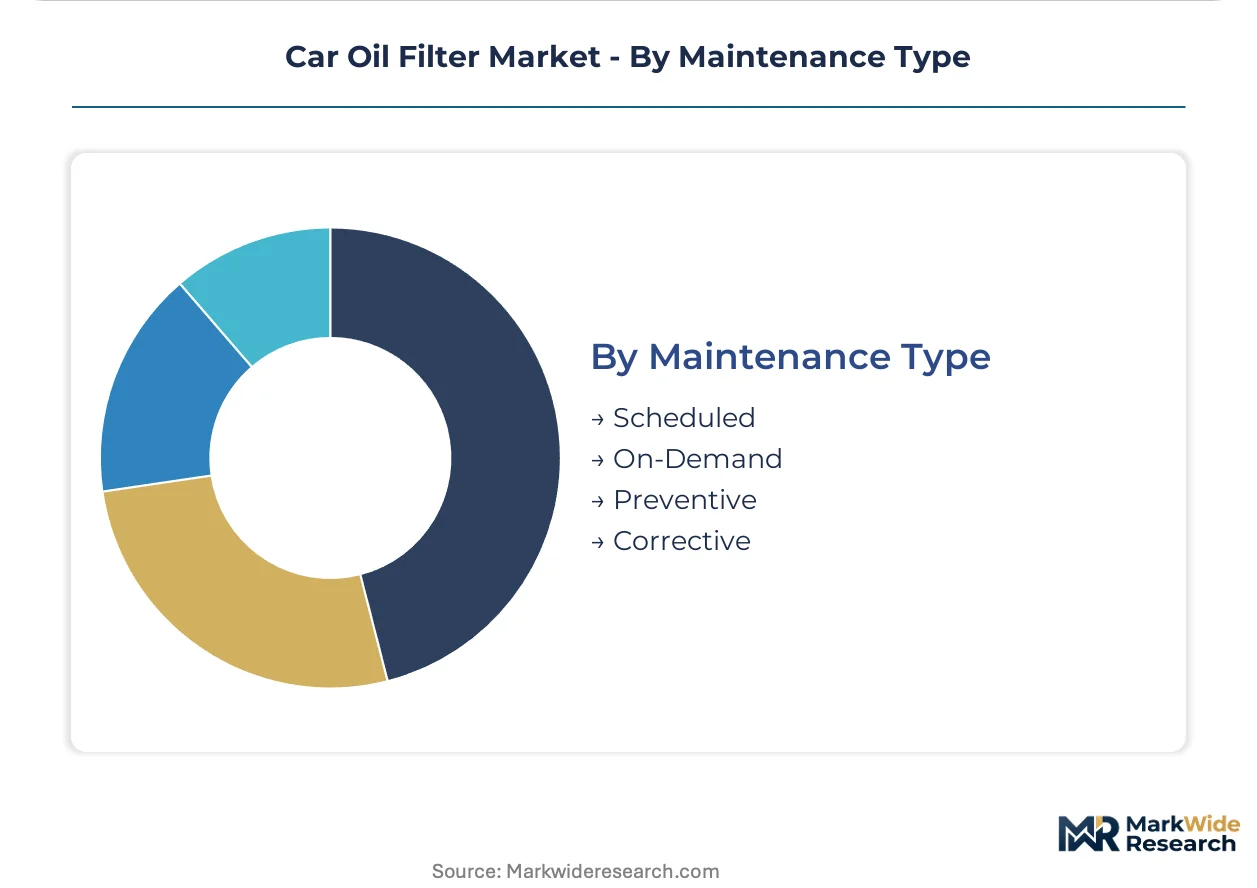
- Scheduled:Calendar or mileage-based replacement intervals tied to warranty compliance and residual value preservation. Subscription-based fleet maintenance programs across North America and Europe are compressing traditional wholesale channels.
- On-Demand:Reactive service triggered by dashboard alerts or diagnostic trouble codes. Software-defined vehicle architectures are recalibrating alert logic and replacement timing through oil quality sensors.
- Preventive:Condition monitoring and predictive algorithms extending intervals based on actual contamination load. Connected powertrain data partnerships are creating recurring revenue streams for filter suppliers with telematics integration.
- Corrective:Post-failure replacement following engine damage or contamination events. Legacy fleet vehicles lacking oil quality sensors force continued calendar-based maintenance in older commercial operations.
Scheduled maintenance retains largest volume share; preventive and on-demand models are gaining share fastest on connected vehicle penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of car oil filters consumed worldwide, while the United States and Germany absorb premium-tier volumes through fleet-intensive aftermarket channels. This production-consumption asymmetry shapes trade flows and pricing stratification across regions.
United States
Class 8 truck operators across Texas and Ohio run centralized maintenance depots that pull high-capacity spin-on filters in scheduled volumes. EPA tailpipe regulations and California Air Resources Board amendments tighten oil consumption limits, forcing bypass valve recalibration in heavy-duty applications. Filter procurement is consolidating into direct manufacturer relationships, bypassing traditional wholesale distribution in the Midwest.
Germany
Stuttgart and Wolfsburg engineering centers concentrate nanofiber layering expertise for premium synthetic media formulations. EU Green Deal automotive benchmarks mandate higher particle retention efficiency, accelerating replacement cycles for diesel and hybrid powertrains. Closed-loop cartridge recovery programs are piloting returnable metal housings under regulatory pressure on industrial waste in manufacturing clusters.
China
Domestic automakers around Shanghai and Guangzhou upgrade filtration systems to meet MIIT fuel-consumption standards, pulling demand for low-pressure-drop designs. The country's MIIT corporate average fuel economy mandates are tightening faster than EPA or EU trajectories. Manufacturing investment is concentrating in Yangtze River Delta automotive supplier parks serving export and domestic OEM platforms.
India
Chennai and Pune industrial corridors are drawing filter manufacturing investment through the PLI scheme for auto components. Fleet operators in the Delhi-Mumbai freight corridor are expanding scheduled maintenance programs. Domestic production is displacing imports for economy-tier cellulose media serving the independent aftermarket.
Japan
Tokyo and Nagoya-based OEMs specify synthetic fiber media for 15,000-mile drain intervals, expanding addressable filter value per vehicle. METI fuel-efficiency standards align with premium positioning for glass fiber composite formulations. Technical partnerships between filter suppliers and powertrain engineers concentrate in Kanto and Chubu regions.
Car Oil Filter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material grades and service integration models. The vendor base organizes into three tiers: integrated system manufacturers with captive aftermarket networks, specialized filtration engineers serving severe-service niches, and regional fabricators competing on cellulose economy volumes. Consolidation pressures concentrate production among players with in-house testing infrastructure for dual EPA-CARB compliance. Strategic moves center on telematics partnerships for predictive maintenance data services and backward integration into synthetic media resin supply.
Among Germany-based integrated manufacturers, Mann+Hummel Group and MAHLE GmbH exemplify the captive aftermarket network archetype, leveraging dense service-center relationships to sustain recurring revenue from commercial vehicle operators. Donaldson Company occupies a position among North American heavy-duty specialists, competing through filtration engineering depth in mining and construction applications. These three anchors represent divergent scale and specialization strategies within a market where direct fleet relationships are displacing traditional distribution.
| Leading Market Players |
|---|
| Denso Corporation |
| Donaldson Company |
| Bosch Group |
| Hengst SE |
| Atmus Filtration Technologies |
| Mann+Hummel Group |
| Fram Group |
| ACDelco |
| MAHLE GmbH |
| Others |
Value Network & Pricing Analysis
Brazilian wood pulp volatility feeds directly into cellulose media pricing tiers, compressing economy-segment margins while synthetic fiber formulations command premium positioning through OEM certification requirements.
Pricing Analysis
Cost-down pressure on economy-tier cellulose products accelerates because Brazilian and Indonesian pulp supply disruptions squeeze converter margins. Three-tier pricing structure across premium synthetic, standard blended, and economy cellulose levels separates certified OEM supply from aftermarket alternatives. Pricing pressure stems from fleet procurement consolidation into direct manufacturer contracts. Independent repair shops in Mexico and Southeast Asia exhibit highest price sensitivity; German and Japanese OEM platforms show lowest sensitivity due to specification-locked sourcing.
Supply Chain Analysis
Direct-to-fleet channels handle high-volume scheduled demand, displacing traditional wholesale distribution across North American interstate corridors. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta supplier parks serving export platforms. Raw material flows draw from Brazilian pulp forests, Saudi resin feedstocks, and German specialty chemical producers. Single-source vulnerability concentrates in cellulose pulp supply. Distribution runs through captive aftermarket networks for commercial vehicle operators and OEM-authorized service centers for passenger car platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cartridge-type filter architectures and predictive maintenance algorithms are displacing legacy spin-on configurations and calendar-based replacement schedules, reconfiguring competitive advantage around telematics integration and sustainable design.
For Market Incumbents: Cement control over synthetic fiber media resin supply through backward integration into polypropylene feedstocks. Expand in-house testing infrastructure for dual EPA-CARB compliance certification. Defend against emerging telematics-native entrants by embedding oil quality sensors into filter housings for data-service revenue capture. For New Entrants and Emerging Players: Fleet telematics providers represent the most accessible channel partnership for predictive maintenance algorithm deployment. Target India's PLI-subsidized manufacturing corridors around Chennai and Pune for economy-tier cellulose production. Penetrate through closed-loop cartridge recovery programs serving Germany's industrial waste regulations. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized filtration engineers with severe-service mining and construction expertise in Western Australia's Pilbara region. Long-term viability hinges on software-defined vehicle integration capabilities and synthetic media formulation IP. Watch for inflection signals in connected Class 8 truck penetration rates across US interstate freight corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Partnership Development | Enables condition-based replacement timing for connected commercial fleets. |
| Backward Integration into Synthetic Resins | Secures polypropylene supply for premium media formulations against feedstock volatility. |
| Closed-Loop Cartridge Recovery Program | Aligns with EU packaging waste directives and German industrial waste regulations. |
| Dual EPA-CARB Certification Investment | Unlocks California aftermarket access bypassing state-level compliance friction. |
| India PLI Manufacturing Footprint | Captures production-linked incentives while serving domestic and export OEM demand. |
Research Methodology
Trade databases, automotive production registries, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews across OEM platform engineers, aftermarket distributor procurement heads, fleet maintenance directors, and filtration media R&D specialists. Bottom-up and top-down triangulation validated volume estimates against customs data and vehicle registration flows.
Bottom-up modeling anchored projections across the analysis window, segmenting by filter configuration type, media material grade, vehicle platform architecture, and maintenance service model. CAGRs derived from production volume trajectories, content-per-vehicle assumptions, and replacement frequency shifts under extended drain intervals. Forecast inputs incorporated MIIT fuel-consumption standard compliance costs and EU Green Deal specification upgrade timelines.
Several conditions sit outside the modeled scope, including geopolitical trade restriction scenarios, raw material supply chain disruptions beyond historical variance bands, and accelerated electrification transitions that eliminate internal combustion service demand. Forecasts reflect documented assumptions about regulatory implementation pacing and fleet telematics adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Engine Support Bar Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Half Shaft Market
Powertrain
Gasoline Turbochargers Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Engine Actuators Market
Powertrain
Natural Gas Engines Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Global Automotive Dyno Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Automotive Carburetor Market
Powertrain
Internal Combustion Engine Market