
 Global Automotive Pneumatic Valve Market | 2026-2036
Global Automotive Pneumatic Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Pneumatic Valve Market Intelligence
The substitution of heavier metals with lightweight composite materials in valve bodies is broadening the application scope for pneumatic systems in electric vehicles. SMC Corporation specializes in miniaturized and high-flow solenoid valves for complex automated systems. Robert Bosch GmbH leverages its extensive electronics expertise to integrate smart controls into its pneumatic valve offerings. Continental AG competes by offering integrated chassis and safety system solutions for major automotive OEMs.
Automotive pneumatic valves are devices that control the flow, pressure, and direction of compressed air within a vehicle's systems. These components, often operating at pressures between 8 and 12 bar, are crucial for functions like air brakes, suspension height control, and transmission shifting. Among product types, solenoid valves command a significant share due to their electronic controllability. The commercial vehicles application segment remains the largest volume consumer, driven by the mandatory use of air brake systems in heavy-duty trucks.
Vehicle safety and emissions standards directly influence valve design and performance requirements. Regulations from the US EPA, compliance with EU directives on vehicle emissions, and China's GB standards for commercial vehicle safety all mandate reliable and efficient pneumatic components. Suppliers must now decide whether to focus on high-volume standard components or invest in specialized electro-pneumatic technologies for next-generation vehicle architectures.
Market Dynamics
The central structural force shaping the automotive pneumatic valve market is the convergence of stringent emissions regulations with the architectural demands of electric vehicles. This combination accelerates the displacement of purely mechanical systems in favor of integrated electro-pneumatic technologies for enhanced efficiency and control.
Growth Catalysts
- Stringent Safety Mandates:China's GB standards for commercial vehicle safety and similar regulations in other regions require advanced, reliable air brake systems, directly driving demand for high-performance pneumatic control valves in heavy-duty trucks and buses.
- Material Innovation:The adoption of lightweight composite materials for valve bodies and internal components reduces overall vehicle weight, making pneumatic systems more viable for mass-sensitive electric vehicles and improving fuel economy in internal combustion engine models.
- Commercial Vehicle Automation:The increasing use of automated manual transmissions (AMTs) and sophisticated air suspension systems in commercial vehicles requires a greater number of electronically controlled solenoid valves for precise and rapid actuation.
Market Restraints
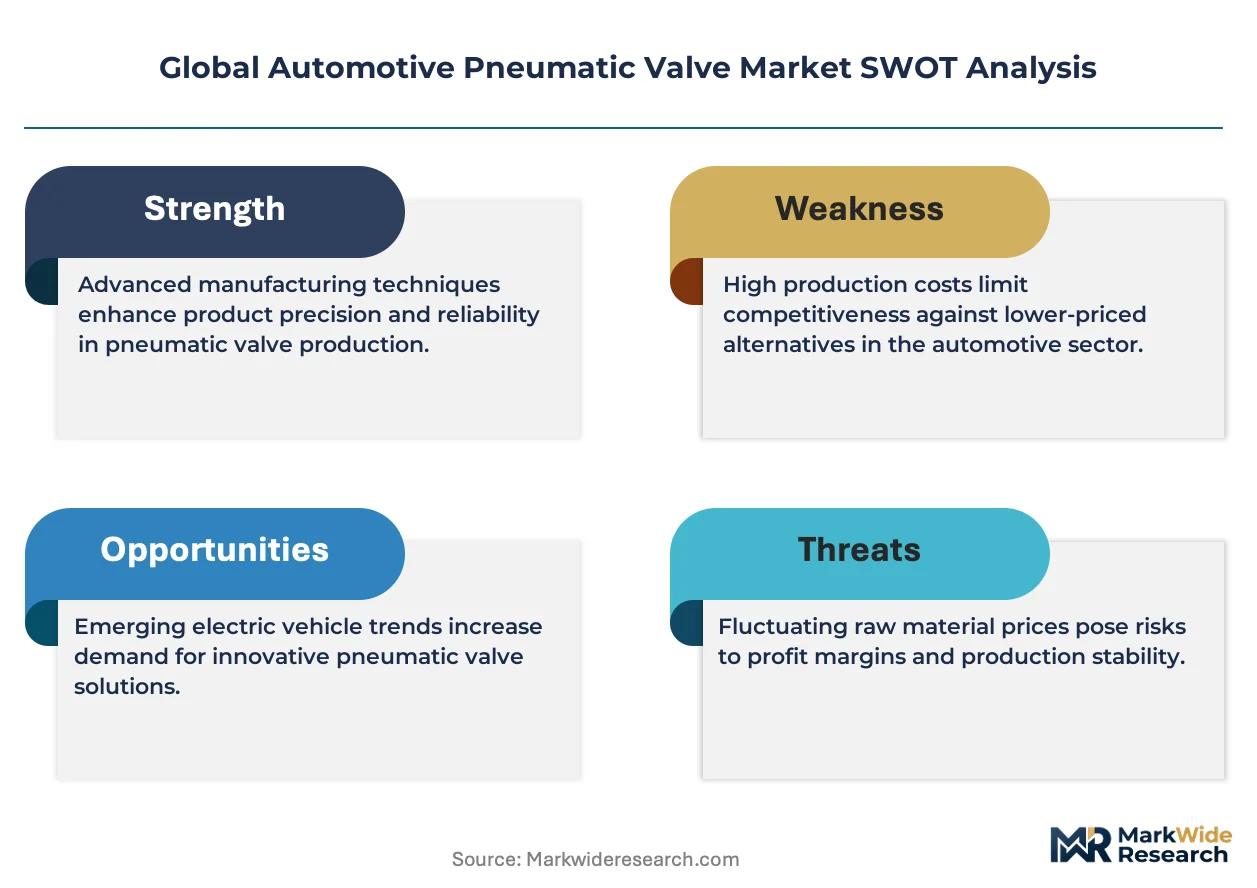
- High System Cost:The initial investment for advanced electro-pneumatic systems is significantly higher than for traditional mechanical or hydraulic alternatives, limiting their adoption in budget-focused vehicle segments and price-sensitive developing markets.
- Competition from Hydraulics:In the passenger vehicle segment, hydraulic systems remain a deeply entrenched and cost-effective solution for braking and power steering, presenting a formidable substitution barrier for pneumatic technologies.
- Technical Integration Hurdles:Integrating pneumatic systems with the unique thermal management and high-voltage power architectures of battery electric vehicles presents significant engineering challenges, slowing development cycles.
Strategic Opportunities
- Aftermarket in Developing Economies:The large and aging commercial vehicle fleets in countries like Brazil and Mexico create a substantial opportunity for aftermarket sales of standardized replacement valves and repair kits.
- Active Aerodynamics:Emerging applications in active aerodynamic systems, such as movable spoilers and grille shutters on performance and electric vehicles, open a new niche for specialized, fast-acting pneumatic valves.
- Smart Valve Development:Integrating sensors and microcontrollers directly into valve assemblies to create self-diagnosing, predictive maintenance components offers a path to higher-margin product lines for suppliers.
Industry Challenges
- Service and Repair Skill Gap:A persistent shortage of technicians trained to diagnose and service complex electro-pneumatic systems creates bottlenecks in the aftermarket, particularly for independent repair shops.
- Cybersecurity Compliance:As valves become connected components within the vehicle network, suppliers face the challenge of meeting evolving and often fragmented cybersecurity standards like ISO/SAE 21434.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Pneumatic Valve Market |
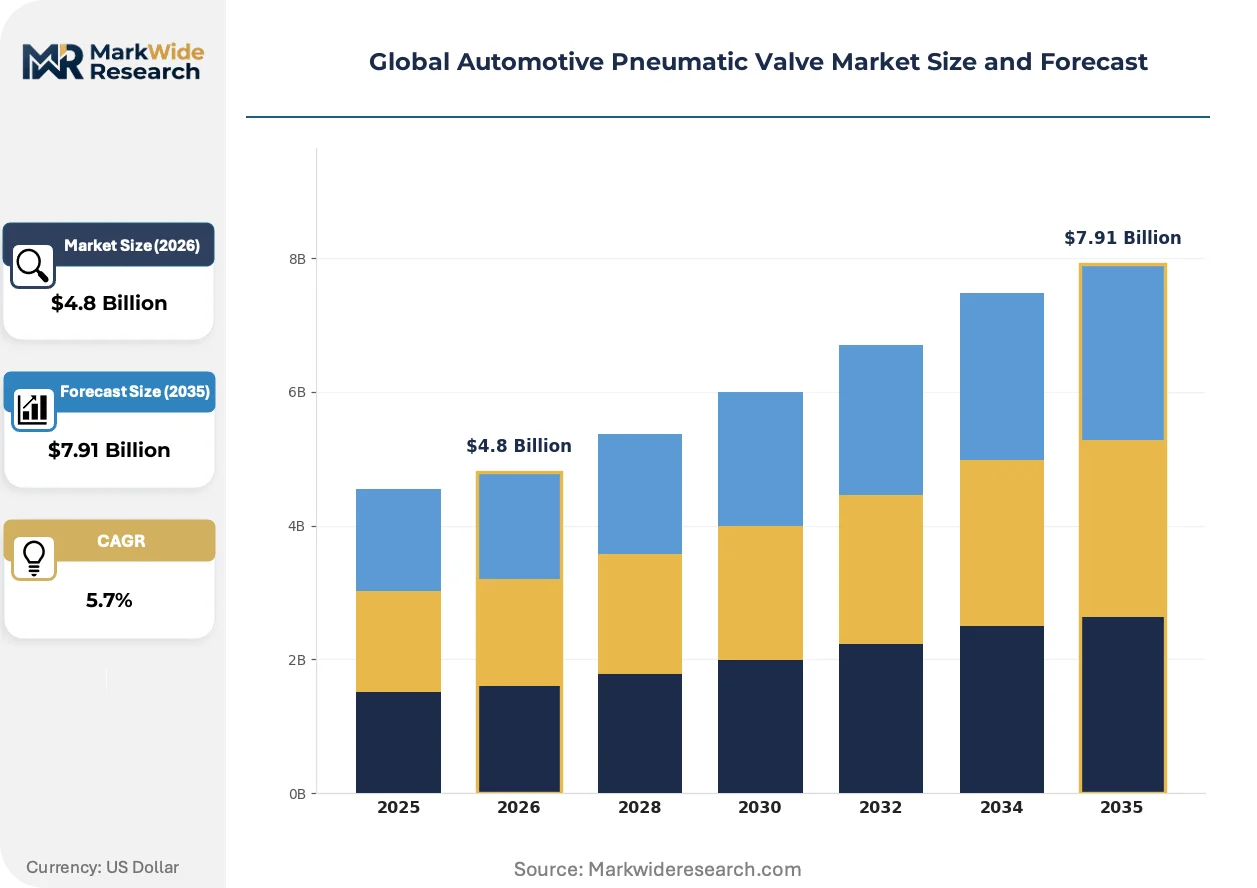
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solenoid Valve, Pressure Relief Valve, Directional Control Valve, Flow Control Valve, Check Valve Technology: Electromechanical, Electro-pneumatic, Direct Acting, Pilot Operated, Composite Materials Application: Commercial Vehicles, Passenger Cars, Two-wheelers, Off-road Vehicles, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Hitachi Ltd., Emerson, Continental AG, SMC Corporation, Parker Hannifin Corporation, Denso Corporation, Delphi Automotive, Festo SE & Co. KG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Pneumatic Valve Market Strategic Shifts & Innovations
The market's trajectory is defined by the integration of digital control with advanced material science. This fusion addresses the twin pressures of improving vehicle efficiency mandated by emissions standards and enabling the sophisticated automation required in next-generation vehicle platforms.
Solenoid valve technology enables rapid, precise airflow control through electronic signals. Commercial vehicle manufacturers are the primary adopters, using them for functions like automated transmission shifting and advanced air brake management. This technology is expanding into new domains such as active chassis control and adaptive suspension systems, areas historically dominated by more complex hydraulic solutions.
Regulations such as the European Union's updated General Safety Regulation (GSR) are a significant influence. The GSR mandates certain advanced driver-assistance systems (ADAS) that rely on rapid vehicle response, such as automated emergency braking. The heavy-duty truck segment is most impacted, as compliance drives the upgrade from basic air brakes to more responsive electro-pneumatic systems capable of integrating with ADAS controllers.
A notable behavioral shift is visible among large commercial fleet operators, who increasingly prioritize total cost of ownership and vehicle uptime over low initial component price. This procurement focus disrupts the market for standard, non-durable valves, creating demand for premium components with integrated diagnostics that can predict failures and reduce maintenance-related downtime. This trend is most advanced in the long-haul logistics sectors of North America and Europe.
Global Automotive Pneumatic Valve Market Segmentation
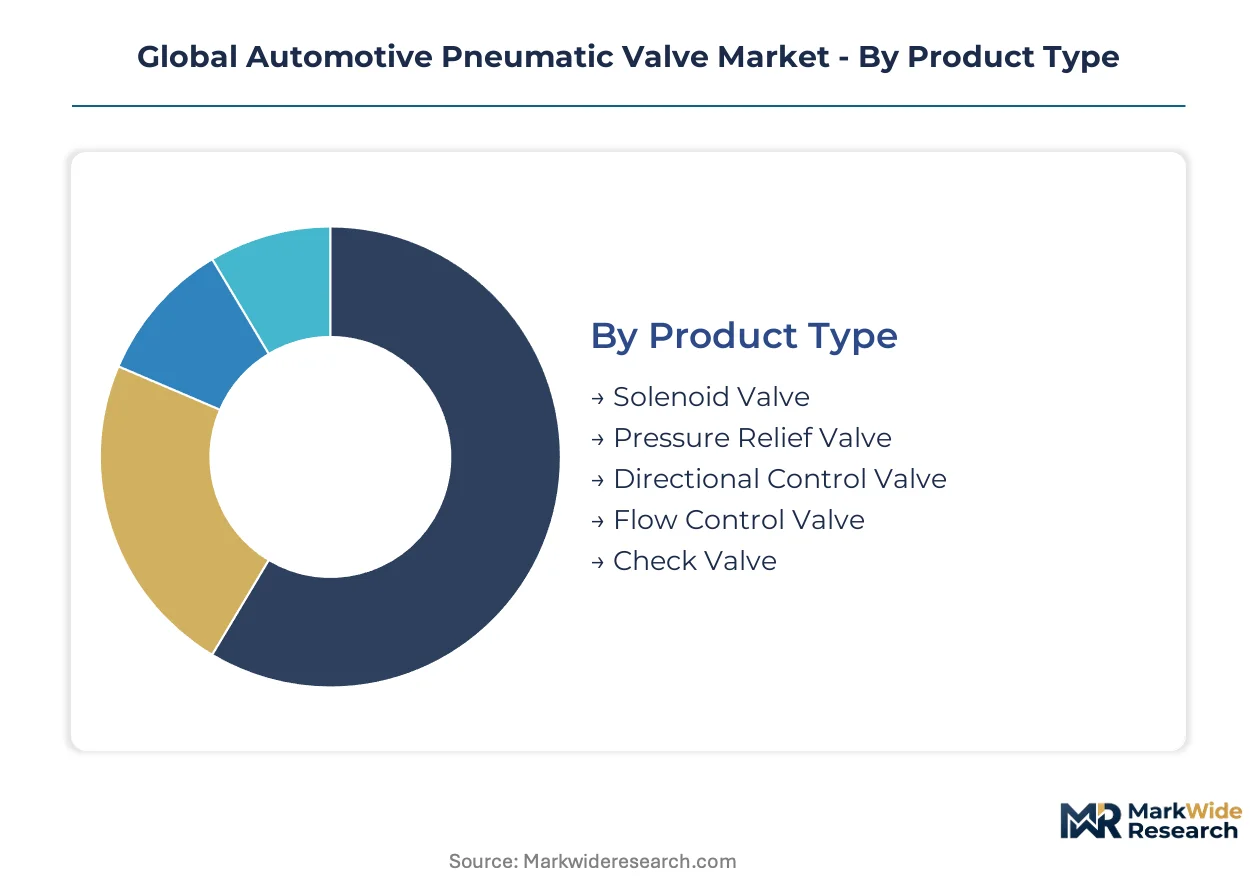
Understanding the market segmentation for automotive pneumatic valves is critical for manufacturers to align product development and market strategies. Distinct requirements across product types, technologies, applications, and end-users shape investment priorities and competitive positioning within the industry.
Product Type:
Manufacturing complexity and capital expenditure vary significantly across pneumatic valve product types, influencing production scale and specialization.
- Solenoid Valve:Electronic control elements actuate these valves, regulating compressed air flow with precision. Demand concentrates in commercial vehicles for advanced air brake and transmission systems, driven by integration with ADAS features.
- Directional Control Valve:These valves manage the path of compressed air to specific actuators, directing system operation. Significant volume is consumed by heavy-duty commercial vehicles for suspension height adjustment and auxiliary functions, requiring robust designs.
- Pressure Relief Valve:These safety components automatically release excess pressure, protecting pneumatic systems from over-pressurization.
- Flow Control Valve:Flow control valves regulate the rate of air movement, enabling precise speed adjustments for pneumatic cylinders.
- Check Valve:Check valves permit air flow in only one direction, preventing backflow and maintaining system pressure.
Solenoid valves absorb the bulk of installed capacity; directional control valves are expanding most quickly.
Technology:
The technology choice for automotive pneumatic valves directly influences manufacturing cost and performance capabilities across vehicle platforms.
- Electro-pneumatic:These advanced systems combine electronic controls with pneumatic actuation for precise, rapid response. Adoption is accelerating in commercial vehicles for integrated ADAS features and enhanced efficiency, driven by stringent emissions regulations.
- Composite Materials:Valve bodies and components manufactured from lightweight composites reduce vehicle mass and improve fuel economy. These materials are gaining traction in electric vehicle architectures and high-performance applications, where weight reduction is critical.
- Electromechanical:Electromechanical technologies utilize electrical signals to activate mechanical valve movements, offering reliable operation.
- Direct Acting:Direct acting valves operate by direct application of force to the sealing element, providing immediate response.
- Pilot Operated:Pilot operated valves use a smaller pilot pressure to control a larger main valve, suitable for higher flow applications.
Electro-pneumatic technology holds a significant share due to its advanced capabilities; composite materials are gaining ground rapidly.
Application:
Vehicle application segments dictate valve volume requirements and operational demands, influencing product durability and performance specifications.
- Commercial Vehicles:Heavy-duty trucks and buses constitute the largest volume consumer, relying on pneumatic valves for critical air brake and suspension systems. Stringent safety mandates from China's GB standards and EU directives drive demand for high-performance, reliable components in this segment.
- Passenger Cars:Pneumatic systems in passenger cars are used for functions like active suspension, adjustable seating, and aerodynamic elements. The shift towards electric vehicles is creating niche opportunities for lightweight pneumatic solutions, displacing some hydraulic applications.
- Off-road Vehicles:Off-road vehicles utilize robust pneumatic valves for heavy-duty braking, differential locks, and specialized equipment control.
- Specialty Vehicles:Specialty vehicles, including municipal and emergency fleets, employ pneumatic valves for auxiliary systems and equipment actuation.
- Two-wheelers:Pneumatic valve applications in two-wheelers are limited but include adjustable suspension and advanced braking systems in premium models.
Commercial vehicles represent the primary demand center for pneumatic valves; passenger cars are showing renewed interest in specific applications.
End User:
The end-user landscape reflects distinct supply chain dynamics and purchasing priorities for automotive pneumatic valve manufacturers.
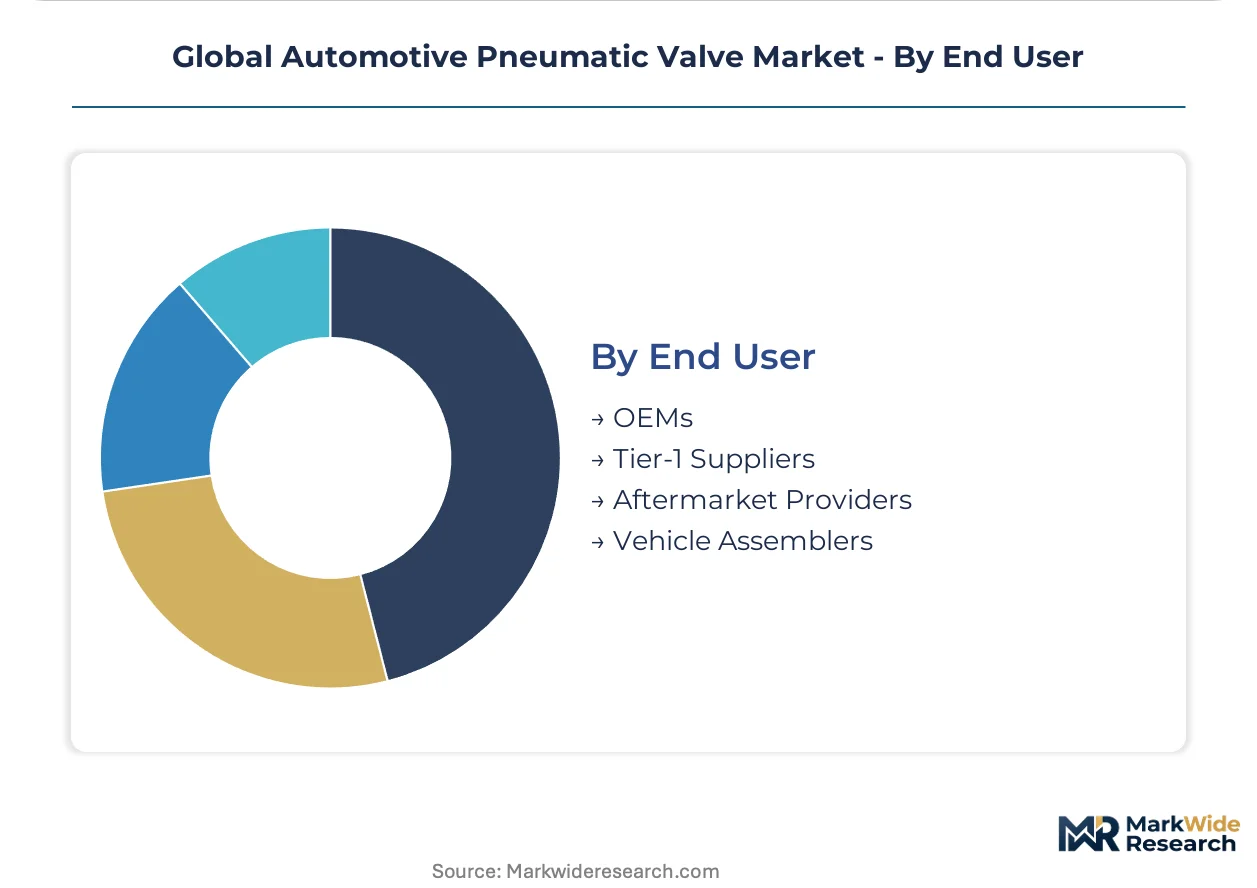
- OEMs:Original Equipment Manufacturers integrate pneumatic valves directly into new vehicle production lines. These customers demand high-volume supply, strict quality control, and collaborative development for next-generation vehicle platforms.
- Aftermarket Providers:Aftermarket providers supply replacement parts for vehicle maintenance and repair, serving an installed base of older vehicles. Demand is strong in developing economies like Brazil and Mexico, where aging commercial vehicle fleets require consistent part availability.
- Tier-1 Suppliers:Tier-1 suppliers procure valves for integration into larger sub-assemblies before delivery to vehicle manufacturers.
- Vehicle Assemblers:Vehicle assemblers incorporate pneumatic valve components during the final stages of vehicle construction.
OEMs drive initial product development and volume; aftermarket providers ensure long-term serviceability and component availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive pneumatic valves is concentrating in key manufacturing hubs globally, driven by stringent regulatory frameworks and the increasing complexity of vehicle systems. This market expansion reflects both the commercial vehicle segment's robust requirements and the evolving needs of passenger car applications.
China
China's massive vehicle production and export base drive substantial demand for pneumatic valves, particularly in the commercial vehicle segment. The country's GB standards for commercial vehicle safety directly mandate advanced air brake systems. Manufacturing clusters in the Yangtze River Delta actively integrate electro-pneumatic technologies into heavy-duty truck platforms.
Germany
German automotive manufacturers require high-performance pneumatic valves for advanced chassis control and ADAS integration in premium vehicles. EU directives on vehicle emissions and safety standards influence valve design and material choices. Engineering centers in Bavaria and Baden-Württemberg focus on developing miniaturized and smart valve solutions.
United States
United States commercial vehicle operators prioritize reliable air brake and suspension systems, creating consistent demand for pneumatic components. The US EPA regulations for heavy-duty vehicle emissions also push for more efficient pneumatic system designs. Automotive manufacturing regions like Michigan are seeing investments in advanced electro-pneumatic assembly lines.
India
India's expanding commercial vehicle market and growing domestic automotive production contribute to the sustained demand for pneumatic valves. The country's safety regulations for heavy vehicles mandate robust braking and suspension components. Manufacturing clusters around Chennai and Pune are expanding their capacity for localized valve production.
Global Automotive Pneumatic Valve Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting a tiered market structure. The market exhibits consolidation at the high-end technology segment, while standard components see greater fragmentation. Key strategic archetypes include integrated system providers, component specialists, and regional aftermarket suppliers. Dominant competitive moves involve strategic partnerships for technology co-development and targeted capacity expansions.
Among established industrial technology firms, Robert Bosch GmbH exemplifies a broad portfolio approach, leveraging its extensive electronics expertise to integrate smart controls into pneumatic valve offerings, catering to diverse automotive needs. Continental AG occupies a position as an integrated chassis and safety system provider, delivering comprehensive solutions for major automotive OEMs globally. SMC Corporation represents a specialist in miniaturized and high-flow solenoid valves, crucial for complex automated systems and advanced vehicle architectures where precision and rapid actuation are paramount.
| Leading Market Players |
|---|
| Hitachi Ltd. |
| Emerson |
| Continental AG |
| SMC Corporation |
| Parker Hannifin Corporation |
| Denso Corporation |
| Delphi Automotive |
| Festo SE & Co. KG |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Vertical integration by major automotive OEMs into component manufacturing anchors their supply position and influences pricing power across the pneumatic valve market. This strategy ensures control over quality and cost for critical vehicle systems.
Pricing Analysis
Volume-driven segments prioritize cost-efficiency, while high-performance applications command premium margins. Pricing is largely transactional, with long-term contracts for OEMs. Price differentiation stems from quality grade (ISO/SAE certifications) and customization level for specific vehicle architectures. Pricing softness runs through standard components due to intense competition. Commercial vehicle operators are highly price-sensitive for aftermarket parts, while premium passenger car OEMs prioritize performance over initial cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized material suppliers for lightweight composites, particularly those in China and Germany. The supply chain draws from raw materials like specialized polymers and various metals for valve bodies and internal components. Logistics chokepoints, particularly in global shipping lanes, present a significant structural risk. Distribution runs through a dual model: direct to OEMs and through a network of Tier-1 suppliers and aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive pneumatic valve market is in a technology-transition phase, as electro-pneumatic systems increasingly replace purely mechanical alternatives. This shift is driven by demands for enhanced efficiency and control in modern vehicles.
For Market Incumbents: Deploy strategic partnerships with ADAS developers to integrate pneumatic systems seamlessly into advanced vehicle architectures. This counters the threat from competing hydraulic systems in passenger cars and addresses technical integration hurdles in EVs. Invest in R&D for miniaturized and smart valve solutions to maintain a competitive edge. Focus on achieving ISO/SAE 21434 cybersecurity compliance for connected valve components.
For New Entrants and Emerging Players: Begin with targeting niche applications like active aerodynamic systems in performance and electric vehicles, where specialized, fast-acting pneumatic valves are needed. Focus on developing high-margin, specialized electro-pneumatic technologies for next-generation vehicle architectures. A go-to-market angle could involve offering integrated sensor capabilities for predictive maintenance, appealing to fleet operators prioritizing uptime. This strategy avoids direct competition with established players in high-volume standard components.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized component manufacturers with strong IP in electro-pneumatic and composite material technologies. The long-term viability of this market (5-10 year window) hinges on the continued electrification of vehicles and stringent safety regulations. Acquisition targets should be firms innovating in smart valve development with integrated sensors and microcontrollers. The signal to watch is the increasing standardization of electro-pneumatic interfaces across major OEM platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Electro-Pneumatic Integration | Accelerates adoption of advanced ADAS features in commercial vehicles. |
| Lightweight Composite Material Development | Reduces vehicle mass, enhancing EV range and ICE fuel economy. |
| Cybersecurity Standard Compliance (ISO/SAE 21434) | Mitigates risks for connected valve components in vehicle networks. |
| Localized Production Capacity in Asia | Addresses growing demand and regulatory mandates in China and India. |
| Smart Valve Sensor Integration | Enables predictive maintenance, improving vehicle uptime for fleet operators. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic publications underwrites the qualitative findings and quantitative projections. This analysis combines primary interviews with automotive OEM platform engineers, Tier-1 supplier procurement leads, and aftermarket distributors. Secondary data sources include vehicle production databases, commercial vehicle safety standards (GB, EU directives), and material science journals. Bottom-up and top-down triangulation validated market sizing and growth rates.
Rate-of-change decomposition modeled market evolution across the analysis window by segmenting demand by product type, technology, application, and end-user. Compound annual growth rates were derived from historical trends, regulatory impacts, and technological adoption curves. Key forecast inputs included vehicle electrification rates and commercial vehicle production volumes. This framework projected market value and volume over the projection horizon.
Geopolitical instability, raw material price volatility, and unforeseen technological disruptions are the dominant revision risks to these forecasts. Projections reflect assumptions regarding regulatory enforcement and vehicle production schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Spark Plug Market