
 Automotive Braking Component Market | 2026-2036
Automotive Braking Component Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Braking Component Market Intelligence
The increasing share of commercial vehicles and electric passenger vehicles in the overall automotive sales mix is rebalancing demand for specific braking component types. Robert Bosch GmbH leverages its extensive electronics portfolio to lead in integrated brake control systems for these emerging applications. Meanwhile, Brembo S.p.A. specializes in high-performance disc brakes for luxury and sports vehicle segments. Continental AG competes through its development of advanced sensor-based braking technologies for autonomous driving functions.
Automotive braking components are mechanical and electronic devices designed to decelerate or stop a vehicle by converting kinetic energy into thermal energy through friction. Key components include brake rotors, often made of grey iron or ceramic composites, and brake pads formulated with specific friction materials to ensure consistent performance under high temperatures. Within technology, regenerative braking systems are seeing rapid adoption in electric and hybrid vehicles, while hydraulic braking remains the standard for the conventional vehicle parc. Disc brakes continue displacing drum brakes in most passenger vehicle applications due to superior heat dissipation.
Safety and performance standards set by regulators like the US National Highway Traffic Safety Administration (NHTSA) and Germany's Kraftfahrt-Bundesamt (KBA) mandate stringent testing protocols. In parallel, environmental regulations from the European Chemicals Agency (ECHA) and China's Ministry of Ecology and Environment (MEE) are restricting the use of copper and other heavy metals in brake pad formulations. Component manufacturers must now navigate a dual challenge of meeting higher performance benchmarks while adhering to an evolving list of material restrictions.
Market Dynamics
The rapid electrification of passenger vehicles, coupled with stringent environmental regulations on material composition, is the central force reconfiguring the automotive braking component market. This dual pressure accelerates innovation in both electronic control systems and friction material science.
Growth Catalysts
- Regenerative Braking Integration:The proliferation of electric and hybrid vehicles necessitates the integration of regenerative systems, creating demand for compatible hydraulic components and advanced electronic brake-by-wire controls.
- Vehicle Safety Mandates:Increasingly stringent vehicle safety standards, such as those requiring advanced driver-assistance systems (ADAS), drive adoption of sophisticated braking components like sensor-integrated calipers and electronic stability control units.
- EV Production in China:Government mandates and consumer demand in China's expansive electric vehicle sector create a concentrated, high-volume market for specialized braking systems designed for EV weight and performance characteristics.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of key inputs like grey iron, aluminum, and specialized resins for composite materials create margin pressure and complicate long-term cost planning for component manufacturers.
- Environmental Material Restrictions:Regulations from bodies like the ECHA and US state laws phasing out copper in brake pads force costly and time-consuming reformulation and validation cycles to find effective, compliant alternatives.
- Integration with Legacy Systems:The large global parc of conventional vehicles with hydraulic braking systems limits the immediate addressable market for purely electronic brake-by-wire systems, slowing their economies of scale.
Strategic Opportunities
- EV Aftermarket Components:Developing a dedicated portfolio of aftermarket brake pads and rotors optimized for the unique wear patterns of electric vehicles with regenerative braking presents a significant growth channel.
- Sensor-Infused Components:Embedding sensors directly into brake pads and calipers to monitor wear, temperature, and performance data creates opportunities for predictive maintenance services and enhanced autonomous driving functions.
- Manufacturing in Southeast Asia:Establishing production or supply partnerships in emerging automotive hubs like Vietnam and Indonesia offers access to growing local demand and potential cost advantages for regional supply chains.
Industry Challenges
- Dual Compliance Burden:Manufacturers face the complex challenge of simultaneously meeting stricter performance benchmarks from regulators like the NHTSA while adhering to evolving material restrictions from agencies like China's MEE.
- High R&D Investment:The shift away from copper and other traditional materials requires substantial capital expenditure in material science research and testing infrastructure to validate new friction formulations without compromising safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Braking Component Market |
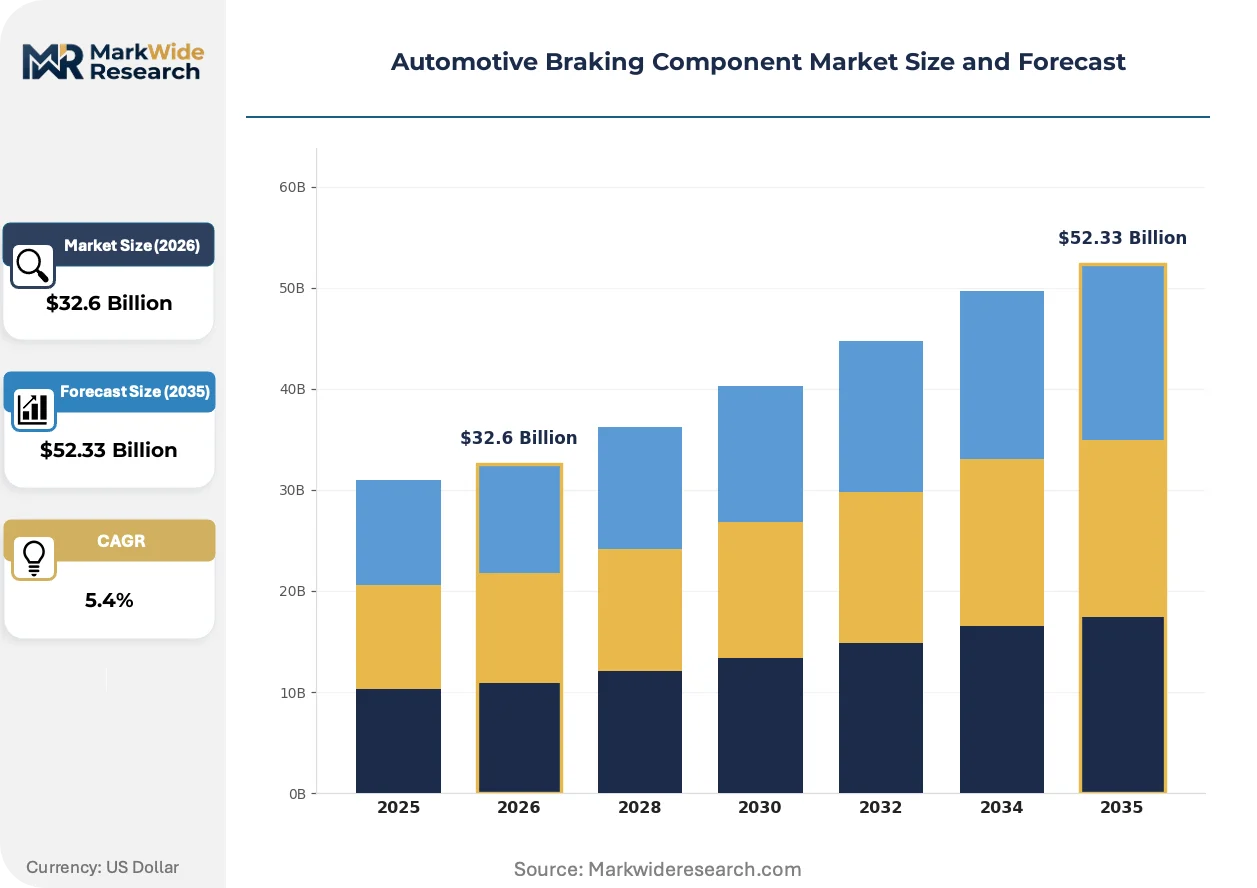
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $52.33 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Brake Pads, Brake Shoes, Brake Rotors Technology: Anti-lock Braking System, Electronic Brakeforce Distribution, Hydraulic Braking, Regenerative Braking, Pneumatic Braking Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Off-road Vehicles, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Rebuilders, Automotive Workshops |
| Companies Covered | Robert Bosch GmbH, Continental AG, Aisin Seiki Co., Ltd., ZF Friedrichshafen AG, Brembo S.p.A., Akebono Brake Industry Co., Ltd., Hitachi Astemo, Ltd., Knorr-Bremse AG, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Braking Component Market Strategic Shifts & Innovations
The convergence of electronics and material science is defining the next generation of braking systems. This evolution prioritizes software-enabled performance and environmental compliance, moving beyond purely mechanical friction.
Brake-by-wire systems replace mechanical and hydraulic linkages with electronic controls, actuators, and sensors. Electric vehicle platforms are rapidly adopting this technology to seamlessly blend regenerative and friction braking. This shift is modularizing the braking system, decoupling the pedal input from the caliper actuation and allowing for software-defined braking profiles.
European Chemicals Agency (ECHA) regulations under the REACH framework are progressively restricting the use of certain heavy metals and hazardous substances in friction materials. This forces a complete supply chain reassessment for brake pad manufacturers supplying the European market. The passenger car segment, particularly for new vehicle type-approvals, is most directly impacted.
A demand-side shift toward application-specific aftermarket components is disrupting the traditional one-size-fits-all replacement model. Independent service centers and vehicle owners are increasingly sourcing pads and rotors designed for specific use cases, such as towing, track use, or EV-specific formulations. This trend is most pronounced in the North American and European performance and light truck segments.
Automotive Braking Component Market Segmentation
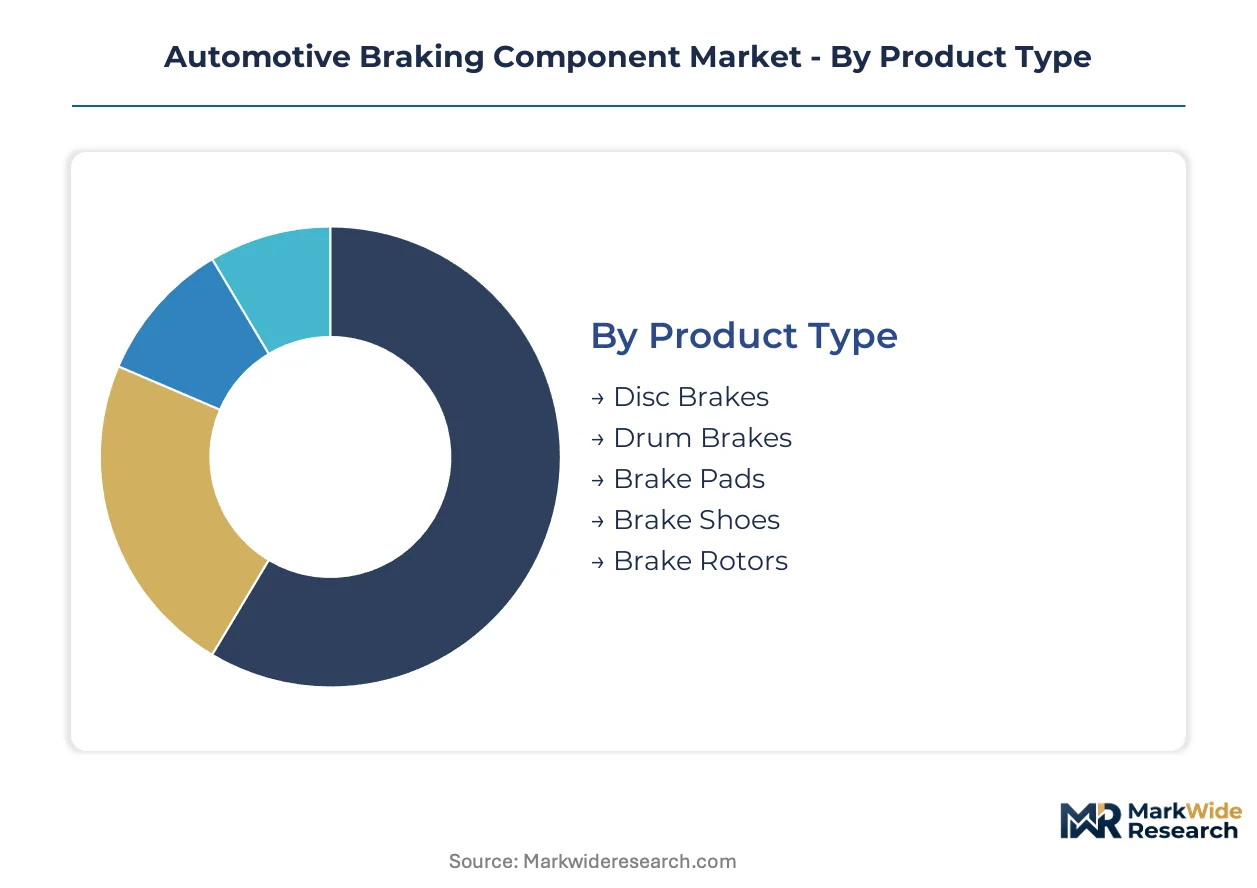
The automotive braking component market is undergoing significant transformation, driven by vehicle electrification and evolving safety standards. Understanding segmentation reveals distinct demands placed on component manufacturers across product types, technologies, applications, and end-user groups.
Product Type:
Supply concentration in braking components is shifting as new vehicle architectures and regulatory pressures influence material selection and manufacturing. These changes are evident across core friction and deceleration elements.
- Disc Brakes:These systems utilize calipers to squeeze pads against a rotating disc, converting kinetic energy into heat. Demand concentrates in passenger vehicles due to superior heat dissipation and consistent performance.
- Brake Pads:Comprising friction material bonded to a metal backing plate, pads are critical for transferring clamping force to the rotor. Demand for advanced formulations is increasing in electric vehicles to minimize wear and meet ECHA restrictions.
- Drum Brakes:Enclosed systems where shoes press against the inside of a rotating drum, often found on rear axles of economy cars.
- Brake Shoes:Curved components lined with friction material, creating friction against the inner surface of a drum brake.
- Brake Rotors:Circular metal discs, typically grey iron or composites, that rotate with the wheel and are clamped by brake pads.
Disc brakes absorb the bulk of installed capacity; brake pads are expanding most quickly.
Technology:
The application of advanced technologies is redefining vehicle safety and performance, with electronic systems increasingly complementing or replacing traditional mechanical linkages. This shift is pronounced in braking integration with vehicle control systems.
- Regenerative Braking:This technology captures kinetic energy during deceleration, converting it into electrical energy for battery recharging in electric and hybrid vehicles. Integration drives demand for electronic brake-by-wire controls, especially in China's EV market.
- Anti-lock Braking System:ABS prevents wheel lock-up during braking, maintaining steering control and reducing stopping distances. NHTSA safety mandates ensure its universal adoption across new passenger vehicles.
- Electronic Brakeforce Distribution:EBD optimizes brake force between front and rear wheels, preventing rear-wheel lock-up and improving stability.
- Hydraulic Braking:Standard system using fluid pressure to transmit force from pedal to calipers or wheel cylinders in conventional vehicles.
- Pneumatic Braking:Systems utilizing compressed air to actuate brakes, primarily found in heavy commercial vehicles due to robust stopping power.
The proliferation of regenerative braking technology is redefining performance benchmarks, while anti-lock braking systems remain essential for safety.
Application:
Demand for braking components varies significantly across different vehicle applications
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suzhou Industrial Park in China, a hub for advanced manufacturing, drives significant demand for automotive braking components, particularly for electric vehicle platforms. This concentration accelerates technological advancement and material science innovation across the industry. Different regions exhibit unique demand patterns influenced by local automotive production, regulatory frameworks, and consumer preferences.
China
Demand for advanced braking components in China stems from its expansive electric vehicle production and stringent EV mandates. The Ministry of Ecology and Environment (MEE) regulations on material composition influence brake pad formulations. Major automotive clusters in Shanghai and Guangzhou are actively integrating brake-by-wire systems into new EV models.
Germany
German automotive manufacturers propel demand for sophisticated braking systems, especially those integrated with advanced driver-assistance systems. Germany's Kraftfahrt-Bundesamt (KBA) sets rigorous safety standards for vehicle braking performance. The Stuttgart region, home to major automotive OEMs, focuses on developing next-generation sensor-integrated calipers.
United States
The United States market exhibits strong demand for robust braking components in light trucks and SUVs, alongside a growing need for EV-specific solutions. The US National Highway Traffic Safety Administration (NHTSA) mandates universal adoption of anti-lock braking systems and electronic stability control. Automotive manufacturing in the Detroit metropolitan area drives innovation in friction material science.
Japan
Japanese automotive companies prioritize lightweight and durable braking components for their extensive hybrid and electric vehicle fleets. Japan's Ministry of Economy, Trade and Industry (METI) promotes sustainable manufacturing practices, influencing material selection. The Toyota City region remains a center for brake system research and development for global vehicle platforms.
India
India's automotive sector generates substantial demand for cost-effective yet reliable braking components, driven by increasing passenger vehicle sales. The Bureau of Indian Standards (BIS) sets national quality and safety benchmarks for automotive parts. Chennai, a prominent automotive manufacturing hub, focuses on high-volume production of conventional and disc braking systems.
Automotive Braking Component Market Key Industry Players
Top-tier vendors anchor the integrated systems segment, while specialized component manufacturers address niche applications and performance requirements. The market structure is tiered, with global conglomerates offering comprehensive solutions and smaller firms focusing on specific material science or component types. Strategic partnerships for technology co-development and targeted geographic expansion are dominant competitive moves.
Integrated system providers like Robert Bosch GmbH and Continental AG represent a segment focused on comprehensive electronic braking solutions, leveraging their extensive electronics portfolios. Brembo S.p.A. exemplifies the high-performance component archetype, specializing in advanced disc braking systems for luxury and sports vehicle segments. These companies anchor innovation in both software-defined braking and friction material advancements, responding to evolving regulatory and performance demands.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Aisin Seiki Co., Ltd. |
| ZF Friedrichshafen AG |
| Brembo S.p.A. |
| Akebono Brake Industry Co., Ltd. |
| Hitachi Astemo, Ltd. |
| Knorr-Bremse AG |
| Schaeffler AG |
| Others |
Cost & Logistics Intelligence
The divergence between high-performance, sensor-integrated braking systems and conventional hydraulic components creates distinct pricing and supply chain configurations. This bifurcation reflects varying material costs and manufacturing complexity across the market.
Pricing Analysis
Premium pricing for short lead times characterizes advanced braking components, while standard parts often see discounts for spot inventory. The dominant pricing model is per-unit transactional, with long-term contracts for major OEMs. Price differentiation stems from quality grade, specific regulatory certifications like NHTSA standards, and volume scale. Pricing pressure stems from raw material price volatility, particularly for grey iron and aluminum. Economy vehicle manufacturers exhibit the highest price sensitivity, whereas luxury EV brands prioritize performance over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns facilitate the timely delivery of braking components to global automotive manufacturing sites. Supply concentration for these components is notable in China, Germany, and Japan. The industry draws from key inputs like grey iron for rotors, ceramic composites for pads, and sophisticated electronic control units. Raw material price volatility presents a structural risk, impacting cost planning. The dominant distribution model involves direct supply to original equipment manufacturers and a separate channel for aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive braking component market is a consolidation play, as stringent environmental material restrictions force smaller manufacturers to exit due to high R&D investment requirements. This environment favors larger, integrated system providers with robust material science capabilities.
For Market Incumbents: Anticipate continued pressure from emerging sensor-integrated component specialists by deepening vertical integration into advanced material R&D for compliant friction formulations. Form strategic partnerships to develop software-defined braking profiles, protecting market share in the rapidly electrifying vehicle segment. Leverage existing manufacturing footprints to add capacity in China, securing a stronger position in the EV supply chain. This proactive approach mitigates the threat of new entrants focusing solely on electronic systems.
For New Entrants and Emerging Players: Independent service centers and specialized online retailers represent key channel partners for market entry. Target the growing white space in EV aftermarket components, focusing on pads and rotors optimized for regenerative braking wear patterns. Develop sensor-infused predictive maintenance solutions for commercial fleets, offering enhanced data capabilities. The most penetrable segment is the performance EV aftermarket in North America, accessible through direct-to-consumer online platforms.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized material science firms or electronic control system developers, offering significant growth potential over the next decade. The market remains viable due to continuous innovation driven by safety and environmental mandates. Target companies with proprietary friction material formulations or advanced brake-by-wire intellectual property. Increased M&A activity among Tier 1 suppliers, particularly for smaller tech-focused firms, signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Regenerative Braking R&D | Positions firms for leadership in the rapidly expanding electric vehicle market segments. |
| Develop Copper-Free Friction Materials | Ensures compliance with ECHA and MEE regulations, maintaining access to key European and Chinese markets. |
| Expand Sensor Integration in Calipers | Supports the evolution of autonomous driving features and predictive maintenance services in advanced vehicles. |
| Establish EV Aftermarket Portfolio | Captures new revenue streams from electric vehicles, addressing unique wear patterns. |
| Form Software Co-development Partnerships | Accelerates the transition to software-defined braking systems, enhancing system modularity. |
Research Approach
Document review covered NHTSA safety reports, ECHA regulatory documents, vehicle production databases, and automotive industry association publications, complemented by interviews with industry stakeholders. Primary interviews included OEM procurement officers, brake system engineers, friction material scientists, and aftermarket distributors. This approach enabled bottom-up data collection and top-down market validation. Data triangulation ensured robust market sizing and trend analysis.
The quantitative model produced volume and value forecasts across the analysis window, integrating various segmentation dimensions. These dimensions included product type, technology, application, vehicle class, and regional production cluster. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key industry-specific forecast inputs included electric vehicle production forecasts and regulatory compliance timelines for material restrictions.
Caveats apply where geopolitical trade tensions or rapid shifts in EV battery technology could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
Automobile Accessories Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
China Automotive Composites Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Automotive Silicone Elastomer Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
United States Automotive Pneumatic Actuators Market