
 Global Automotive Plastic Compounding Market | 2026-2036
Global Automotive Plastic Compounding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Plastic Compounding Market Analysis
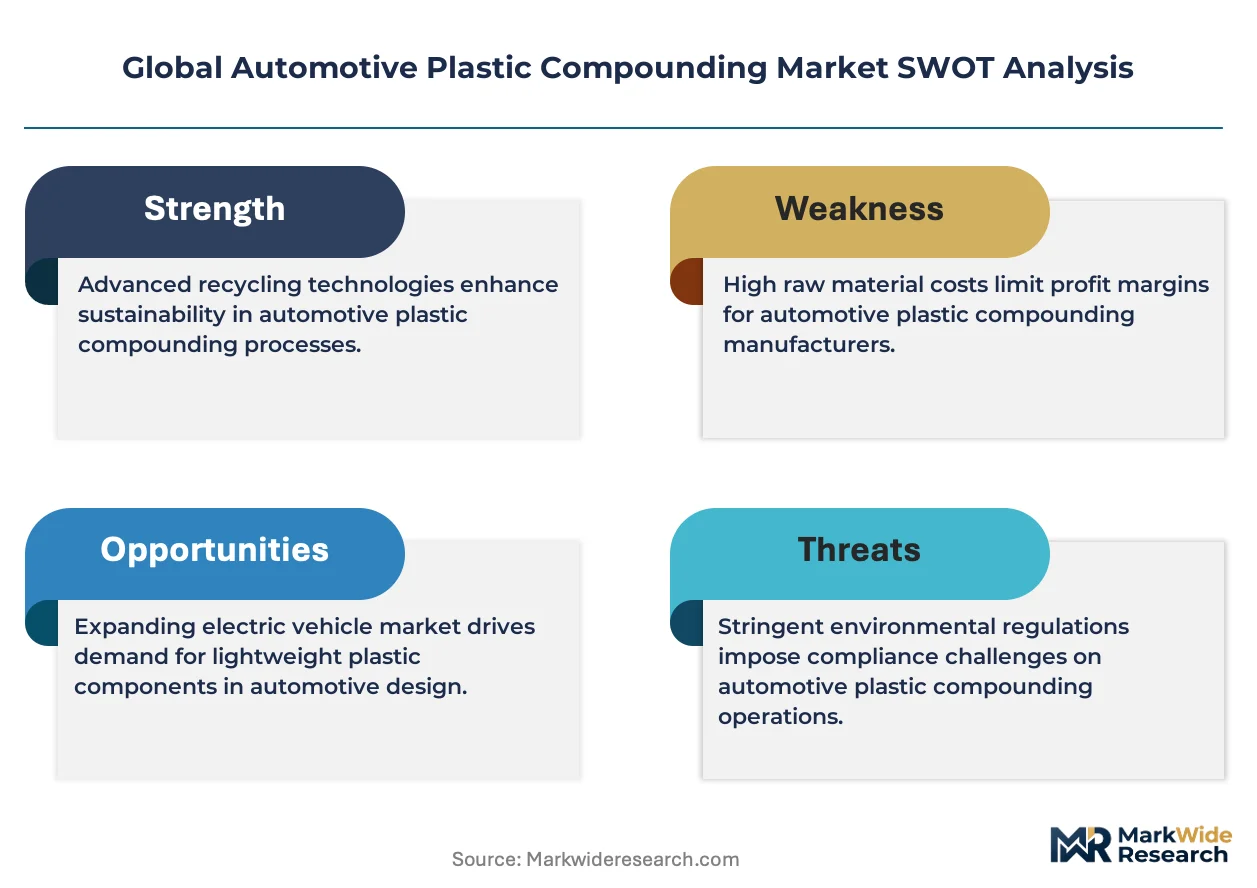
Aftermarket recycling and closed-loop recompounding is rewriting margin distribution across the value chain. BASF SE leverages its integrated Verbund sites in Ludwigshafen to control feedstock quality for automotive grades. SABIC sustains technology leadership in long-glass-fiber polypropylene through dedicated compounding lines in the Netherlands and Saudi Arabia. Covestro AG differentiates via polycarbonate blends optimized for headlamp bezels and panoramic roof modules.
Automotive plastic compounding refers to the melt-blending of base resins with additives, reinforcements, and stabilizers to achieve specified mechanical, thermal, and aesthetic properties for vehicle applications. Typical compounds incorporate glass fiber loadings of 10-40% by weight, mineral fillers, UV stabilizers, and flame retardants to meet OEM performance criteria for under-hood temperatures exceeding 150°C. Polypropylene dominates volume due to its cost position and recyclability in bumper fascias and interior trim, while polycarbonate commands premium positioning in transparent and semi-structural glazing applications. Injection molding remains the primary conversion technology, though extrusion compounding of continuous fiber-reinforced tapes is gaining share in structural battery tray applications.
EPA tailpipe emissions rules and the EU F-Gas Regulation are restricting traditional refrigerants and thermal management fluids, forcing compounders to develop hydrolysis-resistant nylon grades for new heat pump architectures. China's MIIT new-energy vehicle mandates and GB standards for recyclability are reshaping material specifications for domestic OEM supply chains. NHTSA crashworthiness protocols continue to drive high-impact ABS and PC-ABS formulations for pedestrian safety systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compound qualification redundancies that inflate development costs.
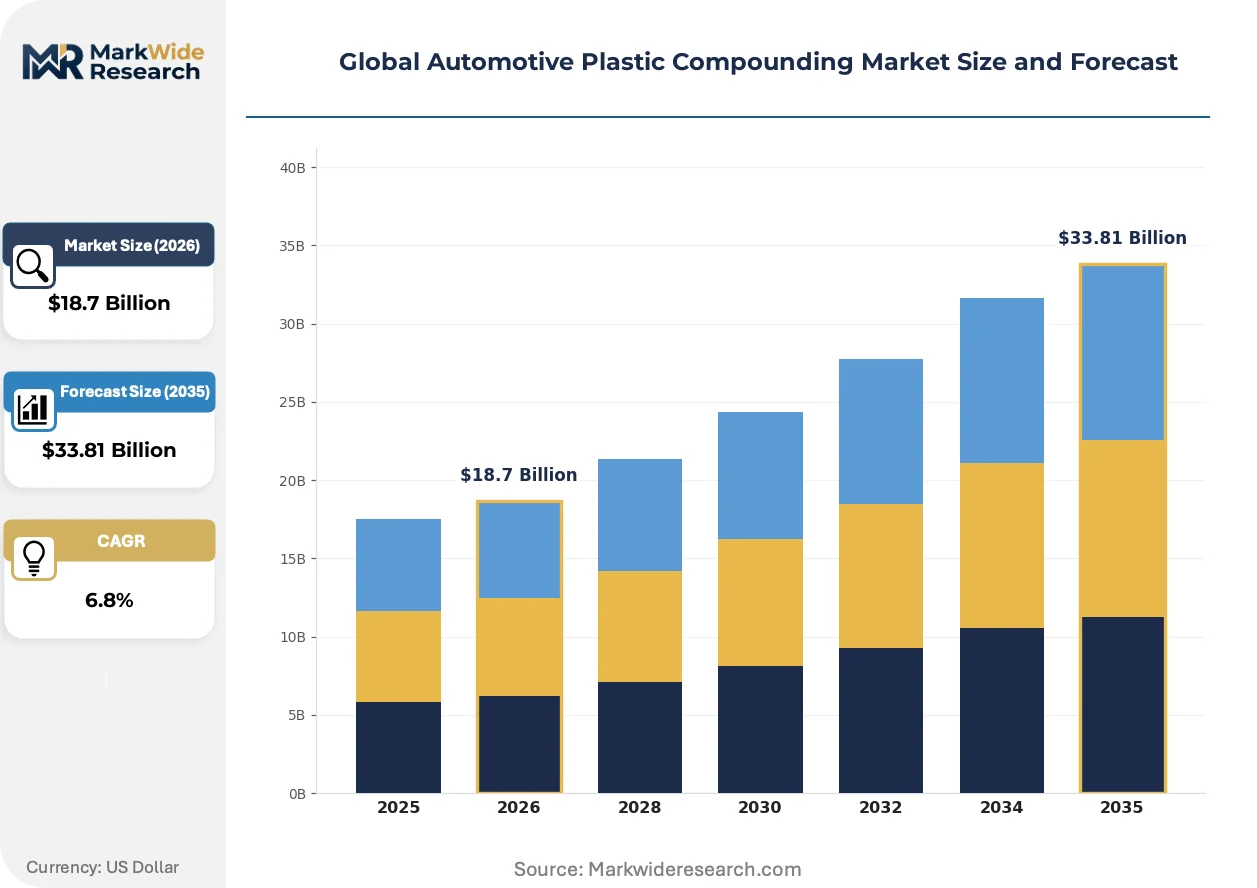
Market Dynamics
Electric vehicle thermal management architectures are forcing compounders to develop hydrolysis-resistant nylon grades capable of withstanding glycol-based coolant exposure at 150°C continuous operating temperatures. This technical pivot is redrawing qualification timelines and capital allocation across the supplier base.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on traditional refrigerants accelerate demand for heat-pump-compatible polymer compounds in battery thermal management systems.
- Glass-reinforced polypropylene:OEMs specify long-fiber compounds for lightweighting structural battery trays without sacrificing crashworthiness.
- China MIIT mandates:Domestic new-energy vehicle production quotas drive localized compounding capacity expansion near assembly plants in Jiangsu and Guangdong provinces.
Market Restraints
- Propylene feedstock volatility:Crude oil price swings and refinery output constraints compress margins for polypropylene-dominant compounders.
- Specialty additive concentration:Flame retardant and UV stabilizer supply concentrates among German and Japanese chemical suppliers, creating single-source vulnerability.
- Metal substitution ceiling:Structural load-bearing applications in chassis components resist polymer conversion due to fatigue performance gaps under cyclic torsional loading.
Strategic Opportunities
- India PLI scheme:Automotive component manufacturing incentives attract compounding joint ventures to serve Maruti Suzuki and Tata Motors electrification programs.
- Continuous fiber-reinforced tapes:Extrusion-compounded unidirectional tapes enable automated fiber placement in battery enclosure sidewalls, displacing stamped aluminum.
- Closed-loop recompounding:Post-industrial scrap recovery partnerships with Tier-1 injection molders create captive feedstock pools and Scope 3 emissions reductions.
Industry Challenges
- Color-matching certification:OEM aesthetic specifications require batch-to-batch delta-E tolerances below 0.5, demanding spectrophotometry investment and skilled formulation chemists.
- Multi-jurisdiction qualification redundancy:Separate EPA, REACH, and GB standard testing protocols inflate development costs for global platform programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Plastic Compounding Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polycarbonate, ABS, Nylon Application: Interior Components, Exterior Parts, Electrical Systems, Fuel Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Extrusion, Injection Molding, Blow Molding, Thermoforming |
| Companies Covered | BASF SE, SABIC, LyondellBasell Industries Holdings B.V., Covestro AG, Dow, DuPont de Nemours, Inc., Ascend Performance Materials, Ravago, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Plastic Compounding Market Emerging Trajectories
Material science convergence with electrification architectures is compressing traditional automotive polymer qualification cycles. Compounders now co-develop grades with battery pack engineers rather than responding to finished specifications.
Continuous fiber-reinforced thermoplastic composites are rendering obsolete stamped aluminum battery tray assemblies. BMW and Hyundai-Kia engineers specify unidirectional glass-polypropylene tapes for structural sidewalls. This substitution eliminates welding operations and enables integrated thermal runaway containment channels.
REACH authorization requirements for flame retardant chemistries are forcing reformulation of under-hood nylon compounds. Decabromodiphenyl ether restrictions under SVHC listings push compounders toward phosphinate-based alternatives. German KBA type-approval processes now demand extended hydrolysis resistance testing for heat pump applications.
Platform engineering teams now specify recycled-content minimums in RFQ documents rather than treating sustainability as a secondary attribute. Volvo Cars mandates 25% post-consumer recycled plastic across interior applications by 2025. This procurement pattern shift forces compounders to secure ISCC PLUS certification and auditable mass-balance documentation.
Global Automotive Plastic Compounding Market Segmentation
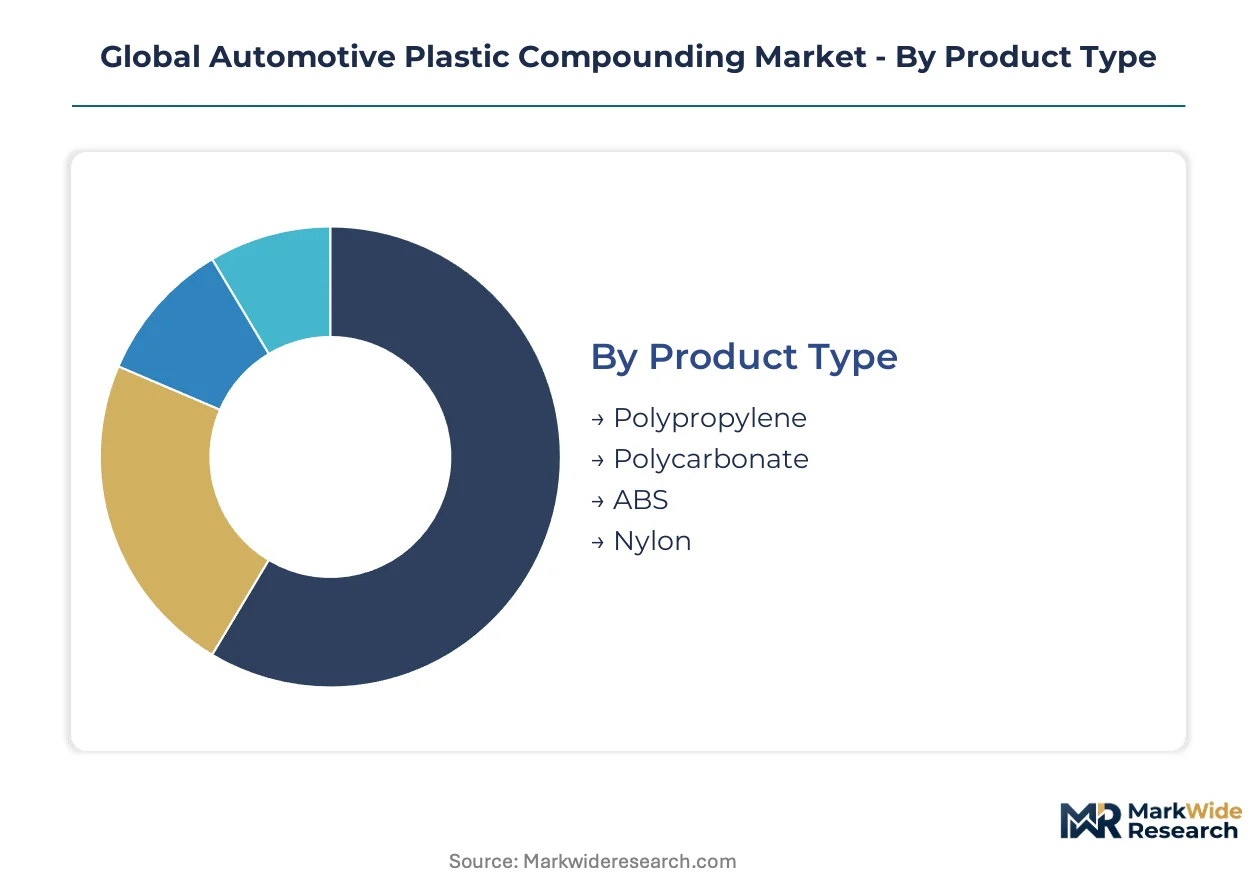
Automotive plastic compounding demand fragments across material chemistry, manufacturing process, and supply chain position. Each segmentation dimension carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Cost tier determines volume concentration and margin capture across base resin categories.
- Polypropylene:Glass-reinforced and mineral-filled grades dominate bumper fascias, instrument panels, and door panels due to density advantages and established recycling infrastructure. German and Chinese OEMs specify long-fiber compounds for structural battery tray applications where fatigue resistance competes with aluminum.
- Polycarbonate:Transparent and semi-structural blends command premium positioning in headlamp bezels, panoramic roof modules, and display housings. Covestro AG maintains technology leadership through specialized compounding lines optimized for optical clarity and UV stability.
- ABS:High-impact formulations serve pedestrian safety systems and interior trim where surface aesthetics and crashworthiness converge. NHTSA protocols drive specification density in US platform programs.
- Nylon:Hydrolysis-resistant grades withstand glycol-based coolant exposure in heat pump architectures, though REACH flame retardant restrictions force continuous reformulation cycles.
Polypropylene holds installed capacity. Nylon is rotating up the share rankings.
Application:
Functional requirements across vehicle zones dictate additive packages and reinforcement loadings.
- Interior Components:Dashboard carriers, door panels, and seating structures utilize talc-filled polypropylene and ABS blends for haptic quality and VOC compliance. Volvo Cars mandates recycled-content minimums across this category, forcing ISCC PLUS certification upstream.
- Exterior Parts:Bumper fascias, body panels, and glazing frames specify UV-stabilized compounds with Class A surface finish capability. Long-glass-fiber polypropylene from SABIC's Netherlands lines displaces sheet molding compound in fender applications.
- Electrical Systems:Connector housings and high-voltage insulation demand flame-retardant nylon and PBT grades meeting IEC standards for electric vehicle architectures.
- Fuel Systems:Barrier-layer coextrusion compounds for conventional powertrains face demand pressure as electrification accelerates, though hybrid applications sustain niche volumes.
Interior Components anchor current formulation volumes. Electrical Systems are climbing the fastest as high-voltage architectures proliferate.
End User:
Customer type determines proximity requirements, inventory models, and technical service intensity.
- OEMs:Integrated compounding partnerships near assembly plants in Germany, China, and the United States enable just-in-sequence delivery and color-matching certification with delta-E tolerances below 0.5.
- Tier-1 Suppliers:Injection molders source certified compounds for dashboard modules, lighting systems, and thermal management components, with closed-loop recompounding partnerships creating captive feedstock pools.
- Aftermarket Providers:Collision repair and replacement part distributors specify color-matched compounds for bumper and trim restoration, though batch sizes fragment logistics economics.
- Dealerships:Service channel demand concentrates in cosmetic trim replacement with limited technical specification requirements.
OEMs hold specification authority. Tier-1 Suppliers are gaining share fastest through vertical integration into compounding assets.
Technology:
Conversion method determines compound rheology design and reinforcement orientation.
- Extrusion:Continuous fiber-reinforced tapes enable automated fiber placement in battery enclosure sidewalls, displacing stamped aluminum at BMW and Hyundai-Kia.
- Injection Molding:Dominant conversion technology for complex geometries in interior and exterior applications, requiring precise melt flow index control and glass fiber length retention.
- Blow Molding:Fuel tank and fluid reservoir applications utilize multi-layer coextrusion compounds with permeation barrier properties.
- Thermoforming:Sheet extrusion followed by vacuum forming serves lower-volume exterior panels and protective covers with reduced tooling investment.
Injection Molding holds installed machine base. Extrusion is expanding most quickly through continuous fiber composite adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States exhibit low price elasticity for specialty nylon grades, while Chinese OEM procurement prioritizes cost efficiency in polypropylene volumes. This divergence shapes regional compounding strategies and margin capture.
United States
NHTSA crashworthiness protocols drive specification density for high-impact ABS and PC-ABS formulations in pedestrian safety systems. EPA tailpipe emissions rules restrict traditional refrigerants, forcing compounders to qualify hydrolysis-resistant grades for heat pump architectures. Detroit-area integrated partnerships enable just-in-sequence delivery to Ford and General Motors assembly plants.
Germany
REACH authorization requirements for flame retardant chemistries force continuous reformulation of under-hood nylon compounds. KBA type-approval processes demand extended hydrolysis resistance testing for battery thermal management applications. Ludwigshafen's Verbund sites anchor captive feedstock quality control for automotive-grade specifications.
China
MIIT new-energy vehicle mandates reshape material specifications for domestic OEM supply chains with localized capacity requirements. GB standards for recyclability force ISCC PLUS certification adoption among compounders serving BYD and CATL. Jiangsu and Guangdong provinces concentrate new compounding investments near NIO and XPeng assembly plants.
Japan
METI carbon neutrality targets accelerate substitution of metal components with glass-reinforced polymer compounds in hybrid architectures. JIS standards for automotive plastics create qualification barriers for imported compounds. Nagoya-area chemical complexes sustain technology leadership in long-fiber polypropylene fatigue resistance.
India
PLI scheme incentives for automotive component manufacturing attract compounding joint ventures to serve Maruti Suzuki and Tata Motors electrification programs. BIS certification requirements for automotive plastics extend qualification timelines for foreign suppliers. Gujarat and Tamil Nadu industrial corridors concentrate new extrusion compounding capacity for battery enclosure applications.
Global Automotive Plastic Compounding Market Vendor Landscape
Integrated chemical conglomerates and specialized compounders split the market between captive resin supply and formulation flexibility. The vendor base concentrates among European and Asian producers with backward integration into base polymer production. Three archetypes dominate: resin-integrated multinationals controlling feedstock quality, independent compounders offering rapid color-matching services, and regional specialists serving single-country OEM programs. Capacity expansion near assembly plants and closed-loop recompounding partnerships constitute the dominant competitive moves.
Within the resin-integrated tier, BASF SE and SABIC exemplify archetypes of feedstock control and technology leadership respectively. Covestro AG occupies a position among specialty polycarbonate compounders optimized for optical clarity applications. These three entities anchor the competitive structure through distinct material chemistry specializations rather than overlapping product portfolios.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| Covestro AG |
| Dow |
| DuPont de Nemours, Inc. |
| Ascend Performance Materials |
| Ravago |
| LANXESS |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European long-glass-fiber polypropylene lines is compressing spot pricing flexibility while Chinese integrated resin-to-compound operations exploit feedstock cost advantages. This utilization asymmetry between Ludwigshafen and Jiangsu plants forces buyers into longer contract tenors to secure allocation.
Pricing Analysis
Aftermarket collision repair parts and recompounded feedstock contracts anchor lifetime value capture beyond initial compound sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by glass fiber loading and OEM qualification status. Cost compression in commodity polypropylene grades is intensifying because Middle Eastern propylene exports are displacing European naphtha-based supply. Tier-1 injection molders exhibit highest price sensitivity due to just-in-sequence inventory models, while German OEMs accept premium positioning for REACH-compliant flame retardant formulations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for battery enclosure compounders serving dual-region OEM platforms. Feedstock supply concentrates in Saudi Arabia, Germany, and the United States for base polymer production, while specialty additive synthesis anchors in Germany and Japan. The supply chain draws from glass fiber rovings sourced in China and flame retardant masterbatches from Japanese chemical suppliers, creating single-source vulnerability in phosphinate-based alternatives. Distribution runs through integrated compounding partnerships near assembly plants rather than merchant distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle thermal architecture disruption is compressing traditional qualification cycles and redrawing material specification authority. EU F-Gas Regulation and EPA tailpipe rules are forcing simultaneous reformulation across multiple jurisdictions.
For Market Incumbents: Pre-empt qualification redundancy by consolidating testing protocols across REACH, EPA, and GB standards through unified hydrolysis resistance validation. BASF SE's Ludwigshafen Verbund model demonstrates how captive feedstock control defends margin position against propylene volatility. Capacity addition in Jiangsu province secures MIIT-mandated localization requirements before joint venture windows close. For New Entrants and Emerging Players: Establish a beachhead in closed-loop recompounding partnerships with Tier-1 injection molders seeking Scope 3 emissions reductions. India PLI scheme incentives for automotive component manufacturing offer the most penetrable geography, with Gujarat industrial corridor concentration matching Maruti Suzuki electrification timelines. Go-to-market through ISCC PLUS certification investment enables Volvo Cars and domestic OEM recycled-content mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous fiber-reinforced tape extrusion lines as BMW and Hyundai-Kia specifications displace stamped aluminum. Five-to-ten-year viability favors compounders with backward integration into base resin production or auditable mass-balance documentation. Acquisition target archetype: regional specialists with OEM co-development relationships and unutilized compounding capacity near NIO or XPeng assembly plants. Signal to watch: KBA type-approval timeline compression for heat pump-grade nylon qualifications.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Compounding Partnership | Just-in-sequence delivery to Ford and General Motors assembly plants reduces working capital requirements. |
| Backward Integration into Base Resin | BASF SE's Ludwigshafen Verbund sites control polypropylene quality for automotive-grade specifications. |
| Closed-Loop Recompounding Network | Post-industrial scrap recovery with Tier-1 molders creates captive feedstock pools and emissions reductions. |
| ISCC PLUS Certification Investment | Auditable mass-balance documentation satisfies Volvo Cars recycled-content mandates across interior applications. |
| Continuous Fiber Tape Capacity Addition | Extrusion-compounded unidirectional tapes enable automated fiber placement in BMW battery enclosure sidewalls. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, compounder technical directors, and aftermarket distributors and refined through secondary validation. Bottom-up modeling triangulated customs data on resin trade flows, IHS Markit vehicle production databases, and SEC filings from resin-integrated multinationals with top-down demand estimation based on content-per-vehicle assumptions across propulsion architectures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning material chemistry, manufacturing process, vehicle application zone, and regional production cluster. CAGRs were derived from regression analysis against historical capacity utilization and forward-looking OEM platform engineering specifications for battery thermal management content.
Stress conditions across propylene feedstock volatility, REACH authorization timelines, and MIIT mandate enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electrification penetration and substitution rates for metal components. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Metal Casting Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Automotive Bushing Market