
 Global Automotive Composite Market | 2026-2036
Global Automotive Composite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Composite Market Analysis
Multi-material vehicle architecture is rewriting how OEMs achieve mass reduction without sacrificing crash performance. Toray Industries leverages its carbon fiber precursor technology to sustain leadership in high-modulus aerospace-grade supply chains that extend into premium automotive programs. SGL Carbon SE anchors European demand through its Moses Lake facility and partnerships with BMW on i-series passenger cell structures. Hexcel Corporation differentiates through thermoplastic unidirectional tape formats that compete directly with traditional thermoset prepregs in automated production lines.
Automotive composites are engineered material systems combining high-strength fibers—carbon, glass, or aramid—with polymer, metal, or ceramic matrices, typically achieving specific tensile strengths exceeding 1,500 MPa at densities below 1.6 g/cm³, primarily to reduce vehicle curb weight while maintaining structural integrity and crash energy absorption. Fiber Reinforced Plastic dominates current volume owing to established supply chains and processing familiarity, though Ceramic Matrix Composite occupies the highest margin tier where thermal protection in electric vehicle battery enclosures commands premium pricing. Resin Transfer Molding leads capital investment among Manufacturing Stage categories as Tier-1 Suppliers seek cycle time compression for structural parts at automotive production scales.
The EPA enforces Corporate Average Fuel Economy thresholds that directly mandate gram-per-mile CO₂ reductions, compelling OEMs toward material lightweighting as a compliance pathway, while ECHA's REACH framework restricts certain resin chemistries and drives reformulation investment across European supply bases. China's MIIT issues GB standards for new energy vehicle safety that specify battery enclosure performance criteria favoring composite architectures over metallic alternatives. Stakeholders must monitor how evolving multi-jurisdictional carbon accounting rules reshape material selection criteria across platform development cycles.
Market Dynamics
Electric vehicle platform architecture is forcing material substitution decisions earlier in vehicle development cycles, compressing the window between composite specification and series production commitment. OEMs now lock fiber-reinforced structures into skateboard chassis designs before powertrain finalization.
Growth Catalysts
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive steel and aluminum favor domestic composite production for European vehicle assembly.
- Structural battery enclosures:Ceramic matrix composites penetrate thermal management layers in high-nickel cathode battery packs where metallic solutions fail.
- Germany's automotive engineering corridor:Concentrated R&D spending in Baden-Württemberg and Bavaria accelerates pre-competitive composite joining technology development.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs swing with oil-derived feedstock markets, compressing margin predictability for Tier-1 laminators.
- Japanese precursor concentration:Toray, Mitsubishi Chemical, and Toho Tenax control 70% of global PAN supply, creating single-source vulnerability for European automotive programs.
- End-of-life recyclability gaps:Thermoset epoxy matrices lack economically viable depolymerization pathways, exposing OEMs to extended producer responsibility liabilities under France's AGEC law.
Strategic Opportunities
- India's PLI scheme for automotive:Component-level incentives for lightweighting attract composite part manufacturing for export-focused compact vehicle platforms.
- Overmolded thermoplastic structural nodes:Hybrid unidirectional tape and injection-molded compound joints replace multi-piece metallic castings in crash-critical locations.
- China's dual carbon goals:Provincial NEV production mandates in Jiangsu and Zhejiang favor composite-intensive body-in-white designs for range extension.
Industry Challenges
- Automated fiber placement programming:Shortage of robotics technicians capable of converting CAD surfaces to machine code for complex A-pillar reinforcements delays production ramp.
- Multi-material corrosion management:Galvanic coupling between carbon fiber and aluminum subframes requires isolation engineering that extends validation timelines.
- Crash simulation calibration:Composite damage models lack standardized material cards, forcing OEMs to run parallel physical test programs that consume development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Composite Market |
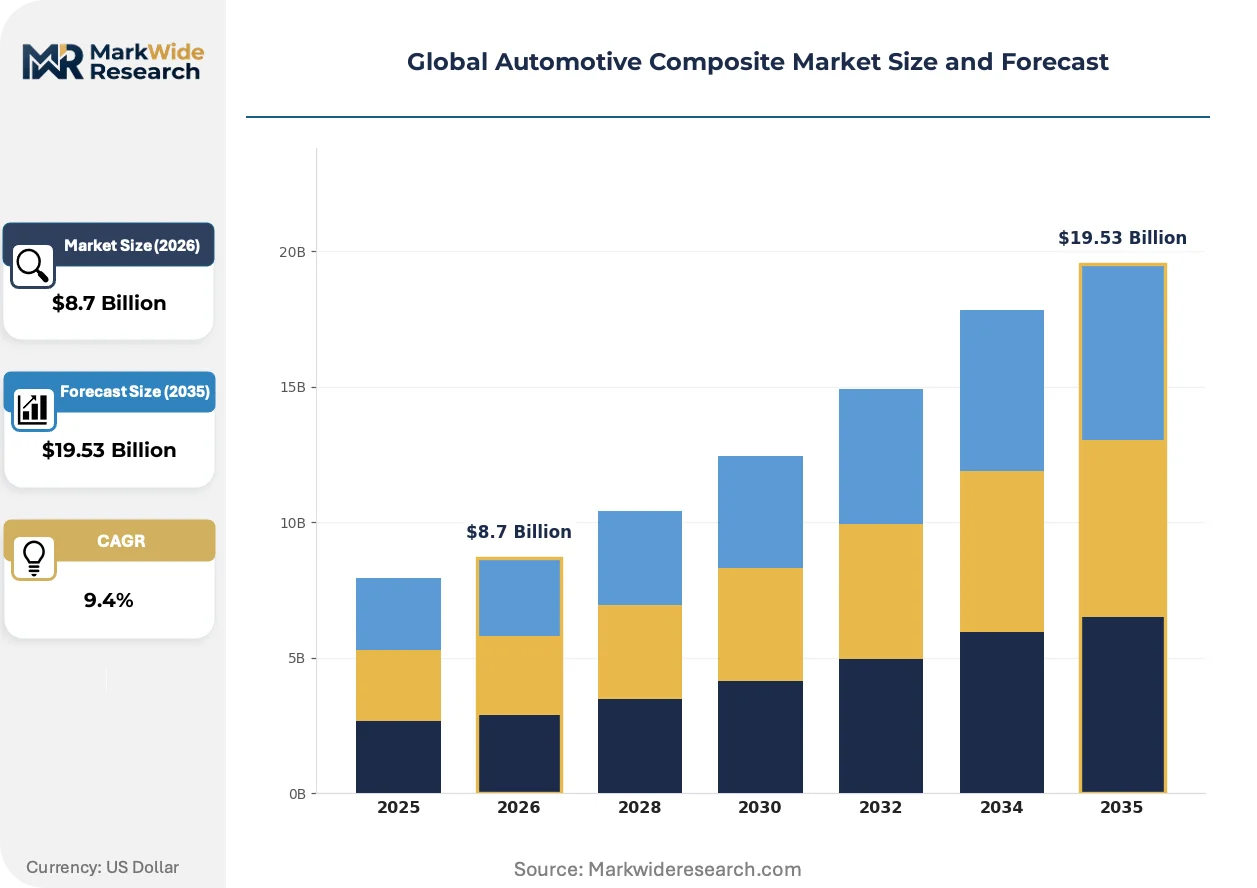
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Reinforced Plastic, Metal Matrix Composite, Ceramic Matrix Composite, Sandwich Composite End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Structural Parts, Body Panels, Interior Components, Chassis Manufacturing Stage: Prepreg Layup, Resin Transfer Molding, Injection Molding, Compression Molding |
| Companies Covered | Solvay SA, Hexcel Corporation, Toray Industries, Inc., Daicel Corporation, Gurit Holding AG, Teijin Limited, SGL Carbon SE, Zoltek Corporation, Mitsubishi Chemical Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Composite Market Emerging Trajectories
Digital thread integration across material qualification and part production is collapsing the traditional handoff between composite suppliers and vehicle assembly plants. Virtual validation protocols now substitute for physical build iterations in early program phases.
Thermoplastic unidirectional tapes with in-situ polymerization are virtualizing the capital footprint of structural composite manufacturing. BMW's i-series production line adopts these formats for A-pillar and roof bow integration, eliminating autoclave curing cycles. The compression of processing time from hours to minutes is virtualizing the economic boundary between metallic stamping and composite forming for annual volumes above 50,000 units.
EPA tailpipe standards under the revised CAFE framework mandate fleet-average CO₂ reductions that composite lightweighting directly addresses. The industrial consequence is specification of carbon fiber-intensive body structures in premium electric SUV platforms where battery mass penalties compound. North American OEMs respond by qualifying domestic preform suppliers in South Carolina and Alabama to hedge against transatlantic logistics exposure.
Consolidated procurement of composite structures by platform engineering teams is displacing commodity purchasing of individual fibers and resins. Tier-1 integrators like Magna and Benteler now contract directly for finished structural modules rather than raw material buy. This concentration is most visible in Germany, where Volkswagen's unified cell architecture bundles composite enclosure supply into single-source agreements spanning multiple vehicle lines.
Global Automotive Composite Market Segmentation
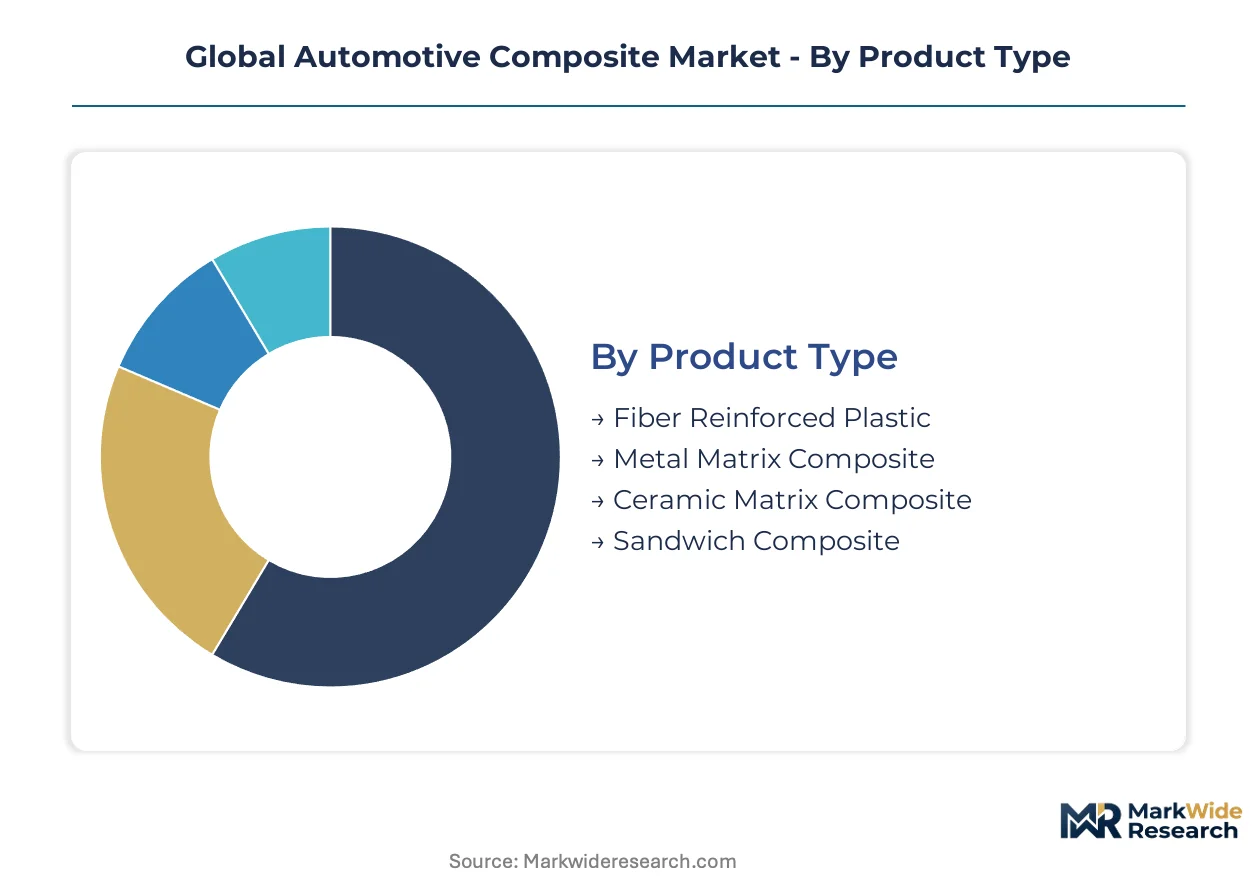
Automotive composite segmentation reveals how material selection maps to distinct value chains, each with unique processing economics and qualification barriers. Understanding these boundaries guides capital allocation across precursor supply, conversion technology, and finished part manufacturing.
Product Type:
Mature thermoset formats dominate installed capacity while emerging thermoplastic and ceramic systems capture specification share in next-generation platforms.
- Fiber Reinforced Plastic:Glass and carbon fiber systems embedded in epoxy or polyester matrices deliver tensile strengths exceeding 1,500 MPa at densities below 1.6 g/cm³. Demand concentrates in Germany's automotive engineering corridor where BMW and Volkswagen anchor composite-intensive passenger cell architectures for electric vehicle platforms.
- Ceramic Matrix Composite:Silicon carbide fiber-reinforced systems withstand continuous operating temperatures above 1,200°C. Battery enclosure thermal management layers in high-nickel cathode packs favor this format where metallic solutions fail, commanding premium pricing in European and Chinese electric vehicle programs.
- Metal Matrix Composite:Aluminum-silicon carbide hybrids bridge metallic processing familiarity with composite stiffness gains.
- Sandwich Composite:Honeycomb or foam core structures with composite skins optimize bending stiffness-to-weight ratios for floor panels and cargo areas.
Fiber Reinforced Plastic retains volume leadership; Ceramic Matrix Composite holds the steepest expansion curve.
End User:
Procurement authority is shifting upstream as platform engineering teams consolidate specification power away from commodity purchasing functions.
- OEMs:Volkswagen's unified cell architecture bundles composite enclosure supply into single-source agreements spanning multiple vehicle lines. Direct material specification locks fiber-reinforced structures into skateboard chassis designs before powertrain finalization.
- Tier-1 Suppliers:Magna and Benteler contract directly for finished structural modules rather than raw material buy, compressing the supply tier between precursor manufacturers and vehicle assembly plants.
- Vehicle Assemblers:Contract manufacturers in emerging production regions qualify local composite part suppliers to satisfy domestic content requirements.
- Aftermarket Providers:Collision repair and performance upgrade channels source prepreg kits and adhesive bonding systems for non-warranty structural restoration.
OEMs retain specification authority; Tier-1 Suppliers are gaining procurement consolidation power fastest.
Application:
Structural integration depth determines margin tier, with crash-critical components commanding qualification premiums over cosmetic applications.
- Structural Parts:A-pillar reinforcements, roof bows, and passenger cell frames carry occupant safety certification burdens. BMW's i-series production line adopts thermoplastic unidirectional tapes for these locations, eliminating autoclave curing cycles and compressing processing time from hours to minutes.
- Chassis:Battery enclosures and subframe components integrate thermal management with structural load paths. China's MIIT GB standards for new energy vehicle safety specify performance criteria favoring composite architectures over metallic alternatives in Jiangsu and Zhejiang production bases.
- Body Panels:Hoods, roofs, and closures prioritize surface quality and dent resistance alongside mass reduction targets.
- Interior Components:Seat shells, instrument panels, and trim elements emphasize acoustic damping and design flexibility over primary structural loading.
Structural Parts retain value concentration; Chassis applications are expanding most quickly as electric vehicle platform architecture matures.
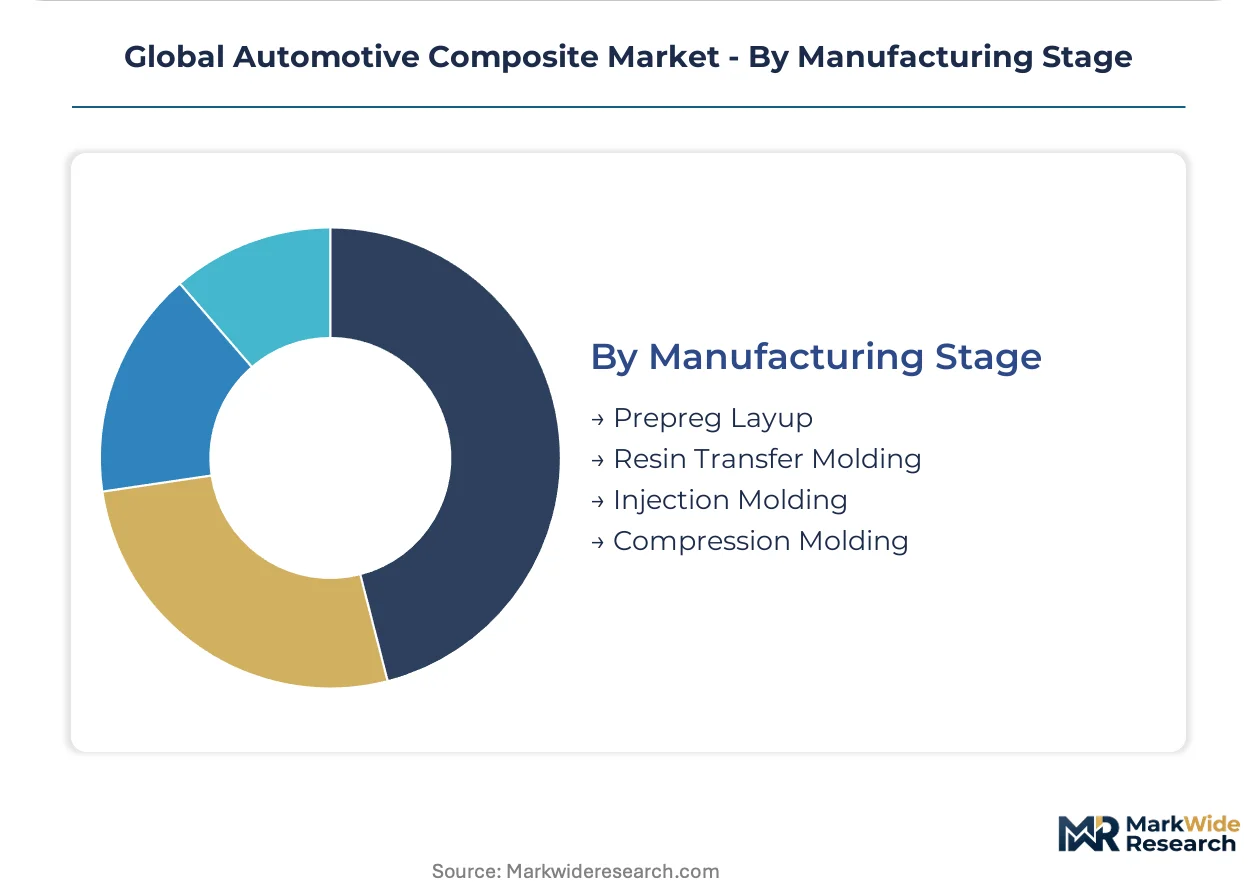
Manufacturing Stage:
Capital intensity and cycle time tradeoffs separate high-volume automotive qualification from aerospace-derived batch processing.
- Resin Transfer Molding:Closed-mold infusion of dry fiber preforms with reactive thermoset resins achieves automotive production cycle times under 10 minutes for structural components. Tier-1 Suppliers in South Carolina and Alabama are qualifying domestic preform suppliers to hedge against transatlantic logistics exposure.
- Prepreg Layup:Pre-impregnated fiber sheets require refrigerated supply chains and autoclave curing, limiting adoption to premium low-volume platforms despite superior mechanical properties.
- Injection Molding:Short-fiber thermoplastic compounds enable complex geometries with metallic insert overmolding for hybrid structural nodes.
- Compression Molding:Sheet molding compound formats serve high-volume body panel applications with established glass fiber supply chains.
Resin Transfer Molding leads capital deployment; Injection Molding is gaining specification share fastest as thermoplastic formats mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports finished composite structural modules to BMW and Volkswagen assembly plants across Europe and North America, establishing the dominant trade-flow corridor for premium automotive fiber systems.
United States
EPA Corporate Average Fuel Economy thresholds compel Detroit automakers toward material lightweighting for compliance. Domestic preform suppliers in South Carolina and Alabama qualify to hedge transatlantic logistics exposure. The Southeast manufacturing belt concentrates thermoplastic tape conversion capacity for electric SUV platforms.
Germany
BMW and Volkswagen anchor composite-intensive passenger cell architectures for electric vehicle programs. EU Green Deal carbon border adjustments favor domestic composite production over carbon-intensive steel imports. Baden-Württemberg and Bavaria accelerate pre-competitive joining technology development through concentrated R&D spending.
China
Provincial NEV production mandates in Jiangsu and Zhejiang favor composite-intensive body-in-white designs for range extension. MIIT GB standards for new energy vehicle safety specify battery enclosure performance criteria favoring composite architectures. The Yangtze River Delta hosts integrated precursor-to-part supply chains for domestic electric vehicle platforms.
Japan
Toray, Mitsubishi Chemical, and Toho Tenax control precursor supply for global automotive programs. METI industrial policy supports carbon fiber downstream integration into mobility applications. The Chubu region maintains aerospace-grade fiber production capacity that extends into premium automotive qualification pipelines.
India
PLI scheme component-level incentives for lightweighting attract composite part manufacturing for export-focused compact vehicle platforms. Domestic content requirements pressure vehicle assemblers to qualify local suppliers. Tamil Nadu and Maharashtra engineering corridors develop thermoplastic compression molding capacity for structural node production.
Global Automotive Composite Market Vendor Landscape
On the supply side, the industry is tiered between precursor manufacturers, intermediate converters, and finished part integrators. Japanese and European chemical conglomerates dominate upstream polyacrylonitrile supply. Strategic archetypes include captive fiber producers, independent preform specialists, and Tier-1 structural module integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs consolidate procurement authority.
Among European-based material science conglomerates, Solvay SA and SGL Carbon SE exemplify the integrated chemical-to-composite archetype, while Hexcel Corporation represents North American specialization in aerospace-grade formats extending into automotive qualification. Toray Industries, Inc. anchors the Japanese precursor concentration that supplies global laminators.
| Leading Market Players |
|---|
| Solvay SA |
| Hexcel Corporation |
| Toray Industries, Inc. |
| Daicel Corporation |
| Gurit Holding AG |
| Teijin Limited |
| SGL Carbon SE |
| Zoltek Corporation |
| Mitsubishi Chemical Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European precursor manufacturing drives aggressive contract positioning among Japanese suppliers, compressing margin buffers for Tier-1 laminators while forcing OEMs into longer-term offtake commitments to secure aerospace-grade fiber allocation.
Pricing Analysis
Thermoset epoxy prepregs command substantial premiums over emerging thermoplastic unidirectional tape formats, with ceramic matrix composites occupying the highest tier where thermal protection specifications justify extreme pricing. Price differentiation centers on certification grade—automotive OEM qualification status versus industrial grade—and volume scale, with annual commitments above 50,000 units unlocking meaningful discounts. Cost compression in standard-grade glass fiber reinforced plastics is intensifying because Chinese capacity expansion in Jiangsu and Zhejiang feeds export-focused pricing. Tier-1 suppliers exhibit the highest price sensitivity due to fixed OEM contract structures, while premium electric vehicle programs show relative inelasticity for crash-critical structural components.
Supply Chain Analysis
Acrylonitrile feedstock availability anchors the entire value chain, with polyacrylonitrile precursor production concentrating in Japan, the United States, and Germany. The automotive composite supply chain draws from oil-derived petrochemicals, silicon carbide ceramic powders, and high-purity carbon fiber tows as critical inputs. Single-source vulnerability runs through Japanese precursor concentration, where Toray, Mitsubishi Chemical, and Toho Tenax collectively control dominant global supply. Distribution runs through Tier-1 structural module integrators who now contract directly with OEM platform engineering teams, displacing traditional commodity purchasing of raw fibers and resins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—EPA CAFE thresholds, EU Green Deal carbon border adjustments, and China's MIIT GB standards—locks incumbent suppliers into multi-year OEM qualification pipelines that resist rapid substitution.
For Market Incumbents: Pre-empt emerging thermoplastic tape suppliers by accelerating in-house conversion capacity in South Carolina and Alabama, securing captive supply of aerospace-grade precursor through long-term Japanese offtake agreements. Threat from ceramic matrix composite specialists penetrating battery enclosure thermal management layers demands immediate R&D allocation toward hybrid material systems. Certification investment in China's MIIT GB standards represents the critical lever for platform-level integration into NEV architectures.
For New Entrants and Emerging Players: India's PLI scheme component-level incentives for lightweighting represent the most penetrable entry point, with Tamil Nadu and Maharashtra engineering corridors developing thermoplastic compression molding capacity that lacks established incumbent presence. Overmolded structural nodes for compact vehicle platforms offer a second white-space target where metallic casting substitution creates specification windows. A go-to-market angle anchored to domestic content compliance for export-focused vehicle assemblers bypasses direct competition with entrenched German and Japanese suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermoplastic unidirectional tape manufacturing as in-situ polymerization eliminates autoclave infrastructure requirements. Long-term viability over the next decade centers on platform engineering team relationships rather than commodity fiber production. Acquisition targets should emphasize preform specialists with active OEM qualification pipelines. The signal to watch is Volkswagen's unified cell architecture procurement consolidation, which will signal whether single-source structural module contracts become industry standard. Cross-checking against IHS Markit vehicle production data is advised before commitment-grade decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Toray's PAN technology control demonstrates how captive feedstock secures margin capture across automotive qualification pipelines. |
| Thermoplastic Tape Conversion Capacity Expansion | BMW's i-series production line adoption validates cycle-time compression from hours to minutes for A-pillar integration. |
| Joint Venture for Ceramic Matrix Composite Scale-Up | High-nickel cathode battery pack thermal management in European and Chinese NEV programs commands premium positioning. |
| Long-Term Supply Agreement with OEM Platform Teams | Volkswagen's unified cell architecture bundling demonstrates how procurement consolidation displaces commodity purchasing functions. |
| Geographic Manufacturing Footprint in Southeast US | South Carolina and Alabama preform supplier qualification hedges transatlantic logistics exposure for North American electric SUV platforms. |
Methodological Framework
Desk research of trade association filings, customs and trade flow databases, and vehicle production registries preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement directors, carbon fiber precursor plant managers, and automotive aftermarket distributors. Primary fieldwork combined with secondary validation against SEC 10-K disclosures, IHS Markit registration data, and EPA regulatory filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Forecast assumptions held fixed the regulatory trajectory of EPA CAFE standards, EU Green Deal implementation timelines, and China's dual carbon policy framework while varying electric vehicle platform adoption rates and composite content per vehicle across propulsion architectures. The analytical framework modeled vehicle class, structural application depth, manufacturing process economics, and regional production cluster dynamics. CAGRs were derived from production volume build-ups weighted by material substitution elasticities, with carbon fiber price volatility and thermoplastic processing yield rates serving as key sensitivity inputs.
Practitioners should monitor acrylonitrile price movements, Japanese precursor capacity utilization signals, and evolving extended producer responsibility regulations for early signals of forecast revision. Forecasts reflect documented assumptions about OEM platform standardization timelines and qualification pipeline durations. Cross-checking against IEA automotive materials demand projections and Cefic chemical industry output data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Resonator Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Electronic Clutch Actuators Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Automotive Silencer Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Europe Automotive Relay Market