
 Automotive Solenoid Valve Market | 2026-2036
Automotive Solenoid Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Solenoid Valve Market Analysis
The automotive solenoid valve market is recalibrating around a widening gap between precision-engineered premium units for electrified powertrains and cost-optimized commodity valves serving internal combustion residual demand. Robert Bosch GmbH leverages its integrated mechatronics portfolio to dominate high-pressure direct-injection applications. Denso Corporation anchors Asian OEM supply chains through captive manufacturing scale in Japan and Thailand. Continental AG competes on electromechanical integration depth, embedding valve control within broader thermal management modules.
An automotive solenoid valve is an electromechanically operated flow control device, typically constructed from ferritic stainless steel bodies, copper-wound coils rated for 12V or 48V architectures, and fluorocarbon elastomer seals capable of withstanding transmission fluid temperatures exceeding 150°C. Its primary function is to modulate hydraulic or pneumatic pressure with millisecond response times across engine, transmission, and brake subsystems. Proportional solenoid technology captures expanding margin pools as continuous variable positioning replaces simple on-off switching in hybrid transmission controls. Electromagnetic actuation leads unit volume but hybrid electropneumatic designs are accelerating fastest in commercial vehicle automated manual transmissions.
NHTSA brake safety mandates and EPA Tier 3 emissions enforcement in the United States, combined with EMA medical-equipment crossover standards and REACH material restrictions in Europe, compel suppliers to validate seal materials and electromagnetic compatibility across multiple regulatory frameworks. China's MIIT new-energy vehicle catalog requirements add a third compliance layer for market access. Stakeholders must monitor how 48V electrical architecture proliferation and solid-state relay displacement threats reshape coil design specifications and supplier qualification timelines.
Market Dynamics
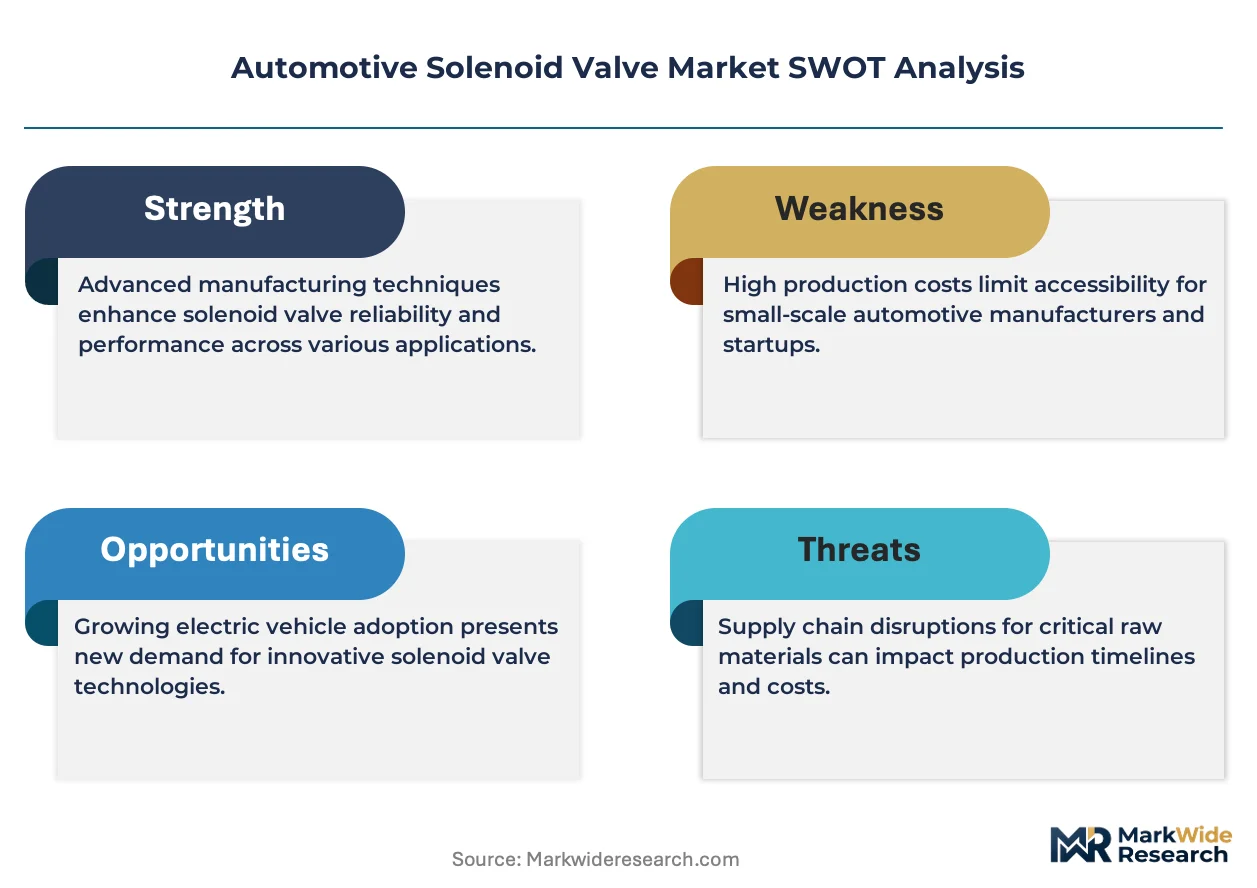
The automotive solenoid valve market is bifurcating around 48V electrical architecture proliferation, which demands redesigned coil specifications and electromagnetic compatibility validation that commodity suppliers cannot meet. This voltage transition separates premium integrated module suppliers from legacy component vendors.
Growth Catalysts
- EPA Tier 3 Emissions Enforcement:United States enforcement mandates millisecond-precision fluid control for direct-injection and aftertreatment systems, forcing OEMs to upgrade from mechanical to electromechanical actuation.
- Electric Vehicle Thermal Management:Battery pack cooling circuits and heat pump systems require proportional solenoid arrays for refrigerant distribution, creating incremental demand beyond powertrain applications.
- China MIIT New-Energy Vehicle Catalog:Access to China's subsidy-eligible vehicle list requires domestic certification of electromagnetic components, pulling localized production investment from multinational suppliers.
Market Restraints
- Copper and Rare Earth Magnet Volatility:Coil winding materials and permanent magnet components face price swings tied to concentrate supply from the Democratic Republic of Congo and China's processing dominance.
- Fluorocarbon Elastomer Supply Concentration:High-temperature seal materials rely on three Japanese chemical conglomerates for base polymer supply, creating single-source vulnerability for 150°C-rated transmission applications.
- Solid-State Relay Substitution:Silicon-carbide power electronics are displacing electromechanical switching in 48V bus architectures, threatening coil-based actuator volumes in secondary vehicle systems.
Strategic Opportunities
- Commercial Vehicle Automated Manual Transmissions:Electropneumatic shift actuation is accelerating fastest in European and North American heavy-duty truck fleets seeking fuel efficiency gains.
- REACH Material Compliance Services:European seal material validation requirements create aftermarket revenue streams for testing and certification services attached to valve replacement programs.
- India PLI Scheme for Auto Components:Production-linked incentives for advanced automotive electronics are drawing greenfield investment for solenoid manufacturing serving domestic OEMs and export markets.
Industry Challenges
- Mechatronics Integration Talent Scarcity:Valve suppliers struggle to hire firmware engineers capable of embedding control algorithms within thermal management modules rather than discrete components.
- Multi-Regulatory Certification Timelines:Simultaneous NHTSA brake safety, EPA electromagnetic compatibility, and China MIIT new-energy vehicle approvals extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Solenoid Valve Market |
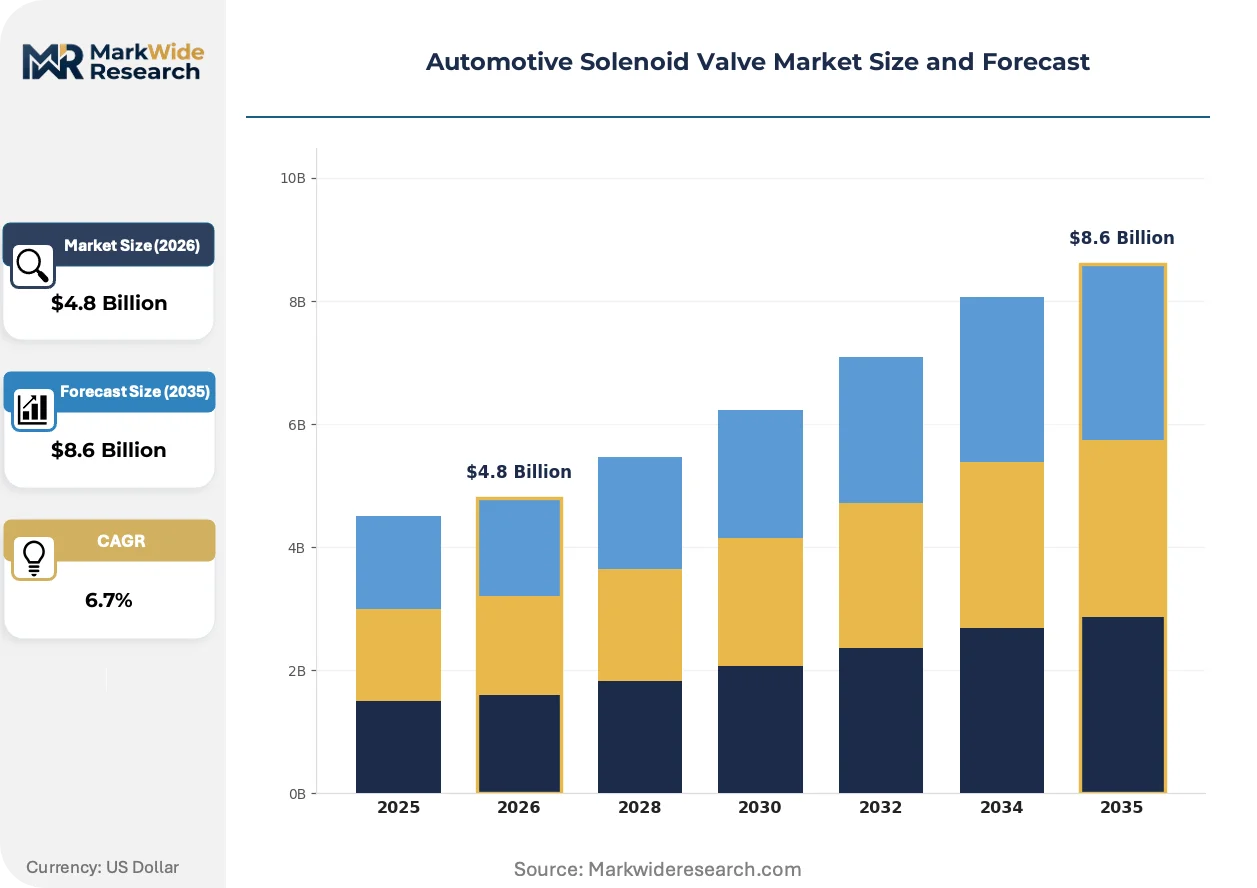
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-Acting, Pilot-Operated, Proportional, Switching Application: Engine Control, Transmission Systems, Fuel System, Brake Control End User: OEMs, Aftermarket Suppliers, Repair Shops, Distributors Technology: Electromagnetic, Pneumatic, Hydraulic, Hybrid |
| Companies Covered | Hitachi Ltd., Mitsubishi Electric Corporation, Robert Bosch GmbH, Emerson Electric Co., Denso Corporation, Continental AG, Johnson Electric Holding Ltd., Delphi Automotive PLC, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Solenoid Valve Market Emerging Trajectories
Proportional solenoid technology is compressing the competitive landscape by replacing binary on-off valves with continuous-position actuators. This shift rewards suppliers with precision manufacturing capabilities and software-integrated control systems.
Variable reluctance actuator designs are decentralizing hydraulic control architectures in hybrid transmissions. Toyota and Hyundai-Kia Group procurement teams specify these units for dual-clutch and e-CVT applications where clutch pack pressure demands infinite modulation. The technology is decentralizing valve function from centralized transmission control modules to distributed mechatronic subassemblies.
Euro 7 emission proposals are forcing seal material reformulation across European supply chains. The regulation's particulate number limits for gasoline direct-injection engines require tighter fuel pressure control, which accelerates fluorocarbon-to-perfluoroelastomer upgrades in high-pressure circuits. German and French OEMs are qualifying alternative seal compounds 18-24 months ahead of anticipated enforcement.
Fleet operators are compressing supplier qualification cycles for aftermarket replacement valves. North American commercial vehicle service networks now demand same-day availability of certified remanufactured units, displacing traditional three-day distribution through regional warehouses. This pattern is most visible in long-haul trucking corridors between Texas and Michigan, where uptime guarantees dominate procurement criteria.
Automotive Solenoid Valve Market Segmentation
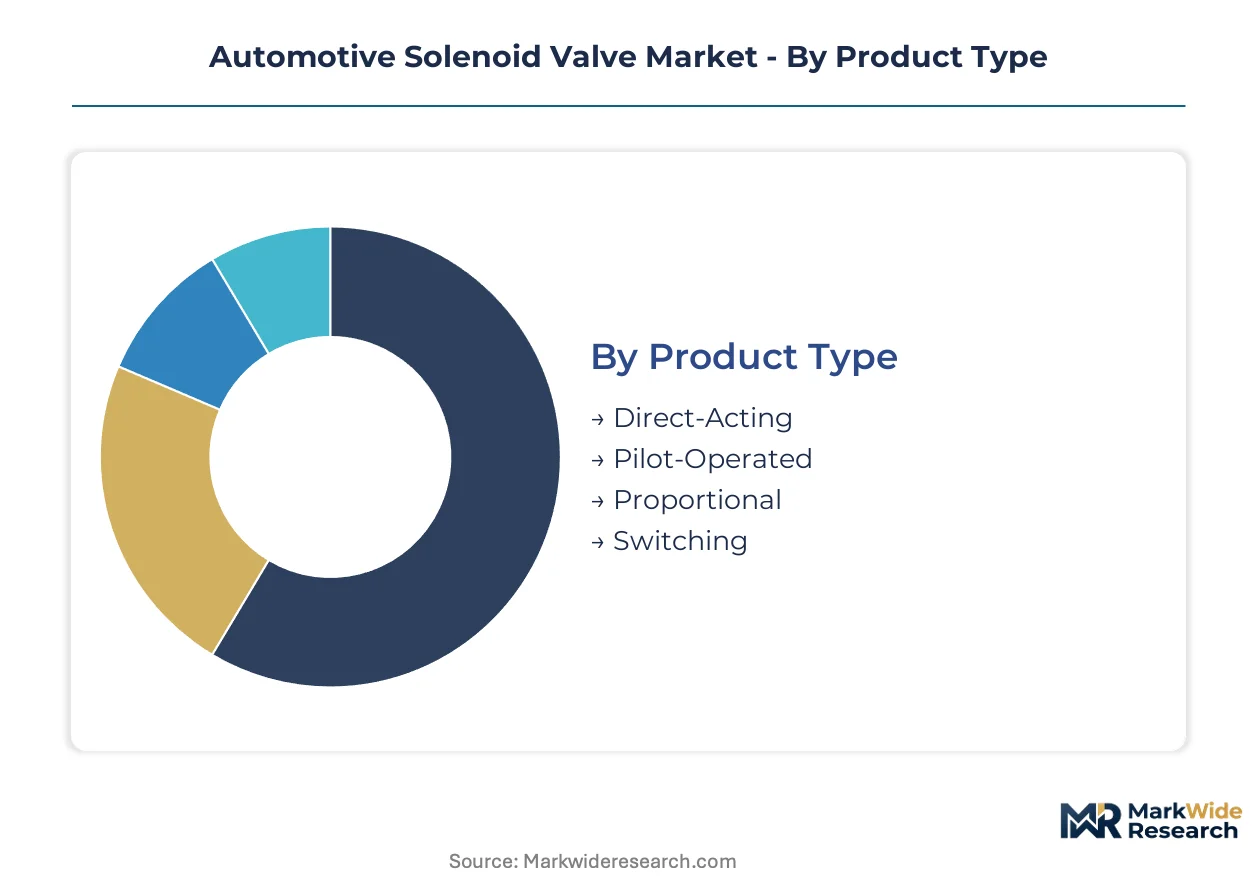
Automotive solenoid valve segmentation reveals how technical specifications, application intensity, and procurement channels fragment demand. Suppliers must align coil architectures and seal materials with distinct performance thresholds across powertrain electrification tiers.
Product Type:
Technical sophistication separates segments capable of millisecond-precision modulation from commodity on-off switching. Coil winding density, plunger metallurgy, and feedback sensor integration define competitive positioning within each architecture.
- Direct-Acting:Compact electromagnetic plungers shift fluid paths without intermediate pressure stages. OEMs specify these for brake control modules in United States passenger vehicles where NHTSA mandates sub-100ms response times for stability control intervention.
- Proportional:Continuous-position actuators modulate flow rates through variable coil excitation. Battery thermal management systems in German and Chinese electric vehicles demand these for refrigerant distribution circuits, capturing expanding margin pools as heat pump adoption accelerates.
- Pilot-Operated:Uses upstream pressure differentials to amplify actuation force for high-flow transmission circuits.
- Switching:Binary on-off designs serve cost-optimized internal combustion residual demand in emerging markets.
Direct-Acting leads on scale; Proportional leads on momentum.
Application:
Application intensity correlates with fluid pressure severity and thermal cycling frequency. High-pressure direct-injection and electrified transmission architectures impose the most demanding validation requirements.
- Transmission Systems:Dual-clutch and e-CVT architectures require infinite clutch pack pressure modulation. Toyota and Hyundai-Kia procurement teams in Japan and South Korea specify proportional arrays for hybrid powertrains where electromechanical coordination determines efficiency.
- Engine Control:Gasoline direct-injection circuits operate at 200+ bar pressures demanding fluorocarbon-to-perfluoroelastomer seal upgrades. Euro 7 proposals in Europe are forcing German and French OEMs to qualify alternative compounds ahead of enforcement timelines.
- Brake Control:ABS and stability modules mandate fail-safe electromagnetic architectures under NHTSA brake safety mandates.
- Fuel System:Vapor recovery and tank ventilation circuits employ lower-pressure pilot-operated designs.
Transmission Systems commands premium pricing; Engine Control faces the steepest regulatory compliance burden.
End User:
Procurement channel structure determines qualification depth, volume scale, and aftermarket service attachment rates. OEM direct supply demands the most intensive electromagnetic compatibility validation.
- OEMs:Tier-1 module suppliers integrate solenoids within thermal management and transmission control assemblies. China MIIT new-energy vehicle catalog requirements pull localized production investment from multinational suppliers seeking subsidy-eligible vehicle platform access.
- Aftermarket Suppliers:Fleet operators in North American long-haul trucking corridors compress qualification cycles for remanufactured units. Texas-to-Michigan service networks now demand same-day availability, displacing traditional three-day distribution.
- Repair Shops:Independent service channels prioritize cost-optimized direct-acting replacements for legacy internal combustion vehicles.
- Distributors:Regional warehousing operations buffer inventory for fragmented commercial vehicle service networks.
OEMs dominate value capture; Aftermarket Suppliers are climbing fastest on electrified vehicle aging.
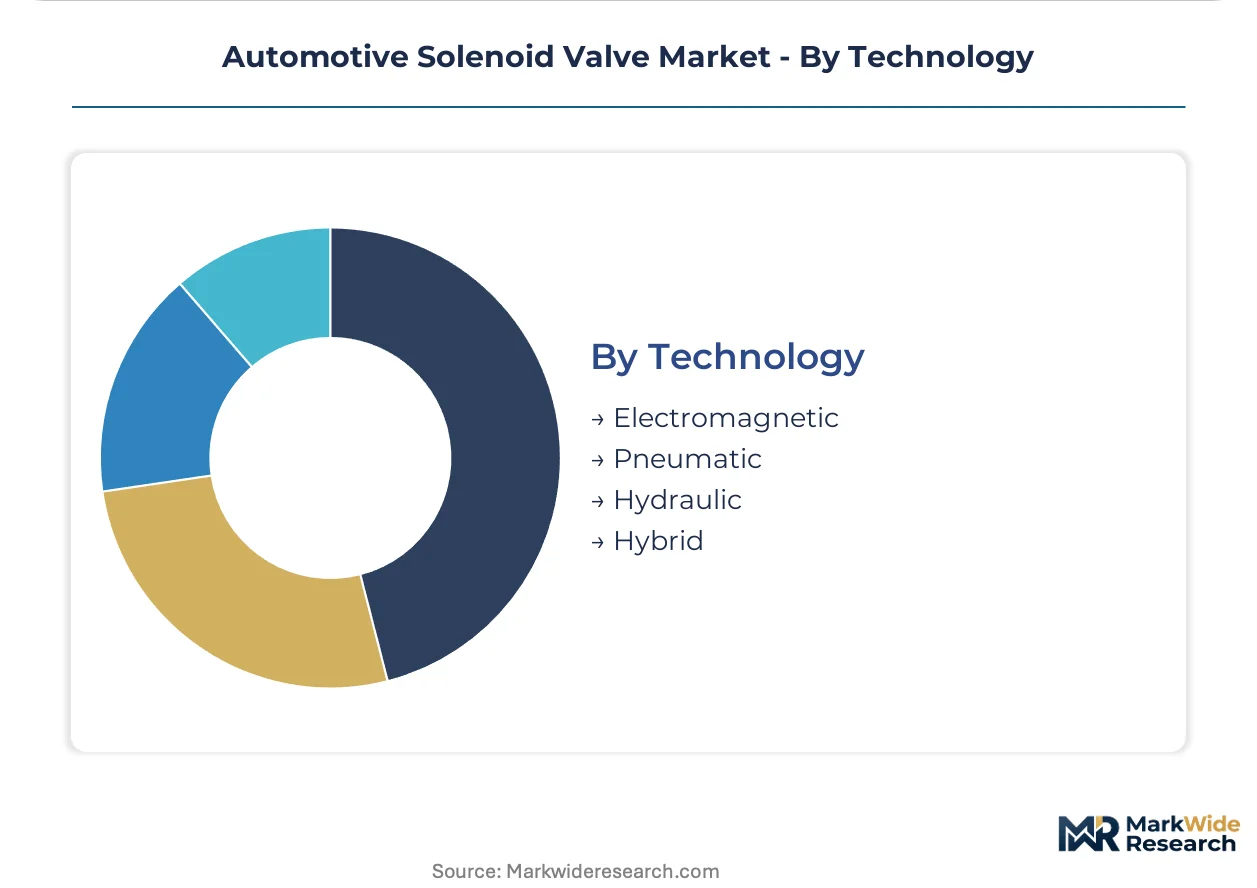
Technology:
Actuation mechanism selection reflects voltage architecture migration and mechatronics integration depth. 48V electrical proliferation is bifurcating suppliers capable of redesigned coil specifications from legacy component vendors.
- Electromagnetic:Copper-wound coils rated for 12V or 48V architectures remain the dominant volume technology. Robert Bosch GmbH and Denso Corporation anchor supply chains through captive ferritic stainless steel body manufacturing and fluorocarbon elastomer seal qualification.
- Hybrid:Electropneumatic designs combine electromagnetic pilot stages with pneumatic amplification. European heavy-duty truck fleets specify these for automated manual transmissions where fuel efficiency gains justify premium positioning.
- Hydraulic:Direct fluid pressure actuation serves high-force commercial vehicle applications.
- Pneumatic:Compressed air systems dominate commercial vehicle brake and suspension circuits.
Electromagnetic anchors installed base; Hybrid is expanding most quickly on commercial vehicle electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Nagoya, and Detroit anchor solenoid valve design capabilities. Manufacturing scale concentrates in industrial corridors where automotive OEM procurement teams maintain direct supplier relationships. Regulatory enforcement intensity varies sharply across jurisdictions, reshaping investment location decisions.
United States
NHTSA brake safety mandates and EPA Tier 3 emissions enforcement drive precision fluid control demand. The Inflation Reduction Act's domestic content requirements pull localized production investment for electrified vehicle components. Michigan-Ohio industrial corridors host module integration facilities serving Detroit Three procurement teams.
Germany
Euro 7 emission proposals force fluorocarbon-to-perfluoroelastomer seal upgrades across supply chains. KBA type-approval requirements extend validation timelines for electromagnetic compatibility certification. Baden-Württemberg engineering clusters specialize in mechatronics integration for thermal management modules.
China
MIIT new-energy vehicle catalog requirements compel domestic electromagnetic component certification for subsidy access. Dual carbon goals accelerate battery thermal management system deployment across OEM platforms. Yangtze River Delta manufacturing bases concentrate high-volume coil winding capacity.
Japan
METI industrial policy supports captive ferritic stainless steel body manufacturing for precision valve architectures. JIS standards govern high-temperature seal material qualification for transmission applications exceeding 150°C. Nagoya-Toyota City supply corridors integrate solenoid production within keiretsu procurement networks.
India
PLI scheme production-linked incentives for advanced automotive electronics draw greenfield solenoid manufacturing investment. BIS certification requirements create compliance barriers for imported electromagnetic components. Tamil Nadu and Gujarat industrial zones host emerging module assembly operations serving domestic OEMs.
Automotive Solenoid Valve Market Vendor Landscape
Top-tier vendors anchor integrated mechatronics portfolios, while commodity coil suppliers struggle with 48V electrical architecture qualification. The market structure separates precision manufacturers capable of millisecond response validation from legacy component vendors. Three archetypes dominate: captive OEM-aligned suppliers, independent electromechanical specialists, and diversified industrial conglomerates. Consolidation pressures intensify through strategic partnerships and geographic expansion moves.
Within the diversified industrial tier, Robert Bosch GmbH exemplifies integrated module supply capabilities. Denso Corporation occupies a position within Asian OEM-aligned manufacturing networks. Continental AG represents European electromechanical integration depth. These three entities anchor competitive positioning across distinct regional procurement clusters.
| Leading Market Players |
|---|
| Hitachi Ltd. |
| Mitsubishi Electric Corporation |
| Robert Bosch GmbH |
| Emerson Electric Co. |
| Denso Corporation |
| Continental AG |
| Johnson Electric Holding Ltd. |
| Delphi Automotive PLC |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
Tier 1 module suppliers concentrate procurement power for solenoid valves, forcing a contract-based long-term offtake pricing model where annual volume commitments lock in coil winding capacity. This buyer concentration rewards integrated mechatronics vendors capable of certifying electromagnetic compatibility across NHTSA, EPA, and China MIIT frameworks.
Pricing Analysis
Bundled module supply dominates OEM procurement while unbundled component sales serve aftermarket channels. Three-tier pricing structure across premium proportional, standard direct-acting, and economy switching valves reflects certification grade and coil architecture complexity. Cost compression in commodity on-off designs intensifies as Chinese domestic suppliers expand Yangtze River Delta capacity. Aftermarket distributors exhibit highest price sensitivity; OEM thermal management module integrators prioritize millisecond-precision validation over unit cost.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing bases to European and North American assembly plants amplifies landed cost differentials for copper-wound coil components. Supply concentrates in China, Japan, and Germany for ferritic stainless steel bodies and fluorocarbon elastomer seals. Raw material dependencies draw from Chilean copper concentrate and Chinese rare earth processing. Single-source vulnerability in high-temperature seal polymers from Japanese chemical conglomerates threatens transmission application supply security. Distribution runs through captive OEM logistics networks and independent aftermarket warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Euro 7 emission proposals and EPA Tier 3 enforcement tighten fluid control precision requirements, accelerating premium proportional valve demand across electrified powertrains.
For Market Incumbents: Lock in coil winding capacity through backward integration into copper conductor supply or captive ferritic stainless steel forging partnerships. Defend against solid-state relay substitution by embedding firmware control algorithms within thermal management modules rather than discrete valve components. Prioritize electromagnetic compatibility pre-certification across NHTSA, EPA, and China MIIT frameworks to compress 14-18 month approval timelines. For New Entrants and Emerging Players: Launch via India PLI scheme production-linked incentives for advanced automotive electronics, targeting domestic OEM procurement and export qualification. Focus on commercial vehicle electropneumatic shift actuation where European and North American heavy-duty truck fleets prioritize fuel efficiency gains over incumbent relationships. Pursue REACH material compliance service revenue streams attached to European aftermarket valve replacement programs. For Investors and Strategic Acquirers: Tier 1 thermal management module suppliers are the most active acquirer in this space, consolidating electromechanical integration capabilities ahead of 48V architecture proliferation. Long-term viability centers on proportional valve technology portfolios serving battery thermal management and hybrid transmission applications. Monitor solid-state relay displacement rates in 48V bus architectures as inflection indicator for coil-based actuator volume erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs consolidate valve architectures across 12V and 48V electrical systems to reduce electromagnetic compatibility validation burden. |
| Battery Supply Agreement | Thermal management module suppliers secure refrigerant circuit allocation through direct cell manufacturer partnerships. |
| Software-Defined Vehicle Investment | Valve control algorithm development shifts from hardware suppliers to OEM software centers in Stuttgart and Detroit. |
| Geographic Manufacturing Footprint | Multinational suppliers localize Yangtze River Delta coil winding capacity for China MIIT catalog compliance. |
| Charging Infrastructure Partnership | Heat pump system suppliers integrate proportional valve arrays through EV charging station thermal management alliances. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with Tier 1 supplier procurement teams, OEM platform engineers, and aftermarket distribution heads with secondary validation. Sources include EPA enforcement databases, MIIT new-energy vehicle catalog filings, IHS Markit vehicle production data, and customs trade records for copper and rare earth magnet flows. Bottom-up unit volume estimates triangulate against top-down OEM platform content assumptions.
Granularity extends to propulsion architecture, vehicle class, and regional production cluster levels across the projection horizon. Segmentation dimensions model direct-acting, proportional, pilot-operated, and switching product types against transmission, engine control, brake, and fuel system applications. CAGRs derive from regression analysis of historical OEM procurement patterns and regulatory enforcement intensity trajectories. Forecast inputs incorporate 48V electrical architecture adoption curves and Euro 7 implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price volatility and geopolitical trade restriction scenarios. Assumptions reflect stated OEM electrification roadmaps and regulatory enforcement schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Pedals Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Differential Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Automotive Axle Market