
 Automotive Refrigerant Market | 2026-2036
Automotive Refrigerant Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Refrigerant Market Analysis
Hydrofluorocarbon chemistries is repositioning product economics across the automotive refrigerant value chain as CO2 and hydrocarbon alternatives gain manufacturing scale. Arkema leverages its fluorochemical heritage to sustain European supply relationships for next-generation formulations. Honeywell International Inc. anchors North American production capacity for low-global-warming-potential blends. Daikin Industries Ltd. competes through specialized compressor-refrigerant system integration in Japanese OEM programs.
Automotive refrigerant denotes the working fluid circulated within vehicle climate control systems, typically operating at pressures between 10 and 40 bar and engineered with specific thermodynamic properties to enable heat absorption and rejection across evaporator and condenser stages. Its primary commercial purpose is cabin temperature regulation and, increasingly, battery thermal management in electrified powertrains. HFC formulations still occupy the largest volume share across passenger vehicle applications, though CO2 segments are recording the fastest growth trajectory as OEMs redesign thermal architectures for electrified platforms. Aftermarket services represent a concentrated margin pool due to recurring recharge demand and regulatory compliance requirements for handling and recovery.
The EPA oversees refrigerant handling certification and phase-down schedules under Clean Air Act authority in the United States, while the EU F-Gas Regulation mandates stepped reductions in hydrofluorocarbon consumption across member states. EMA and national agencies enforce automotive chemical safety standards that shape product registration timelines and market access conditions. Stakeholders must monitor evolving refrigerant charge size regulations and service technician certification requirements as thermal system electrification accelerates.
Market Dynamics
CO2-based refrigerant systems are compressing product development cycles as OEMs redesign thermal architectures for battery-electric platforms, forcing suppliers to retool manufacturing lines ahead of regulatory phase-down deadlines.
Growth Catalysts
- Kigali Amendment phase-down schedules:The Montreal Protocol framework mandates stepped reductions in hydrofluorocarbon production quotas across signatory nations, accelerating OEM investment in alternative chemistries.
- Battery thermal management:Electric vehicle powertrains require precise cabin and pack temperature control, expanding refrigerant charge sizes per vehicle versus conventional internal combustion architectures.
- German automotive cluster:Stuttgart and Munich-based OEMs and tier suppliers are building dedicated CO2 charging infrastructure and technician certification programs.
Market Restraints
- Fluorochemical feedstock volatility:Hydrofluoroolefin precursors depend on fluorspar concentrate supply concentrated in China and Mexico, exposing blenders to input cost swings.
- Service infrastructure gaps:CO2 systems operate at pressures exceeding 100 bar, requiring specialized recovery equipment that remains scarce in independent repair networks across Southern and Eastern Europe.
- Legacy HFC lock-in:Existing vehicle parc and service technician familiarity with R-134a and R-1234yf formulations slows fleet-wide transition timelines despite regulatory deadlines.
Strategic Opportunities
- India automotive production:Domestic OEMs and joint ventures are scaling manufacturing capacity without legacy refrigerant infrastructure, enabling direct adoption of low-global-warming-potential systems.
- Heat pump convergence:Integration of cabin cooling with battery heating circuits is consolidating thermal system architectures and expanding refrigerant circuit complexity per vehicle.
- EU F-Gas quota trading:Refrigerant blenders with excess allocation rights can monetize surplus permits as phase-down intensifies, creating secondary revenue streams.
Industry Challenges
- Technician certification bottlenecks:EPA Section 608 and EU F-Gas handler credentials require separate training pathways for CO2 and flammable hydrocarbon systems, constraining service capacity expansion.
- Thermal system integration complexity:Battery-electric platforms demand simultaneous optimization of range, charging speed, and occupant comfort, compressing engineering validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Refrigerant Market |
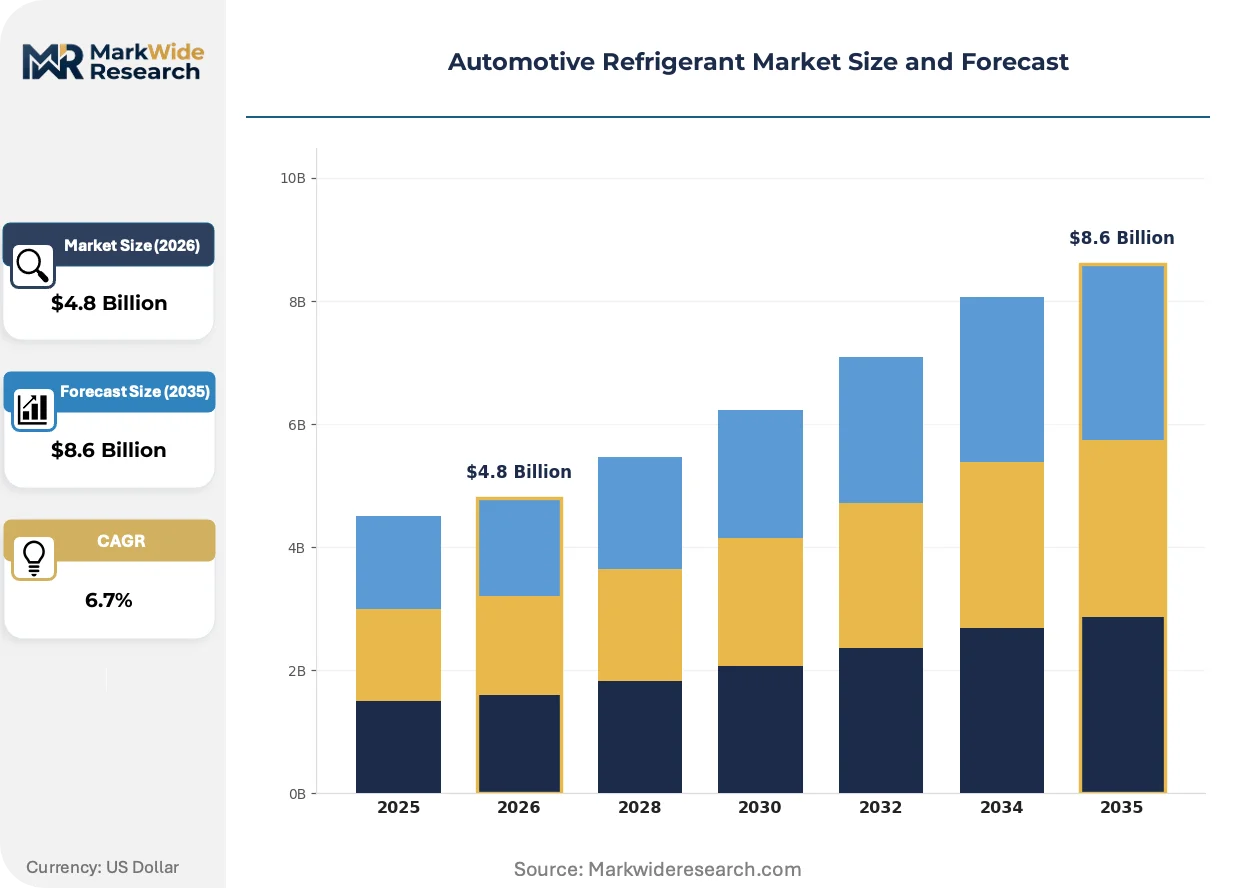
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HFC, CO2, NH3, Hydrocarbon Application: Passenger Vehicles, Commercial Vehicles, Light Trucks, Heavy-Duty Trucks End User: OEMs, Aftermarket Services, Fleet Operators, Repair Workshops Distribution Channel: Direct Sales, Distributors, Online Retail, Stores |
| Companies Covered | Denso Corporation, Hanon Systems, Arkema, Honeywell International Inc., MAHLE GmbH, AGC Inc., Daikin Industries Ltd., Hitachi Ltd., The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Refrigerant Market Emerging Trajectories
Refrigerant selection criteria are expanding beyond thermodynamic efficiency to encompass lifecycle carbon accounting and service ecosystem readiness, reshaping how OEMs evaluate supplier proposals.
Transcritical CO2 systems are integrating battery and cabin thermal loops into unified architectures. Premium European OEMs have adopted this approach for dedicated electric platforms since 2019. The technology is integrating heat pump functionality and fast-charge thermal preconditioning into single refrigerant circuits, compressing the competitive window for conventional HFC-based suppliers.
The EU F-Gas Regulation mandates 55% hydrofluorocarbon consumption reduction by 2030 versus 2015 baselines. This framework forces refrigerant blenders to redirect R&D spending toward unsaturated HFO formulations and natural refrigerant handling systems. German and French OEMs are most exposed, accelerating supplier qualification timelines for CO2-compatible compressor and seal technologies.
Fleet operators are unbundling refrigerant recharge services from traditional dealership maintenance contracts. Commercial vehicle and ride-hail fleets in California and the Netherlands now procure refrigerant management through specialized contractors with dedicated recovery and reclamation capabilities. This procurement pattern shift concentrates volume with service providers holding EPA or national environmental agency certifications, marginalizing uncertified independent workshops.
Automotive Refrigerant Market Segmentation
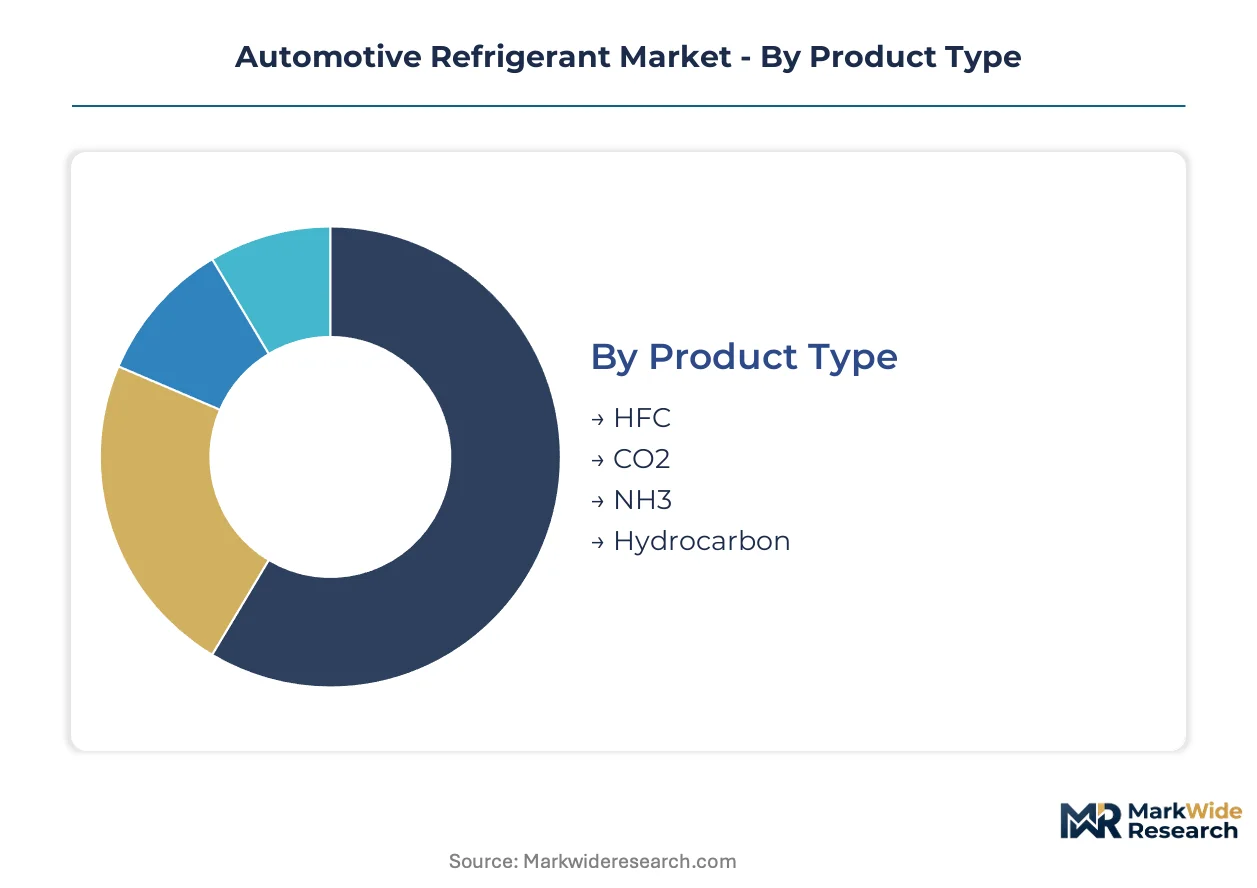
Refrigerant selection criteria diverge sharply across vehicle platforms and service models. OEMs prioritize thermal integration and regulatory compliance, while aftermarket channels emphasize handling certification and recovery infrastructure.
Product Type:
Standardization dominates at the chemistry level as OEMs consolidate around fewer formulations, yet system architecture customization accelerates for electrified platforms.
- HFC:Hydrofluorocarbon blends remain the incumbent chemistry across legacy vehicle parc, with R-1234yf formulations capturing new passenger vehicle production in the United States and Japan. Demand concentrates in retrofit services and independent repair networks constrained by equipment replacement costs.
- CO2:Transcritical systems operate at pressures exceeding 100 bar, requiring redesigned compressors, seals, and charging infrastructure. German OEMs have adopted this chemistry fastest for dedicated battery-electric platforms, compressing supplier qualification timelines for compatible components.
- NH3:Ammonia formulations deliver superior thermodynamic efficiency for commercial vehicle refrigeration units, though toxicity concerns restrict passenger vehicle applications.
- Hydrocarbon:Propane and isobutane blends serve niche markets in light commercial vehicles where charge size regulations permit flammable refrigerant deployment.
Leading the category by volume: HFC. Growing fastest: CO2.
Application:
Passenger vehicle electrification is fragmenting thermal architectures, while commercial vehicle duty cycles sustain simpler, proven refrigerant circuits.
- Passenger Vehicles:Battery-electric platforms require simultaneous cabin cooling and pack thermal management, doubling refrigerant circuit complexity versus internal combustion predecessors. European OEMs are converging on CO2-based heat pump systems for dedicated EV architectures.
- Commercial Vehicles:Long-haul trucks and delivery vans prioritize reliability and service network density, preserving HFC formulations despite regulatory phase-down pressure. Fleet operators in California and the Netherlands are piloting CO2 systems for depot-based charging scenarios.
- Light Trucks:Pickup and van segments in North America lag passenger car electrification, extending R-1234yf dominance through legacy platform carryover.
- Heavy-Duty Trucks:Sleeper cab climate control and transport refrigeration drive refrigerant demand, with ammonia systems gaining traction in European cold-chain logistics.
Passenger vehicles command the largest volume position. Commercial vehicles are climbing the fastest as fleet electrification accelerates.
End User:
Procurement patterns split between OEM captive supply agreements and fragmented aftermarket certification requirements.
- OEMs:Automakers qualify refrigerant suppliers through multi-year platform contracts tied to thermal system architecture decisions. German and Japanese OEMs are consolidating supplier bases around CO2-compatible component ecosystems.
- Aftermarket Services:Specialized contractors with EPA Section 608 or EU F-Gas handler credentials are capturing fleet maintenance contracts, marginalizing uncertified independent workshops. Recharge demand concentrates in high-temperature climates with accelerated refrigerant degradation.
- Fleet Operators:Commercial and ride-hail fleets in California unbundle refrigerant management from dealership service contracts, procuring through dedicated recovery and reclamation providers.
- Repair Workshops:Independent garages face capital barriers to CO2-compatible recovery equipment, constraining service capacity for newer vehicle parc.
OEMs dominate value capture. Aftermarket services are expanding most quickly as vehicle parc diversifies across refrigerant chemistries.
Distribution Channel:
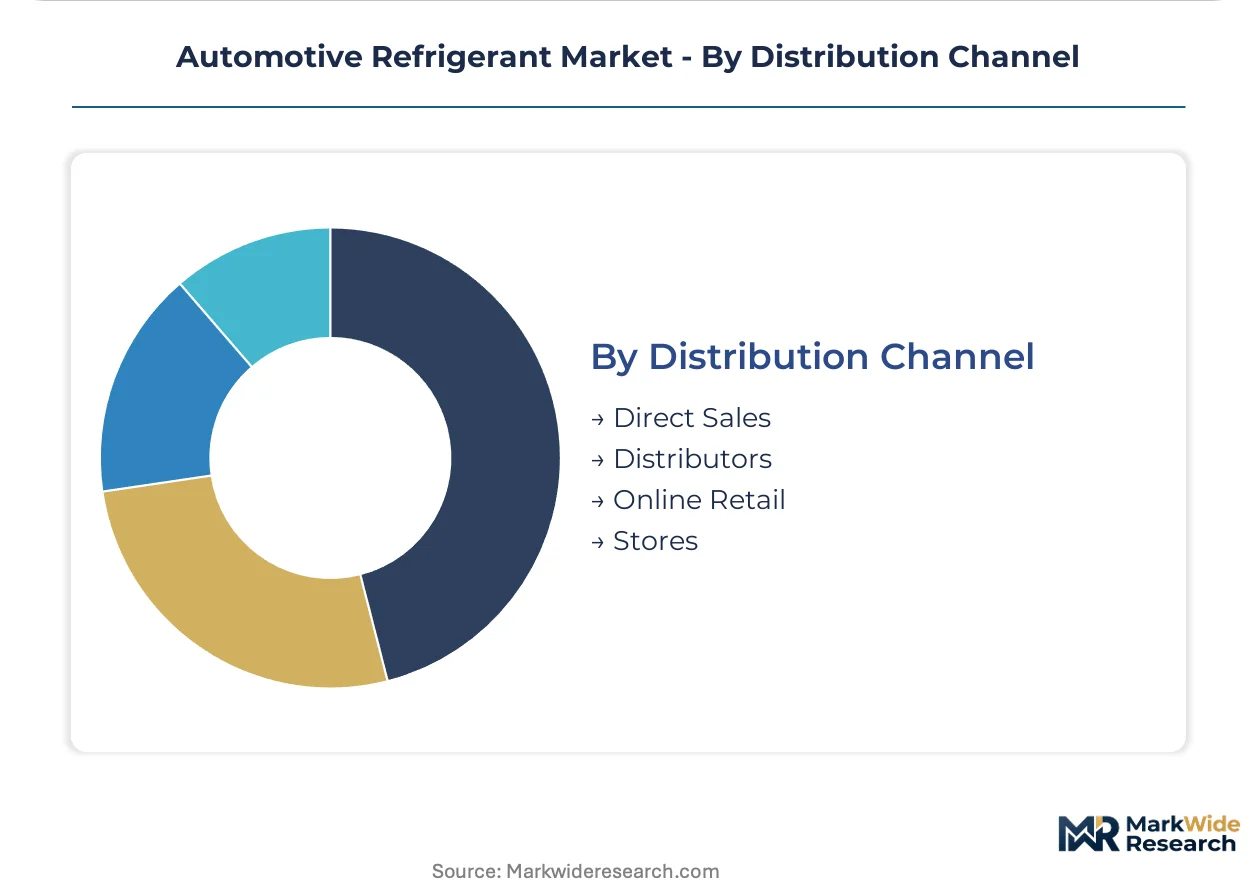
Channel selection tracks customer scale and certification requirements, with bulk supply favoring direct relationships and small-volume demand fragmenting across intermediaries.
- Direct Sales:Refrigerant blenders supply OEMs and large fleet operators through long-term contracts with embedded recovery and reclamation services. Arkema and Honeywell anchor European and North American direct supply relationships.
- Distributors:Regional wholesalers bridge blenders to independent repair networks, consolidating fragmented demand across multiple refrigerant SKUs. Inventory management complexity rises with HFC phase-down quota volatility.
- Online Retail:Small-volume canister sales to certified technicians are migrating to specialized B2B platforms with credential verification requirements.
- Stores:Automotive retail chains serve DIY recharge demand in markets with permissive handling regulations, though EPA and EU restrictions constrain this channel.
Direct sales lead by volume. Distributors are gaining share fastest as service network fragmentation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automakers and suppliers concentrate CO2 charging infrastructure investment, while Japanese OEMs and Chinese battery-electric manufacturers drive divergent thermal system architectures across major production centers.
Germany
Stuttgart and Munich-based OEMs mandate CO2-compatible components for dedicated electric platforms, compressing supplier qualification timelines. The EU F-Gas Regulation drives stepped HFC consumption reductions through 2030. The Baden-Württemberg automotive cluster hosts dedicated technician certification programs and charging infrastructure deployment.
United States
EPA Section 608 certification requirements shape aftermarket service capacity as fleet operators unbundle refrigerant management from dealership contracts. The Inflation Reduction Act provisions accelerate commercial vehicle electrification procurement patterns. California-based fleet operators pilot CO2 systems for depot-based charging scenarios.
China
Domestic OEMs and joint ventures scale battery-electric manufacturing without legacy refrigerant infrastructure constraints. The Ministry of Ecology and Environment implements dual carbon goals affecting chemical sector feedstock planning. The Yangtze River Delta concentration includes compressor-refrigerant system integration facilities serving both domestic and export programs.
Japan
METI standards and JIS certification frameworks govern refrigerant handling and equipment specifications across OEM supply chains. Daikin Industries anchors specialized compressor-refrigerant integration for domestic automotive programs. The Nagoya-Tokyo industrial corridor sustains precision component manufacturing for thermal management systems.
India
Domestic OEMs and joint ventures scale manufacturing capacity without legacy refrigerant infrastructure, enabling direct low-global-warming-potential system adoption. The Bureau of Indian Standards and DGFT administer chemical safety and trade regulations affecting import timelines. The Tamil Nadu and Maharashtra automotive corridors attract supplier investments for electrified platform thermal components.
Automotive Refrigerant Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with refrigerant blenders consolidating around direct OEM supply relationships while component integrators compete through thermal system architecture partnerships. Market structure tilts toward consolidated supply tiers in Europe and North America, with fragmented distributor networks bridging to independent service channels. Strategic archetypes include fluorochemical heritage blenders, compressor-integrated system suppliers, and specialized climate control module assemblers. Dominant competitive moves encompass capacity expansion for low-global-warming-potential formulations and strategic partnerships for CO2-compatible component ecosystems.
Among heritage fluorochemical blenders, Arkema and Honeywell International Inc. occupy positions anchoring European and North American direct supply relationships respectively. Daikin Industries Ltd. exemplifies the compressor-integrated system supplier archetype through its specialized positioning in Japanese OEM programs. These three entities represent distinct strategic postures: fluorochemical formulation scale, regional production anchoring, and vertical thermal system integration.
| Leading Market Players |
|---|
| Denso Corporation |
| Hanon Systems |
| Arkema |
| Honeywell International Inc. |
| MAHLE GmbH |
| AGC Inc. |
| Daikin Industries Ltd. |
| Hitachi Ltd. |
| The Chemours Company |
| Others |
Supply Flow & Price Mechanics
German OEM procurement consolidation around CO2-compatible thermal systems anchors contract-based long-term offtake pricing, compressing margin negotiation windows for refrigerant blenders serving legacy HFC retrofit channels.
Pricing Analysis
Volume capture concentrates in bulk OEM supply agreements with thin margins, while aftermarket services retain superior margin profiles through certification-gated service premiums. Three-tier pricing structure across premium, standard, and economy levels separates EPA Section 608-certified contractors from uncertified independents and DIY canister channels. Pricing pressure stems from fluorspar concentrate feedstock volatility concentrated in Chinese and Mexican supply zones. Fleet operators exhibit lowest price sensitivity due to bundled recovery-reclamation service contracts, whereas independent repair workshops face acute cost compression from CO2 equipment upgrade requirements.
Supply Chain Analysis
Fluorochemical feedstock supply rests on fluorspar mining concentration in China and Mexico, with hydrofluoroolefin precursor synthesis anchored in German and Japanese specialty chemical infrastructure. Critical inputs span refrigerant-grade fluorspar, unsaturated HFO intermediates, and compressor-compatible lubricant formulations. Single-source vulnerability runs through Chinese fluorspar concentrate exports subject to environmental compliance inspections. Distribution runs through direct OEM contracts for volume, regional wholesalers bridging to certified service networks, and specialized B2B platforms for technician-verified canister sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerant blenders and thermal system integrators are racing to secure backward integration into compressor-seal manufacturing and captive CO2 charging infrastructure, compressing the competitive window for pure-play formulation suppliers.
For Market Incumbents: Cement platform-standardization partnerships with German and Japanese OEMs before 2030 F-Gas quota tightening accelerates supplier consolidation. Secure captive supply agreements for fluorspar alternative feedstocks to offset Chinese export restriction exposure. Prioritize EPA Section 608 and EU F-Gas certification program ownership to lock aftermarket channel access against emerging service aggregators. For New Entrants and Emerging Players: Independent fleet operators in California and the Netherlands present the most penetrable buyer archetype, as these entities unbundle refrigerant management from dealership contracts and seek specialized recovery-reclamation providers. Target CO2-compatible equipment leasing models for repair workshops capital-constrained by 100-bar system upgrade requirements. Pursue technician certification partnerships as the primary go-to-market angle, embedding service capacity building into supply agreements. For Investors and Strategic Acquirers: The window for entry favors compressor-integrated system suppliers with demonstrated CO2 thermal loop validation, as OEM platform decisions are freezing out pure-play refrigerant blenders without component ecosystem partnerships. Acquisition targets should demonstrate heat pump-battery thermal integration capabilities and active German or Japanese OEM qualification programs. Watch EU F-Gas quota auction pricing as the inflection indicator for margin compression timing across HFC-dependent formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Arkema and Honeywell anchor European and North American captive component supply for CO2 systems. |
| CO2 Charging Infrastructure Deployment | Baden-Württemberg automotive cluster hosts dedicated technician certification and high-pressure charging networks. |
| Long-term OEM Platform Contracts | Multi-year thermal architecture agreements lock out competitors as battery-electric vehicle production scales. |
| Recovery-Reclamation Service Integration | EPA-certified contractors capture fleet maintenance contracts, marginalizing uncertified independent workshops. |
| Heat Pump Thermal Loop Convergence | Integration of cabin cooling with battery heating circuits consolidates supplier qualification timelines for premium OEMs. |
Methodological Framework
Multi-period observation of refrigerant charge size regulations, OEM thermal platform announcements, and F-Gas quota trading volumes anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and EPA-certified service technicians. Secondary validation drew from EPA Section 608 certification databases, EU F-Gas Regulation compliance filings, vehicle production databases, and customs trade records for fluorspar concentrate and HFO precursor movements. Bottom-up segment sizing triangulated against top-down market value reconstruction across chemistry, application, and end-user dimensions.
The input-output matrix framed refrigerant demand as a function of battery-electric vehicle production trajectories, thermal system architecture decisions, and regulatory phase-down schedules across the projection horizon. Segmentation dimensions modeled encompass chemistry type, vehicle propulsion architecture, OEM tier positioning, and regional regulatory cluster intensity. CAGRs were derived through logistic adoption curve fitting for CO2 system penetration and linear extrapolation for legacy HFC retrofit demand. Industry-specific forecast inputs included OEM platform thermal system announcements and F-Gas quota allocation auction outcomes.
Revisions become necessary when Kigali Amendment ratification timelines accelerate, fluorspar export restrictions materialize, or OEM thermal architecture standardization shifts abruptly between CO2 and hydrocarbon alternatives. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM platform decision timelines. A small set of named triggers warrants ongoing watch: EU F-Gas quota pricing volatility, Chinese environmental inspection intensity affecting fluorspar output, and German OEM CO2 system adoption rate deviations from announced platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
China Automotive Composites Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Automotive Metal Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Air Deflector Market