
 Automotive Air Deflector Market | 2026-2036
Automotive Air Deflector Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Deflector Market Analysis
Aftermarket service revenue is tilting toward OEM-integrated aerodynamic packages as vehicle manufacturers bundle deflectors into trim configurations. Robert Bosch GmbH leverages its electronics and sensor fusion expertise to embed smart actuation into deflector systems. Magna International Inc. sustains manufacturing scale across North American and European assembly corridors. Plastic Omnium dominates thermoplastic exterior module supply, extending its bumper-and-deflector integration capabilities into platform-shared architectures.
An automotive air deflector is a body-mounted aerodynamic device, typically molded from polycarbonate, ABS, or polypropylene blends, designed to redirect airflow around the vehicle cabin or cargo area to reduce drag coefficient and wind noise. Front deflectors and roof deflectors lead volume as OEMs prioritize highway fuel efficiency on SUVs and trucks, while side deflectors represent the fastest-growing product category due to aftermarket customization demand. Material selection stratifies around polycarbonate for optical clarity in window-channel applications versus polypropylene for cost-driven universal-fit aftermarket units.
The EPA enforces Corporate Average Fuel Economy standards that effectively mandate aerodynamic optimization across light-truck and SUV fleets, while NHTSA Federal Motor Vehicle Safety Standards govern protrusion limits and impact performance of exterior accessories. ECE Regulation 26 in Europe and China's GB standards for motor vehicle external projections similarly constrain deflector geometry and mounting integrity. Stakeholders must monitor how evolving fuel-economy enforcement thresholds and cross-border type-approval reciprocity reshape sourcing decisions between integrated OEM supply and aftermarket retrofit channels.
Market Dynamics
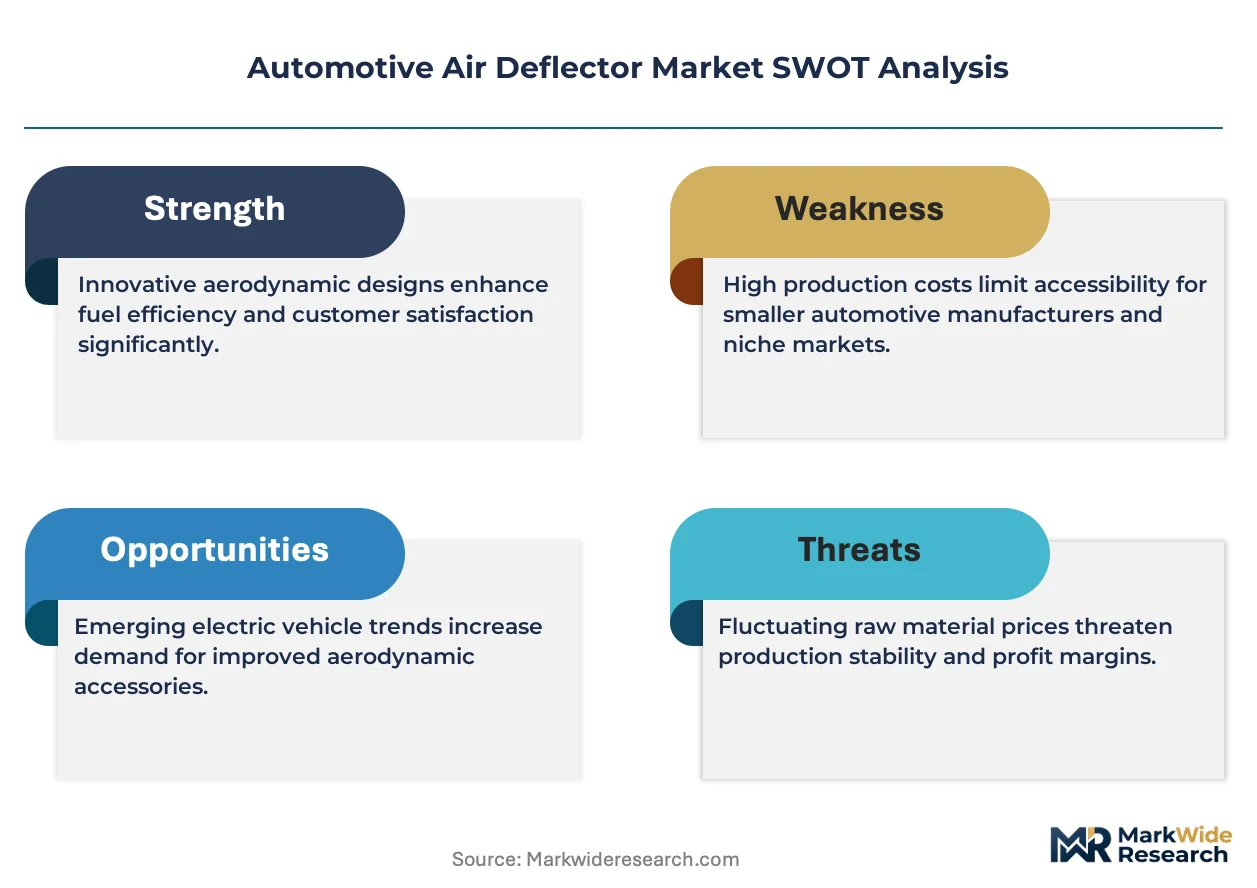
Factory integration of aerodynamic modules is compressing aftermarket channels as OEMs bundle deflectors into trim packages, forcing suppliers to choose between captive supply relationships or independent retail positioning.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Light-truck fleet mandates compel Detroit automakers to install front and roof deflectors as standard equipment on SUVs and pickups.
- Commercial fleet procurement:Highway freight operators in the United States prioritize aerodynamic add-ons to reduce diesel consumption across long-haul routes.
- Polycarbonate optical clarity:Window-channel deflector applications demand this material for driver visibility compliance, expanding OEM specification sheets.
Market Restraints
- Petrochemical input volatility:ABS and polypropylene resin prices fluctuate with crude oil benchmarks, squeezing margin stability for thermoplastic molders.
- Supplier concentration in Germany:Tooling and injection-molding expertise clusters around Stuttgart and Munich corridors, creating geographic supply risk.
- ECE Regulation 26 protrusion limits:European external projection standards constrain deflector geometry, adding engineering validation costs.
Strategic Opportunities
- China's GB standards evolution:Tightening motor vehicle external projection rules create compliance-driven replacement demand for domestic OEMs.
- Smart actuation convergence:Sensor fusion with adjustable deflector angles opens premium tier pricing for highway adaptive aerodynamics.
- Aftermarket e-commerce channels:Direct-to-consumer platforms bypass traditional auto parts distributors, capturing customization demand for side deflectors.
Industry Challenges
- Cross-border type-approval reciprocity gaps:Divergent EPA, ECE, and GB certification timelines delay platform-shared vehicle launches.
- CAE simulation talent scarcity:Computational fluid dynamics expertise for aerodynamic validation commands premium wages, constraining mid-tier supplier expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Deflector Market |
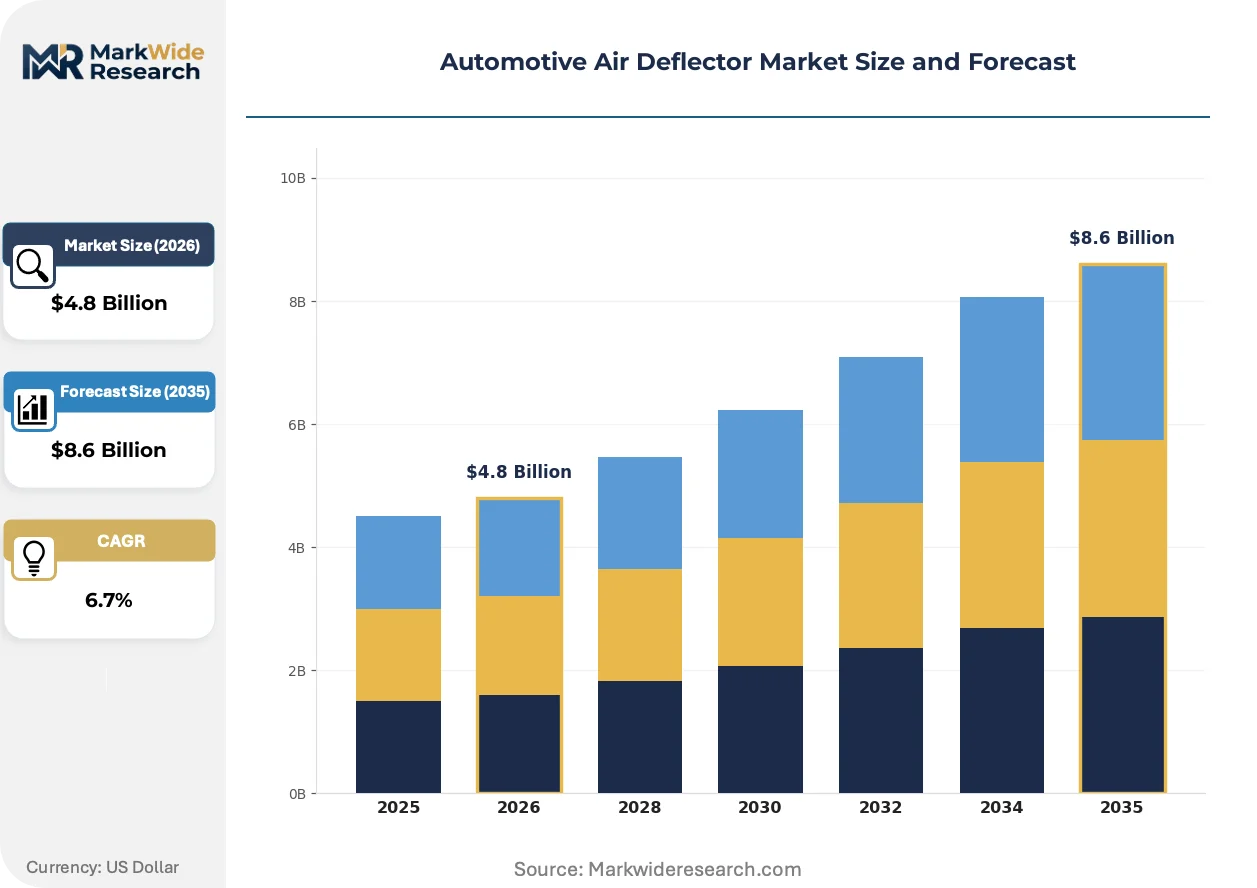
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Deflectors, Side Deflectors, Rear Deflectors, Roof Deflectors Material: Polycarbonate, Acrylic, ABS, Polypropylene Vehicle Type: Passenger Cars, SUVs, Trucks, Vans Installation Type: OEM, Aftermarket, Custom Fit, Universal Fit |
| Companies Covered | Robert Bosch GmbH, Magna International Inc., Lund International, Stampede Automotive Accessories, Climair UK Ltd, AVS (Auto Ventshade), Plastic Omnium, EGR, WeatherTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Deflector Market Emerging Trajectories
Active aerodynamics is virtualizing static component boundaries as deflectors gain motorized adjustment, sensor feedback loops, and integration with vehicle dynamics controllers.
Computational fluid dynamics simulation is virtualizing physical wind-tunnel testing for deflector design validation. Tier 1 suppliers now run digital airflow models before cutting prototype tooling. This compression of development cycles is virtualizing the traditional 18-month design-to-production timeline into 8-month sprints.
China's GB standards for motor vehicle external projections are tightening protrusion tolerances and mounting integrity requirements. Domestic OEMs must redesign deflector attachment points to satisfy updated compliance protocols. The passenger car segment bears the heaviest re-engineering burden as platforms migrate to shared global architectures.
Fleet procurement teams now specify total cost of ownership metrics rather than unit price in aerodynamic package tenders. Large commercial operators in the United States negotiate fuel-savings guarantees from deflector suppliers, displacing traditional parts-catalog relationships. This performance-contracting shift concentrates buying power among national fleet managers and marginalizes regional distributors.
Automotive Air Deflector Market Segmentation
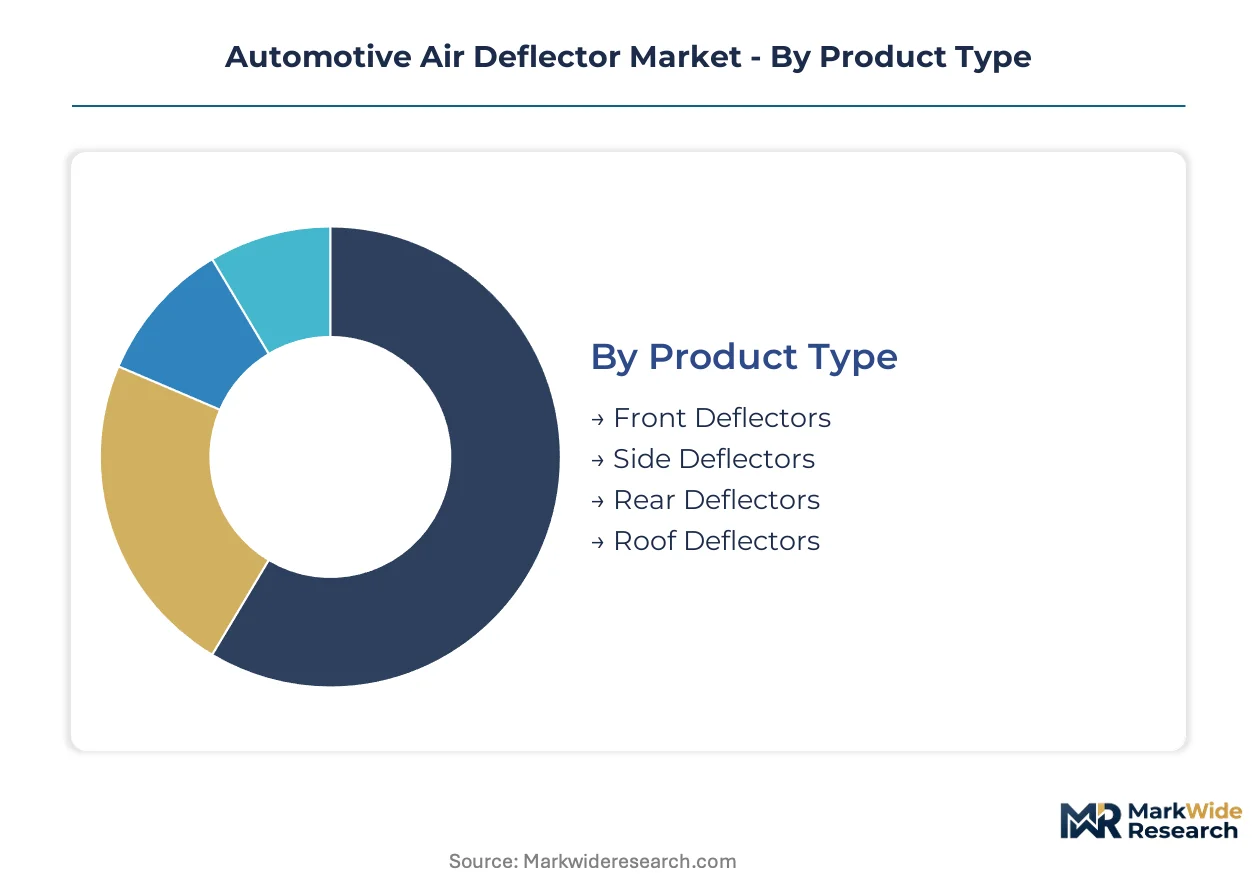
Automotive air deflector segmentation reflects divergent engineering priorities across aerodynamic performance, material economics, and channel strategy. Each dimension captures distinct margin structures and regulatory exposure that shape supplier positioning.
Product Type:
Mature highway-efficiency applications coexist with emerging customization segments across the aerodynamic add-on portfolio.
- Front Deflectors:Molded polycarbonate or ABS assemblies mount at the hood leading edge to redirect airflow over the windshield and reduce bug accumulation. OEM specification concentrates in Detroit's light-truck platforms where EPA fuel-economy mandates compel factory installation.
- Roof Deflectors:Cab-mounted spoilers on commercial trucks and SUVs manage airflow across cargo boxes or roof racks to cut drag coefficient at highway speeds. Fleet procurement in the United States drives specification for long-haul diesel efficiency.
- Side Deflectors:Window-channel units channel airflow past open windows to reduce cabin buffeting.
- Rear Deflectors:Tailgate or trunk-lid spoilers manage rear airflow separation on performance variants.
Front deflectors retain volume leadership; side deflectors hold the steepest expansion curve.
Material:
Cost tiers stratify around optical performance requirements versus commodity resin economics.
- Polycarbonate:High-impact thermoplastic with optical clarity for window-channel applications where driver visibility compliance is mandatory. OEM specification in Germany and the United States favors this material for integrated exterior modules despite premium pricing.
- Polypropylene:Low-density commodity resin dominates universal-fit aftermarket units where cost minimization overrides performance metrics. Injection molders in China's Yangtze River Delta exploit scale economies for export production.
- Acrylic:UV-resistant alternative for transparent deflector segments with moderate impact requirements.
- ABS:Balanced stiffness and processability for painted body-color applications on premium trim packages.
Polycarbonate commands the premium tier; polypropylene captures the highest shipment volumes.
Vehicle Type:
Application intensity varies sharply between consumer light trucks and commercial freight platforms.
- Trucks:Class 3-8 commercial vehicles carry the highest deflector penetration rates as fleet operators quantify fuel savings across million-mile duty cycles. United States highway freight corridors sustain replacement demand for damaged or upgraded aerodynamic packages.
- SUVs:Consumer light trucks integrate front and roof deflectors as trim-level differentiators, with OEM bundling accelerating factory-fit adoption over aftermarket retrofit.
- Passenger Cars:Sedan and hatchback applications concentrate in performance subsegments where rear spoilers carry styling rather than efficiency priority.
- Vans:Commercial and passenger van segments adopt side deflectors for cabin ventilation and roof units for cargo box aerodynamics.
Trucks sustain the highest unit economics; SUVs are expanding most quickly through OEM bundling.
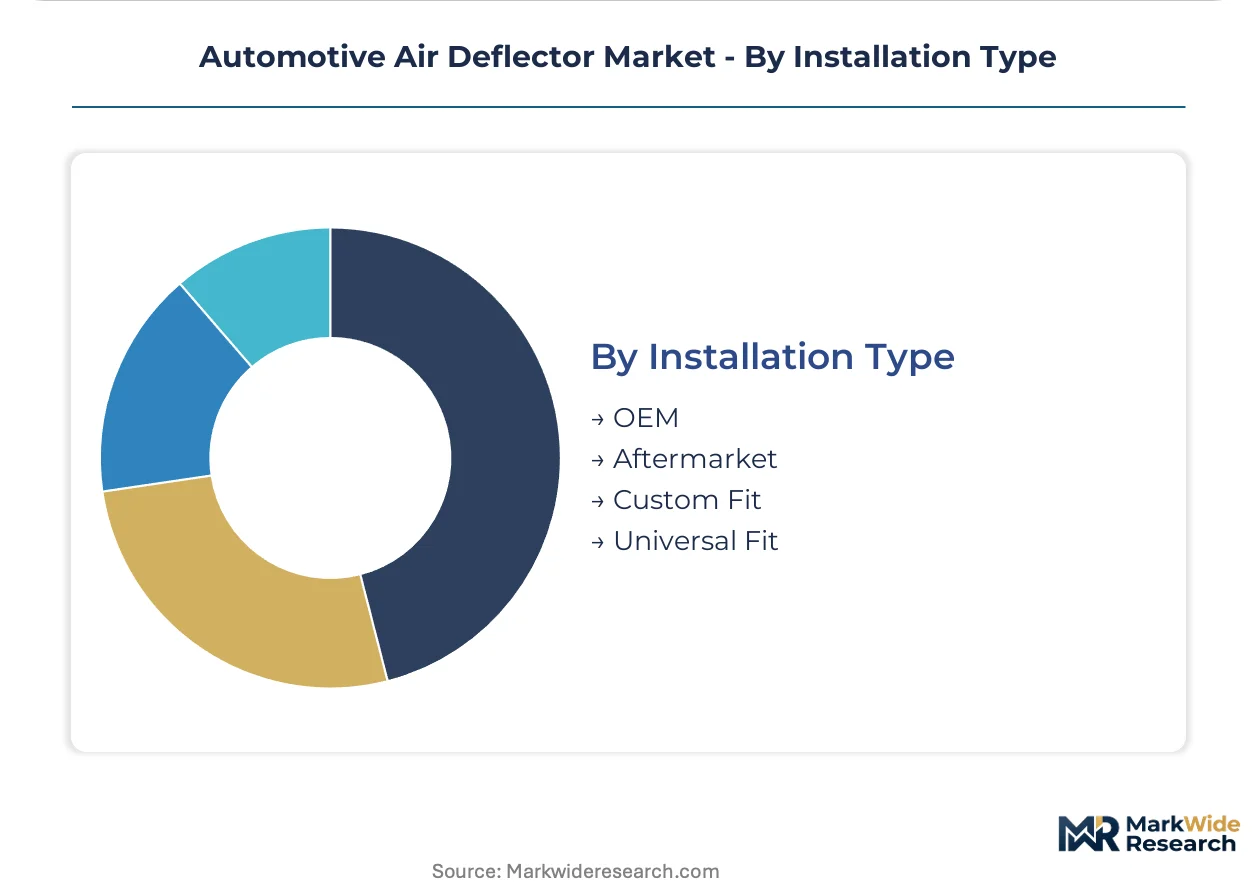
Installation Type:
Channel conflict intensifies as factory integration displaces traditional aftermarket relationships.
- OEM:Factory-integrated aerodynamic modules bundled into trim configurations capture margin premiums and lock in supplier relationships. Magna International and Plastic Omnium leverage platform-shared architectures to supply Detroit and Stuttgart assembly corridors.
- Aftermarket:Independent retail channels face compression as OEM bundling reduces addressable market, though e-commerce platforms sustain side deflector customization demand.
- Custom Fit:Vehicle-specific tooling for model-year exact matching commands price premiums over universal alternatives.
- Universal Fit:Clip-on or adhesive-mounted units target price-sensitive consumers with flexible geometry adaptation.
OEM integration is gaining share fastest; aftermarket retains residual customization volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators in the United States exhibit the lowest price elasticity, accepting factory-integrated aerodynamic packages that capture lifetime fuel savings, while price-sensitive aftermarket consumers in emerging markets drive commoditization of universal-fit polypropylene units.
United States
Class 8 freight carriers operating along I-80 and I-95 corridors mandate aerodynamic packages as standard procurement terms. EPA Corporate Average Fuel Economy standards compel Detroit automakers to install front deflectors on light-truck platforms. Manufacturing concentrates in Michigan and Ohio assembly corridors where Magna International maintains captive supply relationships.
Germany
Premium OEMs in Stuttgart and Munich specify polycarbonate deflectors for optical clarity compliance in window-channel applications. ECE Regulation 26 protrusion limits constrain geometry validation, adding engineering overhead for export-bound platforms. Tooling expertise clusters around Baden-Württemberg injection-molding corridors serving both domestic assembly and tier supply.
China
Domestic OEMs face redesign pressure as GB standards for motor vehicle external projections tighten mounting integrity requirements. Highway freight volumes along Beijing-Shanghai and Beijing-Guangzhou corridors sustain replacement demand for commercial aerodynamic packages. Yangtze River Delta molders exploit scale economies for polypropylene aftermarket export production.
Japan
Keiretsu-affiliated suppliers integrate deflectors into platform-shared architectures for domestic and Southeast Asian export markets. METI fuel-efficiency guidelines shape OEM specification sheets for kei-car and light-truck segments. Chubu region manufacturing corridors around Nagoya concentrate thermoplastic exterior module production.
India
Commercial vehicle operators on Golden Quadrilateral highway routes adopt roof deflectors to cut diesel consumption across long-haul duty cycles. BIS certification requirements for automotive exterior accessories create compliance barriers for unorganized aftermarket suppliers. Tamil Nadu and Maharashtra assembly corridors attract tier-1 deflector integration for SUV platforms.
Automotive Air Deflector Market Vendor Landscape
Full-system integrators and specialized component suppliers split the market between captive OEM relationships and independent aftermarket channels. Consolidation pressure intensifies as factory bundling reduces addressable aftermarket volume. Two strategic archetypes dominate: tier-1 automotive suppliers leveraging platform-shared architectures, and niche accessory specialists capturing customization demand. Competitive moves center on backward integration into resin compounding and geographic expansion through regional distribution partnerships.
Within the tier-1 integrator tier, Robert Bosch GmbH and Magna International Inc. exemplify scale-driven platform supply, while Lund International occupies a position among aftermarket-focused specialists. German-origin entities anchor European regulatory compliance capabilities, whereas North American-based fabricators concentrate fleet procurement relationships. Plastic Omnium represents thermoplastic module integration archetypes serving shared global vehicle architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Magna International Inc. |
| Lund International |
| Stampede Automotive Accessories |
| Climair UK Ltd |
| AVS (Auto Ventshade) |
| Plastic Omnium |
| EGR |
| WeatherTech |
| Others |
Supply Flow & Price Mechanics
Petrochemical input volatility in ABS and polypropylene resin markets compresses margin stability for thermoplastic molders while simultaneously widening pricing tier spreads between optical-grade polycarbonate specifications and commodity aftermarket units. This raw material uncertainty forces suppliers to index contract pricing to crude oil benchmarks and concentrate sourcing relationships around integrated resin compounders with captive feedstock access.
Pricing Analysis
Aftermarket service revenue from extended warranty and replacement cycles drives lifetime value capture for deflector suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies around material certification and optical clarity grades. Cost compression in polypropylene universal-fit segments is intensifying because Yangtze River Delta molders exploit export scale economies. Fleet procurement teams exhibit the lowest price sensitivity, accepting factory-integrated aerodynamic packages with fuel-savings guarantees, while independent retail consumers in emerging markets drive commoditization of clip-on aftermarket units.
Supply Chain Analysis
Contract manufacturing concentration rests with Magna International and Plastic Omnium for platform-shared OEM architectures, alongside specialized injection molders in China's Yangtze River Delta for aftermarket export production. Geographic supply concentration clusters in Germany, China, and the United States. Raw material dependencies draw from polycarbonate resin, polypropylene compounds, and ABS pellets. Single-source vulnerability concentrates around Stuttgart and Munich tooling corridors for precision injection-molding expertise. Distribution runs through captive OEM supply relationships for factory-integrated units and direct-to-consumer e-commerce platforms for aftermarket customization demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from active aerodynamics systems that displace static deflectors with sensor-fusion-enabled adjustable geometries, requiring defensive positioning around smart actuation capabilities.
For Market Incumbents: Pre-empt displacement by smart aerodynamics through backward integration into sensor fusion and motorized actuation technologies. Lock in captive supply relationships with Detroit and Stuttgart OEMs by embedding deflectors into platform-shared architectures. Certify products under evolving GB standards ahead of Chinese regulatory tightening to defend position against domestic competitors.
For New Entrants and Emerging Players: India's Golden Quadrilateral commercial corridor offers underpenetrated fleet procurement relationships for roof deflector specification. Target side deflector customization demand through direct-to-consumer e-commerce channels in price-sensitive emerging markets. Pursue vehicle-specific tooling partnerships with regional aftermarket distributors to bypass established catalog relationships.
For Investors and Strategic Acquirers: EPA Corporate Average Fuel Economy standard tightening reshapes the acquisition landscape toward suppliers with OEM-integrated platform contracts. Prioritize targets with computational fluid dynamics capabilities and polycarbonate optical-grade certification. Monitor NHTSA safety mandate evolution as the signal indicating factory integration acceleration versus aftermarket channel viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Actuation Integration | Sensor fusion with adjustable deflector angles opens premium tier pricing for highway adaptive aerodynamics. |
| Platform Standardization | Shared global vehicle architectures enable Magna International and Plastic Omnium to supply Detroit and Stuttgart corridors. |
| Regulatory Pre-Certification | Early GB standards compliance in China creates compliance-driven replacement demand for domestic OEMs. |
| Direct-to-Consumer Channel | E-commerce platforms bypass traditional auto parts distributors, capturing customization demand for side deflectors. |
| Computational Fluid Dynamics Investment | Virtual design validation compresses development cycles from traditional timelines into accelerated sprints. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet procurement managers; and secondary validation through vehicle production databases, IHS Markit registration data, EPA fuel-economy compliance filings, and customs trade records. Bottom-up segmentation modeling triangulated against top-down market sizing from industry association disclosures.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the analysis window. CAGRs derive from regression analysis against historical penetration rates and regulatory mandate trajectories. Industry-specific inputs include commercial fleet mileage accumulation patterns and polycarbonate resin price index movements.
Practitioners should monitor crude oil benchmark volatility, GB standards implementation timelines, and smart aerodynamics patent filings for early signals of forecast revision. Quarterly review of EPA enforcement thresholds and fleet procurement contract structures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Engine Connecting Rods Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Pedals Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Automotive Retarders Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Automotive Wiper Blades Market