
 Europe Automotive Pneumatic Actuators Market | 2026-2036
Europe Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Pneumatic Actuators Market Foresight
Eastern European manufacturing zones are reconfiguring supplier ecosystems as Slovakia and the Czech Republic add pneumatic component capacity for German OEM supply chains. Robert Bosch GmbH leverages its Stuttgart engineering base to sustain integrated actuator-valve development. Continental AG anchors large-volume contracts through its Regensburg facility's proximity to BMW and Audi assembly plants. Denso Corporation competes via specialized thermal management actuators that address engine downsizing requirements.
Europe automotive pneumatic actuators are electromechanical-pneumatic hybrid devices that convert compressed air energy into linear or rotary mechanical motion, typically operating at pressures between 4 and 10 bar to control engine intake, exhaust, braking, and suspension functions. Their primary purpose is delivering rapid response, high force-to-weight actuation in powertrain and chassis systems where electrical alternatives face thermal or electromagnetic constraints. Brake system applications generate the most stable margin pools due to safety-critical certification requirements, while transmission actuators represent the fastest structural expansion as dual-clutch and automated manual architectures proliferate across passenger cars and commercial vehicles. Actuating cylinders dominate component value given their material intensity and precision machining requirements.
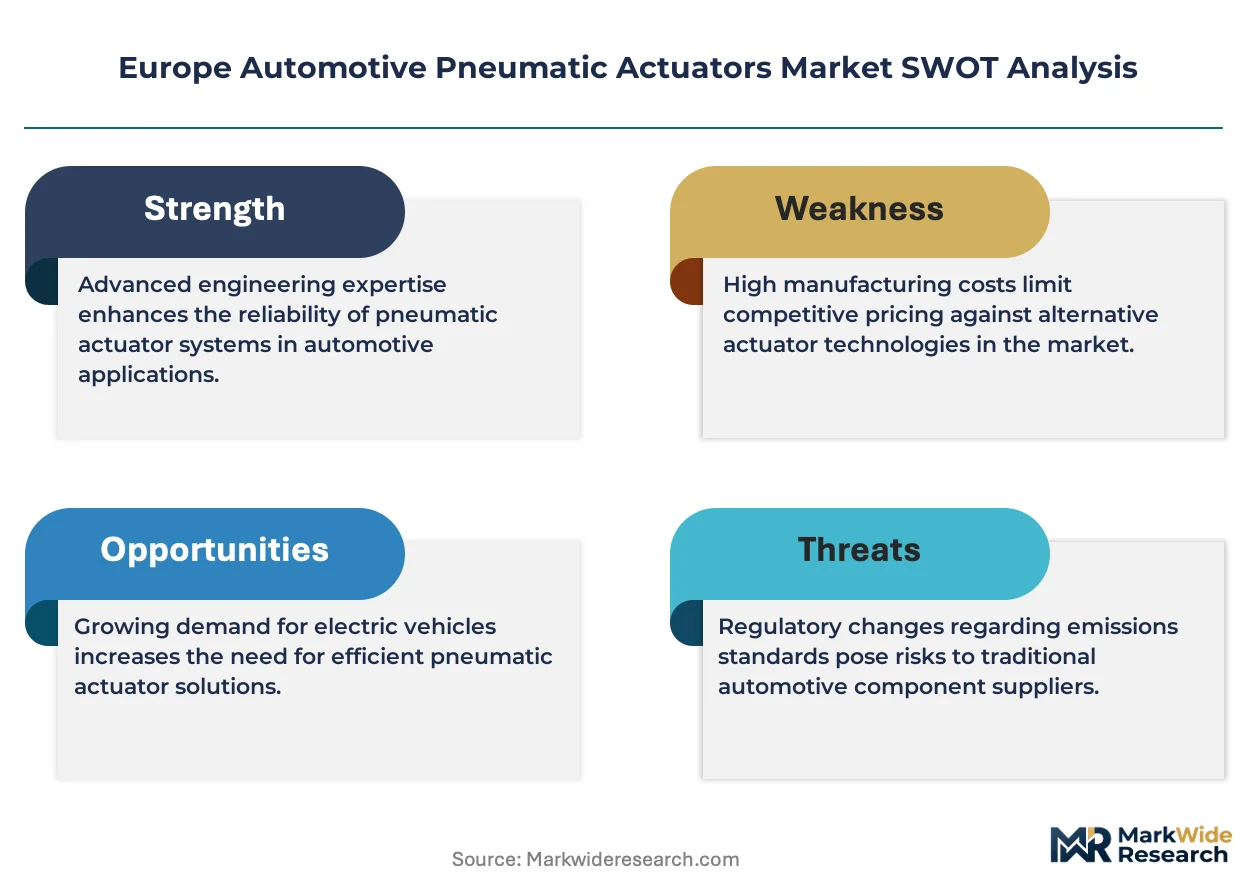
EMA's MDR framework and the EU F-Gas Regulation shape pneumatic actuator design by restricting fluorinated greenhouse gases in sealing technologies and mandating extended service-life documentation. REACH compliance adds material traceability burdens that favor established suppliers with dedicated chemical management systems. Stakeholders must monitor how the EU AI Act's risk classification protocols affect smart actuator architectures with embedded position sensing and predictive diagnostics.
Market Dynamics
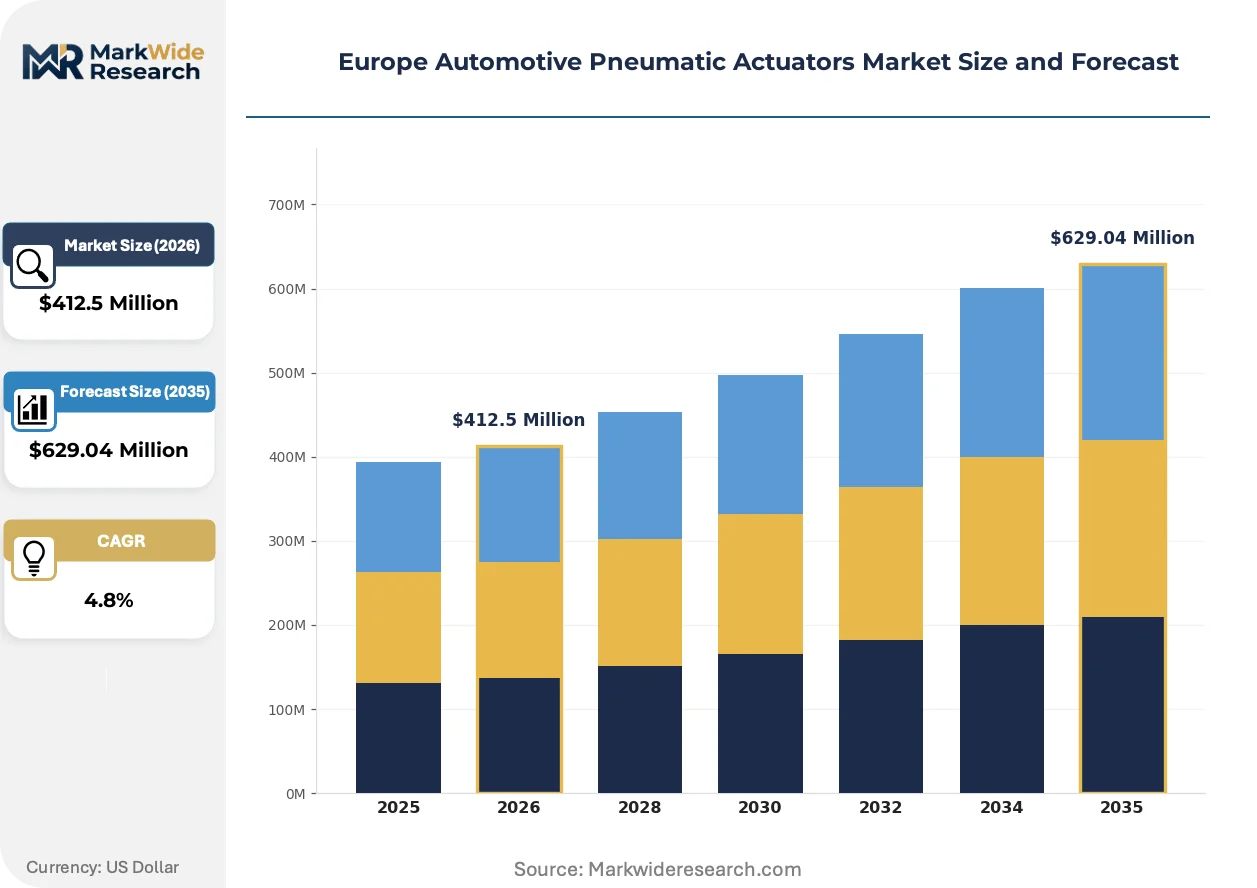
EU Green Deal emissions benchmarks are forcing pneumatic actuator suppliers to redesign architectures for lower compressed-air energy consumption, while dual-clutch transmission proliferation across German and French commercial fleets pulls demand toward higher-precision linear actuation systems.
Growth Catalysts
- Automated manual transmission architectures:Commercial vehicle fleets across Germany and France are expanding actuator procurement for gear-shifting automation, creating sustained demand for high-cycle pneumatic cylinders.
- REACH compliance infrastructure:Material traceability mandates favor established suppliers with dedicated chemical management systems, consolidating procurement toward certified vendors with documented supply chains.
- Brake system safety certification:Safety-critical certification requirements for pneumatic brake actuators generate stable margin pools and long-term supplier relationships resistant to price competition.
Market Restraints
- Aluminum and specialty steel input volatility:Precision-machined cylinder bodies depend on aluminum alloy and stainless steel feedstocks subject to energy-cost-driven price swings.
- Eastern European supplier concentration:Slovakia and Czech Republic manufacturing zones concentrate component capacity, creating single-source vulnerability for German OEM supply chains.
- Electromechanical substitution in thermal management:Engine downsizing trends enable electric actuator alternatives to displace pneumatic solutions in certain HVAC and cooling applications.
Strategic Opportunities
- Polish and Romanian manufacturing corridors:Underdeveloped pneumatic component capacity in these markets offers first-mover advantages for suppliers establishing EU Green Deal-compliant production.
- Predictive diagnostics integration:Embedded position sensing and edge computing convergence enables smart actuator architectures with condition-based maintenance capabilities.
- EU AI Act risk classification protocols:Regulatory frameworks for automated systems create certification-based differentiation for actuators with integrated diagnostic intelligence.
Industry Challenges
- Precision machining talent scarcity:Cylinder bore tolerances below 10 microns require specialized tool-and-die skills concentrated in Stuttgart and Munich engineering clusters.
- EMA MDR documentation timelines:Extended service-life documentation mandates for sealing technologies extend product validation cycles and compress launch windows.
- F-Gas Regulation sealing requalification:Fluorinated greenhouse gas restrictions force redesign of elastomer seals with uncertain compatibility matrices for legacy actuator fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Pneumatic Actuators Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Actuating Cylinders, Valves, Compressors, Hoses Application: Engine Control, Brake Systems, Suspension, Transmission Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, SUVs Technology: Electromechanical, Pneumatic, Hydraulic, Hybrid |
| Companies Covered | Delphi Automotive PLC, ASCO Valve Inc, Denso Corporation, Numatics Inc, Schrader Duncan Limited, Robert Bosch GmbH, Hitachi Ltd, CTS Corporation, Continental AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Pneumatic Actuators Market Shifts & Advancements
Pneumatic actuator architectures are converging with digital sensing and predictive analytics, compressing the traditional electromechanical-pneumatic boundary while regulatory frameworks reshape material and documentation requirements across European supply chains.
Smart actuator systems with embedded Hall-effect position sensors and edge-computing diagnostics are digitizing maintenance workflows across German commercial vehicle fleets. Fleet operators in Bavaria and Baden-Württemberg are piloting these architectures for predictive brake wear monitoring. The technology is digitizing service contract structures from scheduled replacement toward condition-based intervention models.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon-based sealing compounds is forcing elastomer reformulation across pneumatic cylinder production. Continental AG and Robert Bosch GmbH are accelerating fluorosilicone and hydrogenated nitrile butadiene rubber qualification programs. Brake system applications face the steepest compliance curves given safety-critical requalification requirements under EMA's MDR framework.
Long-term service contracts bundling hardware, compressed-air infrastructure, and predictive maintenance are displacing transactional component sales among French logistics operators. Tier-1 suppliers are capturing multi-year commitments spanning actuator replacement cycles. The shift is most visible in Paris and Lyon distribution hubs where fleet standardization programs concentrate procurement authority.
Europe Automotive Pneumatic Actuators Market Segmentation
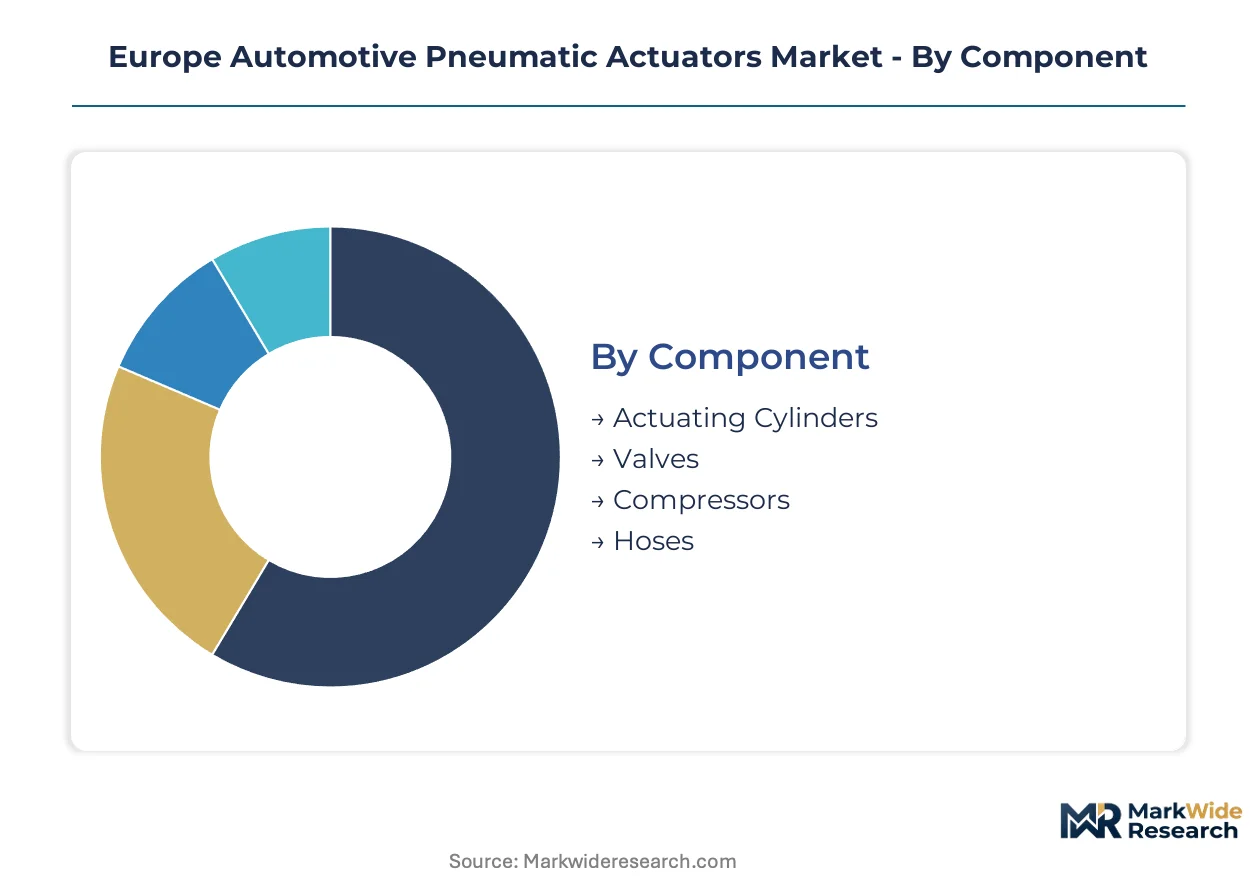
Pneumatic actuator procurement patterns diverge sharply across component hierarchies and vehicle architectures. Suppliers must align capacity with brake system safety certifications while capturing transmission automation growth in German and French commercial fleets.
Component:
Mature machining-intensive segments dominate value capture, while emerging smart component categories reshape service contract structures.
- Actuating Cylinders:Precision-machined aluminum and stainless steel bodies with bore tolerances below 10 microns convert compressed air into linear mechanical force. German OEMs in Stuttgart and Wolfsburg specify these for brake and transmission applications where cycle life exceeds 10 million operations.
- Valves:Directional and proportional control valves regulate airflow pressure between 4 and 10 bar across engine intake and exhaust systems. French commercial vehicle manufacturers in Lyon prioritize fast-switching solenoid-pneumatic hybrids for automated manual transmissions.
- Compressors:Belt-driven and electric auxiliary units generate system pressure for centralized pneumatic architectures. Slovakian suppliers serving BMW and Audi assembly lines concentrate volume production of compact variable-displacement designs.
- Hoses:Reinforced elastomer and thermoplastic conduits deliver compressed air with F-Gas Regulation-compliant sealing interfaces. Czech Republic manufacturing zones export braided hose assemblies to German tier-1 integrators.
Actuating cylinders handle the majority of throughput; valves are the fastest mover on share.
Application:
Cost tier stratification separates safety-critical systems from performance-optimizing functions.
- Brake Systems:Pneumatic brake actuators deliver emergency stopping force in commercial vehicles through spring-applied, air-released mechanisms. EMA MDR documentation mandates and extended service-life validation create margin stability for certified suppliers.
- Transmission:Dual-clutch and automated manual architectures deploy linear pneumatic cylinders for clutch engagement and gear selection. German fleet operators in Bavaria are standardizing predictive diagnostic actuators for condition-based maintenance contracts.
- Engine Control:Variable valve timing and turbocharger wastegate actuators optimize combustion efficiency under EU Green Deal emissions benchmarks. Downsizing trends enable partial electromechanical substitution in thermal management zones.
- Suspension:Air spring and damping control actuators adjust ride height and stiffness in luxury passenger vehicles. Polish and Romanian logistics corridors show emerging demand for heavy-duty variants.
Brake systems anchor supplier margins through certification barriers; transmission applications are expanding most quickly as automation proliferates.
Vehicle Type:
Volume concentration versus margin structure shapes supplier portfolio priorities.
- Commercial Vehicles:Heavy-duty trucks and buses specify high-cycle pneumatic actuators for brake, transmission, and suspension functions. German and French fleet standardization programs concentrate procurement authority through long-term service contracts.
- Passenger Cars:Compact and mid-size segments balance cost pressure with dual-clutch transmission adoption. Continental AG's Regensburg facility captures volume through proximity to BMW and Audi assembly plants.
- SUVs:Higher-margin all-terrain applications demand robust suspension actuators with extended temperature ranges. Robert Bosch GmbH leverages Stuttgart engineering for integrated actuator-valve development.
- Motorcycles:Lightweight pneumatic solutions address clutch and braking in premium touring and adventure segments. Eastern European suppliers are underdeveloped in this niche.
Commercial vehicles generate the steepest expansion trajectory; passenger cars maintain volume concentration.
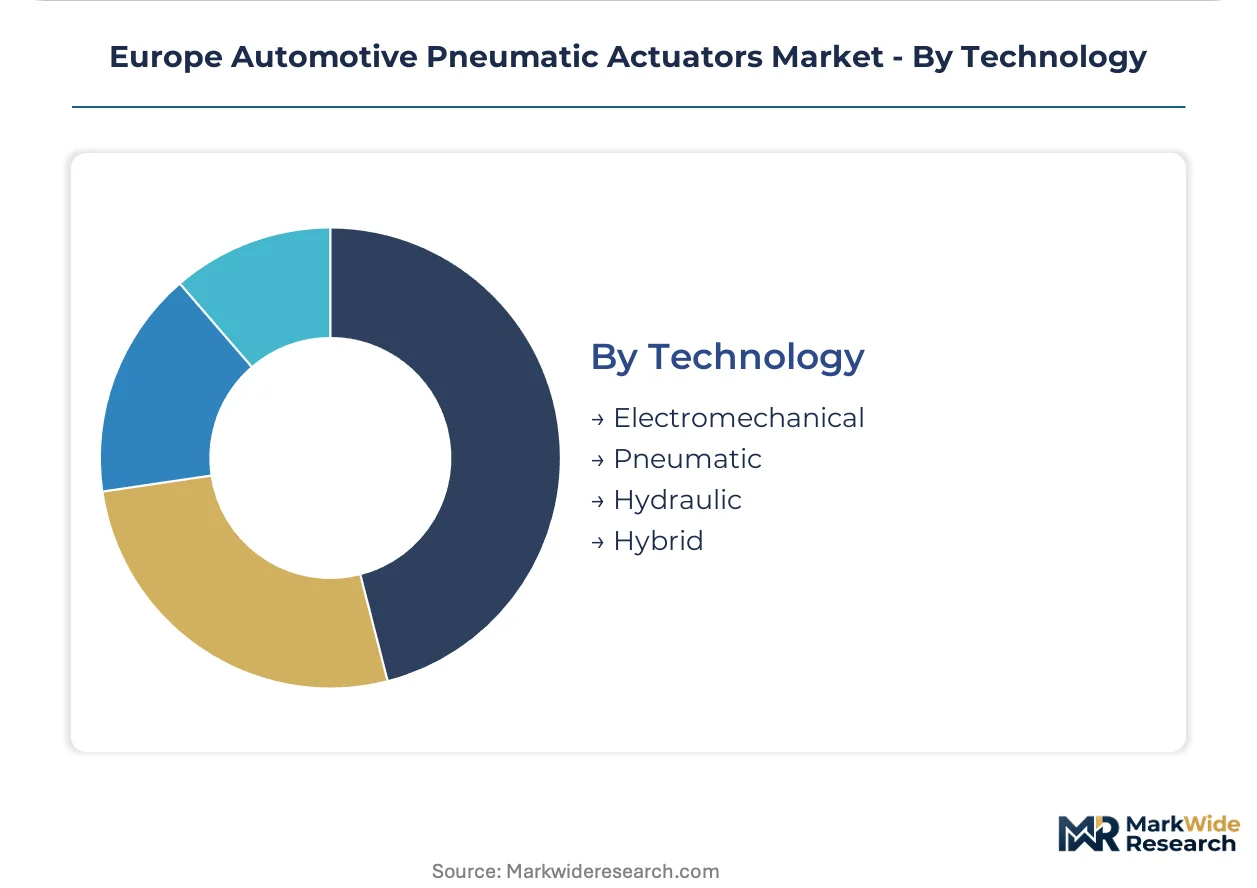
Technology:
Supply concentration in electromechanical-pneumatic boundaries determines competitive positioning.
- Hybrid:Electromechanical-pneumatic systems combine compressed air power with electronic position sensing and edge-computing diagnostics. EU AI Act risk classification protocols create certification-based differentiation for smart architectures.
- Pneumatic:Pure compressed air systems dominate brake safety applications where thermal and electromagnetic constraints exclude electrical alternatives. REACH compliance favors established suppliers with dedicated chemical management systems.
- Electromechanical:Electric motor-driven actuators displace pneumatic solutions in certain HVAC and cooling applications under engine downsizing pressure. Thermal management segments show fastest substitution rates.
- Hydraulic:Fluid power systems retain niche applications in high-force chassis functions where pneumatic force density proves insufficient. Czech and Slovak manufacturing zones lack comparable capacity.
Hybrid architectures are gaining share fastest; pure pneumatic systems retain safety-critical dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters concentrate actuator development capacity, while Eastern European manufacturing zones expand component supply for OEM integration. The EU Green Deal's emissions benchmarks and REACH compliance frameworks are redrawing procurement geography across the continent.
Germany
Automated transmission demand from Bavarian and Baden-Württemberg commercial fleets pulls precision actuator procurement toward Stuttgart and Munich engineering corridors. The EU F-Gas Regulation forces elastomer seal redesigns across cylinder production lines. Robert Bosch GmbH anchors integrated actuator-valve development from its Stuttgart base, while Continental AG's Regensburg facility captures volume through BMW and Audi assembly plant proximity.
France
Paris and Lyon logistics hubs standardize fleet procurement through multi-year service contracts bundling hardware and predictive maintenance. The EU AI Act's risk classification protocols shape certification requirements for smart actuator architectures with embedded diagnostics. Auvergne-Rhône-Alpes manufacturing zones supply fast-switching solenoid-pneumatic valve hybrids for automated manual transmission programs.
Slovakia
BMW and Audi supply chain integration drives pneumatic component capacity expansion in Bratislava-region manufacturing zones. REACH compliance documentation mandates favor established suppliers with dedicated chemical management infrastructure. Component producers cluster near final assembly plants to compress logistics lead times for just-in-sequence delivery.
Czech Republic
Braided hose assembly exports to German tier-1 integrators concentrate capacity in Moravian manufacturing zones. EMA MDR framework documentation timelines extend product validation cycles for sealing technologies. The country's supplier ecosystem reconfigures around EU Green Deal energy consumption benchmarks for compressed-air systems.
Poland
Underdeveloped pneumatic component capacity creates first-mover positioning for EU Green Deal-compliant production establishment. Polish logistics corridors show emerging demand for heavy-duty suspension actuators in commercial vehicle applications. Warsaw-region industrial zones attract supplier investment targeting German OEM supply chain diversification.
Europe Automotive Pneumatic Actuators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream machining precision cylinder bodies. The supplier base organizes around three archetypes: Stuttgart-engineered integrated system houses, Regensburg-proximate volume contract anchors, and Eastern European component exporters. Consolidation pressure runs through REACH compliance infrastructure requirements and EMA MDR documentation capabilities. Competitive moves center on predictive diagnostics integration and long-term service contract capture.
Among diversified automotive suppliers, Robert Bosch GmbH and Continental AG exemplify platform integration archetypes with German engineering heritage, while Denso Corporation represents specialized thermal management positioning. These three anchors illustrate the competitive spectrum from integrated system development to segment-specific actuator design. Their geographic distribution across Stuttgart, Regensburg, and Japanese engineering bases reflects the market's multinational supply architecture.
| Leading Market Players |
|---|
| Delphi Automotive PLC |
| ASCO Valve Inc |
| Denso Corporation |
| Numatics Inc |
| Schrader Duncan Limited |
| Robert Bosch GmbH |
| Hitachi Ltd |
| CTS Corporation |
| Continental AG |
| Others |
Supply & Pricing Matrix
Stuttgart's precision machining clusters concentrate actuator cylinder production capacity, concentrating pricing power among incumbent suppliers with dedicated REACH compliance infrastructure and EMA MDR documentation capabilities. German OEM procurement offices in Wolfsburg and Munich leverage this supply concentration to negotiate multi-year service contracts that bundle hardware, compressed-air infrastructure, and predictive maintenance.
Pricing Analysis
EMA MDR documentation mandates dictate the pricing tier structure across brake system applications, where safety-critical certification requirements separate premium suppliers with validated sealing technologies from standard-tier competitors. Price differentiation hinges on certification grade and volume scale, with German fleet operators showing lowest price sensitivity for brake actuators and Eastern European logistics buyers driving hardest bargains on transmission components. Cost compression in standard-tier cylinders is intensifying because aluminum alloy feedstock volatility feeds through precision-machined body costs.
Supply Chain Analysis
Continental AG's Regensburg facility and Robert Bosch GmbH's Stuttgart engineering base anchor contract-manufacturing concentration for integrated actuator-valve systems. Component supply draws from Germany, Slovakia, and the Czech Republic, with precision-machined aluminum bodies, fluorosilicone seals, and braided hose assemblies as critical inputs. Single-source vulnerability in Eastern European manufacturing zones creates structural risk for German OEM supply chains. Distribution runs through tier-1 integrators delivering just-in-sequence to BMW and Audi assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe automotive pneumatic actuators are crossing into platform-economics territory as predictive diagnostics integration creates service-contract ecosystems that lock in multi-year customer relationships and reshape competitive boundaries around data interoperability.
For Market Incumbents: Build regulatory documentation moats by deepening EMA MDR validation capabilities and REACH chemical management infrastructure before F-Gas Regulation phase-down deadlines tighten. Consolidate procurement relationships through long-term service contracts bundling hardware and predictive maintenance. Electromechanical substitution in thermal management zones threatens margin pools; counter by accelerating hybrid actuator development with embedded position sensing. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian manufacturing corridors where pneumatic component capacity remains underdeveloped and EU Green Deal-compliant production offers first-mover positioning. Target heavy-duty suspension actuators for commercial vehicle applications in emerging logistics corridors. Go-to-market leverage: partner with fleet standardization programs seeking supplier diversification away from Eastern European concentration. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH compliance infrastructure and EMA MDR documentation capabilities favor scaled incumbents with dedicated chemical management systems. Acquisition target archetype: mid-tier component specialists with precision machining talent in Stuttgart or Munich engineering clusters lacking predictive diagnostics integration. Signal to watch: EU AI Act risk classification protocol implementation creating certification-based differentiation for smart actuator architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Integration | Embedded position sensing and edge computing enable condition-based maintenance contracts across Bavarian commercial fleets. |
| Elastomer Seal Reformulation | Fluorosilicone and hydrogenated nitrile butadiene rubber qualification addresses EU F-Gas Regulation compliance for cylinder production. |
| Long-Term Service Contract Capture | Multi-year hardware and maintenance bundles displace transactional sales among Paris and Lyon logistics operators. |
| Eastern European Capacity Expansion | Polish and Romanian manufacturing corridors offer first-mover positioning for EU Green Deal-compliant pneumatic component production. |
| Precision Machining Talent Acquisition | Stuttgart and Munich engineering clusters harbor scarce tool-and-die skills for sub-10-micron cylinder bore tolerances. |
Research Methodology
Desk research of EU regulatory filings, automotive production databases, and tier-1 supplier annual disclosures preceded structured interviews with OEM platform engineers, Tier 1 procurement leads, aftermarket distributors, and fleet operations managers. Primary fieldwork combined telephone and video interviews with secondary validation against vehicle registration data and customs trade records. Bottom-up component demand modeling triangulated against top-down OEM production forecasts.
Baseline assumptions held EU Green Deal emissions benchmarks and REACH compliance timelines fixed while varying commercial vehicle fleet expansion rates and dual-clutch transmission penetration across passenger car segments. Segmentation dimensions spanned component hierarchy, application function, vehicle architecture, and technology type. CAGRs were derived from regression analysis of historical procurement patterns projected across the modeling period. Industry-specific inputs included brake system safety certification cycles and F-Gas Regulation phase-down curves for sealing compound substitution.
Macroeconomic conditions sit as an overlay; deviation in aluminum alloy pricing, energy cost trajectories, or German commercial vehicle production volumes would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and OEM platform standardization timelines. Quarterly review of EU AI Act risk classification protocol developments and Eastern European supplier concentration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Tailgate Market