
 Automotive Push Rods Market | 2026-2036
Automotive Push Rods Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Push Rods Market Analysis
ISO/TS 16949 qualification is redrawing supplier eligibility across the automotive push rods landscape. Manton Pushrods leverages in-house heat-treatment capacity to control microstructure consistency in chrome-molybdenum alloys. Schaeffler anchors European OEM supply through automated friction-welding lines that reduce unit-to-unit variance. COMP Cams dominates the North American performance aftermarket with dedicated tooling for 7.400-inch and longer custom lengths.
An automotive push rod is a slender mechanical linkage, typically 5/16 to 3/8 inch in diameter and fabricated from seamless steel tubing or solid bar stock, that transmits reciprocating motion from the camshaft lifter to the rocker arm in overhead-valve engine architectures. Wall thickness, typically 0.080 to 0.120 inch in hollow designs, and end-form geometry determine fatigue life under cyclic loading at 6,000-plus RPM. Solid push rods retain the largest volume share in heavy-duty truck and commercial vehicle applications where bending stiffness outweighs mass reduction priorities. Hollow push rods capture margin concentration in motorsports and premium passenger vehicles where valvetrain inertia limits engine speed ceiling. Titanium and carbon fiber variants remain niche but command the highest per-unit pricing due to raw material scarcity and specialized welding requirements.
EPA tailpipe standards and NHTSA fuel economy mandates compel OEMs to scrutinize valvetrain friction losses, directly influencing push rod surface finish and coating specifications. The EU F-Gas Regulation and REACH chemical restrictions constrain lubricant formulations that interact with push rod coatings, forcing material compatibility testing upstream. Stakeholders must monitor how California Air Resources Board zero-emission vehicle mandates redirect capital from internal combustion valvetrain programs toward electrification, even as aftermarket demand for legacy engine architectures persists through the forecast horizon.
Market Dynamics
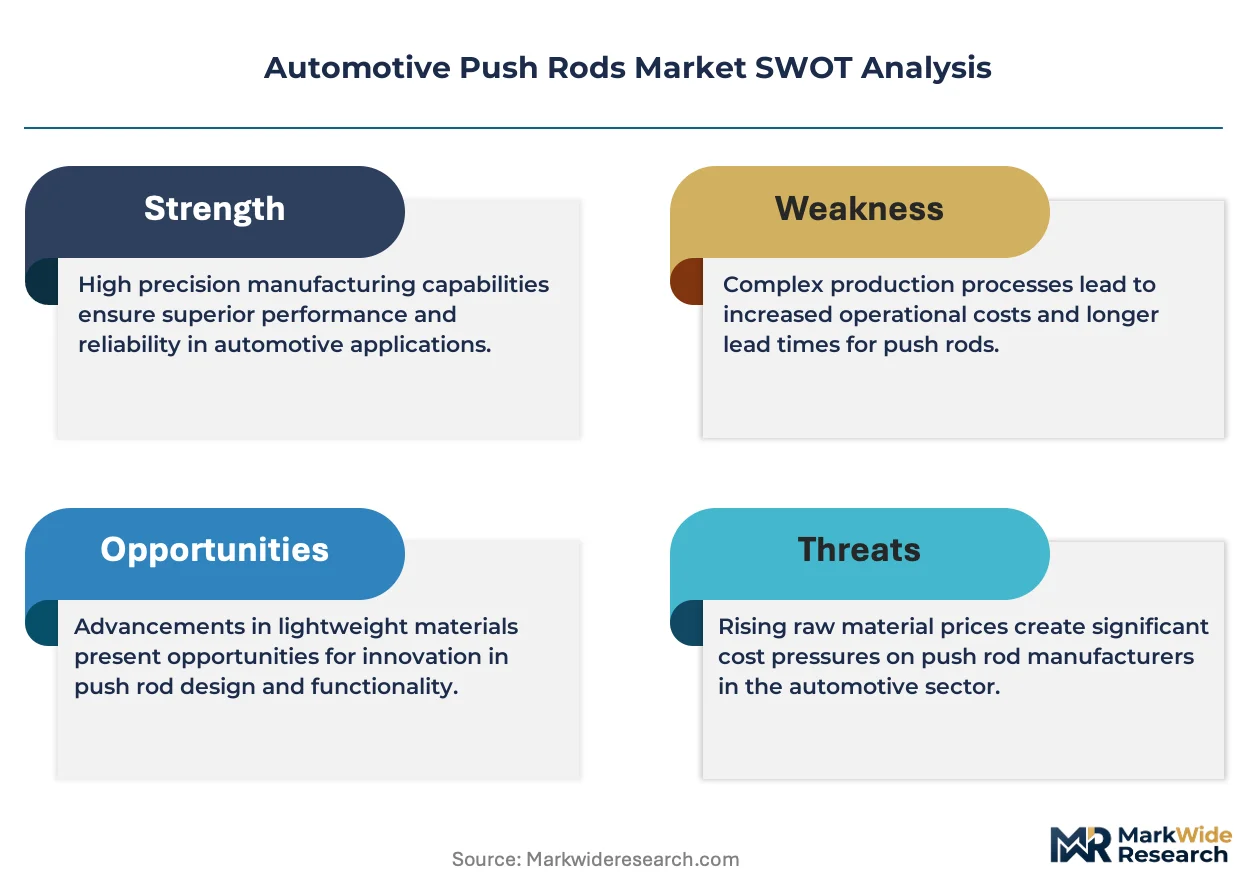
Valvetrain electrification pressure from EPA tailpipe standards is fragmenting engineering resources across legacy internal combustion programs and emerging e-motor architectures, forcing push rod suppliers to defend core revenue while funding capability pivots.
Growth Catalysts
- Aftermarket Performance Build Volume:High-compression crate engine programs from specialty builders sustain replacement demand for chrome-molybdenum and titanium push rod configurations. These builders operate outside OEM procurement cycles, insulating segment revenue from production volatility.
- EPA Tier 3 Emissions Enforcement:Tighter hydrocarbon limits compel precision grinding and diamond-like carbon coating adoption to reduce valvetrain friction losses. Suppliers with in-house finishing capacity capture specification upgrades.
- Heavy-Duty Diesel Residual Demand:Commercial fleet operators in the United States extend engine rebuild intervals rather than adopting unproven electrified alternatives, sustaining solid push rod volume in 15-liter and larger displacement categories.
Market Restraints
- Alloy Steel Price Volatility:Seamless 4130 and 4140 tubing feedstock costs fluctuate with scrap metal and energy inputs, compressing margin on fixed-price OEM contracts.
- Supplier Concentration in Midwest Forging:Heat-treatment and end-forming capacity clusters in Indiana and Ohio create geographic exposure to regional labor disruptions and utility rate spikes.
- Cam-in-Block Architecture Decline:Overhead cam and camless valvetrain designs eliminate push rod positions entirely in new passenger vehicle programs.
Strategic Opportunities
- Restomod and Pro-Touring Build Expansion:Enthusiast spending on 1960s-1980s platform modernization creates demand for custom-length, adjustable push rods with heritage fitment.
- India Commercial Vehicle Localization:Bharat Stage VI compliance drives domestic sourcing mandates for heavy-duty valvetrain components, opening qualification pathways for export-capable suppliers.
- Additive Manufacturing Convergence:Hybrid production combining precision-drawn tubing with laser-deposited end features enables lot-size-one customization without dedicated tooling investment.
Industry Challenges
- ISO/TS 16949 Transition Timeline:IATF 16949 recertification demands documented process capability for microstructure consistency, stretching quality engineering bandwidth at mid-tier suppliers.
- Legacy Equipment Integration:Automated friction-welding lines must interface with 1990s-vintage CNC end-formers, creating downtime risk and maintenance skill gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Push Rods Market |
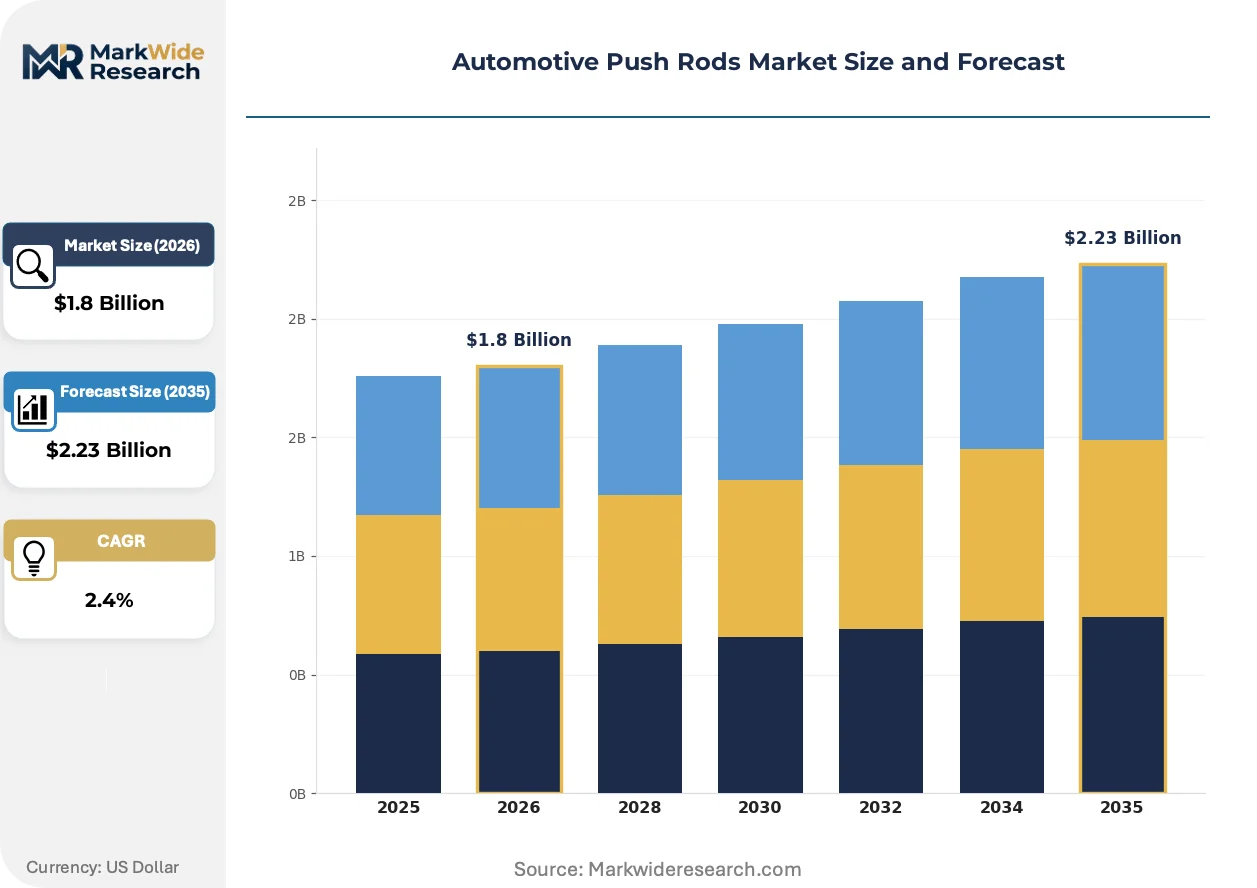
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hollow Push Rods, Solid Push Rods, Adjustable Push Rods, Push Rod Kits Material: Steel, Aluminum, Carbon Fiber, Titanium End Use: Passenger Vehicles, Commercial Vehicles, Motorsports, Heavy-Duty Trucks Construction Type: Custom Fabricated, Standardized, Aftermarket Replacement, OEM |
| Companies Covered | Manton Pushrods, COMP Cams, Smith Bros Pushrods, Lunati, Schaeffler, OE Pushrods, Rane Engine Valve, Wuxi Xizhou Machinery, Elgin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Push Rods Market Emerging Trajectories
Surface engineering and material substitution are compressing the performance gap between commodity steel and exotic alloy push rods, while regulatory friction loss mandates accelerate specification turnover.
Hollow chrome-molybdenum designs with wall thickness below 0.080 inch are displacing solid bar stock in high-RPM street performance applications. Engine builders targeting 7,500-plus redlines specify these configurations to reduce valvetrain inertia and stabilize dynamic stability. The shift is compressing addressable volume for traditional solid push rod suppliers while expanding premium tubing demand.
EPA fuel economy mandates and NHTSA Corporate Average Fuel Economy enforcement are mandating diamond-like carbon and molybdenum disulfide coating adoption across OEM valvetrain programs. These surface treatments reduce boundary friction at the rocker arm interface. Heavy-duty diesel manufacturers in the United States are responding with qualification programs for coated hollow push rods in long-haul applications.
Direct-to-builder digital channels are fragmenting traditional warehouse distributor dominance in the performance aftermarket. Specialty engine shops now specify push rod length, diameter, and end geometry through online configurators with two-week fulfillment. This pattern concentrates in the United States where domestic tubing mills support rapid-turn fabrication.
Automotive Push Rods Market Segmentation
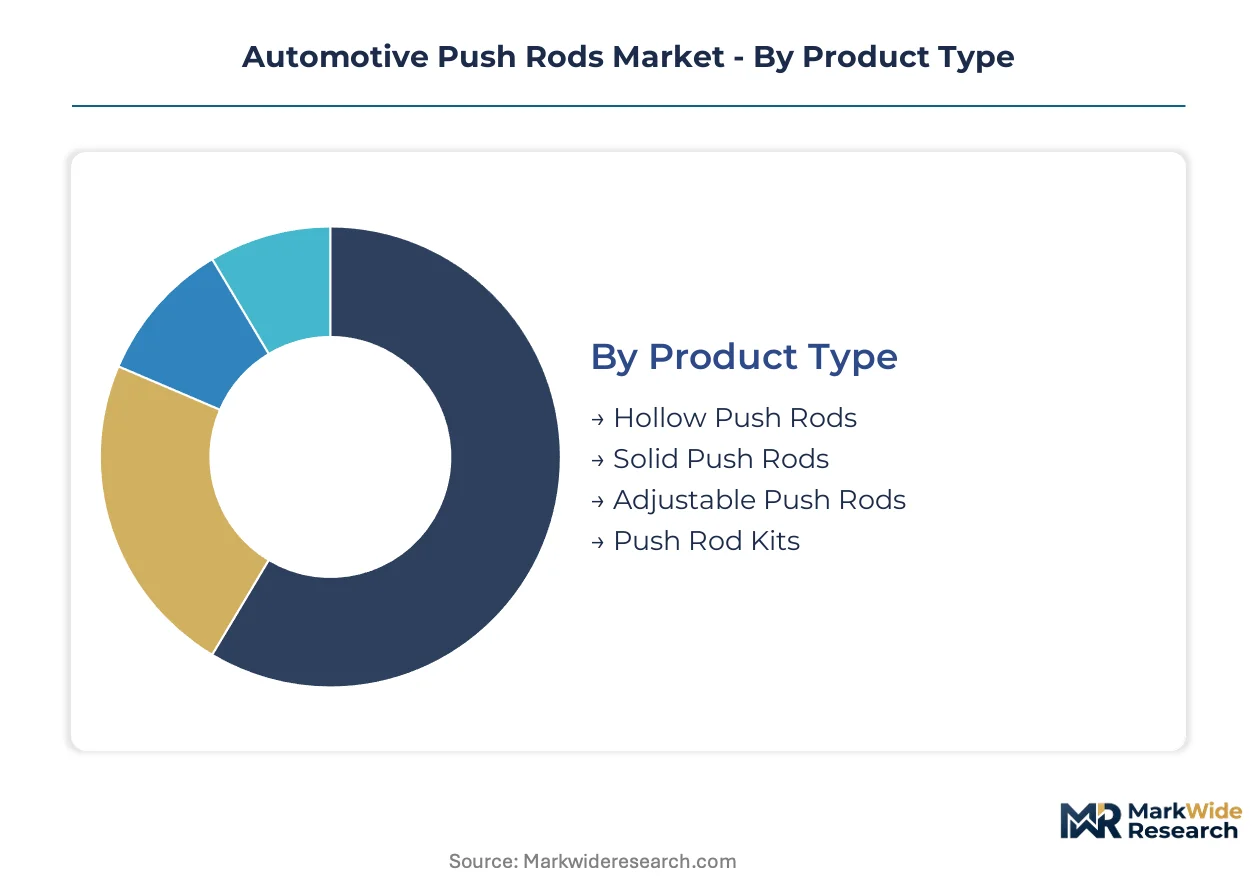
Push rod segmentation reveals divergent margin economics across material grades and end-use applications. Product architecture and construction type determine supplier qualification pathways and pricing power.
Product Type:
Hollow configurations capture the steepest margin expansion as valvetrain inertia reduction becomes a priority for high-RPM engine builds.
- Hollow Push Rods:Seamless chrome-molybdenum tubing with wall thickness below 0.080 inch reduces reciprocating mass by 40-60 percent versus solid alternatives. Demand concentrates in United States motorsports and premium passenger vehicle programs where 7,500-plus RPM operation requires dynamic stability. EPA fuel economy mandates accelerate OEM adoption for friction reduction.
- Solid Push Rods:Fabricated from 4130 or 4140 bar stock, these deliver maximum bending stiffness for commercial diesel applications. United States heavy-duty truck manufacturers specify solid designs for 15-liter and larger displacement engines where durability outweighs mass considerations. Fleet operators extending rebuild intervals sustain replacement volume.
- Adjustable Push Rods:Threaded mid-section designs enable precise valvetrain geometry correction during engine assembly.
- Push Rod Kits:Pre-matched sets bundle rods with guide plates and rocker arm studs for crate engine builders.
Solid push rods hold installed capacity across North American forging networks. Hollow push rods are rotating up the share rankings in performance aftermarket channels.
Material:
Raw material selection separates commodity volume from premium pricing tiers, with exotic alloys commanding qualification premiums.
- Steel:Chrome-molybdenum grades dominate OEM and aftermarket volume through seamless tubing and bar stock availability. Indiana and Ohio heat-treatment clusters control microstructure consistency for Tier 1 suppliers. EPA Tier 3 emissions enforcement tightens tolerance requirements for surface finish and coating compatibility.
- Titanium:Ti-6Al-4V and similar alloys deliver 45 percent mass reduction with comparable stiffness to steel. Motorsports applications in the United States absorb limited supply from aerospace-certified mills. Specialized electron-beam welding requirements constrain supplier entry.
- Aluminum:7075-T6 variants serve niche valvetrain applications where moderate load and temperature limits permit.
- Carbon Fiber:Hybrid designs with metallic end fittings command the highest per-unit pricing due to layup complexity and inspection protocols.
Steel retains the broadest supplier base and lowest feedstock volatility. Titanium is climbing the fastest in motorsports specification share.
End Use:
Application-specific durability requirements fragment procurement patterns across divergent qualification standards.
- Commercial Vehicles:Heavy-duty diesel programs specify solid steel rods with diamond-like carbon coatings to extend service intervals under sustained high-load operation. United States fleet operators prioritize total cost of ownership over initial component cost. NHTSA fuel economy mandates penetrate slower in this segment due to duty-cycle constraints.
- Motorsports:Custom engine builders specify hollow titanium and thin-wall chrome-molybdenum configurations for drag racing and road course applications. Direct-to-builder digital channels fragment traditional distribution, with two-week fulfillment now standard for custom lengths.
- Passenger Vehicles:OEM programs favor hollow steel designs with friction-reducing coatings for mass production scale.
- Heavy-Duty Trucks:15-liter and larger displacement architectures sustain demand for maximum-stiffness solid rods.
Commercial vehicles anchor steel volume through predictable replacement cycles. Motorsports is expanding most quickly in premium material adoption.
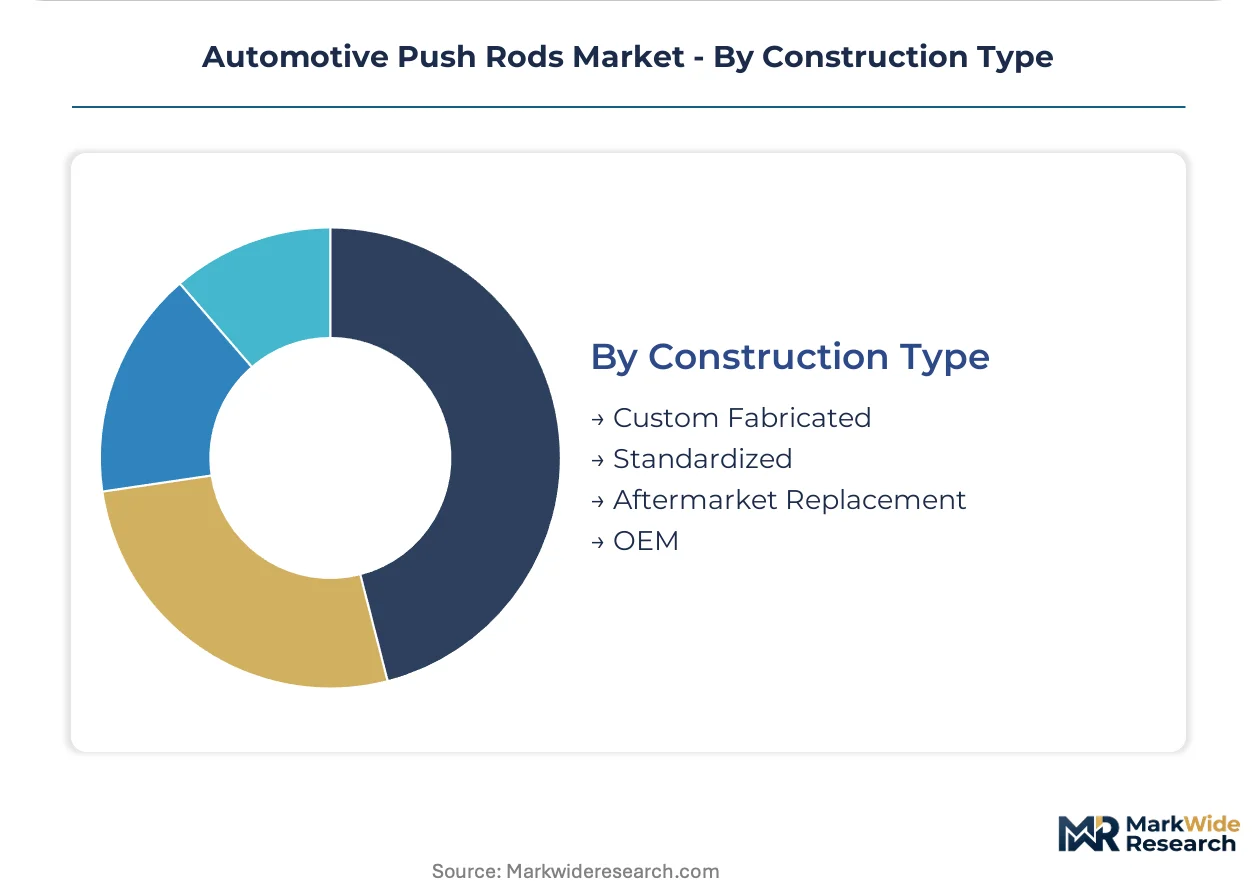
Construction Type:
Production methodology determines lead times, tooling amortization, and customer relationship structures.
- OEM:Automated friction-welding lines and statistical process control satisfy IATF 16949 requirements for microstructure consistency. Schaeffler and similar Tier 1 suppliers anchor European and United States passenger vehicle programs with dedicated capacity. Long-term contracts expose margins to alloy steel price volatility.
- Aftermarket Replacement:Independent engine rebuilders and repair shops source through warehouse distributors or direct manufacturer relationships. COMP Cams and specialty suppliers dominate North American performance channels with configurable length and end geometry options.
- Custom Fabricated:Lot-size-one production serves restomod and pro-touring builders requiring heritage fitment with modern materials.
- Standardized:Catalog designs with fixed dimensions serve high-volume replacement demand for legacy engine architectures.
OEM construction holds the deepest quality system investment. Aftermarket replacement is gaining share fastest through digital channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 emissions enforcement and NHTSA fuel economy mandates are redirecting supplier investment toward friction-reducing surface treatments across major automotive manufacturing regions. Domestic content requirements and commercial fleet replacement cycles sustain push rod demand in markets with established heavy-duty truck production.
United States
High-performance crate engine builders and commercial fleet operators drive aftermarket and replacement demand for chrome-molybdenum and solid steel configurations. NHTSA Corporate Average Fuel Economy enforcement pressures OEMs to adopt diamond-like carbon coatings for valvetrain friction reduction. Indiana and Ohio heat-treatment clusters control microstructure consistency for Tier 1 suppliers serving domestic V8 and diesel programs.
Germany
Automated friction-welding capacity anchors European OEM supply for passenger vehicle valvetrain programs. EU F-Gas Regulation and REACH chemical restrictions constrain lubricant formulations that interact with push rod coatings, forcing upstream material compatibility testing. Baden-Württemberg precision engineering networks specialize in statistical process control for IATF 16949-qualified production lines.
China
Domestic commercial vehicle manufacturers source solid steel push rods for heavy-duty diesel engines serving logistics and construction sectors. MIIT fuel consumption standards for commercial vehicles parallel EPA trajectory on friction loss reduction. Yangtze River Delta forging networks are expanding heat-treatment capacity to capture specification upgrades from multinational OEM localization programs.
India
Bharat Stage VI compliance drives domestic sourcing mandates for heavy-duty valvetrain components in commercial vehicle applications. The PLI scheme for automotive components incentivizes capital investment in precision grinding and coating capability. Tamil Nadu and Maharashtra industrial corridors are qualifying export-capable suppliers for integration into global OEM supply chains.
Japan
Keiretsu supply structures concentrate precision valvetrain component sourcing within domestic tiered supplier networks. METI energy efficiency regulations for transportation equipment influence material selection for mass reduction in high-RPM engine architectures. Aichi Prefecture manufacturing clusters maintain captive heat-treatment capacity for microstructure consistency in motorsports and premium passenger vehicle programs.
Automotive Push Rods Market Vendor Landscape
Player mix skews toward specialized forging and precision machining operations with captive heat-treatment capability. Market structure concentrates around Tier 1 automotive suppliers with IATF 16949 qualification and independent performance aftermarket specialists with configurable production lines. Three archetypes dominate: automated friction-welding OEM suppliers, custom-length performance fabricators, and vertically integrated heat-treatment specialists. Competitive moves center on in-house coating capability expansion and direct-to-builder digital channel development.
Within the heat-treatment-specialist tier, Manton Pushrods exemplifies backward integration into microstructure control for chrome-molybdenum alloys. COMP Cams occupies a position among North American performance aftermarket suppliers with dedicated tooling for extended-length configurations. Schaeffler represents the automated OEM supply archetype through European friction-welding line investment. These three entities illustrate the capability segmentation between statistical process control for mass production and lot-size-one customization for heritage engine builds.
| Leading Market Players |
|---|
| Manton Pushrods |
| COMP Cams |
| Smith Bros Pushrods |
| Lunati |
| Schaeffler |
| OE Pushrods |
| Rane Engine Valve |
| Wuxi Xizhou Machinery |
| Elgin Industries |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between United States heavy-duty diesel OEMs and Indiana heat-treatment clusters lock in chrome-molybdenum tubing access while capping price visibility against scrap metal volatility. These arrangements concentrate procurement power among Tier 1 suppliers with IATF 16949 qualification, forcing mid-tier fabricators toward spot-market exposure.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers in this market. IATF 16949-qualified suppliers command sustained premiums through statistical process control guarantees, while uncertified competitors compete on per-unit transactional pricing for aftermarket replacement volume. Price differentiation intensifies as EPA Tier 3 emissions enforcement tightens surface-finish tolerances, elevating diamond-like carbon coating costs. Fleet operators in commercial vehicle segments exhibit lowest price sensitivity, prioritizing total cost of ownership over initial component cost.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta forging networks to North American assembly plants fluctuate with container availability on transpacific trade lanes. Raw material supply concentrates in United States seamless tubing mills, Chinese induction-hardening facilities, and German precision-grinding equipment manufacturers. Feedstock dependency rests on 4130 and 4140 alloy steel scrap flows, titanium aerospace mill allocations, and specialized coating chemical supply. Single-source vulnerability permeates electron-beam welding capacity for titanium configurations. Distribution runs through warehouse distributors serving independent engine rebuilders, direct-to-builder digital channels for custom fabrication, and captive OEM supply lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive push rod demand follows cyclical recovery patterns tied to commercial fleet replacement intervals, with heavy-duty diesel rebuild programs providing baseline revenue stability through electrification transition turbulence.
For Market Incumbents: Shield core OEM relationships by securing captive heat-treatment capacity in Ohio and Indiana forging clusters before regional labor disruptions materialize. Deepen backward integration into chrome-molybdenum microstructure control to defend margin position against alloy steel price volatility. Prioritize in-house diamond-like carbon coating capability expansion to capture specification upgrades from EPA Tier 3 friction-reduction mandates. For New Entrants and Emerging Players: Lead with additive manufacturing convergence for restomod and pro-touring heritage fitment, where lot-size-one customization commands premium pricing without dedicated tooling investment. Target India commercial vehicle localization under Bharat Stage VI domestic sourcing mandates as the most penetrable geography. Establish direct-to-builder digital configurators with two-week fulfillment to bypass entrenched warehouse distributor relationships. For Investors and Strategic Acquirers: Heat-treatment-specialist mid-caps with seamless tubing backward integration represent the highest-conviction acquisition archetype for valvetrain component consolidation. Long-term viability hinges on aftermarket replacement demand persistence through electrification transition, with five-to-ten-year windows favoring suppliers serving legacy internal combustion architectures. Monitor California Air Resources Board zero-emission vehicle mandate acceleration as the critical inflection signal for internal combustion capital reallocation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | Captive microstructure control in Indiana and Ohio secures IATF 16949 qualification pathways for Tier 1 supply. |
| In-House Coating Capability Investment | Diamond-like carbon application capacity captures EPA Tier 3 friction-reduction specification upgrades. |
| Direct-to-Builder Digital Channel Development | Online configurators with rapid fulfillment fragment traditional warehouse distributor dominance in performance aftermarket. |
| India Commercial Vehicle Localization | Bharat Stage VI domestic sourcing mandates open qualification pathways for export-capable suppliers in Tamil Nadu. |
| Additive Manufacturing Integration | Laser-deposited end features enable lot-size-one customization without dedicated tooling for heritage engine builds. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with Tier 1 supplier procurement officers, aftermarket distributor operations heads, specialty engine builder technical directors, and heat-treatment facility managers; and secondary validation through vehicle production databases, EPA emissions enforcement documentation, SEC automotive supplier filings, and IHS Markit registration data. Bottom-up fabrication capacity modeling triangulated against top-down valvetrain component demand estimates from OEM platform engineering disclosures.
Across the analysis window, the forecasting framework modeled segmentation by construction type, material grade, end-use application, and regional regulatory cluster. CAGRs derived from production volume trajectories, replacement cycle analysis, and specification upgrade adoption curves. Industry-specific inputs included cam-in-block architecture decline rates, EPA Tier 3 implementation timing, and commercial fleet rebuild interval extension patterns.
The analysis sits within stated boundaries; outcomes outside sustained internal combustion aftermarket demand, stable alloy steel feedstock availability, or unchanged EPA emissions enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding electrification transition pacing and heritage engine build persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Metal Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Brackets Market
Automotive Components
North America Automotive Bearing Market