
 India Automotive Heat Exchanger Market | 2026-2036
India Automotive Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Heat Exchanger Market Foresight
Asset-light leasing models for thermal management equipment is tilting competitive dynamics toward suppliers with balance-sheet flexibility. Denso Corporation leverages its captive aluminum casting network to control input costs across radiator and intercooler lines. Mahle GmbH anchors its India position through dedicated R&D facilities focused on lightweight HVAC units for commercial vehicle platforms. Valeo SA competes via localized production of oil coolers serving passenger car OEMs in the Pune-Aurangabad belt.
An automotive heat exchanger is a thermal transfer device typically constructed from aluminum alloy fins brazed to tube cores, engineered to regulate fluid temperatures in powertrain and climate systems across ambient conditions exceeding 50°C. Its primary purpose is maintaining optimal thermal efficiency for engines, transmissions, and passenger compartments under variable load cycles. Radiators remain the dominant product category by installed base across passenger cars and heavy-duty trucks, though intercoolers command premium pricing tied to turbocharged engine penetration. Aluminum leads material demand due to density advantages over copper in fuel-economy-sensitive applications, while OEM direct procurement channels capture the largest margin pool by bypassing tiered distribution markups.
Bharat Stage VI emission standards enforced by the Central Pollution Control Board mandate tighter engine thermal management, directly expanding specification requirements for oil coolers and intercoolers in diesel commercial vehicles. BIS certification for aluminum alloy grades and CEA efficiency guidelines for auxiliary power units further constrain material sourcing and design parameters for domestic manufacturers. Stakeholders must monitor PLI scheme revisions for automotive components and evolving state-level electric vehicle policies that will redefine thermal architecture demand across powertrain categories.
Market Dynamics
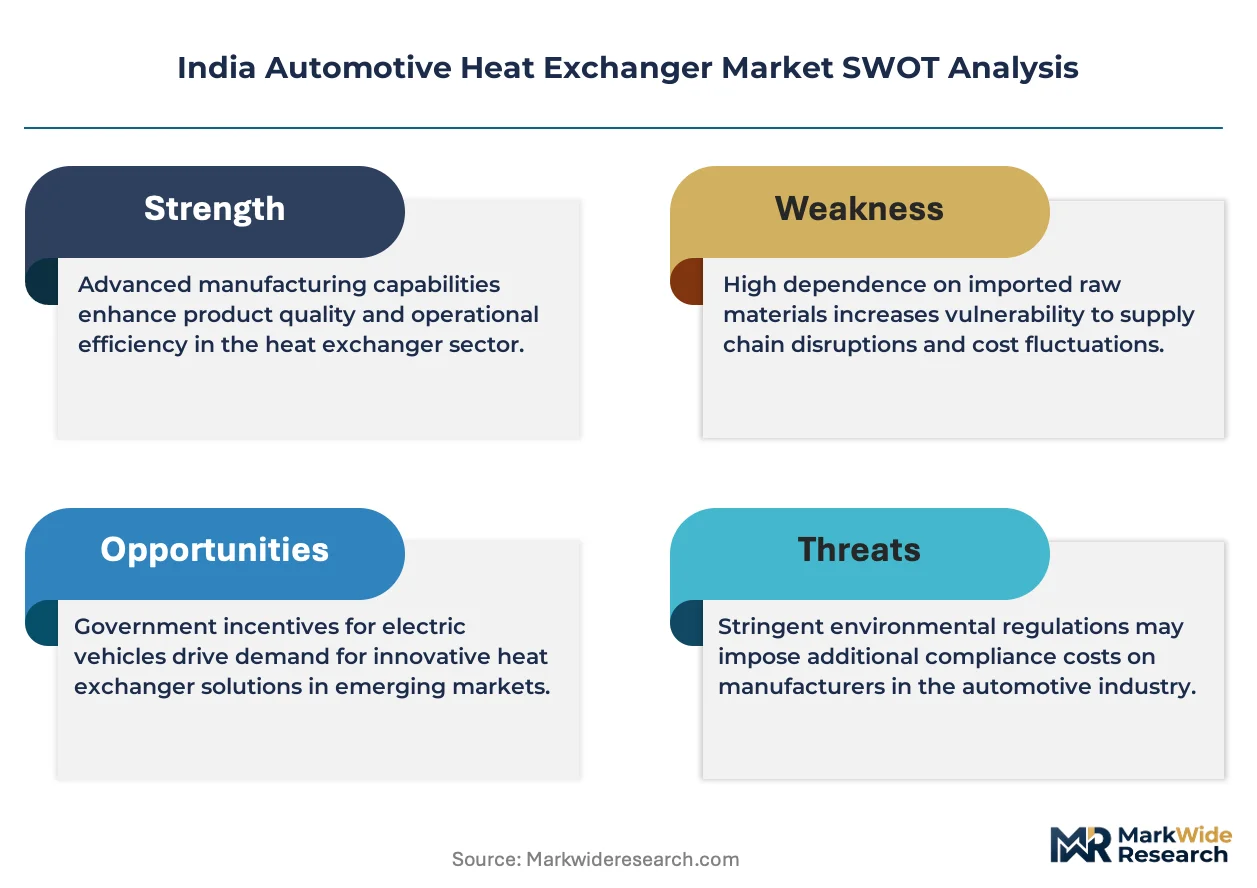
Bharat Stage VI compliance deadlines are compressing thermal management upgrade cycles across India's commercial vehicle fleet, forcing simultaneous replacement of radiators, intercoolers, and oil coolers in ways that favor integrated suppliers with aluminum casting capabilities.
Growth Catalysts
- Turbocharged diesel penetration:Commercial vehicle OEMs in Maharashtra and Tamil Nadu are specifying larger intercooler cores to meet power density targets under Bharat Stage VI emission thresholds.
- CEA auxiliary power guidelines:Efficiency mandates for engine-driven refrigeration units on long-haul trucks are expanding radiator capacity requirements in the cold-chain logistics segment.
- Aluminum brazing automation:Controlled atmosphere brazing technology adoption in Pune-Aurangabad manufacturing clusters is reducing defect rates and enabling thinner fin stock.
Market Restraints
- Primary aluminum price volatility:Input cost swings for A356.2 alloy ingot strain margin stability for radiator manufacturers without captive smelter arrangements.
- BIS certification timelines:Bureau of Indian Standards approval cycles for new alloy grades extend product development windows by six to nine months.
- Copper-aluminum hybrid competition:Niche performance applications in high-temperature operating environments retain copper tube-and-fin architectures.
Strategic Opportunities
- Electric vehicle thermal architecture:Battery cooling plates and power electronics chillers represent white-space demand as state EV policies in Gujarat and Karnataka accelerate two-wheeler electrification.
- Leasing model penetration:Fleet operators in the Delhi-Mumbai freight corridor are testing heat-exchanger-as-a-service contracts that transfer lifecycle risk to suppliers.
- PLI scheme automotive component incentives:Revised production-linked subsidy thresholds reward capital investment in advanced brazing and surface treatment capacity.
Industry Challenges
- Skilled brazing technician scarcity:Controlled atmosphere furnace operation and flux application expertise concentrates in legacy Pune industrial zones, constraining greenfield expansion.
- Legacy platform integration:Retrofit thermal packages for Bharat Stage III and IV trucks in secondary markets require custom mounting solutions that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Heat Exchanger Market |
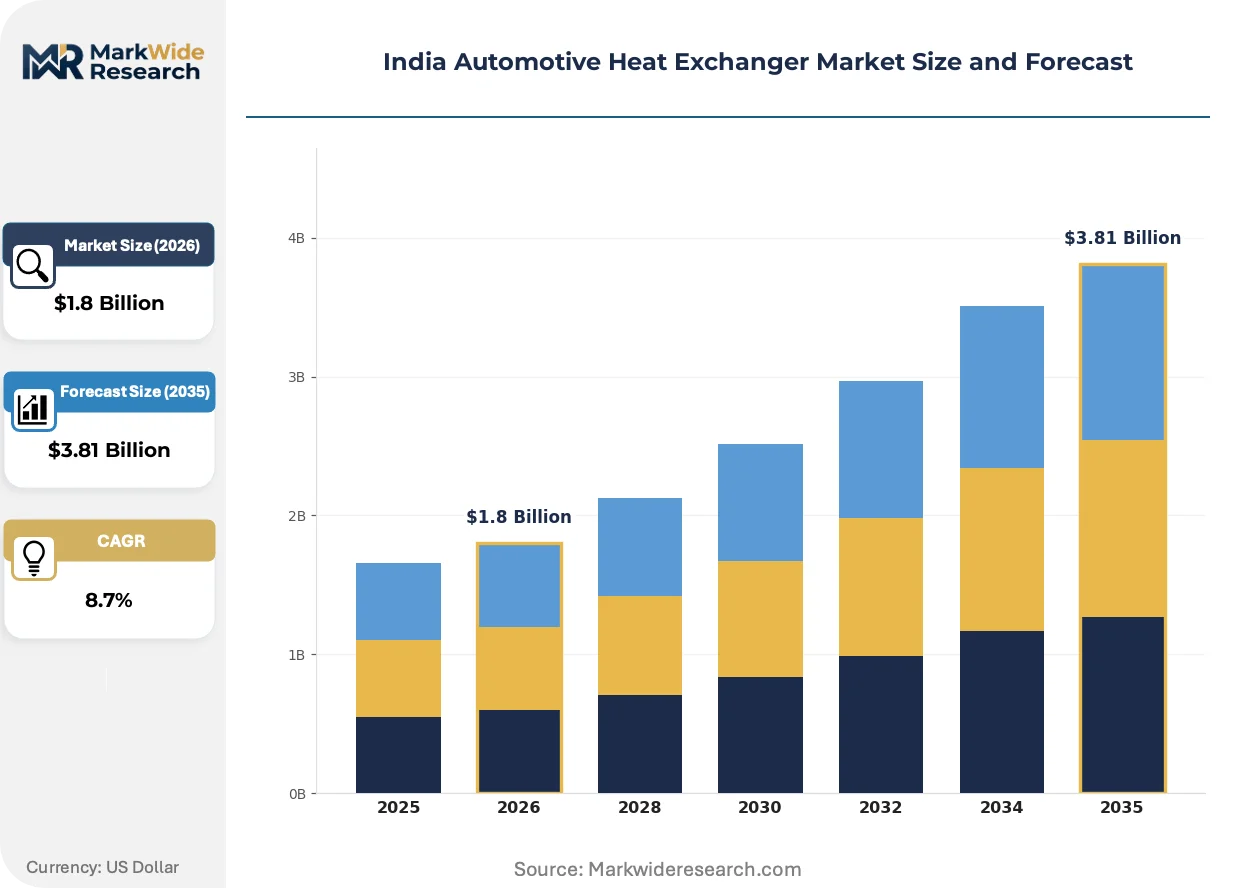
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiators, Oil Coolers, Intercoolers, HVAC Units Material: Aluminum, Copper, Plastic, Steel End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks |
| Companies Covered | Denso Corporation, Valeo SA, Mahle GmbH, Hanon Systems, Modine Manufacturing, T.RAD Co., Ltd., Nippon Light Metals, Dana Limited, Sanden Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Heat Exchanger Market Shifts & Advancements
Digital process control and predictive quality systems are penetrating aluminum heat exchanger manufacturing, compressing inspection cycles while enabling real-time parameter adjustment during brazing operations.
Machine vision inspection is digitizing defect detection in fin forming and tube insertion stages. Tier-1 suppliers serving Maruti Suzuki and Tata Motors have deployed camera-based systems that flag brazing gaps and fin deformation before furnace entry. This technology is compressing rework rates and reducing warranty exposure for high-volume radiator programs.
Bharat Stage VI emission norms enforced by the Central Pollution Control Board mandate closed crankcase ventilation and exhaust gas recirculation cooling. These systems require compact oil coolers and EGR coolers with enhanced corrosion resistance. Diesel commercial vehicle platforms above 3.5 tonnes gross vehicle weight face the steepest thermal load increases, driving specification upgrades in the heavy-duty truck segment.
Fleet procurement departments are consolidating supplier relationships around integrated thermal module providers. Single-source contracts covering radiators, intercoolers, and HVAC condensers are displacing component-level purchasing at large logistics operators. This concentration is most visible in the Mumbai-Chennai freight corridor where asset-light fleet managers prioritize total cost of ownership over upfront piece pricing.
India Automotive Heat Exchanger Market Segmentation
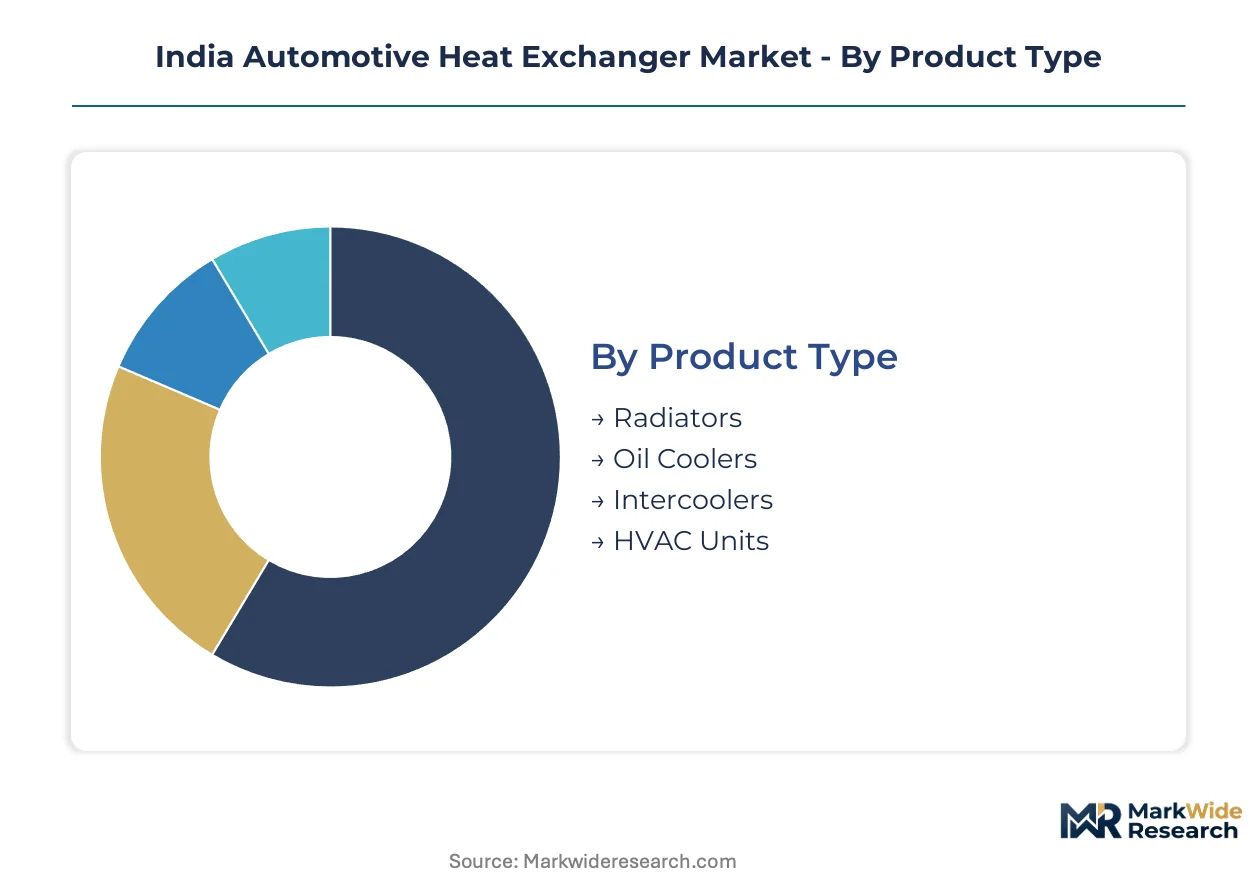
Segmentation reveals how thermal management demand fragments across powertrain architectures, material preferences, and procurement channels in India's automotive supply base. Understanding these divisions exposes where specification pressures and margin pools concentrate for component suppliers.
Product Type:
The use-case spectrum spans engine cooling, lubrication thermal control, forced induction management, and cabin climate regulation across India's vehicle parc.
- Radiators:Aluminum tube-and-fin cores brazed with controlled atmosphere technology dominate cooling circuit architecture. Demand concentrates in Maharashtra and Tamil Nadu passenger car assembly plants where Maruti Suzuki and Tata Motors specify lightweight designs for compact car platforms.
- Intercoolers:Charge air cooling modules with aluminum bar-plate construction manage compressed air temperatures for turbocharged diesel engines. Commercial vehicle OEMs in Pune-Aurangabad manufacturing corridors specify larger core volumes to meet Bharat Stage VI thermal efficiency mandates on heavy-duty truck platforms.
- Oil Coolers:Compact plate-type or tube-and-shell configurations regulate lubricant viscosity in high-load powertrain applications.
- HVAC Units:Evaporator and condenser assemblies integrate with refrigerant circuits for passenger compartment thermal comfort.
Established volume favors radiators; emerging adoption favors intercoolers.
Material:
Cost tier differentiation separates mass-market aluminum adoption from premium copper retention and emerging polymer alternatives.
- Aluminum:A356.2 alloy castings and brazed fin stock deliver density advantages critical for fuel economy compliance. Pune-Aurangabad supplier clusters have automated controlled atmosphere brazing lines to reduce defect rates in high-volume radiator production.
- Copper:Tube-and-fin architectures persist in niche high-temperature applications where thermal conductivity outweighs weight penalties. Heavy-duty mining trucks and certain defense vehicle specifications retain copper cores despite aluminum's market penetration.
- Plastic:Glass-reinforced nylon end tanks and structural components reduce assembly mass in HVAC module construction.
- Steel:Structural brackets and mounting hardware provide mechanical durability in chassis-mounted cooler applications.
Aluminum captures the widest specification range; copper defends the highest thermal load segments.
End User:
Procurement channel structure determines margin retention and technical specification authority across India's automotive value chain.
- OEMs:Direct thermal module sourcing from Maruti Suzuki, Tata Motors, and Mahindra & Mahindra bypasses tiered distribution markups. These manufacturers specify integrated radiator-intercooler-HVAC packages for platform standardization.
- Tier-1 Suppliers:Denso, Mahle, and Valeo contract manufacturing relationships concentrate in Maharashtra and Tamil Nadu corridors where captive aluminum casting capacity controls input costs.
- Aftermarket Providers:Independent distributors serve Bharat Stage III and IV vehicle parc in secondary markets with replacement radiators and intercoolers.
- Vehicle Assemblers:Knockdown kit operations in Gujarat and Karnataka import thermal subassemblies for local integration.
OEM direct procurement captures margin concentration; aftermarket channels address legacy fleet replacement cycles.
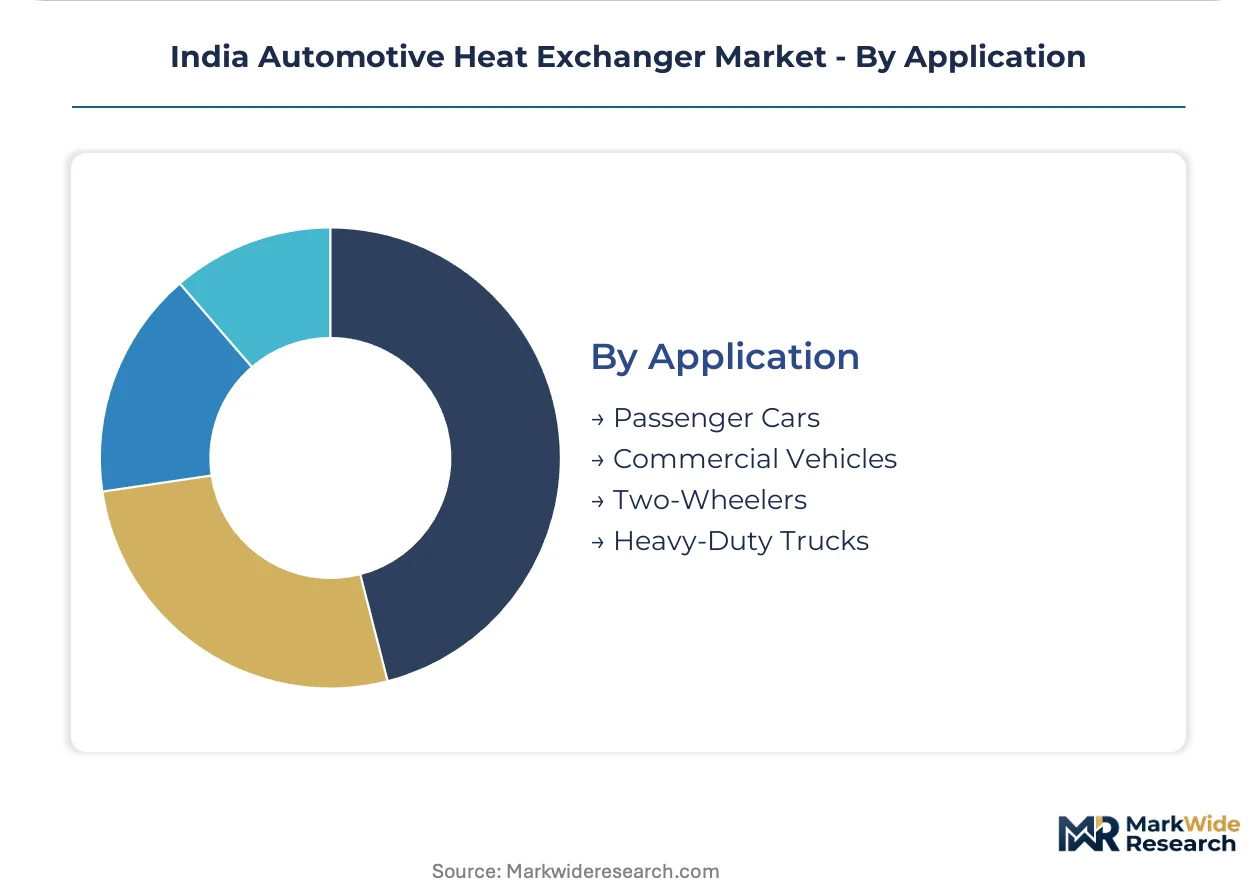
Application:
Vehicle category thermal loads vary by powertrain density, duty cycle severity, and operating environment exposure across Indian road conditions.
- Passenger Cars:Compact radiator and HVAC condenser specifications prioritize packaging efficiency and weight reduction. Sub-4-metre vehicle platforms in Delhi-Mumbai corridors drive high-volume aluminum radiator demand.
- Commercial Vehicles:Integrated thermal modules combining radiators, intercoolers, and oil coolers manage diesel engine thermal loads under Bharat Stage VI emission constraints. Fleet operators in the Mumbai-Chennai freight corridor consolidate supplier relationships around single-source thermal providers.
- Two-Wheelers:Small-format air-cooled engines with auxiliary oil coolers address urban commuter thermal management requirements.
- Heavy-Duty Trucks:Multi-circuit cooling systems with separate EGR coolers, transmission oil coolers, and fuel chillers serve long-haul logistics applications.
Passenger cars generate unit volume concentration; heavy-duty trucks drive specification complexity and per-vehicle value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's automotive heat exchanger trade flows reflect a structural deficit in precision aluminum casting capacity, with imports of brazed fin stock and controlled atmosphere furnace equipment outpacing exports of finished radiator and intercooler assemblies. The domestic supply base concentrates in western and southern manufacturing corridors where OEM assembly plants anchor thermal module demand.
Maharashtra
Commercial vehicle OEMs in Pune and Aurangabad specify integrated radiator-intercooler packages for Bharat Stage VI diesel platforms. The state's industrial development corporations offer capital subsidies for advanced brazing equipment under revised PLI scheme thresholds. Pune-Aurangabad supplier clusters have automated controlled atmosphere brazing lines to reduce defect rates in high-volume production.
Tamil Nadu
Passenger car assembly plants operated by Maruti Suzuki and Hyundai Motor India drive aluminum radiator demand for compact vehicle platforms. The Tamil Nadu government's electric vehicle policy offers incentives for battery cooling plate manufacturing. Chennai-Sriperumbudur automotive corridors concentrate tier-1 thermal module suppliers with captive aluminum casting operations.
Gujarat
Knockdown kit operations in Sanand and Halol import thermal subassemblies for local integration into passenger car and commercial vehicle platforms. The state's EV acceleration policies in two-wheeler segments are expanding demand for power electronics chillers. Gandhinagar-based regulatory coordination with BIS streamlines certification timelines for new alloy grades.
Karnataka
Two-wheeler electrification policies in Bengaluru and Mysuru corridors are generating white-space demand for battery cooling plates and compact thermal management modules. The Karnataka Industrial Areas Development Board allocates land parcels for surface treatment and brazing capacity expansion. Hosur-Bengaluru manufacturing zones attract tier-1 suppliers serving electric scooter OEMs.
Haryana
Delhi-Mumbai freight corridor fleet operators in Gurugram and Faridabad are testing heat-exchanger-as-a-service leasing contracts. The Haryana government's logistics park development program concentrates cold-chain vehicle demand with expanded radiator capacity for engine-driven refrigeration units. Manesar-Bawal industrial areas host aftermarket distribution centers serving legacy Bharat Stage III and IV vehicle parc.
India Automotive Heat Exchanger Market Competitive Landscape
On the supply side, the industry is consolidating around integrated thermal module providers with captive aluminum casting networks and controlled atmosphere brazing capabilities. Tier-1 suppliers with backward integration into alloy smelting command margin advantages over fabricators dependent on spot-market A356.2 ingot. Three archetypes dominate: Japanese-Korean conglomerates with global thermal technology platforms, European automotive component specialists with India-dedicated R&D facilities, and domestic fabricators serving aftermarket replacement cycles. Competitive dynamics center on M&A activity targeting brazing automation capabilities and strategic partnerships with fleet operators for lifecycle service contracts.
Within the integrated supplier tier, Denso Corporation, Valeo SA, and Mahle GmbH exemplify contrasting geographic and structural positioning. Denso Corporation represents Japanese conglomerate archetypes with extensive captive supply networks. Valeo SA occupies a position among European automotive component specialists with localized production strategies. Mahle GmbH anchors German engineering-focused positioning within the commercial vehicle thermal management segment.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Mahle GmbH |
| Hanon Systems |
| Modine Manufacturing |
| T.RAD Co., Ltd. |
| Nippon Light Metals |
| Dana Limited |
| Sanden Corporation |
| Others |
Supply & Pricing Matrix
A356.2 alloy ingot concentration in domestic smelters and Gulf import channels feeds directly into margin retention at radiator and intercooler fabricators with captive casting operations. Fleet procurement consolidation along the Mumbai-Chennai freight corridor compresses component-level pricing power while amplifying volume leverage for integrated thermal module suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium certified, standard BIS-grade, and economy aftermarket tiers. Price differentiation separates BIS-certified alloy grades from uncertified alternatives and bundles after-sales service commitments into multi-year fleet agreements. Cost compression in economy replacement radiators is intensifying because secondary market operators prioritize piece-price over lifecycle value. Tier-1 suppliers with captive aluminum casting face the least price sensitivity; independent fabricators dependent on spot-market ingot face the most.
Supply Chain Analysis
Tariff exposure between India and Gulf aluminum suppliers dominates input cost volatility for radiator manufacturers without backward integration into alloy sourcing. Primary aluminum draws from domestic Hindalco and Vedanta smelters plus UAE and Bahrain import channels; brazing flux and controlled atmosphere furnace equipment hinge on German and Japanese suppliers. Single-source vulnerability concentrates in precision fin stock rolling capacity. Distribution runs through OEM direct procurement channels for new vehicle platforms and fragmented aftermarket distributors serving legacy Bharat Stage III and IV parc.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation around single-source thermal module contracts has shifted bargaining power toward buyers with multi-year volume commitments. Three large logistics groups now control over half of heavy-duty truck procurement in the Delhi-Mumbai-Chennai triangle.
For Market Incumbents: Insulate margin position through captive A356.2 casting capacity expansion in Maharashtra and Tamil Nadu corridors. Denso Corporation's aluminum smelter network demonstrates how backward integration neutralizes primary aluminum price volatility. Prioritize BIS certification investment for new alloy grades to compress six-to-nine-month approval timelines that currently cede specification authority to faster-certified competitors. For New Entrants and Emerging Players: Pursue battery cooling plate manufacturing for Karnataka and Gujarat two-wheeler electrification programs where state EV policies generate white-space demand absent entrenched supplier relationships. Target power electronics chiller modules for electric scooter OEMs in Hosur-Bengaluru zones. Anchor go-to-market strategy through PLI scheme qualification that rewards capital investment in surface treatment and brazing automation capacity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic fabricators serving aftermarket replacement cycles for Bharat Stage III and IV commercial vehicles. Long-term viability hinges on migration path toward electric vehicle thermal architecture or Bharat Stage VI-compliant integrated modules. Watch PLI scheme revision timing as inflection indicator for capital deployment returns in advanced brazing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Casting Expansion | Backward integration into A356.2 smelting neutralizes input cost volatility for Denso and Mahle. |
| Controlled Atmosphere Brazing Automation | Pune-Aurangabad supplier clusters reduce defect rates through furnace technology upgrades. |
| Battery Cooling Plate Manufacturing | Karnataka EV policy incentives attract tier-1 suppliers to Hosur-Bengaluru electric scooter corridors. |
| Heat-Exchanger-as-a-Service Contracts | Haryana fleet operators transfer lifecycle risk to suppliers through Delhi-Mumbai freight corridor leasing pilots. |
| BIS Certification Fast-Track Investment | Compressed approval timelines for new alloy grades capture specification authority from slower competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS certification databases, CEA auxiliary power guidelines, and PLI scheme disclosure filings. Thermal management procurement heads at Maruti Suzuki and Tata Motors, controlled atmosphere furnace operators in Pune-Aurangabad clusters, and aftermarket distributors serving Bharat Stage III and IV legacy parc provided structured input. Aluminum alloy trade data and vehicle production statistics from IHS Markit registration databases anchored bottom-up volume triangulation against top-down OEM thermal module specification analysis.
Forecast inputs span vehicle class segmentation across passenger cars, commercial vehicles, and two-wheelers; propulsion architecture differentiation between internal combustion and electric platforms; content per vehicle escalation tied to Bharat Stage VI thermal load requirements; and regional production cluster concentration in Maharashtra, Tamil Nadu, Gujarat, and Karnataka. CAGRs derive from modeled unit volume trajectories intersecting with specification value expansion across radiator, intercooler, oil cooler, and emerging battery cooling plate categories throughout the forecast period.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Gulf aluminum suppliers or accelerated EV policy shifts in Gujarat and Karnataka would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Automotive Headliners Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Fender Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market