
 Polyamide in E-Mobility Market | 2026-2036
Polyamide in E-Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Polyamide in E-Mobility Market Analytics
The gap between premium heat-stabilized grades and commodity polyamide is hardening as OEMs specify materials for 800V architectures. BASF SE leverages its Ultramid portfolio to anchor supply relationships with European EV platforms. Arkema SA specializes in bio-based polyamide 11, competing on sustainability credentials rather than cost. DuPont de Nemours, Inc. controls high-performance Zytel formulations that dominate North American battery connector specifications.
Polyamide in e-mobility encompasses engineered thermoplastic polymers—primarily PA6, PA66, and PA12—formulated with glass fiber reinforcement, flame retardants, and thermal stabilizers to withstand continuous operating temperatures above 150°C in under-hood and battery environments. These materials serve as structural housings, electrical insulation barriers, and fluid management components where metal replacement reduces vehicle weight. Resin formulations currently lead volume consumption, while injection molding technology captures the dominant share of processing value due to its precision in complex connector geometries. Film and sheet applications for battery cell separators represent the fastest-expanding category, though from a smaller base, as solid-state battery prototypes demand thinner, more thermally stable barrier layers.
The EPA tailpipe emission rules and NHTSA fuel economy standards in the United States directly intensify lightweighting mandates that expand polyamide substitution for aluminum and steel. China's MIIT new-energy vehicle catalog ties subsidy eligibility to battery energy density thresholds that favor advanced polymer thermal management. Germany's KBA type-approval process enforces flame-spread resistance standards for battery enclosures, filtering out uncertified material suppliers. Stakeholders must monitor how pending revisions to the EU Battery Regulation's recycled-content quotas will reshape raw-material sourcing strategies for compounders serving the e-mobility value chain.
Market Dynamics
The 800V battery architecture transition concentrates material specifications around heat-stabilized polyamide grades that withstand continuous thermal cycling above 150°C. OEMs in Germany, China, and the United States now mandate these formulations for connector housings and battery structural components, compressing supplier qualification timelines and fragmenting the compounder landscape between certified and uncertified tiers.
Growth Catalysts
- MIIT Energy Density Thresholds:China's subsidy catalog ties new-energy vehicle incentives to battery pack performance metrics that require advanced polymer thermal management solutions in cell-to-pack architectures.
- REACH Chemical Restrictions:ECHA's tightening substance restrictions on halogenated flame retardants push compounders toward phosphorus-based and mineral-filled polyamide formulations for European EV platforms.
- Yangtze River Delta Cluster:Concentrated EV production lines in Jiangsu and Zhejiang provinces source locally compounded resins, creating demand density that attracts specialty material investments.
Market Restraints
- Caprolactam Price Volatility:PA6 feedstock costs fluctuate with benzene and cyclohexane derivatives, squeezing compounder margins when crude oil benchmarks spike above refinery hedging positions.
- Adipic Acid Supply Concentration:PA66 precursor production clusters in China and the United States create geographic chokepoints that amplify disruption risks from plant outages or trade policy shifts.
- Technical Limitation in Solid-State Interfaces:Current polyamide grades lack sufficient ionic purity for direct solid-state electrolyte contact, limiting deployment to pack-level rather than cell-level applications.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for automotive component manufacturing attract polyamide compounders to establish compounding facilities near Chennai and Pune EV assembly hubs.
- Bio-Based PA11 Feedstock:Castor oil-derived polyamide offers carbon-intensity advantages for OEMs sourcing materials under EU Battery Regulation recycled-content mandates and CSRD disclosure requirements.
- Film and Sheet Battery Separators:Solid-state battery prototypes demand thinner thermally stable barrier layers, opening technical specifications that commodity resins cannot satisfy.
Industry Challenges
- Material Scientist Talent Gap:Compounders struggle to recruit formulators with simultaneous expertise in flame-retardant chemistry, glass-fiber interface optimization, and injection molding rheology for thin-wall connectors.
- KBA Type-Approval Timelines:German battery enclosure certification requires 18-24 month flame-spread resistance validation cycles that delay revenue recognition for new grade introductions.
- Legacy Aluminum Tooling Conversion:Tier-2 suppliers face capital intensity in retooling injection molding equipment optimized for metal replacement geometries with tighter tolerance bands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyamide in E-Mobility Market |
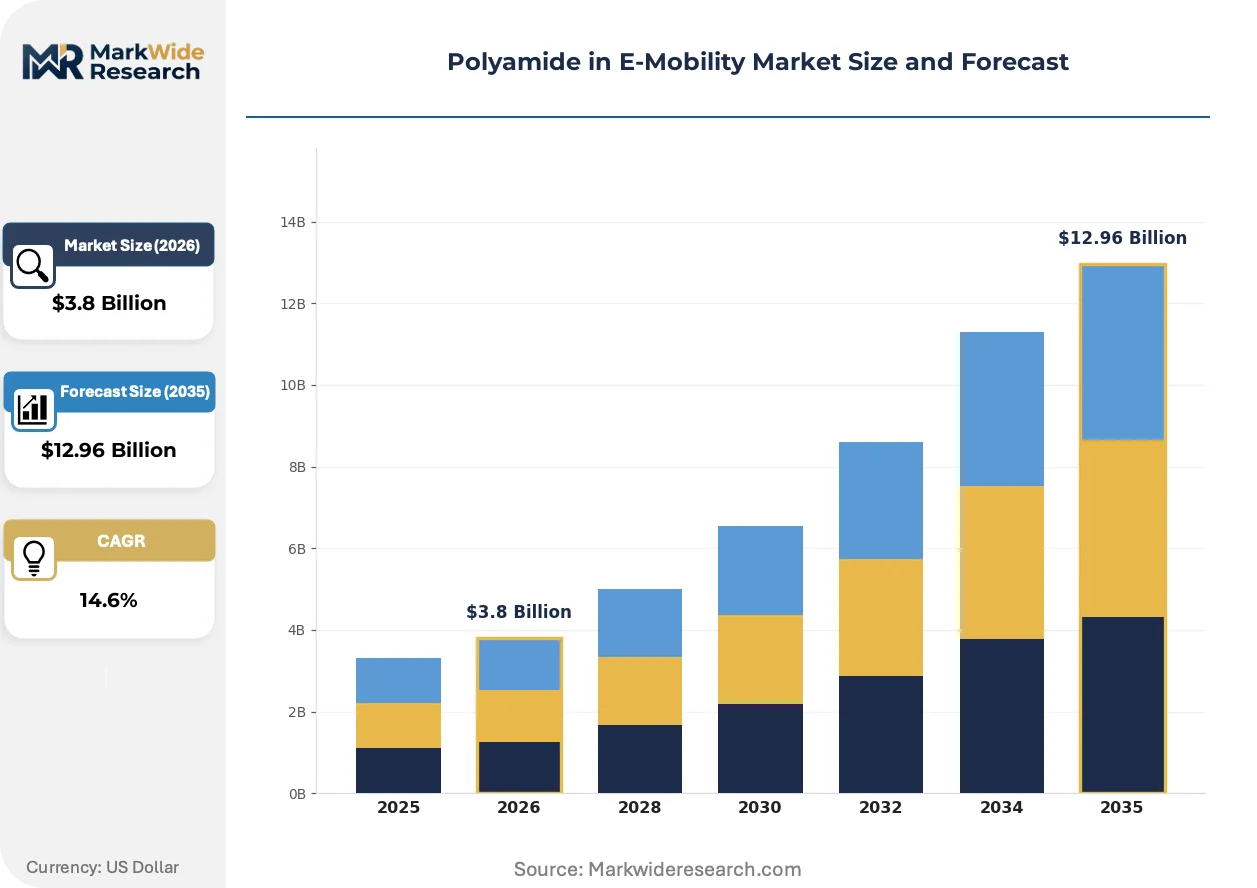
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber, Resin, Film, Sheet Application: Battery Packs, Insulation, Connectors, Housing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Contractors Technology: Injection Molding, Extrusion, 3D Printing, Compression Molding |
| Companies Covered | BASF SE, Arkema SA, DuPont de Nemours, Inc., Lanxess AG, Evonik Industries AG, Teijin Limited, Toyoda Gosei Co. Ltd., Asahi Kasei Corporation, UBE Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyamide in E-Mobility Market Evolving Landscape
Material innovation and regulatory compression are reconfiguring how polyamide compounders compete, with technical differentiation now inseparable from carbon-accounting transparency and regional supply proximity.
Glass-fiber-reinforced PA66 formulations serve as structural battery module carriers and high-voltage connector housings where metal replacement reduces mass. European OEMs specify these grades for 800V architectures, accelerating qualification cycles that previously spanned three product generations. The technology is expanding into thermal runaway propagation barriers, displacing mica sheets and ceramic coatings in pack-level fire containment systems.
REACH restrictions on halogenated flame retardants compound with EU Battery Regulation recycled-content quotas to reshape raw-material sourcing strategies. Compounders must now document mass-balance certificates for post-industrial polyamide feedstocks while reformulating with phosphorus-based and mineral flame retardants. Battery pack manufacturers in Germany and France prioritize suppliers with ECHA-registered alternative chemistries, filtering out commodity compounders lacking regulatory affairs capabilities.
Buyer concentration among tier-1 battery pack integrators compresses supplier negotiation leverage and extends payment terms. Procurement teams at CATL, BYD, and European platform suppliers now mandate carbon-footprint disclosures alongside technical datasheets, favoring compounders with renewable energy certificates in their production footprint. This behavioral shift concentrates contract awards in China's Yangtze River Delta and Germany's Rhine-Ruhr corridor, where renewable-powered compounding capacity scales fastest.
Polyamide in E-Mobility Market Segmentation
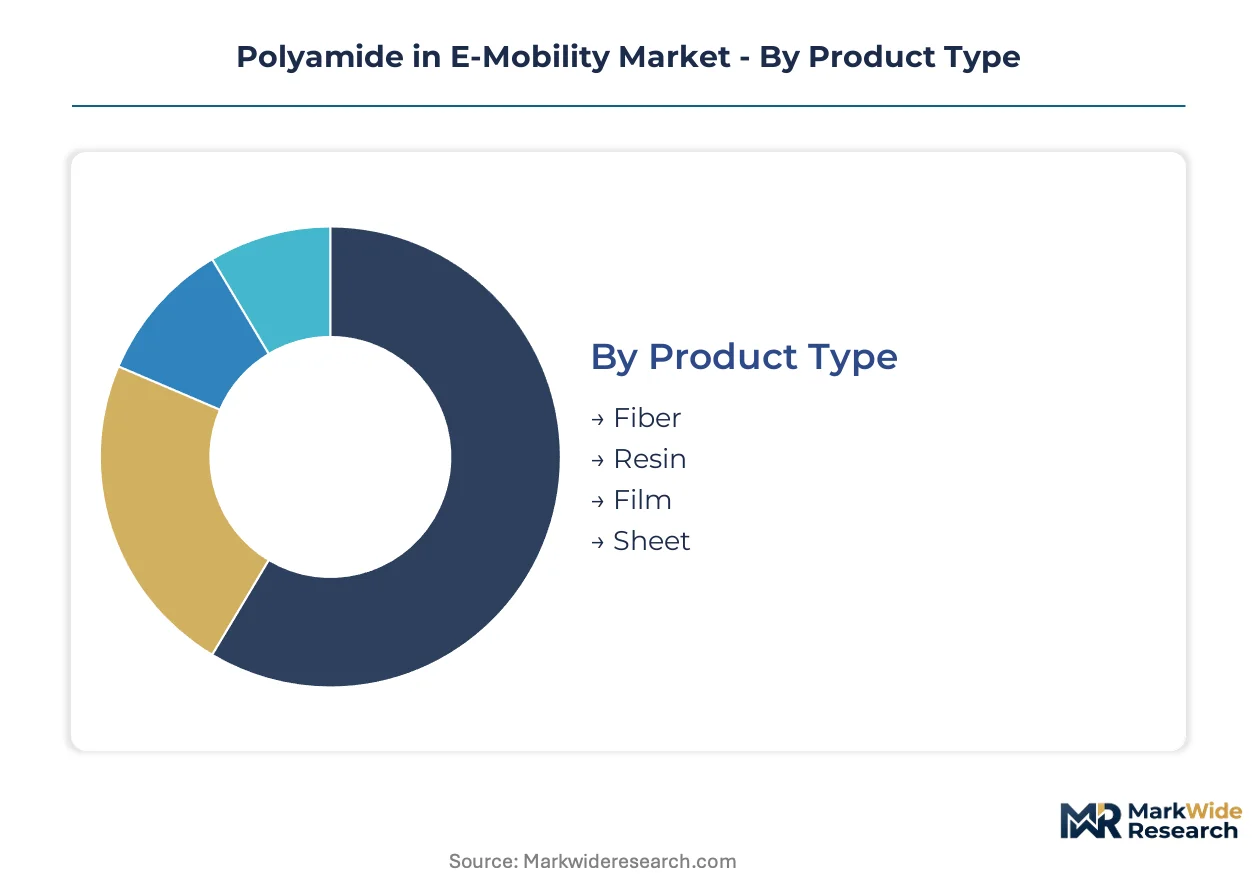
Segmentation in polyamide for e-mobility reveals how material specifications diverge across voltage architectures, processing methods, and supply chain tiers. Each dimension carries distinct margin profiles and qualification barriers that reshape compounder competitiveness.
Product Type:
Upgrade cycles in 800V platforms are forcing material substitutions that favor thermally stable grades over legacy formulations.
- Resin:Glass-fiber-reinforced PA6 and PA66 formulations dominate structural battery module carriers and high-voltage connector housings. Demand concentrates in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta, where CATL and BYD source locally compounded grades meeting 150°C continuous service requirements.
- Fiber:Chopped and continuous glass fiber reinforcements enhance dimensional stability in thermal runaway barriers, displacing mica sheets in pack-level fire containment. European OEMs specify these grades for 800V architectures, accelerating qualification timelines that previously spanned multiple product generations.
- Film:Thin-gauge PA12 and modified PA6 serve as battery cell separator substrates where ionic purity and thermal stability intersect.
- Sheet:Extruded polyamide plates provide electrical insulation barriers between battery cells and pack enclosures.
Resin sits at the top of the volume ranking, with fiber climbing the fastest as thermal propagation standards tighten.
Application:
Cost tiering separates certified grades for high-voltage systems from commodity formulations in auxiliary components.
- Battery Packs:Structural housings, module carriers, and thermal runaway barriers demand heat-stabilized PA66 with continuous operating temperatures above 150°C. China's MIIT energy density thresholds and Germany's KBA flame-spread requirements filter out uncertified suppliers.
- Connectors:High-voltage interlock circuits and busbar housings require flame-retardant formulations meeting UL 94 V-0 without halogenated additives. REACH restrictions on brominated compounds push compounders toward phosphorus-based systems for European platforms.
- Housing:Inverter enclosures and charging port assemblies use glass-filled grades balancing dimensional stability with electromagnetic shielding compatibility.
- Insulation:Cell-to-cell barriers and busbar wraps prioritize dielectric strength and tracking resistance in thin-wall configurations.
Battery packs command the premium tier by certification burden, while connectors expand most quickly with 800V platform proliferation.
End User:
Customer type determines contract structure, with volume commitments and technical collaboration depth varying sharply across tiers.
- OEMs:Volkswagen, BYD, and Tesla specify materials directly for battery enclosures and structural components, mandating carbon-footprint disclosures alongside technical datasheets. Procurement teams extend payment terms and compress supplier margins in exchange for platform-level qualification.
- Tier-1 Suppliers:CATL, LG Energy Solution, and Samsung SDI source compounded resins for connector and housing integration, concentrating demand among compounders with renewable energy certificates.
- Aftermarket Providers:Repair and retrofit operations for legacy EV fleets source commodity grades without platform-specific certification requirements.
- Contractors:Engineering service providers specify materials for prototype builds and low-volume specialty vehicle programs.
OEMs anchor volume concentration, with tier-1 suppliers gaining share fastest as battery pack integrators consolidate procurement.
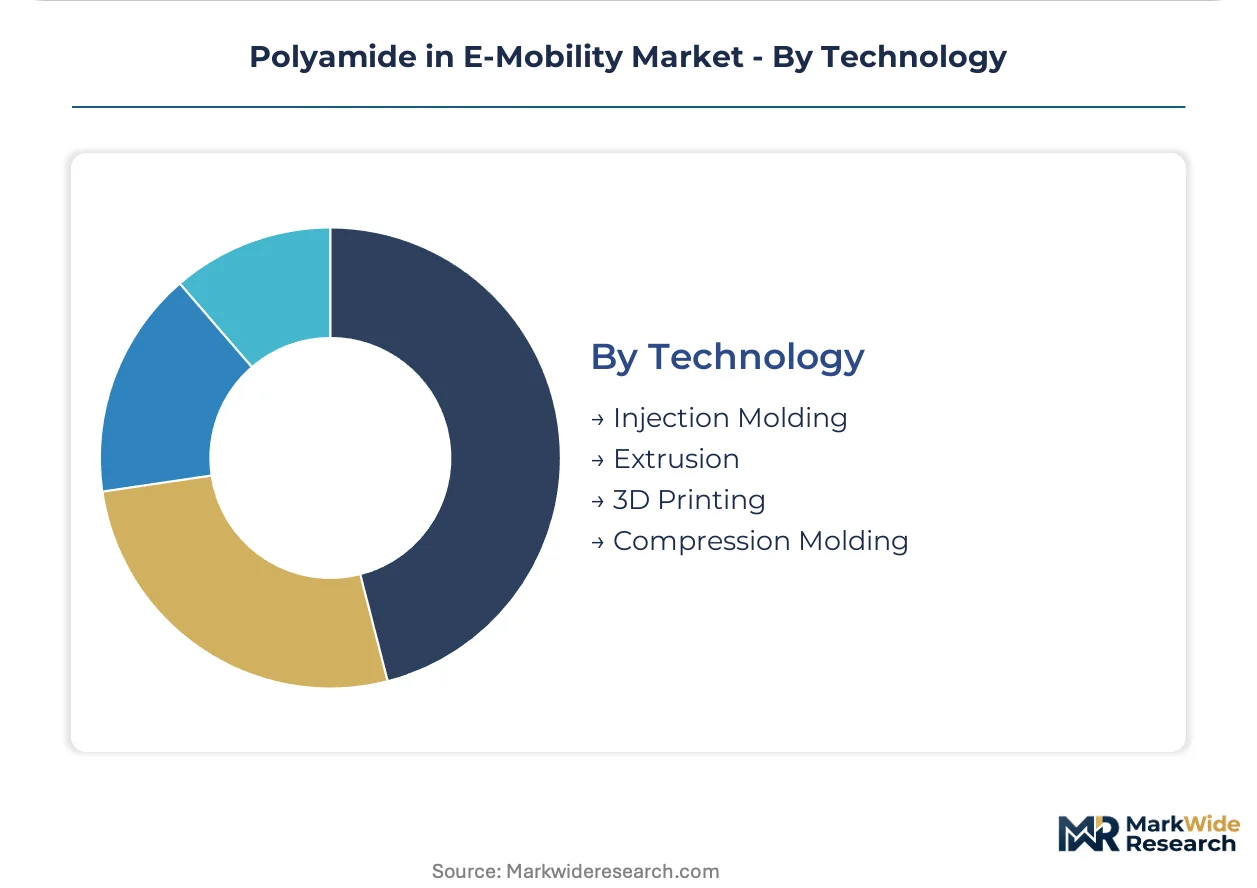
Technology:
Processing method selection hinges on part complexity, wall thickness, and production scale across the e-mobility value chain.
- Injection Molding:Precision forming of complex connector geometries with tight tolerance bands dominates high-voltage applications. Germany's KBA type-approval process enforces dimensional stability validation that favors established molders with documented process control.
- Extrusion:Continuous profile production for film, sheet, and fiber applications serves battery separator and insulation barrier markets.
- 3D Printing:Fused filament fabrication and selective laser sintering enable rapid prototyping of custom connector housings and thermal management components.
- Compression Molding:Sheet molding compound processing for large-format battery enclosure lids and structural reinforcement plates.
Injection molding captures value concentration by precision requirements, with 3D printing expanding most quickly in prototype-to-production workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta cluster sources more compounded polyamide resin than Germany's Rhine-Ruhr corridor, yet both regions face tightening carbon-footprint disclosure mandates from their respective regulators.
China
CATL and BYD anchor demand for heat-stabilized PA66 grades in Jiangsu and Zhejiang provinces. MIIT energy density thresholds tie subsidy eligibility to battery pack performance metrics requiring advanced polymer thermal management. The Yangtze River Delta cluster concentrates EV production lines that source locally compounded resins for connector and housing applications.
Germany
Volkswagen and BMW specify materials directly for 800V battery enclosures and structural components. KBA type-approval processes enforce 18-24 month flame-spread resistance validation cycles for battery enclosures. The Rhine-Ruhr corridor hosts compounders with renewable energy certificates that scale production for European EV platforms.
United States
Tesla and Detroit-based OEMs drive lightweighting mandates through polyamide substitution for aluminum and steel. EPA tailpipe emission rules and NHTSA fuel economy standards intensify material performance requirements. Michigan and Ohio assembly hubs source compounded grades from domestic suppliers meeting UL 94 V-0 specifications without halogenated additives.
France
Renault and Stellantis procurement teams prioritize suppliers with ECHA-registered alternative chemistries for phosphorus-based flame retardant formulations. REACH restrictions on halogenated compounds filter out commodity compounders lacking regulatory affairs capabilities. The Auvergne-Rhône-Alpes region concentrates automotive supplier engineering centers qualifying new polyamide grades.
India
Domestic EV startups and two-wheeler electrification programs expand addressable demand for cost-optimized PA6 formulations. PLI scheme production-linked incentives attract polyamide compounders to establish facilities near Chennai and Pune assembly hubs. Maharashtra and Tamil Nadu industrial corridors develop compounding capacity to serve battery pack integrators qualifying for government subsidies.
Polyamide in E-Mobility Market Competitive Landscape
Top-tier vendors anchor platform-level qualification relationships with OEMs and tier-1 battery pack integrators, while mid-tier compounders compete on regional supply proximity and carbon-accounting transparency. The vendor base stratifies between certified suppliers meeting 150°C continuous service requirements and commodity producers serving aftermarket applications. Three archetypes dominate: integrated petrochemical conglomerates with captive feedstock, specialty polymer houses with formulation expertise, and regional compounders with renewable-powered production. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Within the integrated petrochemical tier, BASF SE and Lanxess AG exemplify European-based conglomerates with backward integration into caprolactam and adipic acid precursors. DuPont de Nemours, Inc. occupies a position among North American specialty polymer houses with long-standing connector specification relationships. Arkema SA represents the bio-based formulation archetype, leveraging castor oil-derived feedstocks for carbon-intensity advantages under EU disclosure mandates.
| Leading Market Players |
|---|
| BASF SE |
| Arkema SA |
| DuPont de Nemours, Inc. |
| Lanxess AG |
| Evonik Industries AG |
| Teijin Limited |
| Toyoda Gosei Co. Ltd. |
| Asahi Kasei Corporation |
| UBE Industries Ltd. |
| Others |
Value Network & Pricing Analysis
EU Battery Regulation recycled-content mandates gate qualified supply access and premium-tier pricing power for compounders serving European EV platforms. Buyers now demand mass-balance certificates alongside technical datasheets, filtering out uncertified suppliers and compressing margins for commodity-grade producers while certified compounders capture pricing premiums.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for glass-fiber-reinforced PA66 grades. Three-tier pricing structure across premium heat-stabilized, standard reinforced, and economy unfilled levels separates certified suppliers from commodity compounders. Price differentiation hinges on KBA flame-spread certification status and renewable energy certificate coverage in production footprints. Cost compression in standard grades is intensifying because adipic acid supply volatility squeezes compounder margins when feedstock benchmarks spike. Aftermarket providers exhibit highest price sensitivity, while OEM procurement teams prioritize technical qualification over unit cost.
Supply Chain Analysis
Material scientist shortages in Germany and China constrain formulation capacity expansion for heat-stabilized grades. Geographic supply concentrates in Germany, China, and the United States, with the Rhine-Ruhr corridor and Yangtze River Delta anchoring certified compounding capacity. Raw material dependencies rest on caprolactam for PA6, adipic acid for PA66, and castor oil derivatives for bio-based PA11. Single-source vulnerability in adipic acid precursor production amplifies disruption risks from plant outages or trade policy shifts. Distribution runs through tier-1 battery pack integrators who consolidate procurement and extend payment terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through premium-grade substitution as 800V architectures displace legacy formulations. Compounders capturing KBA certification early lock in platform-level supply relationships that resist price erosion.
For Market Incumbents: Deploy backward integration into caprolactam and adipic acid precursors to defend margin position against feedstock volatility. BASF SE and Lanxess AG exemplify this approach through captive supply of PA6 and PA66 monomers. Incumbents must simultaneously invest in phosphorus-based flame-retardant formulation capabilities to meet REACH restrictions on halogenated compounds. Certification investment in ECHA-registered alternative chemistries filters out mid-tier competitors lacking regulatory affairs infrastructure.
For New Entrants and Emerging Players: Premium-to-economy price gaps in India's domestic EV segment create white-space opportunities for cost-optimized PA6 formulations. New entrants should target Maharashtra and Tamil Nadu industrial corridors where PLI scheme subsidies attract battery pack integrators qualifying for government incentives. A regional compounding facility near Chennai or Pune assembly hubs offers the most penetrable entry point. Go-to-market positioning as a renewable-powered supplier with carbon-footprint disclosure capabilities aligns with tier-1 procurement mandates.
For Investors and Strategic Acquirers: Roll-up economics work for specialty polymer houses with formulation expertise because platform-level qualification relationships concentrate among a shrinking pool of certified suppliers. Acquisition targets include regional compounders with ECHA-registered chemistries and renewable energy certificates in their production footprint. Long-term viability hinges on 800V architecture proliferation sustaining premium-grade demand. The signal to watch is KBA type-approval timeline compression, which would accelerate revenue recognition for new grade introductions and reward early certification investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Captive precursor supply insulates compounder margins from benzene derivative volatility. |
| Phosphorus-Based Flame Retardant Certification | ECHA-registered chemistries unlock European EV platform procurement contracts. |
| Renewable Energy Certificate Coverage | Carbon-footprint disclosures satisfy CATL and BYD supplier qualification mandates. |
| Regional Compounding in India | PLI scheme proximity captures domestic EV startup demand near Pune assembly hubs. |
| Bio-Based PA11 Scale-Up | Castor oil-derived grades meet EU Battery Regulation recycled-content thresholds. |
Research Methodology
Bottom-up battery pack modeling reconciled against top-down resin production tracking forms the analytical core of this study. Primary interviews with compounder technical directors, OEM platform engineers, tier-1 battery pack procurement leads, and KBA certification specialists combined with secondary validation from MIIT subsidy catalogs, ECHA substance restriction databases, customs trade data, and SEC filings from petrochemical conglomerates. Triangulation across these sources ensures volume estimates align with actual qualification relationships and capacity expansion announcements.
Historical trendline analysis of resin consumption per battery pack across the analysis window established baseline penetration rates for glass-fiber-reinforced grades. Segmentation modeling captured product type, application, end user, and technology dimensions alongside voltage architecture tier and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating MIIT energy density threshold revisions, REACH restriction implementation timelines, and 800V platform rollout schedules. Industry-specific forecast inputs include solid-state battery prototype development trajectories and bio-based feedstock cost curves.
Caveats apply where caprolactam price spikes, adipic acid supply disruptions, or REACH restriction acceleration could materially shift the outlook. Forecasts reflect assumptions about KBA type-approval timeline stability and tier-1 battery pack integrator procurement consolidation patterns. Material deviation in feedstock volatility or regulatory implementation schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Mufflers Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Automotive Silicone Elastomer Market