
 Automotive Sunroof Glass Market | 2026-2036
Automotive Sunroof Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sunroof Glass Market Insights
Project finance tied to dedicated sunroof glass production lines is rewriting competitive entry barriers for mid-tier suppliers. Webasto Group leverages captive bonding and framing capabilities across European assembly corridors. Aisin Corporation anchors its position through in-house control over motorized rail mechanisms paired with glass modules. Fuyao Glass America dominates North American supply through proximity to Detroit-based OEM stamping plants.
Automotive sunroof glass refers to transparent or translucent apertures installed in vehicle roofs, typically fabricated from chemically strengthened soda-lime silica or polyvinyl butyral-interlayer laminates rated for impact resistance and optical clarity, designed to admit natural light while maintaining structural integrity during rollover events. Panoramic glass configurations command the widest installation footprint among premium vehicle architectures, whereas laminated glass technology captures the fastest technology migration as OEMs prioritize shard retention under ECE R43 and FMVSS 205 protocols. Fixed glass variants occupy the most mature demand tier with compressed margin pools, while spoiler glass specializes within coupe segments where aerodynamic integration limits supplier proliferation.
FDA guidelines for polycarbonate optical materials in automotive glazing, EPA fuel-economy credits linked to lightweight glass substitution, and UN ECE R43 homologation standards collectively determine product certification pathways and cross-border market access. NHTSA rollover structural integrity rules further constrain glass thickness and curvature specifications for vehicles sold in the United States. Stakeholders must monitor evolving battery-electric vehicle platform architectures, where flat rooflines and integrated solar glass threaten traditional sunroof penetration rates.
Market Dynamics
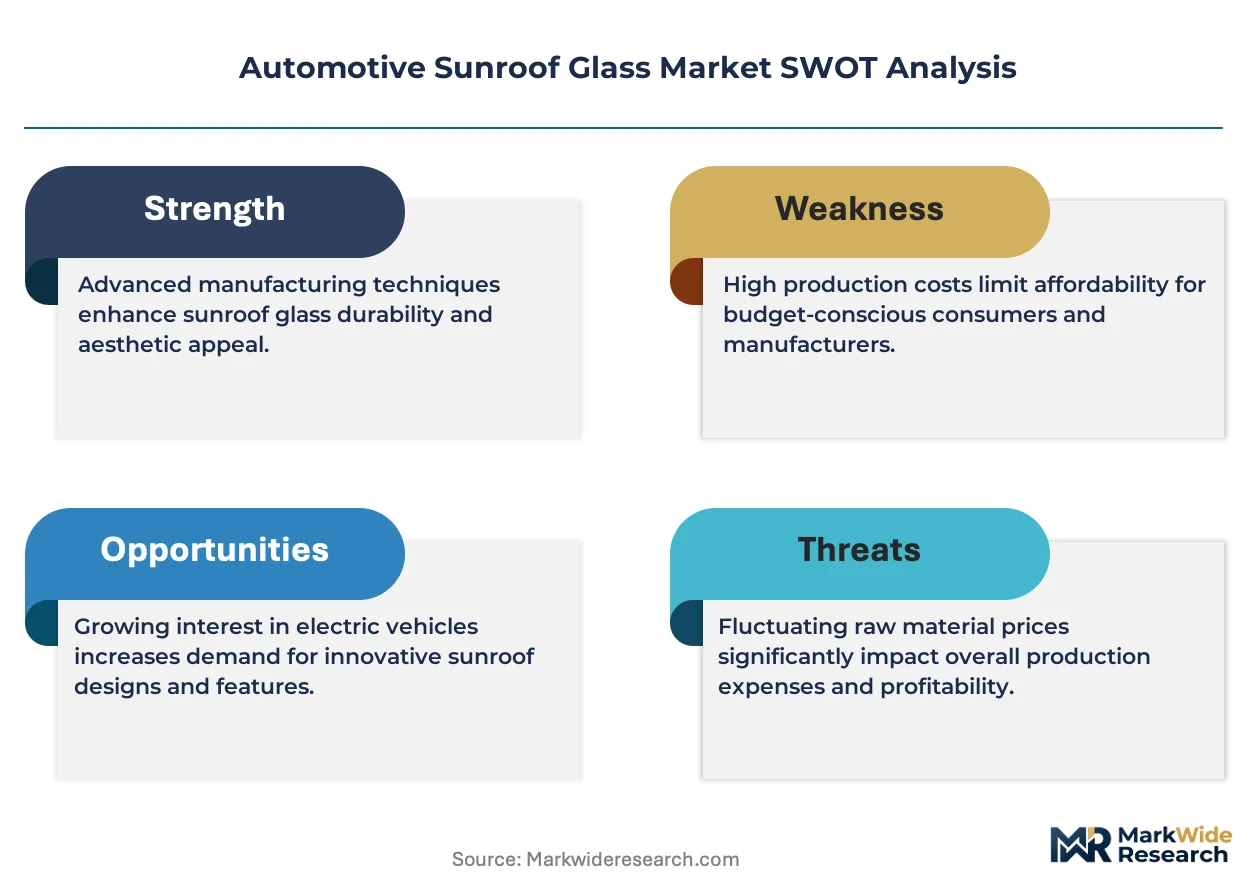
The migration from tempered to laminated glass architectures under stricter occupant-retention mandates is restructuring supplier capability requirements and capital deployment patterns across the value chain.
Growth Catalysts
- UN R43 Homologation:ECE regulations mandating shard retention during rollover events are accelerating laminated glass penetration in European premium vehicle programs.
- Panoramic Configurations:German and US-based SUV OEMs are standardizing full-roof glass apertures across their luxury lineups, expanding addressable glass surface area per vehicle.
- Yangtze River Delta Cluster:Concentrated domestic EV assembly capacity in eastern China is generating localized demand pull for regional glass processors.
Market Restraints
- PVB Interlayer Cost Volatility:Polyvinyl butyral resin prices fluctuate with acetic acid and polyvinyl alcohol feedstock markets, compressing margin predictability for laminate specialists.
- Curvature Specification Limits:Deep-draw glass forming for aerodynamic spoiler applications remains constrained by optical distortion thresholds under FMVSS 205.
- Integrated Solar Glass Substitution:Photovoltaic roof panels on battery-electric platforms threaten traditional sunroof penetration in flat-roof EV architectures.
Strategic Opportunities
- Lightweight Glass Credits:EPA fuel-economy certification pathways reward mass reduction from chemically strengthened thin-glass substitutes.
- Aftermarket Replacement Channel:Independent service networks for damaged panoramic assemblies remain underdeveloped relative to OEM-captive distribution.
- Smart Glass Convergence:Electrochromic interlayer technology paired with laminated modules enables dynamic tinting without mechanical shades.
Industry Challenges
- Bonding Chemistry Expertise Gap:Structural adhesive selection for direct-to-body glazing requires specialized polymer engineering capabilities scarce among mid-tier suppliers.
- Homologation Timeline Compression:Simultaneous UN ECE R43, FMVSS 205, and GB standard compliance for multi-region vehicle programs extends certification cycles.
- Capex Intensity for Lamination Lines:Autoclave and cleanroom investments for PVB processing exceed tempered furnace economics, raising entry barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sunroof Glass Market |
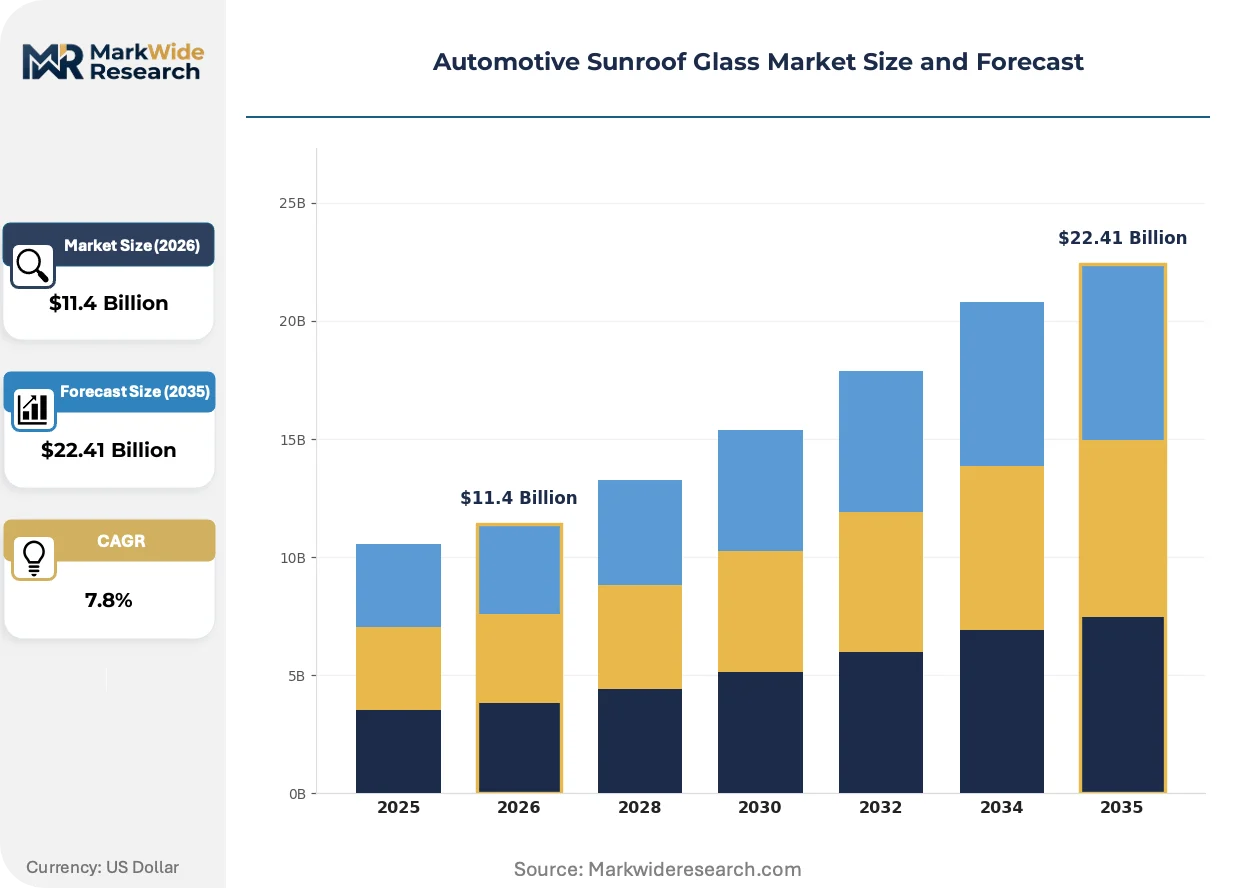
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic Glass, Tilt and Slide Glass, Spoiler Glass, Fixed Glass Technology: Tempered Glass, Laminated Glass, Tinted Glass, UV Protection Glass Vehicle Type: SUV, Sedan, Coupe, Hatchback End User: OEMs, Aftermarket Retailers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Webasto Group, Inalfa Roof Systems Group B.V., Magna International Inc., Aisin Corporation, Inteva Products LLC, CIE Automotive SA, Yachiyo Industry Co. Ltd, AGC Inc., Fuyao Glass America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sunroof Glass Market Trends and Innovations
Material substitution and regulatory convergence are compressing traditional technology lifecycles while opening adjacent functionality domains for glass module suppliers.
Laminated glass architectures are collapsing the historical cost premium over tempered alternatives as autoclave throughput scales and interlayer suppliers achieve formulation standardization. European and North American OEMs are adopting laminated modules across mid-tier vehicle segments previously served by tempered products. This shift is collapsing the addressable market for standalone tempered sunroof processors and redirecting capital toward lamination capacity.
REACH substance restrictions on polycarbonate optical materials are redirecting formulation strategies toward compliant copolymer alternatives in European glazing applications. ECHA candidate list updates targeting bisphenol-A derivatives are forcing material qualification cycles for transparent roof modules. German KBA type-approval processes are extending to cover supply-chain substance documentation, affecting processors serving Stuttgart and Munich-based OEM stamping plants.
Fleet procurement of glass modules is consolidating toward platform-contract structures that bundle sunroof, windshield, and backlight volumes under multi-year agreements. Tier-1 integrators are displacing direct OEM-supplier relationships for glass sourcing, capturing specification influence. This pattern is most visible in Detroit-based OEM supply chains where Fuyao Glass America has secured proximity-located framing and logistics capabilities.
Automotive Sunroof Glass Market Segmentation
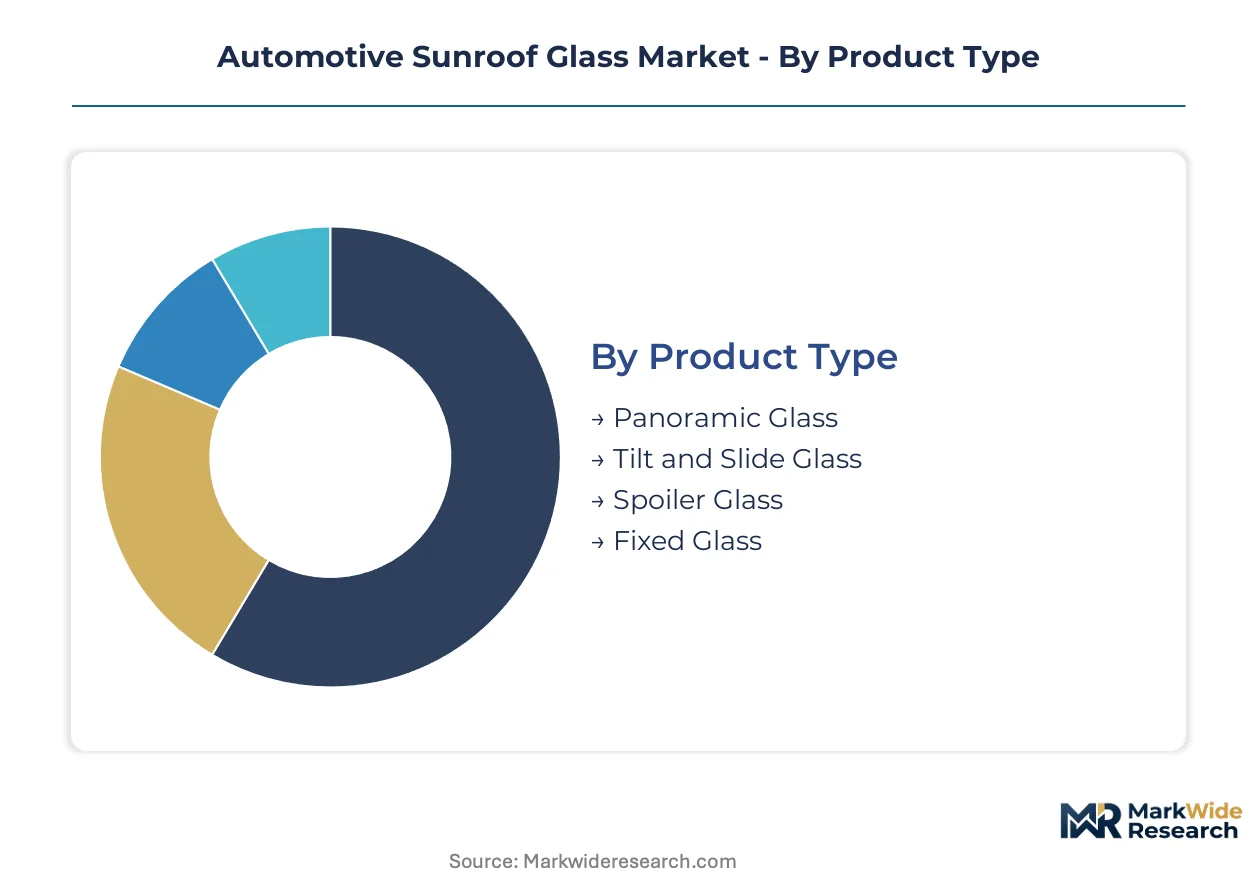
Automotive sunroof glass segmentation reveals distinct margin pools and capability requirements across product architectures, with laminated technologies and panoramic formats commanding premium positioning while fixed variants compete on scale.
Product Type:
Maturity varies sharply across this category, with legacy formats facing displacement while expansive glass configurations capture specification influence in premium vehicle programs.
- Panoramic Glass:Multi-panel laminated assemblies spanning front and rear passenger zones, bonded directly to roof structures without intermediate frames. German SUV OEMs in Stuttgart and Munich are standardizing these configurations across luxury lineups, expanding glass surface area per vehicle by factors of three to four over traditional apertures. This segment concentrates demand pull in China's Yangtze River Delta, where domestic EV assemblers specify full-roof transparency as a brand differentiator.
- Fixed Glass:Non-operable single-pane modules sealed permanently into roof stampings, historically dominant in economy and mid-tier segments. This architecture occupies the most mature demand tier with compressed margin pools, as tempered variants face displacement by laminated alternatives under stricter occupant-retention mandates.
- Tilt and Slide Glass:Mechanized panels combining pop-up ventilation with rearward travel along motorized rails, prevalent in sedan and compact SUV applications.
- Spoiler Glass:Aerodynamically profiled rear-fixed panels integrated into coupe rooflines, constrained by curvature specification limits under FMVSS 205 optical distortion thresholds.
Fixed glass handles the majority of throughput; panoramic configurations are expanding most quickly on share as OEMs prioritize cabin openness in premium segments.
Technology:
Cost tier stratification dominates this category, with lamination investments separating premium-capable suppliers from tempered-glass processors competing on furnace throughput.
- Laminated Glass:Polyvinyl butyral-interlayer constructions rated for shard retention during rollover events, now mandatory under UN ECE R43 homologation for European type approval. Autoclave and cleanroom investments for PVB processing exceed tempered furnace economics, raising entry barriers and consolidating supply toward integrated glass-framing specialists.
- Tempered Glass:Chemically strengthened soda-lime silica subjected to rapid thermal quenching, historically cost-advantaged but losing share to laminated alternatives. This technology faces accelerating displacement as NHTSA structural integrity rules and ECE regulations converge on occupant-retention performance.
- Tinted Glass:Body-tinted substrates reducing solar heat gain without mechanical shade mechanisms, common in sun-belt vehicle specifications.
- UV Protection Glass:Spectrally selective coatings or interlayers blocking ultraviolet transmission, increasingly specified for panoramic applications where passenger exposure is prolonged.
Laminated glass commands the steepest expansion trajectory; tempered variants are surrendering share fastest to regulatory migration.
Vehicle Type:
Application-driven specification intensity varies by body style, with roof architecture determining glass curvature limits and operating mechanism requirements.
- SUV:Dominant end-use for panoramic configurations, with extended rooflines accommodating full-length glass apertures. Detroit-based OEM stamping plants and German luxury assemblers are driving specification convergence toward laminated panoramic modules as standard equipment.
- Sedan:Traditional tilt-and-slide stronghold, though sedan volume contraction in North American and European markets is compressing absolute demand.
- Coupe:Spoiler glass specialization segment, where aerodynamic integration and steeply raked backlight angles limit supplier proliferation to curvature-capable processors.
- Hatchback:Compact fixed-glass applications, with cost-sensitive specifications favoring tempered substrates in emerging-market vehicle programs.
SUVs handle the majority of throughput; coupes are climbing the fastest on specification value per square meter.
End User:
Customer type determines procurement channel structure, with platform-contract consolidation favoring integrated Tier-1 intermediaries over direct OEM-supplier relationships.
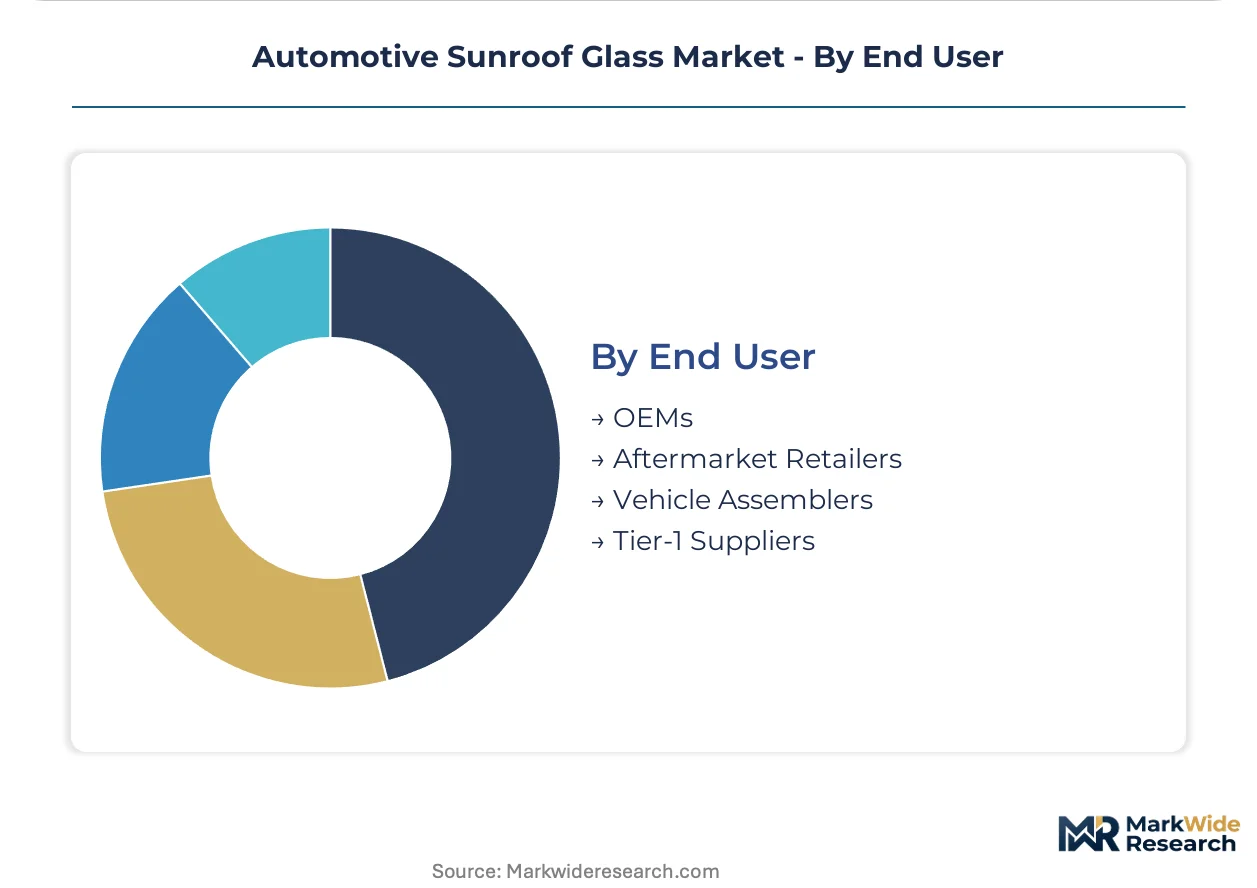
- OEMs:Final vehicle manufacturers specifying glass modules within complete roof systems, increasingly delegating sourcing to Tier-1 integrators under bundled platform contracts. Fleet procurement consolidation is visible in Detroit supply chains, where proximity-located framing capabilities influence supplier selection.
- Tier-1 Suppliers:Roof system integrators capturing specification influence by bundling sunroof, windshield, and backlight volumes under multi-year agreements. Webasto Group and Aisin Corporation anchor positions through captive bonding, framing, and motorized rail capabilities.
- Vehicle Assemblers:Contract manufacturing operations, particularly in China's Yangtze River Delta cluster, sourcing from regional glass processors to serve domestic EV brand portfolios.
- Aftermarket Retailers:Independent service networks for damaged panoramic assemblies, currently underdeveloped relative to OEM-captive distribution channels.
Tier-1 suppliers handle the majority of procurement volume; aftermarket retailers are gaining share fastest as panoramic repair complexity outpaces dealer network capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA fuel-economy credits for lightweight glass substitution and UN ECE R43 homologation mandates are redirecting capital toward laminated capacity in key manufacturing corridors. Regional demand patterns diverge sharply between mature regulatory environments and emerging EV assembly clusters.
United States
Detroit-based OEM stamping plants drive specification pull for proximity-located glass framing operations. NHTSA rollover structural integrity rules constrain curvature specifications for spoiler applications. Michigan and Ohio assembly corridors concentrate Tier-1 integrator investments in bonded module capabilities.
Germany
Stuttgart and Munich-based luxury OEMs standardize panoramic configurations across SUV lineups. KBA type-approval processes extend to supply-chain substance documentation under REACH restrictions. Bavarian and Baden-Württemberg stamping plants anchor European laminated glass demand.
China
Domestic EV assemblers in the Yangtze River Delta specify full-roof transparency as brand differentiation. GB standards compliance runs parallel to ECE homologation for export-bound vehicle programs. Shanghai and Jiangsu-based glass processors serve regional assembly capacity expansion.
Japan
MetI industrial policy supports chemically strengthened thin-glass development for mass-reduction credits. JIS standards govern optical clarity thresholds for panoramic applications. Kansai and Chubu manufacturing belts concentrate precision forming capabilities for coupe spoiler segments.
South Korea
Seoul Capital Area battery-electric platform architects integrate solar roof panels threatening traditional sunroof penetration. MFDS-aligned material qualification cycles govern polycarbonate optical substitutions. Gyeonggi-do and Incheon clusters host glass module integration for Hyundai-Kia export programs.
Automotive Sunroof Glass Market Competitive Landscape
Channel-controlling players compete with product-specialist players for specification influence in roof system procurement. The vendor base separates into three tiers: integrated glass-framing specialists, captive bonding operations, and regional substrate processors. Consolidation pressure favors platform-contract bundling over direct OEM relationships. Dominant competitive moves include autoclave capacity expansion for lamination scale and backward integration into PVB interlayer supply.
Among integrated system architects, Webasto Group and Aisin Corporation exemplify the channel-control archetype through captive mechanism and bonding capabilities. Fuyao Glass America occupies a position among proximity-located substrate specialists serving Detroit corridor demand. These three entities represent the spectrum from full-system integration to regional glass supply, with each archetype defending margin pools through distinct capability depth rather than interchangeable product competition.
| Leading Market Players |
|---|
| Webasto Group |
| Inalfa Roof Systems Group B.V. |
| Magna International Inc. |
| Aisin Corporation |
| Inteva Products LLC |
| CIE Automotive SA |
| Yachiyo Industry Co. Ltd |
| AGC Inc. |
| Fuyao Glass America |
| Others |
Pricing and Supply Chain Analysis
Shanghai and Jiangsu-based glass processors in China's Yangtze River Delta cluster command downstream pricing leverage through captive supply relationships with domestic EV assemblers, while Detroit corridor OEMs squeeze margin pools through platform-contract consolidation toward Tier-1 integrators.
Pricing Analysis
Certification level creates the primary spread between laminated modules meeting UN ECE R43 homologation and tempered variants facing displacement. Three-tier pricing structure separates premium panoramic assemblies from standard tilt-and-slide configurations and economy fixed-glass tiers. Cost compression in tempered segments is intensifying because autoclave scale economies collapse the historical laminate premium. Fleet procurement teams at volume OEMs exhibit highest price sensitivity, whereas luxury SUV program managers prioritize shard-retention performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for North American glass module sourcing. Manufacturing concentrates in China, Germany, and the United States, with each hub serving distinct regulatory compliance pathways. PVB interlayer supply draws from acetic acid and polyvinyl alcohol feedstock markets centered in East Asian petrochemical corridors. Distribution runs through Tier-1 roof system integrators bundling sunroof, windshield, and backlight volumes under multi-year platform agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where roof system modularity and battery-electric vehicle architectures are collapsing standalone glass procurement into bundled subsystem contracts.
For Market Incumbents: Build captive bonding chemistry expertise as a moat against mid-tier suppliers lacking polymer engineering capabilities. Expand autoclave lamination capacity in the Yangtze River Delta to capture domestic EV platform volumes. Secure backward integration into PVB interlayer supply to defend margin pools against resin price volatility. For New Entrants and Emerging Players: Establish a beachhead in the aftermarket replacement channel for damaged panoramic assemblies, where dealer network capacity constraints create service gaps. Target independent glass processors in China's Jiangsu province lacking ECE homologation capabilities for acquisition or partnership. Pursue smart glass convergence through electrochromic interlayer technology licensing as a differentiated entry vector. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because platform-contract bundling favors integrated glass-framing specialists over standalone substrate processors. Target regional processors with proximity-located capabilities serving Detroit or Stuttgart OEM stamping plants. Monitor NHTSA rollover structural integrity rulemaking as the signal for laminated glass penetration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | Scales laminated glass throughput to meet UN ECE R43 homologation mandates across European premium vehicle programs. |
| PVB Interlayer Backward Integration | Captures margin pools currently exposed to acetic acid and polyvinyl alcohol feedstock price volatility. |
| Smart Glass Technology Licensing | Enables electrochromic interlayer deployment for dynamic tinting without mechanical shade mechanisms. |
| Aftermarket Service Network Buildout | Addresses capacity constraints in dealer networks for complex panoramic assembly replacement. |
| Platform-Contract Consolidation | Bundles sunroof, windshield, and backlight volumes under multi-year agreements with Tier-1 integrators. |
Research Methodology
The analysis maps laminated and tempered glass sub-sectors, each validated through primary interviews with Tier-1 supplier procurement teams, OEM platform engineers, aftermarket distributors, and regional glass processor operations managers. Secondary validation draws from vehicle production databases, IHS Markit registration data, UN ECE R43 homologation filings, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up volume triangulation against top-down value estimates ensures segmentation integrity.
Assumptions held fixed include regulatory convergence on UN ECE R43 and FMVSS 205 occupant-retention standards, while battery-electric vehicle platform penetration and solar glass substitution rates were varied across sensitivity bands. The projection horizon spans vehicle class, propulsion architecture, glass technology tier, and regional production cluster dimensions. CAGRs derive from regression against historical content-per-vehicle trajectories and OEM specification trend analysis, with laminate-to-tempered substitution elasticity as a primary demand driver.
Stress conditions across PVB resin price volatility, tariff regime shifts, and integrated solar glass penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline compliance and technology substitution curves. Macroeconomic contraction, accelerated NHTSA rulemaking, or breakthrough thin-glass mass-reduction technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Differential Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Torque Vectoring Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Automotive Resonator Market