
 North America Automotive Hydraulic Actuators Market | 2026-2036
North America Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Hydraulic Actuators Market Analytics
SAE J1939 compliance tier is collapsing the gap between legacy hydraulic systems and electromechanical alternatives across medium and heavy truck platforms. Robert Bosch GmbH leverages its integrated brake control architecture to anchor European-derived technology within Detroit's supplier ecosystem. Parker Hannifin competes through specialized aerospace-to-automotive fluid power transfer, while Magna International dominates contract manufacturing for Detroit Three hydraulic steering programs.
Automotive hydraulic actuators are precision fluid-power devices that convert pressurized hydraulic energy into linear or rotary mechanical motion, typically operating at system pressures between 1,500 and 5,000 psi to enable force multiplication in brake, clutch, and steering subsystems. Their primary commercial purpose centers on delivering high force density in confined spaces where electromagnetic alternatives face thermal or packaging constraints. Linear actuators sustain the largest revenue pool across the product type dimension, reflecting entrenched demand for brake and clutch applications, while compact actuators represent the fastest structural expansion as electric vehicle platforms demand space-efficient thermal management actuation. OEM installation channels anchor volume concentration, though retrofit installation for commercial fleet life-extension programs is gaining structural traction as equipment longevity pressures intensify.
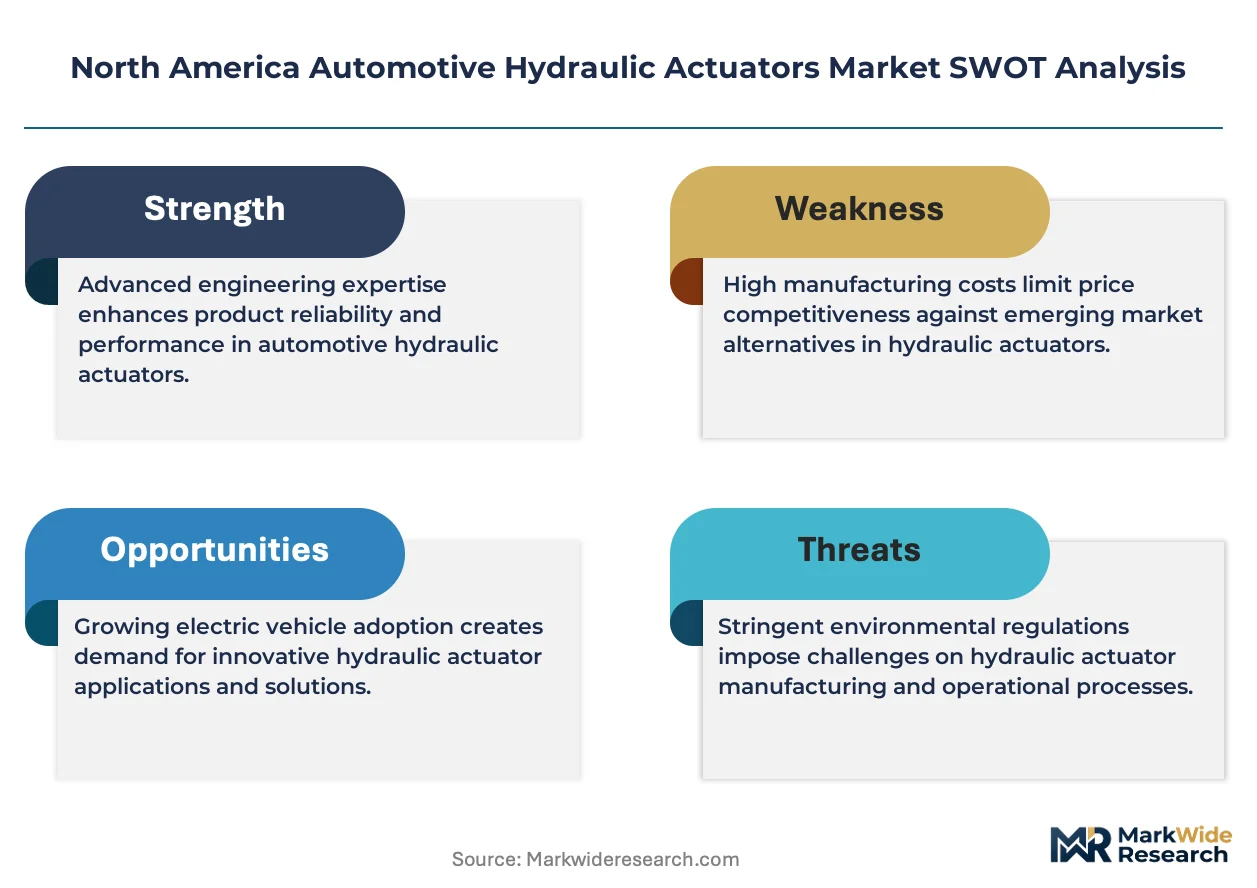
NHTSA Federal Motor Vehicle Safety Standards and EPA emissions compliance frameworks jointly dictate hydraulic actuator sealing, durability, and efficiency benchmarks across United States production. Transport Canada and Environment and Climate Change Canada mirror these requirements through aligned CMVSS regulations, creating a unified North American certification corridor that elevates engineering thresholds for cross-border suppliers. Stakeholders must monitor the divergence trajectory between EPA Phase 3 stringency and provincial zero-emission mandates in California and Quebec, as this regulatory tension will determine whether hydraulic actuation retains relevance or yields to full electromechanical substitution in next-generation platforms.
Market Dynamics
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are compressing the performance envelope for hydraulic actuation, forcing simultaneous weight reduction and efficiency gains while maintaining SAE J1939 protocol compatibility with emerging electromechanical architectures.
Growth Catalysts
- Heavy-duty fleet electrification preparation:Commercial vehicle operators in the United States are retrofitting hydraulic brake and steering systems to extend asset life ahead of platform transitions, sustaining aftermarket demand for precision actuators.
- SAE J1939 protocol harmonization:Unified communication standards across medium and heavy truck platforms are collapsing integration barriers between hydraulic and electronic control systems, accelerating replacement cycles.
- Ontario Tier-1 supplier cluster concentration:Proximity to Detroit Three engineering centers enables rapid prototype-to-production cycles for hydraulic steering programs, compressing supplier qualification timelines.
Market Restraints
- Electromechanical substitution pressure:Full-electric brake-by-wire and steer-by-wire systems from European and Asian suppliers are capturing design wins in next-generation heavy truck platforms.
- Specialized alloy input volatility:High-strength aluminum and titanium alloys essential for weight-reduced hydraulic housings face price instability from concentrated primary metal sourcing.
- Cross-border certification friction:Divergent interpretation of CMVSS versus FMVSS sealing and durability benchmarks between Transport Canada and NHTSA creates redundant testing burdens.
Strategic Opportunities
- Quebec zero-emission commercial vehicle mandates:Provincial fleet electrification timelines create captive demand for lightweight hydraulic thermal management actuation during hybrid transition periods.
- Aerospace-to-automotive fluid power transfer:Specialized sealing and pressure containment technologies from defense and aviation applications are migrating into premium commercial vehicle segments.
- Life-extension retrofit channels:Independent service networks and fleet maintenance depots represent underdeveloped distribution pathways for remanufactured hydraulic steering and clutch actuators.
Industry Challenges
- Mechatronics skill scarcity:Integration of hydraulic hardware with electronic control modules demands cross-trained engineers fluent in both fluid power dynamics and embedded software architecture.
- Legacy platform compatibility burden:Supporting decades-spanning vehicle populations requires maintaining obsolete actuator specifications alongside current production designs, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Hydraulic Actuators Market |
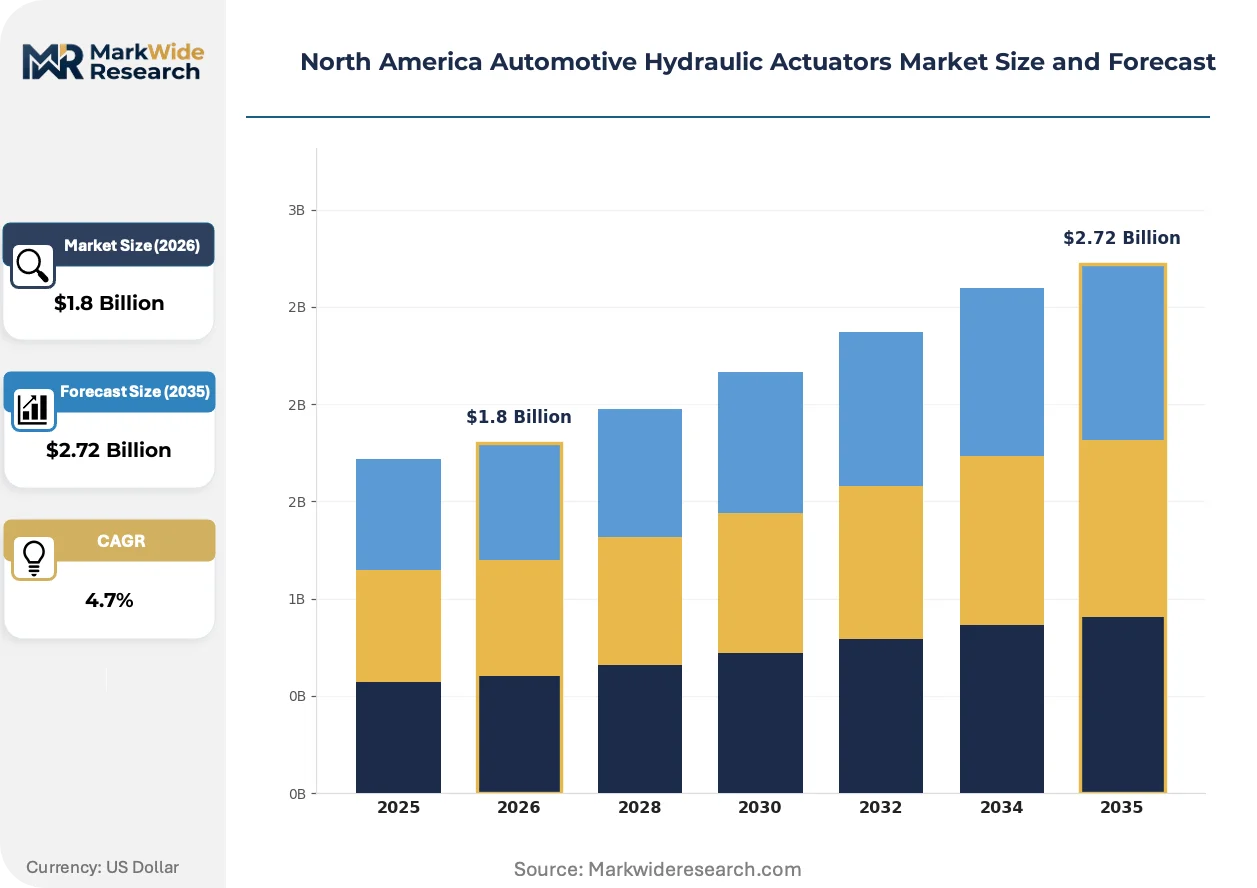
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Compact Actuators, Heavy-Duty Actuators End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: OEM Installation, Retrofit Installation, Standard Installation, Custom Installation Power Source: Electric, Pneumatic, Hydraulic, Mechanical |
| Companies Covered | Robert Bosch GmbH, Nidec Corporation, Denso Corporation, Johnson Electric, Magna International, BorgWarner, Continental AG, Hitachi Ltd, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Hydraulic Actuators Market Evolving Landscape
Actuator architecture is bifurcating between legacy hydraulic dominance in heavy commercial segments and electromechanical encroachment in emerging electric platforms, with hybrid electro-hydraulic systems occupying an expanding transitional middle ground.
Compact high-pressure hydraulic actuators utilizing advanced polymer composite housings are fragmenting the traditional steel-dominated supply base. Fleet operators in Michigan and Ontario are piloting these units for space-constrained electric vehicle thermal management applications. The shift is fragmenting incumbent supplier relationships as aerospace-derived material expertise gains automotive relevance.
NHTSA Federal Motor Vehicle Safety Standard 135 and its Canadian CMVSS 135 counterpart are tightening brake actuator response time and fail-safe requirements for heavy trucks. The regulatory pressure is accelerating development of redundant hydraulic circuits with integrated electronic monitoring. Brake system suppliers serving cross-border manufacturing corridors face the steepest compliance cost escalation.
Commercial fleet procurement is consolidating around total cost of ownership metrics rather than unit price, favoring suppliers offering predictive maintenance telemetry and extended service intervals. Large logistics operators in the United States are unbundling actuator supply from vehicle OEM contracts, creating direct sourcing relationships with specialized hydraulic component manufacturers. This pattern is most visible among long-haul trucking fleets operating across the I-75 manufacturing corridor.
North America Automotive Hydraulic Actuators Market Segmentation
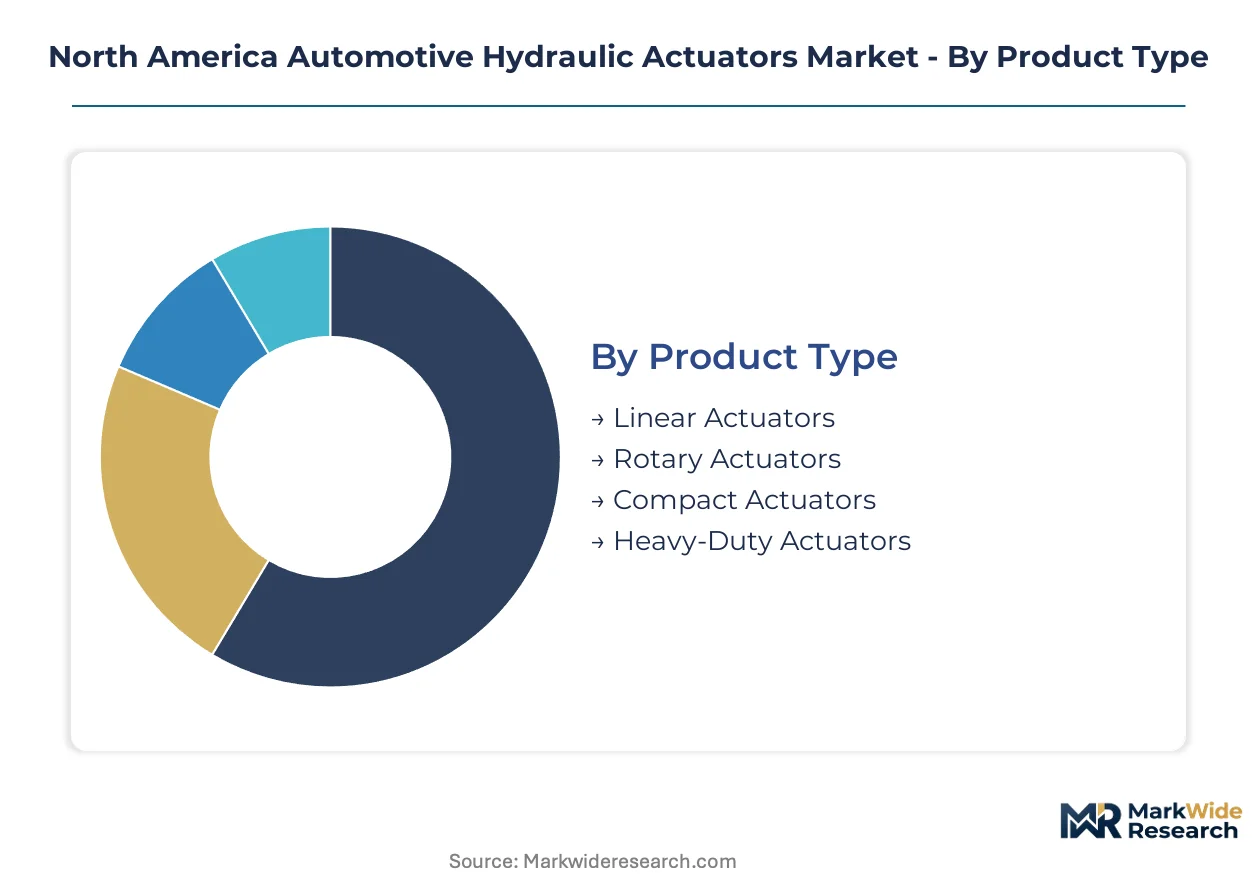
Segmentation in North American automotive hydraulic actuators reveals distinct margin architectures across product types and installation channels. OEM versus aftermarket dynamics diverge sharply in pricing power and technical requirements.
Product Type:
Linear actuators command the widest margin pools due to entrenched brake and clutch applications requiring precision force multiplication. Rotary and compact variants compete on engineering specialization rather than volume scale.
- Linear Actuators:These devices convert pressurized hydraulic energy into straight-line mechanical motion through piston-cylinder architectures operating at 1,500–5,000 psi. Demand concentrates across Michigan's heavy-duty truck manufacturing corridor, where NHTSA FMVSS 135 brake response requirements sustain premium specification tiers. Fleet operators prioritize these units for predictable maintenance intervals.
- Compact Actuators:Space-constrained polymer-composite housings enable thermal management actuation in hybrid electric platforms. Ontario's Tier-1 supplier cluster drives fastest prototype-to-production cycles for these units as Quebec zero-emission mandates compress packaging envelopes. The shift from steel housings fragments incumbent supply relationships.
- Rotary Actuators:Vane and gear-type mechanisms deliver torque multiplication for steering assist applications in medium-duty commercial vehicles.
- Heavy-Duty Actuators:Forged steel construction withstands sustained high-cycle operation in long-haul trucking fleets across the I-75 corridor.
The dominant share belongs to Linear Actuators, while Compact Actuators are closing the gap fastest.
End User:
Volume concentration tilts toward direct OEM relationships, though aftermarket procurement consolidation is rewriting channel economics. Tier-1 suppliers capture disproportionate engineering influence through design-in authority.
- OEMs:Original equipment manufacturers specify actuator architectures during platform development, locking in multi-year supply agreements with hydraulic system integrators. Detroit Three engineering centers in Michigan mandate SAE J1939 protocol compatibility for all new brake and steering programs.
- Aftermarket Providers:Independent service networks and fleet maintenance depots source remanufactured units for life-extension programs. Large logistics operators in the United States are unbundling actuator supply from vehicle OEM contracts, creating direct sourcing relationships with specialized hydraulic component manufacturers.
- Vehicle Assemblers:Final assembly plants in Ontario and Michigan integrate pre-validated actuator modules into completed chassis.
- Tier-1 Suppliers:Contract manufacturers dominate hydraulic steering program production through proximity to Detroit Three engineering centers.
OEMs retain volume leadership, though Aftermarket Providers are expanding share through fleet-direct procurement restructuring.
Installation Type:
Factory-fit channels anchor revenue stability, while retrofit installation gains traction as commercial fleet longevity pressures intensify. Custom installation serves niche applications with specification divergence from standard platforms.
- OEM Installation:Factory-integrated actuators undergo validation against unified NHTSA FMVSS and Transport Canada CMVSS benchmarks. Cross-border manufacturing corridors face redundant testing burdens from divergent sealing and durability interpretations.
- Retrofit Installation:Life-extension programs for heavy-duty commercial vehicle fleets sustain demand as operators delay full platform transitions ahead of electrification. EPA Phase 3 greenhouse gas standards accelerate retrofit activity as fleets seek to extract additional service years from existing assets.
- Standard Installation:Catalog-specified units serve replacement demand through established distribution networks.
- Custom Installation:Application-specific engineering addresses non-standard packaging constraints in specialized commercial vehicle upfits.
OEM Installation holds the largest revenue base, while Retrofit Installation is expanding most quickly through fleet life-extension strategies.
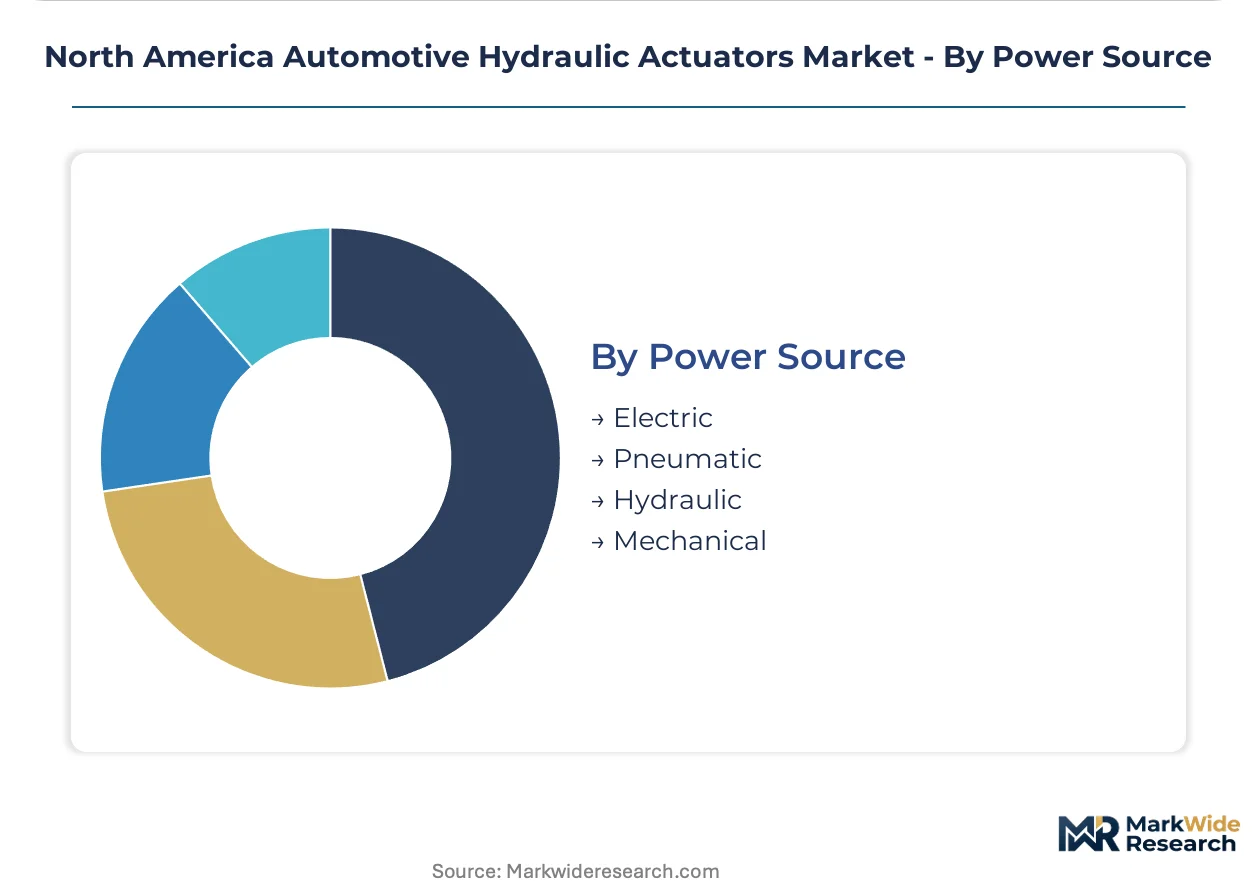
Power Source:
Hydraulic power dominates force density applications where electromagnetic alternatives face thermal or packaging constraints. Electric actuation encroaches on steering functions as electromechanical architectures mature.
- Hydraulic:Pressurized fluid systems deliver force multiplication in confined spaces across brake, clutch, and steering subsystems. SAE J1939 protocol harmonization is collapsing integration barriers between hydraulic hardware and electronic control modules.
- Electric:Motor-driven actuators capture design wins in next-generation heavy truck platforms from European and Asian suppliers. Full-electric brake-by-wire and steer-by-wire systems are displacing hydraulic alternatives in emerging electric vehicle architectures.
- Pneumatic:Compressed air systems serve auxiliary functions in commercial vehicle applications with lower force requirements.
- Mechanical:Direct mechanical linkages persist in legacy platforms and cost-optimized vehicle segments.
Hydraulic power maintains category leadership, while Electric actuation is gaining share fastest through electromechanical substitution in next-generation platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier engineering centers cluster along the I-75 corridor and Ontario's manufacturing belt, creating a unified North American production network for hydraulic actuation systems. Cross-border component flows face certification friction from divergent NHTSA and Transport Canada interpretations. Fleet electrification timelines vary sharply by jurisdiction, fragmenting demand patterns.
United States
Heavy-duty commercial vehicle fleets in Michigan and the broader Midwest are retrofitting brake and steering actuators to extend asset life ahead of electrification transitions. EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are compressing the performance envelope, forcing simultaneous weight reduction and efficiency gains. Detroit's supplier ecosystem anchors prototype-to-production cycles for SAE J1939-compliant hydraulic programs.
Canada
Ontario's Tier-1 supplier cluster drives fastest qualification timelines for hydraulic steering modules through proximity to Detroit Three engineering centers. Transport Canada and Environment and Climate Change Canada enforce CMVSS regulations that mirror NHTSA benchmarks but diverge in sealing and durability testing protocols. Quebec's zero-emission commercial vehicle mandates are creating captive demand for lightweight thermal management actuation during hybrid transition periods.
Mexico
Vehicle assembly plants in Nuevo León and the Bajío Region are integrating pre-validated hydraulic actuator modules for export-oriented heavy truck production. The country's automotive regulator aligns with FMVSS frameworks to maintain US market access for assembled vehicles. Manufacturing investment concentrates in Monterrey's industrial corridor, where labor cost advantages support component sourcing for North American OEMs.
North America Automotive Hydraulic Actuators Market Competitive Landscape
Concentration sits with diversified automotive suppliers possessing integrated brake control architectures and fluid power expertise. The vendor base spans three tiers: European-derived technology anchors with Detroit engineering integration, specialized aerospace-to-automotive transfer specialists, and contract manufacturers dominating hydraulic steering programs. Strategic moves center on SAE J1939 protocol harmonization investments and cross-border capacity positioning to serve unified North American certification corridors.
Among the diversified tier, Robert Bosch GmbH exemplifies European technology anchoring within North American OEM supply chains. Parker Hannifin occupies a position bridging aerospace-derived fluid power into commercial vehicle applications. Magna International represents the contract manufacturing archetype, leveraging Ontario proximity for Detroit Three hydraulic steering program execution.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Nidec Corporation |
| Denso Corporation |
| Johnson Electric |
| Magna International |
| BorgWarner |
| Continental AG |
| Hitachi Ltd |
| Parker Hannifin |
| Others |
Value Network & Pricing Analysis
NHTSA FMVSS 135 and Transport Canada CMVSS 135 certification tiers gate both supplier qualification timelines and price differentiation across brake actuator procurement channels simultaneously. OEMs command premium positioning through validated SAE J1939 protocol compliance, while aftermarket channels compete on remanufactured unit availability and fleet-direct sourcing relationships.
Pricing Analysis
NHTSA FMVSS 135 dictates the pricing tier structure across North American automotive hydraulic actuators, separating premium OEM-validated units from standard aftermarket replacements and economy remanufactured alternatives. Price differentiation rests on certification grade and SAE J1939 protocol integration complexity, with OEM channels capturing the widest margins. Cost compression in the economy tier is intensifying because fleet operators unbundle actuator supply from vehicle contracts and source directly through independent service networks. Aftermarket providers show highest price sensitivity, while OEM platform engineering centers demonstrate lowest sensitivity due to design-in authority and multi-year supply agreements.
Supply Chain Analysis
Port congestion along Pacific trade lanes and container availability constraints on Asia-North America routes are elevating inbound logistics costs for specialized alloy inputs. Manufacturing concentration spans Germany, Japan, and Mexico, with forged steel and high-strength aluminum housings drawing from concentrated primary metal sourcing. Single-source vulnerability persists for aerospace-derived polymer composite materials migrating into compact actuator thermal management applications. Distribution runs through Tier-1 supplier clusters in Ontario and Michigan, with cross-border component flows facing redundant testing burdens from divergent NHTSA and Transport Canada sealing interpretations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance telemetry and extended service interval bundling represent a service-attach opportunity expanding faster than hardware unit sales across commercial fleet procurement channels. Fleet operators now unbundle actuator supply from OEM contracts to capture total cost of ownership advantages through direct component manufacturer relationships.
For Market Incumbents: Shield core OEM platform relationships through accelerated SAE J1939 protocol harmonization investments and captive supply of remanufactured units for aftermarket life-extension programs. Electromechanical substitution pressure from European brake-by-wire suppliers demands backward integration into polymer composite housing production to defend margin position in compact actuator segments. Certification investment in unified NHTSA-Transport Canada testing protocols reduces cross-border qualification friction for Detroit Three engineering center programs. For New Entrants and Emerging Players: Anchor in Quebec zero-emission commercial vehicle mandate timelines, where hybrid transition periods create captive demand for lightweight thermal management actuation before full electrification displacement. The retrofit installation channel for heavy-duty fleet life-extension programs offers the most penetrable entry point, with independent service networks and fleet maintenance depots representing underdeveloped distribution pathways. A go-to-market angle centered on predictive maintenance telemetry integration differentiates against incumbent hardware-only positioning. For Investors and Strategic Acquirers: EPA Phase 3 greenhouse gas standard stringency reshapes the acquisition landscape toward suppliers possessing simultaneous weight-reduction and efficiency-gain capabilities across hydraulic and electro-hydraulic architectures. Long-term viability over the next decade hinges on positioning within hybrid transition platforms rather than legacy hydraulic dominance or pure electromechanical capture. Acquisition target archetypes include aerospace-to-automotive fluid power transfer specialists with polymer composite expertise. The signal to watch is divergence trajectory between EPA Phase 3 enforcement and California-Quebec zero-emission mandate acceleration, which determines whether hydraulic actuation retains design-in relevance or yields to full substitution.| Strategic Initiative | Industry Significance |
|---|---|
| SAE J1939 Protocol Harmonization Investment | Collapses integration barriers between hydraulic hardware and electronic control modules across Detroit Three platforms. |
| Polymer Composite Housing Manufacturing Scale-Up | Captures thermal management actuation demand from Quebec zero-emission commercial vehicle mandates. |
| Predictive Maintenance Telemetry Platform Launch | Aligns with fleet procurement consolidation around total cost of ownership metrics rather than unit price. |
| Cross-Border Certification Corridor Expansion | Reduces redundant testing burdens from divergent NHTSA and Transport Canada sealing interpretations. |
| Retrofit Channel Distribution Partnership | Penetrates underdeveloped independent service networks and fleet maintenance depot pathways for remanufactured units. |
Research Methodology
The analysis maps linear actuator brake applications, compact actuator thermal management systems, rotary steering assist mechanisms, and heavy-duty long-haul trucking units, each validated through Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet maintenance operations. Primary interviews with hydraulic system integrators and electronic control module specialists combined with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS filing records, and EPA Phase 3 compliance disclosures. Bottom-up segment sizing and top-down market reconciliation ensured cross-verification across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from segment-level growth trajectory modeling incorporating EPA regulatory stringency indices, fleet electrification preparation timelines, and SAE J1939 adoption curves. Forecast inputs included commercial vehicle production forecasts, heavy-duty fleet age demographics, and cross-border manufacturing corridor investment patterns.
Material uncertainties — electromechanical substitution velocity, specialized alloy price volatility, and regulatory divergence between EPA Phase 3 and provincial zero-emission mandates — sit outside the modeled envelope. Forecasts reflect documented assumptions about hybrid platform persistence and hydraulic-electronic integration architecture longevity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Global Automotive Water Separation Systems Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
China Automotive Composites Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Global Automotive Gears Market
Automotive Components
Automotive Push Rods Market