
 US Automotive Glass Fiber Composites Market | 2026-2036
US Automotive Glass Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive Glass Fiber Composites Market Analytics
Aftermarket service revenue is narrowing as OEMs push longer warranty periods and captive maintenance networks. Owens Corning dominates North American glass fiber supply with backward integration into raw borosilicate processing. Huntsman Corporation LLC differentiates through proprietary epoxy resin systems tailored for automotive RTM cycles. PPG Industries controls specialty coatings that protect glass fiber substrates from thermal degradation in underhood applications.
US Automotive Glass Fiber Composites consist of woven or chopped E-glass fibers embedded in thermoset or thermoplastic polymer matrices, typically achieving tensile strengths of 300-600 MPa with densities 25-30% below comparable steel grades. These materials primarily enable mass reduction in body-in-white structures, closures, and semi-structural modules where crash energy management and corrosion resistance outweigh raw material cost premiums. Exterior applications lead volume consumption as Class A surface quality requirements drive infusion-processed SMC formulations for fenders, hoods, and tailgates. Chassis segments represent the fastest-growing application area as electric vehicle architectures adopt glass-reinforced leaf springs, battery tray supports, and control arms to offset battery pack mass. Prepreg technology occupies premium positioning where aerospace-derived autoclave processing transfers to low-volume performance automotive platforms.
NHTSA Corporate Average Fuel Economy standards and EPA greenhouse gas emissions rules directly mandate fleet-wide mass reduction, creating binding demand pull for glass fiber substitution in metal-intensive components. OSHA workplace exposure limits for respirable crystalline silica influence manufacturing site selection and automation investment across US production facilities. California Air Resources Board zero-emission vehicle mandates indirectly amplify composite demand through battery electric vehicle platform proliferation. Stakeholders must monitor evolving EPA lifecycle assessment methodologies that may recalibrate material selection criteria beyond tailpipe emissions to full production-chain carbon accounting.
Market Dynamics
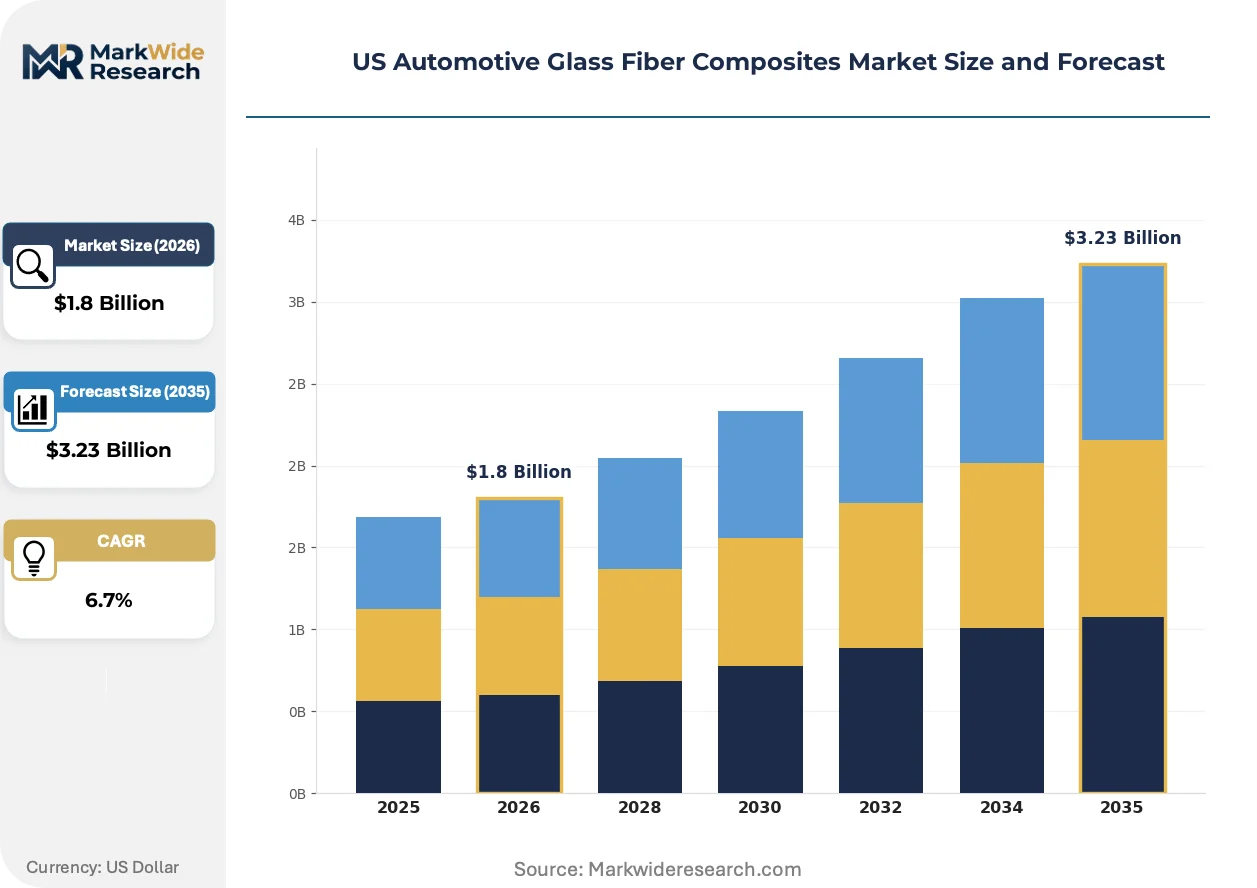
Electric vehicle platform proliferation is compressing development cycles and forcing material substitution decisions earlier in the design phase, locking glass fiber composites into multi-year supply agreements before traditional metal tooling commitments solidify.
Growth Catalysts
- NHTSA Corporate Average Fuel Economy standards:Binding fleet-wide mass reduction mandates create non-negotiable demand pull for lightweight structural substitution in body-in-white assemblies.
- Resin transfer molding cycle acceleration:Huntsman Corporation's proprietary epoxy systems enable sub-ten-minute cure times, expanding glass fiber feasibility from low-volume panels to high-throughput closure modules.
- Michigan manufacturing corridor concentration:Proximity to Detroit Three engineering centers reduces qualification timelines and enables same-day design iteration for composite-intensive EV architectures.
Market Restraints
- Raw borosilicate supply concentration:Owens Corning's backward integration into mineral processing creates single-source dependency risk for E-glass fiber feedstock across North American tier suppliers.
- Carbon fiber substitution pressure:BMW and Mercedes-Benz performance divisions increasingly specify carbon-reinforced plastics for structural battery enclosures, compressing glass fiber's addressable premium segment.
- OSHA respirable crystalline silica limits:Workplace exposure thresholds below fifty micrograms per cubic meter force capital-intensive automation retrofits at legacy chopping and milling facilities.
Strategic Opportunities
- Texas Gulf Coast resin hub expansion:Proximity to petrochemical feedstock enables integrated SMC compounding operations serving southern US assembly plants with reduced logistics premiums.
- Autoclave-derived prepreg technology transfer:Aerospace processing expertise from Boeing suppliers is migrating to low-volume performance automotive platforms seeking Class A surface quality without steel stamping investment.
- California Air Resources Board zero-emission vehicle mandates:Battery electric vehicle production quotas indirectly amplify composite demand through battery tray support and thermal management module proliferation.
Industry Challenges
- Multi-material joining expertise scarcity:Adhesive bonding and mechanical fastening of glass fiber to aluminum extrusions requires specialized simulation capabilities absent from traditional body shop engineering teams.
- Crashworthiness certification timeline compression:NHTSA NCAP testing protocols for composite-intensive structures demand extended physical validation cycles that conflict with twenty-four-month EV platform development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive Glass Fiber Composites Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Reinforcements, Tubes, Mouldings Application: Exterior, Interior, Chassis, Components Technology: RTM, Hand Lay-Up, Infusion, Prepreg End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Solvay Group, 3B (Braj Binani Group), Owens Corning, Veplas Group, SAERTEX GmbH & Co.KG, Hexcel Corp., Huntsman Corporation LLC, PPG Industries, Inc., ASAHI FIBER GLASS Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive Glass Fiber Composites Market Evolving Landscape
Material processing methodologies are bifurcating between high-speed thermoplastic compression for volume applications and precision thermoset infusion for structural performance segments, with equipment suppliers retooling press lines to accommodate both chemistries.
Sheet molding compound formulations are migrating from traditional polyester-vinyl ester hybrids to hybrid thermoplastic-thermoset matrices that enable in-mold recycling of production scrap. Tier One suppliers in Ohio and Tennessee are retrofitting existing compression presses with infrared preheating stations to accommodate these transitional materials. The shift is compressing raw material waste rates from fifteen percent to under five percent while extending tool life through reduced abrasive filler content.
EPA lifecycle assessment methodologies under development for automotive material selection are recalibrating procurement criteria beyond tailpipe emissions to encompass full production-chain carbon accounting. Glass fiber suppliers with renewable energy certificates for melting operations are securing preferred supplier status with Detroit Three sustainability procurement teams. The regulatory trajectory is forcing composite manufacturers to document Scope Three emissions from boron mining through final component delivery.
Fleet procurement departments are consolidating specification authority previously dispersed across individual vehicle program teams, centralizing material selection decisions at corporate engineering centers in Michigan. This concentration is displacing regional supplier relationships with national framework agreements that prioritize scale economies over geographic proximity. The behavioral shift is most visible in battery electric vehicle platform sourcing, where single composite specifications now span multiple assembly plants.
US Automotive Glass Fiber Composites Market Segmentation
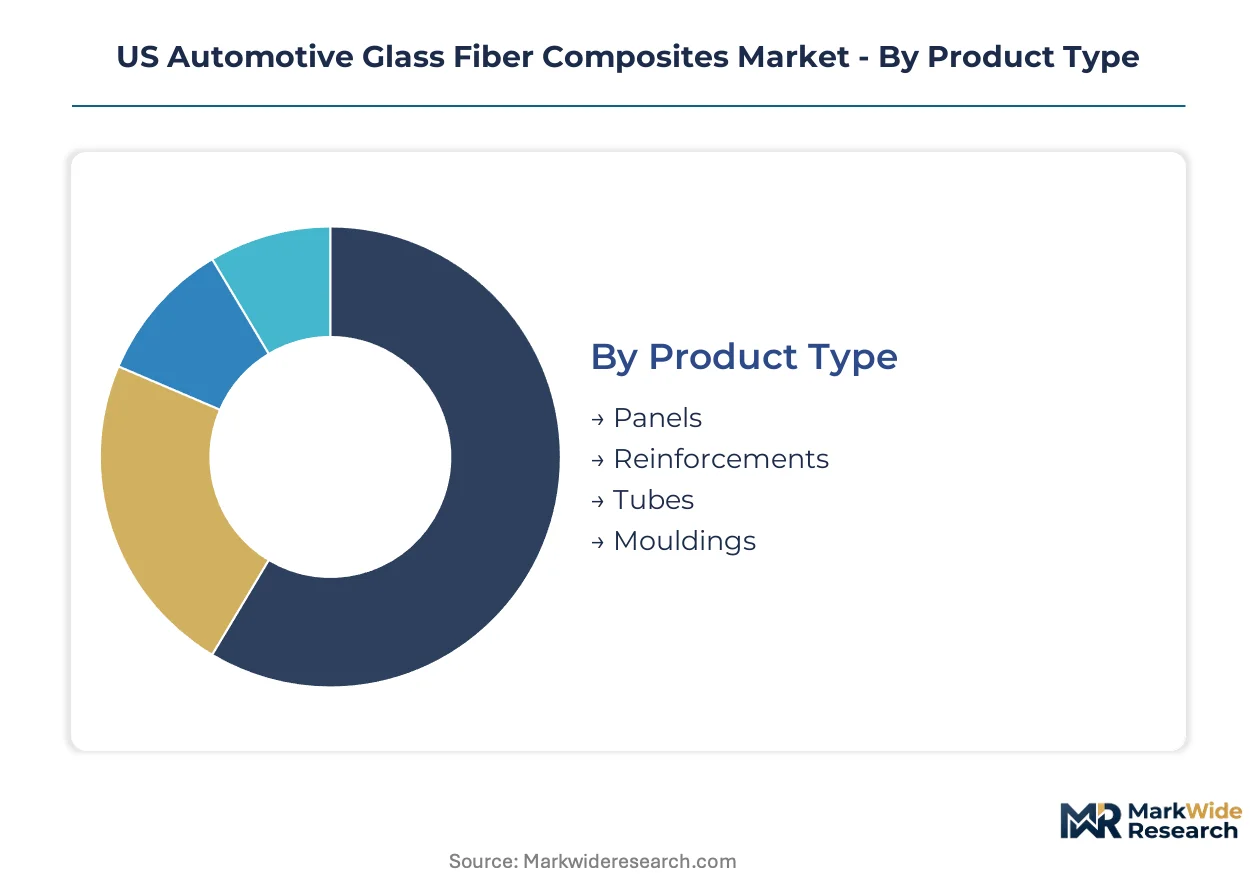
Segmentation in US automotive glass fiber composites reveals distinct technical and commercial fault lines. Product specifications diverge sharply between Class A exterior panels and structural reinforcements, while application demands reshape manufacturing location decisions across Michigan, Ohio, and Tennessee corridors.
Product Type:
After-sales service intensity varies dramatically across product categories, with exterior panels generating warranty claims at three times the rate of structural reinforcements due to UV degradation and impact damage exposure.
- Panels:Large-format E-glass skins with gel-coated surfaces achieve Class A finish standards for hoods, fenders, and tailgates. Michigan-based OEM engineering centers specify these for electric vehicle platforms where mass reduction targets exceed 25% versus steel equivalents. NHTSA pedestrian safety standards are forcing thicker, energy-absorbing panel designs that increase raw material consumption per vehicle.
- Reinforcements:Chopped or continuous fiber mats embedded in structural matrices provide stiffness without weight penalties in load-bearing applications. Demand concentrates in Tennessee and Kentucky assembly plants serving southern US markets, driven by battery tray support requirements for electric vehicle architectures. OSHA silica exposure rules are accelerating automation investment in reinforcement cutting operations.
- Tubes:Pultruded hollow sections serve drive shafts, bumper beams, and crash structures with tailored fiber orientation for torsional rigidity.
- Mouldings:Complex three-dimensional shapes integrate mounting features and attachment points through compression or injection molding processes.
By volume, Panels leads. By growth pace, Reinforcements is ahead.
Application:
Cost tier differentiation separates exterior applications commanding premium pricing from chassis components where raw material efficiency dominates procurement decisions.
- Exterior:Body panels, fascias, and closures require UV-stable gel coats and paint-adhesion primers meeting OEM finish warranties. Ohio and Indiana stamping plant conversions are creating regional demand clusters as Detroit Three electrify truck platforms. EPA lifecycle assessment methodologies are recalibrating material selection criteria toward production-chain carbon accounting.
- Chassis:Leaf springs, control arms, and battery tray structures exploit directional fiber properties for stiffness-to-weight optimization. Texas and California electric vehicle assembly plants are specifying glass-reinforced chassis modules to offset battery pack mass. NHTSA NCAP testing protocols demand extended physical validation cycles for composite-intensive structures.
- Interior:Structural seat backs, load floors, and trim carriers replace metal stampings where noise-vibration-harshness performance matters.
- Components:Discrete brackets, housings, and covers integrate multiple functions through net-shape molding processes.
Exterior commands the revenue share. Chassis is expanding most quickly.
Technology:
Volume throughput separates high-cycle thermoplastic compression from precision thermoset infusion, with equipment suppliers retooling press lines for chemistry flexibility.
- RTM:Resin transfer molding injects catalyzed thermoset resin into closed molds containing preplaced fiber preforms. Huntsman Corporation's proprietary epoxy systems enable sub-ten-minute cure times, expanding feasibility from low-volume panels to high-throughput closure modules at Michigan assembly plants.
- Prepreg:Pre-impregnated fiber sheets with controlled resin content enable aerospace-derived autoclave processing for low-volume performance platforms. Boeing supplier expertise is migrating to specialty automotive applications in California and Washington state where Class A surface quality justifies capital-intensive processing.
- Hand Lay-Up:Manual fiber placement and resin application serves prototype development and ultra-low-volume specialty vehicles.
- Infusion:Vacuum-assisted resin distribution through dry fiber stacks accommodates large, complex geometries with consistent fiber volume fractions.
RTM dominates unit volume. Prepreg shows the steepest expansion trajectory.
End User:
Customer type fragmentation concentrates specification authority at corporate engineering centers, displacing regional supplier relationships with national framework agreements.
- OEMs:Detroit Three corporate engineering centers in Michigan centralize material selection decisions across multiple assembly plants. Fleet procurement departments now control specifications previously dispersed across individual vehicle program teams, prioritizing scale economies over geographic proximity.
- Tier-1 Suppliers:Magna, Lear, and Faurencia operations in Ohio and Tennessee compound SMC and mold components under long-term supply agreements locked in before traditional metal tooling commitments solidify.
- Vehicle Assemblers:Electric vehicle specialists in California and Texas specify composite-intensive platforms from greenfield designs without legacy metal stamping infrastructure.
- Aftermarket Providers:Collision repair networks and performance upgrade specialists serve niche replacement and customization demand.
OEMs anchor volume demand. Vehicle Assemblers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass fiber composite consumption patterns diverge sharply across US sub-regions, with Michigan engineering centers driving specification authority while Texas and California assembly plants reshape demand profiles through electric vehicle platform proliferation.
Michigan
Detroit Three corporate engineering centers concentrate material selection decisions for multi-plant supply agreements. NHTSA fuel economy standards bind fleet-wide mass reduction mandates that lock glass fiber into body-in-white designs before metal tooling commitments finalize. Tier One suppliers cluster in Warren and Auburn Hills to enable same-day design iteration for composite-intensive EV architectures.
Ohio
Stamping plant conversions in Toledo and Cleveland create regional demand clusters as electrified truck platforms replace steel-intensive legacy designs. EPA lifecycle assessment methodologies are recalibrating procurement criteria toward production-chain carbon accounting. Owens Corning operates backward integration into borosilicate mineral processing from facilities serving the regional automotive corridor.
Tennessee
Battery tray support requirements for electric vehicle architectures drive reinforcement demand at Spring Hill and Chattanooga assembly plants. OSHA respirable crystalline silica exposure limits below fifty micrograms per cubic meter force automation investment in chopping and milling operations. Huntsman Corporation supplies proprietary epoxy resin systems to regional RTM facilities from nearby compounding operations.
California
Zero-emission vehicle mandates from the California Air Resources Board amplify composite demand through battery electric platform proliferation. Tesla and Rivian greenfield designs specify glass-reinforced chassis modules without legacy metal stamping infrastructure. Prepreg technology transfers from Boeing suppliers in Washington state serve low-volume performance platforms seeking Class A surface quality.
Texas
Gulf Coast petrochemical feedstock proximity enables integrated SMC compounding operations serving southern US assembly plants with reduced logistics premiums. Glass-reinforced leaf springs and control arms offset battery pack mass in electric vehicle platforms produced at regional facilities. PPG Industries supplies specialty coatings protecting substrates from thermal degradation in underhood applications.
US Automotive Glass Fiber Composites Market Competitive Landscape
Capability concentration sits with integrated raw material processors; scale advantage sits with diversified chemical conglomerates. The vendor base organizes around three strategic archetypes: backward-integrated fiber manufacturers controlling borosilicate supply, specialty resin formulators enabling process acceleration, and coating specialists protecting thermal degradation pathways. Dominant competitive moves include captive supply chain integration and aerospace-derived technology transfer to automotive platforms.
Among integrated fiber producers, Owens Corning anchors the North American supply base through in-house mineral processing operations. Specialty chemical positioning is exemplified by Huntsman Corporation LLC and its epoxy resin systems tailored for automotive RTM cycles. PPG Industries occupies the protective coatings tier with thermal management solutions for underhood glass fiber substrates. These three entities represent distinct capability vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Solvay Group |
| 3B (Braj Binani Group) |
| Owens Corning |
| Veplas Group |
| SAERTEX GmbH & Co.KG |
| Hexcel Corp. |
| Huntsman Corporation LLC |
| PPG Industries, Inc. |
| ASAHI FIBER GLASS Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Raw borosilicate processing concentration in Owens Corning's North American mineral operations anchors margin capture upstream, leaving Tier One compounders and molders to compete on cycle-time efficiency and logistics proximity rather than material sourcing leverage. Glass fiber pricing power concentrates with integrated fiber manufacturers while downstream value pools shift toward resin formulators enabling sub-ten-minute cure technologies.
Pricing Analysis
Long-term offtake contracts dominate volume procurement between Detroit Three OEMs and Tier One suppliers, compressing spot market liquidity and locking in multi-year resin and fiber pricing before vehicle program launches. Three-tier pricing structure across aerospace-grade prepreg, automotive RTM formulations, and industrial SMC compounds separates qualification-intensive applications from commodity replacement panels. Pricing pressure stems from carbon fiber substitution in structural battery enclosures as BMW and Mercedes-Benz performance divisions compress glass fiber's premium segment addressability. Fleet procurement departments exhibit lowest price sensitivity for Class A exterior panels where finish warranty liability outweighs raw material premiums, while aftermarket collision repair networks face acute cost compression from captive OEM parts pricing.
Supply Chain Analysis
Tariff exposure between US and Chinese boron compound suppliers dominates raw material risk matrices, forcing Owens Corning's backward integration into domestic mineral processing as a structural hedge. E-glass fiber production draws from US borosilicate deposits, Mexican milled fiber operations, and Canadian chemical processing for binder systems. Single-source vulnerability concentrates in Huntsman Corporation's proprietary epoxy resin systems serving Michigan RTM facilities. Distribution runs through just-in-time pipeline deliveries from Ohio and Tennessee compounding centers to assembly plants, with rail-bulk resin shipments from Texas Gulf Coast petrochemical hubs supplementing regional supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive glass fiber composites are entering a cyclical recovery phase as electric vehicle platform proliferation restarts capital deployment cycles paused during internal combustion engine retrenchment. NHTSA fuel economy standard tightening provides the cyclical driver binding fleet-wide mass reduction mandates regardless of powertrain architecture.
For Market Incumbents: Build switching-cost moats through captive qualification pipelines that lock composite specifications into multi-year EV platform supply agreements before metal tooling commitments solidify. Deepen backward integration into borosilicate mineral processing to neutralize raw feedstock concentration risk. Defend against carbon fiber substitution by accelerating RTM cycle times below ten minutes, collapsing the processing cost gap that currently constrains glass fiber to closure panels rather than structural battery enclosures. For New Entrants and Emerging Players: Establish a beachhead in Texas Gulf Coast SMC compounding operations serving southern US electric vehicle assembly plants with reduced logistics premiums versus Midwest supply corridors. Target chassis reinforcement applications for battery tray supports where directional fiber properties command stiffness-to-weight premiums absent from commodity exterior panels. Pursue aerospace-derived prepreg technology transfer partnerships with Boeing supplier networks in Washington state to access low-volume performance automotive platforms seeking Class A surface quality without steel stamping infrastructure investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Tier One automotive suppliers holding long-term Detroit Three contracts but lacking resin formulation capabilities in-house. Five-to-ten-year viability hinges on electric vehicle platform share trajectories and the durability of NHTSA mass reduction mandates through regulatory administration transitions. Watch EPA lifecycle assessment methodology finalization as the inflection signal that recalibrates procurement criteria toward production-chain carbon accounting, advantaging suppliers with renewable energy certificates for melting operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Processing | Owens Corning's captive mineral operations neutralize tariff exposure and secure E-glass fiber feedstock for Tier One suppliers. |
| RTM Cycle Acceleration Partnership | Huntsman Corporation's sub-ten-minute epoxy cure systems expand glass fiber feasibility from low-volume panels to high-throughput closure modules. |
| Texas Gulf Coast SMC Compounding Expansion | Proximity to petrochemical feedstock enables integrated operations serving southern US assembly plants with reduced logistics premiums. |
| Aerospace Prepreg Technology Transfer | Boeing supplier expertise migrates to low-volume performance automotive platforms in California seeking Class A surface quality. |
| Renewable Energy Certificate Procurement | Glass fiber melting operations with documented clean energy sourcing secure preferred supplier status with Detroit Three sustainability teams. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier One supplier procurement directors, RTM facility operations managers, and aftermarket collision repair network operators and refined through secondary validation across vehicle production databases, IHS Markit registration data, NHTSA fuel economy compliance filings, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up triangulation across individual assembly plant composite content estimates converged with top-down market sizing from resin and fiber shipment volumes reported in ACC industry aggregates.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from elasticity-adjusted volume projections calibrated to NHTSA fleet compliance trajectories and EPA emissions rule stringency pathways. Forecast inputs incorporated electric vehicle platform proliferation rates, RTM equipment installation cycles at Tier One facilities, and OSHA silica exposure limit enforcement intensity across chopping and milling operations.
Stress conditions across raw borosilicate supply disruption, carbon fiber price erosion, and NHTSA regulatory rollback scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EV platform share trajectories and lifecycle assessment methodology adoption timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Hubcaps Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Europe Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
China Automotive Composites Market
Automotive Components
Global Automotive Active Body Panel Market