
 Germany Automotive Hydraulic Actuators Market | 2026-2036
Germany Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Hydraulic Actuators Market Foresight
Market Context
Capital-intensity divergence between in-house forging capacity and outsourced precision machining is rotating competitive advantage toward vertically integrated suppliers. Robert Bosch GmbH leverages captive foundry operations to control cylinder-head actuator costs for brake and steering modules. Continental AG sustains R&D intensity through dedicated hydraulics labs in Frankfurt am Main. Knorr-Bremse AG dominates pneumatic-hydraulic hybrid systems for commercial vehicle braking.
Technical Definition and Segments
Germany automotive hydraulic actuators are fluid-power devices converting pressurized oil into mechanical force, typically operating at 100–200 bar for chassis systems and up to 350 bar for brake-by-wire applications, enabling precise motion control in powertrain and safety-critical vehicle functions. Linear actuators lead unit volume in suspension and steering systems, while integrated actuator modules capture disproportionate margin pools through embedded sensor fusion and ECU co-packaging. Electro-hydraulic technology is displacing pure hydraulic architectures in premium brake systems, though proportional valve designs retain cost advantages in mass-market transmission actuation.
Regulatory Frame
KBA type-approval requirements and EU Green Deal fleet emission targets shape product roadmaps, compelling actuator suppliers to reduce parasitic hydraulic losses and enable brake-energy recuperation. REACH chemical restrictions and RoHS substance limits constrain seal and coating material choices, adding compliance cost layers. Stakeholders must monitor KBA enforcement of UN ECE braking regulations and EU battery-hydraulic integration standards for electrified platforms.
Market Dynamics
Electro-hydraulic brake actuators are compressing pure hydraulic architectures as German OEMs chase EU Green Deal fleet standards, forcing suppliers to retool cylinder-head production lines and recalibrate forging-to-machining cost structures.
Growth Catalysts
- EU Green Deal fleet emission mandates:CO2 reduction targets compel brake-energy recuperation systems, expanding procurement of electro-hydraulic actuators for regenerative braking architectures.
- Baden-Württemberg supplier ecosystem density:Concentrated chassis and powertrain hydraulics R&D infrastructure accelerates prototype-to-production cycles for integrated actuator modules.
- Brake-by-wire pressure thresholds:Operating requirements up to 350 bar drive demand for high-pressure cylinder-head designs in premium vehicle platforms.
Market Restraints
- Seal material input cost volatility:REACH chemical restrictions and RoHS substance limits constrain fluoroelastomer and coating choices, adding compliance cost layers to actuator manufacturing.
- Forging capacity supply concentration:Captive foundry operations at vertically integrated suppliers lock out mid-tier competitors from cost-competitive cylinder-head production.
- Pure hydraulic substitution threat:Proportional valve designs retain cost advantages in mass-market transmission actuation, slowing electro-hydraulic penetration in volume segments.
Strategic Opportunities
- Electrified platform battery-hydraulic integration:UN ECE braking regulation evolution creates white space for actuator suppliers co-packaging ECU and sensor fusion in integrated modules.
- Commercial vehicle pneumatic-hydraulic hybrid systems:Heavy-duty braking applications under KBA type-approval frameworks offer margin expansion through specialized actuator configurations.
- Suspension linear actuator sensor fusion:Embedded position-feedback integration enables tiered pricing stratification across premium chassis control systems.
Industry Challenges
- Hydraulics-specific mechatronics skill scarcity:Cross-functional talent combining fluid-power engineering with ECU firmware development commands wage premiums in Baden-Württemberg and Frankfurt am Main clusters.
- Legacy brake system integration complexity:Electro-hydraulic architectures must maintain backward compatibility with existing hydraulic infrastructure during multi-year platform transition cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Hydraulic Actuators Market |
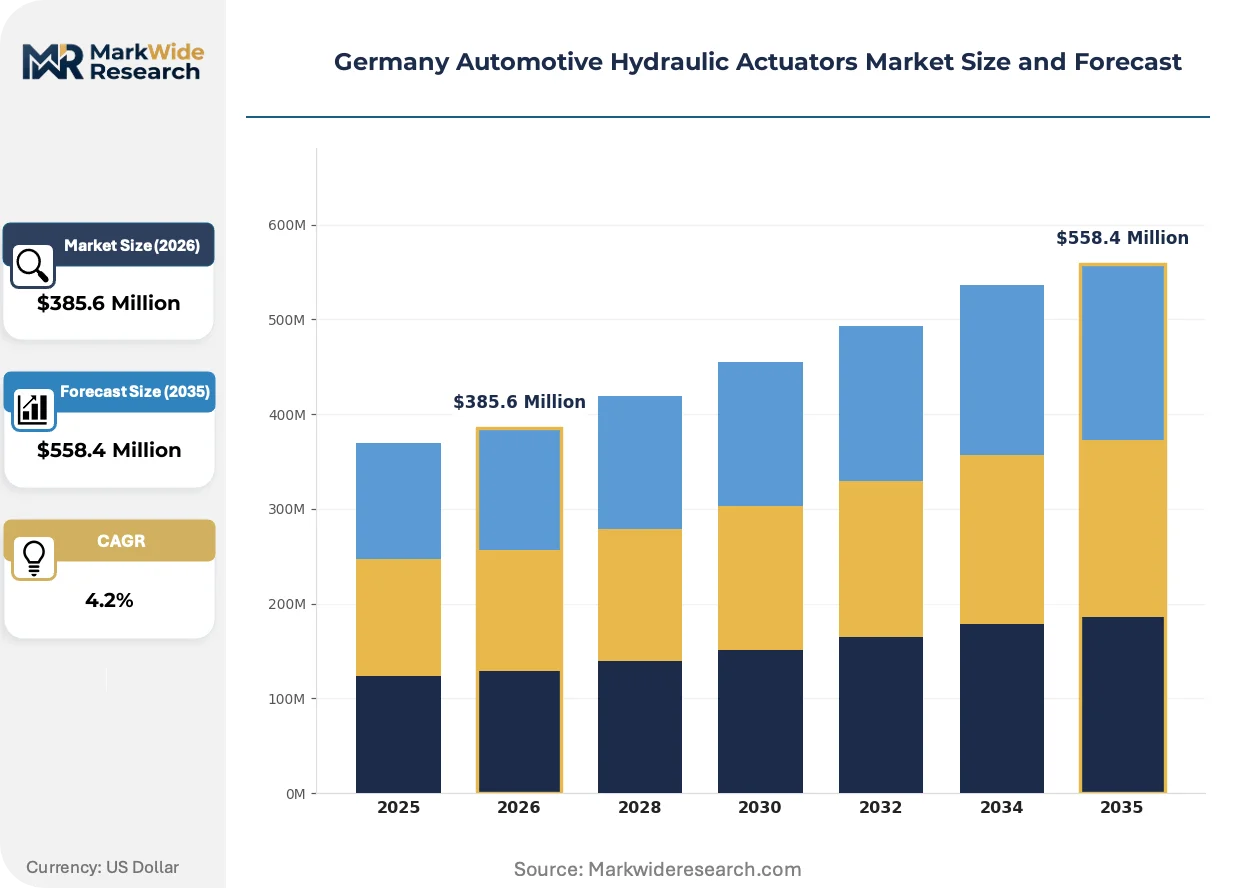
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Telescopic Actuators, Integrated Actuator Modules Technology: Electro-Hydraulic, Proportional Valve, Servo-Hydraulic, Direct-Acting, Pilot-Operated Application: Power Steering Systems, Brake Systems, Suspension Systems, Transmission Systems End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Wabco Holdings Inc., Denso Corporation, Continental AG, Mahle GmbH, BorgWarner Inc., Robert Bosch GmbH, Sonceboz SA, Knorr-Bremse AG, Hella KGaA Hueck & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Hydraulic Actuators Market Shifts & Advancements
Actuator architectures are bifurcating between modular open systems and tightly integrated proprietary stacks, with sensor fusion and ECU co-packaging emerging as the primary axis of product differentiation.
Electro-hydraulic brake actuator technology is fragmenting competitive positioning across German OEM supply chains. Bosch and Continental are deploying divergent cylinder-head designs for 350-bar brake-by-wire applications. This fragmentation is compressing margin pools for pure hydraulic suppliers locked into 100–200-bar chassis system architectures.
KBA enforcement of evolving UN ECE braking regulations is accelerating hardware redesign cycles. Suppliers must pre-certify integrated actuator modules for battery-hydraulic compatibility on electrified platforms. The commercial vehicle segment faces the steepest compliance timeline compression as type-approval frameworks tighten.
Fleet procurement departments are consolidating brake actuator specifications across premium and volume nameplates. Tier-1 suppliers face compressed switching cycles as OEMs reduce qualified vendor lists to capture scale economies. This concentration is most visible in Baden-Württemberg, where Bosch and Continental supply agreements now span multiple VW Group and Mercedes-Benz platforms.
Germany Automotive Hydraulic Actuators Market Segmentation
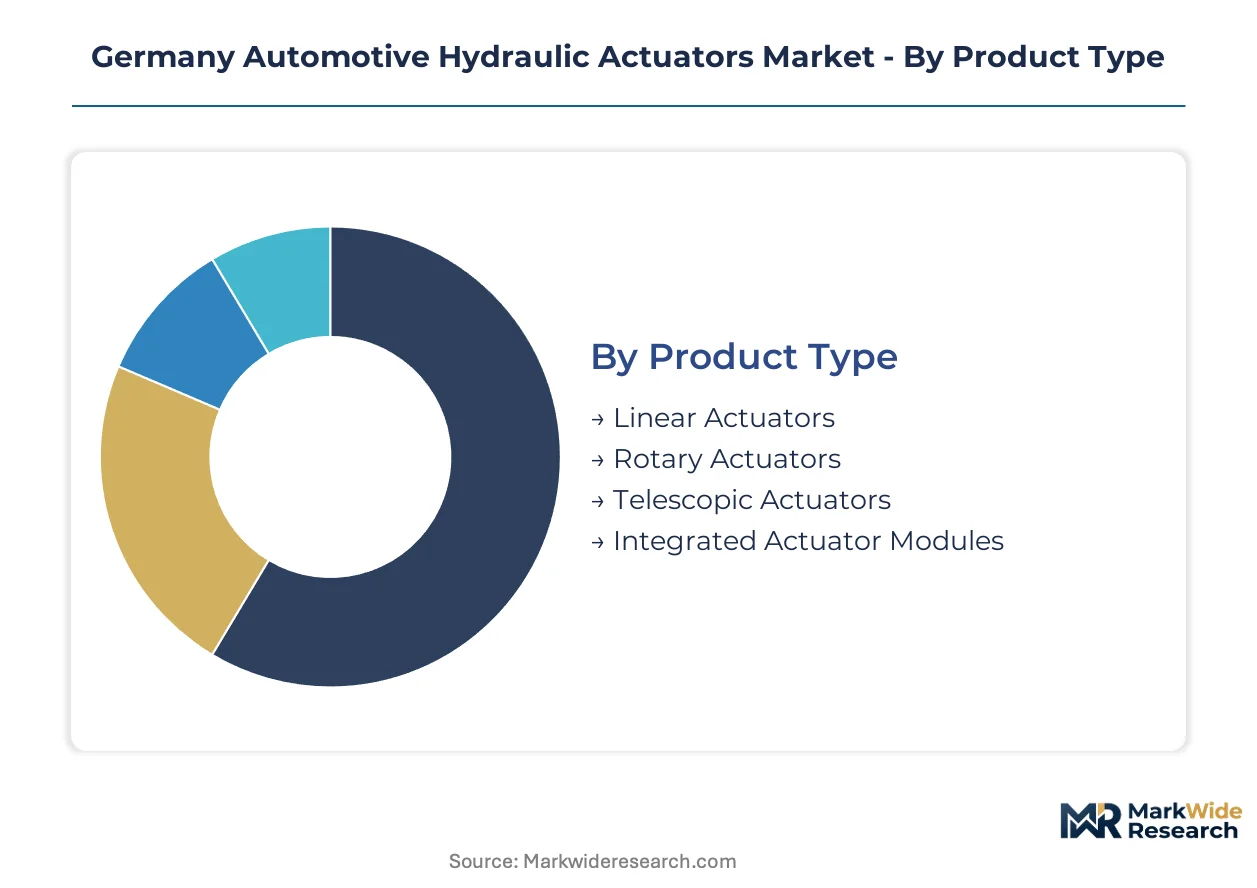
German automotive hydraulic actuator segmentation reveals divergent pressure points across product architectures. Substitution threats from electro-mechanical alternatives and brake-by-wire electrification reshape competitive intensity differently across linear, rotary, and integrated module categories.
Product Type:
Linear actuator configurations face the most acute substitution pressure from electromechanical alternatives in chassis applications, while integrated modules build defensive moats through ECU co-packaging complexity.
- Linear Actuators:Cylindrical piston-rod assemblies operating at 100–200 bar dominate suspension and steering linkages across Baden-Württemberg production clusters. Demand concentrates in Mercedes-Benz and Porsche premium chassis programs where precise position control justifies hydraulic retention over electromechanical alternatives.
- Integrated Actuator Modules:Self-contained units combining valve bodies, position sensors, and embedded ECUs resist substitution through firmware-dependent system integration. Procurement from Bosch and Continental supply agreements now spans multiple VW Group platforms, locking in specification consolidation.
- Rotary Actuators:Vane and gear-type designs convert fluid pressure into rotational motion for limited-slip differential and all-wheel-drive coupling applications.
- Telescopic Actuators:Multi-stage cylinder arrangements deliver extended stroke lengths for commercial vehicle cab tilt and heavy-equipment hydraulic functions.
Linear actuators retain volume leadership across German OEM procurement; integrated actuator modules hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium electro-hydraulic architectures from mass-market proportional valve designs, with pressure thresholds and certification complexity determining pricing bands.
- Electro-Hydraulic:Solenoid-controlled valve systems enabling brake-energy recuperation operate at up to 350 bar for brake-by-wire applications. KBA type-approval requirements for UN ECE braking regulations concentrate demand in premium Mercedes-Benz and BMW electrified platforms.
- Proportional Valve:Continuous-flow control devices maintain cost advantages in transmission clutch actuation and variable valve timing systems. Procurement from VW Group volume nameplates sustains manufacturing scale at Continental hydraulics labs in Frankfurt am Main.
- Servo-Hydraulic:Closed-loop feedback systems deliver precise force control for active suspension and steering assist functions.
- Direct-Acting:Unpiloted spool valves provide rapid response for emergency brake assist and stability control interventions.
- Pilot-Operated:Two-stage valve configurations manage high-flow requirements in commercial vehicle air-over-hybrid braking systems.
Proportional valve technology commands the largest installed base; electro-hydraulic architectures are gaining share fastest in premium platform integration.
Application:
Application-driven segmentation tracks divergent electrification timelines, with brake and power steering systems facing accelerated displacement while suspension hydraulics retain longer technology cycles.
- Brake Systems:Electro-hydraulic actuators for regenerative braking architectures face the steepest procurement expansion as German OEMs pursue EU Green Deal fleet emission targets. Operating pressure requirements up to 350 bar drive specification differentiation between Bosch and Continental cylinder-head designs.
- Suspension Systems:Active damper and anti-roll control actuators resist electromechanical substitution through force density requirements. Baden-Württemberg supplier ecosystem density accelerates prototype-to-production cycles for adaptive chassis programs.
- Power Steering Systems:Rack-assist and column-assist electro-hydraulic units face terminal decline as fully electric power steering dominates new platform development.
- Transmission Systems:Clutch and gear selection actuators retain hydraulic persistence in dual-clutch and automated manual configurations.
Brake system applications dominate near-term procurement growth; suspension systems maintain the most durable technology retention.
End User:
Customer-type segmentation reveals procurement consolidation dynamics, with OEM direct sourcing expanding at the expense of tier-1 supplier intermediation in critical brake and steering functions.
- OEMs:Volkswagen AG and Mercedes-Benz Group AG increasingly specify integrated actuator modules directly, bypassing traditional tier-1 sourcing layers. REACH chemical restrictions and RoHS substance limits compel direct supplier engagement on seal material compliance.
- Tier-1 Suppliers:Bosch and Continental sustain margin pools through captive foundry operations and dedicated hydraulics R&D infrastructure.
- Vehicle Assemblers:Contract manufacturing arrangements for specialty and low-volume platforms require flexible actuator sourcing configurations.
- Aftermarket Providers:Replacement demand concentrates in commercial vehicle brake system refurbishment and legacy passenger car suspension repairs.
OEMs capture the dominant procurement share; tier-1 suppliers face margin compression from direct sourcing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across German sub-regions, with volume-focused procurement in northern industrial zones contrasting against specification-driven demand in southwestern premium manufacturing clusters.
Baden-Württemberg
Mercedes-Benz and Porsche chassis programs sustain premium actuator demand at 100–200 bar pressure thresholds. KBA type-approval requirements for UN ECE braking regulations concentrate electro-hydraulic development cycles in Stuttgart and surrounding production clusters. Bosch and Continental maintain dedicated hydraulics R&D infrastructure here, accelerating prototype-to-production timelines for integrated actuator modules.
Bavaria
BMW electrified platforms drive procurement of 350-bar brake-by-wire actuators for regenerative braking architectures. EU Green Deal fleet emission mandates compel local suppliers to reduce parasitic hydraulic losses in cylinder-head designs. Munich anchors a supplier ecosystem where tier-1 firms co-package ECU and sensor fusion for battery-hydraulic integration on electrified vehicles.
North Rhine-Westphalia
VW Group volume nameplates sustain manufacturing scale for proportional valve transmission actuation. REACH chemical restrictions and RoHS substance limits constrain seal material choices, adding compliance cost layers to Ruhr Valley production facilities. Dortmund and Cologne host mid-tier suppliers locked out of cost-competitive cylinder-head forging by vertically integrated competitors.
Hesse
Continental AG sustains R&D intensity through dedicated hydraulics labs in Frankfurt am Main. Hydraulics-specific mechatronics skill scarcity commands wage premiums for cross-functional talent combining fluid-power engineering with ECU firmware development. The region faces acute recruitment competition from Baden-Württemberg and Bavaria clusters.
Lower Saxony
Volkswagen AG headquarters in Wolfsburg drives direct OEM procurement of integrated actuator modules, bypassing traditional tier-1 sourcing layers. Commercial vehicle pneumatic-hydraulic hybrid systems for heavy-duty braking applications concentrate around Hanover truck manufacturing. KBA enforcement timelines compress most severely here for type-approval framework compliance.
Germany Automotive Hydraulic Actuators Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operations and dedicated R&D infrastructure separating the two groups. The upper tier commands specification-setting authority through backward integration into precision forging and machining. Three archetypes populate the competitive map: vertically integrated system suppliers with captive manufacturing, precision component specialists focused on niche pressure regimes, and diversified automotive conglomerates leveraging cross-divisional technology transfer. Competitive moves concentrate on capacity consolidation in southwestern production clusters and strategic partnerships for battery-hydraulic integration on electrified platforms.
Among Germany-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the vertically integrated archetype through control of upstream forging operations and dedicated hydraulics research infrastructure. Knorr-Bremse AG occupies a specialized position in commercial vehicle braking systems. These three represent distinct competitive positions: one anchored in broad chassis and powertrain system supply, another in premium brake-by-wire development, and the third in heavy-duty pneumatic-hydraulic hybrid configurations.
| Leading Market Players |
|---|
| Wabco Holdings Inc. |
| Denso Corporation |
| Continental AG |
| Mahle GmbH |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Sonceboz SA |
| Knorr-Bremse AG |
| Hella KGaA Hueck & Co. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Bosch and Continental with Baden-Württemberg OEMs lock in cylinder-head supply access while anchoring price visibility across 100–350 bar actuator tiers. These contracts insulate vertically integrated suppliers from fluoroelastomer cost volatility while exposing mid-tier competitors to spot-market seal material premiums.
Pricing Analysis
After-sales service contracts and extended warranty bundles drive lifetime value capture for integrated actuator modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by pressure certification and ECU co-packaging complexity. Cost compression in mass-market proportional valve tiers intensifies as VW Group procurement consolidates qualified vendor lists. Tier-1 suppliers face acute price sensitivity in transmission actuation, while brake-by-wire specifications command premium tolerance at Mercedes-Benz and BMW.
Supply Chain Analysis
Inbound logistics costs through Hamburg and Bremerhaven ports constrain just-in-time delivery windows for forged cylinder-head blanks sourced from Austrian and Czech foundries. Germany's actuator manufacturing draws from Chinese rare-earth magnet feedstock for solenoid assemblies, Italian precision steel for piston rods, and domestic aluminum billet for valve bodies. Single-source vulnerability concentrates in high-pressure seal compounds subject to REACH chemical restrictions. Distribution runs through captive OEM supply docks at Stuttgart, Munich, and Wolfsburg assembly complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's automotive hydraulic actuator market represents early-cycle expansion driven by brake-by-wire electrification tailwinds and EU Green Deal fleet compliance deadlines. Electro-hydraulic architecture penetration remains below saturation across volume OEM platforms, leaving runway for specification consolidation.
For Market Incumbents: Secure captive foundry capacity expansion in Baden-Württemberg to defend against mid-tier forging competitors locked out by vertical integration barriers. Deepen firmware-dependent system integration through ECU co-packaging to raise switching costs for OEM procurement teams evaluating second-source options. For New Entrants and Emerging Players: Lead with specialized pneumatic-hydraulic hybrid configurations for commercial vehicle braking under KBA type-approval frameworks, where Bosch and Continental maintain thinner coverage. Target aftermarket refurbishment channels for legacy suspension linear actuators as a low-capital entry path with faster qualification cycles. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision-machining specialists with brake-by-wire certification progress. Long-term viability hinges on battery-hydraulic integration capabilities for electrified platforms. Watch UN ECE braking regulation evolution as the inflection signal for integrated module procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Hydraulic Platform Standardization | Bosch and Continental consolidate cylinder-head specifications across multiple VW Group and Mercedes-Benz architectures. |
| Seal Material Compliance Investment | REACH and RoHS adaptation secures fluoroelastomer supply continuity for 350-bar brake-by-wire production lines. |
| Baden-Württemberg R&D Footprint Expansion | Dedicated hydraulics labs in Stuttgart accelerate prototype-to-production cycles for integrated actuator modules. |
| Battery-Hydraulic Integration Partnership | Tier-1 suppliers co-package ECU and sensor fusion for electrified platform compatibility under evolving UN ECE frameworks. |
| Commercial Vehicle Hybrid System Development | Knorr-Bremse extends pneumatic-hydraulic configurations for heavy-duty braking applications in Hanover truck manufacturing. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and KBA regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through KBA type-approval databases, EU Green Deal policy filings, and vehicle production registration data. Bottom-up actuator unit demand modeling triangulated against top-down OEM procurement budget analysis.
Sensitivity analysis tested forecast robustness across alternative electrification penetration scenarios and regulatory timeline compressions. Segmentation dimensions spanned product architecture, pressure threshold tier, propulsion platform compatibility, and regional production cluster concentration. CAGRs derived from fitted growth curves incorporating brake-by-wire adoption elasticity and EU fleet emission compliance deadlines. Industry-specific inputs included cylinder-head forging capacity utilization rates and hydraulics-specific mechatronics wage premium trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated electromechanical substitution timelines would require recalibration. Forecasts reflect documented assumptions regarding KBA regulatory evolution and OEM platform electrification roadmaps. Supply chain disruption from seal material restriction expansion or foundry capacity bottlenecks represents specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
VVT Actuators Market