
 Automotive Spark Plug Market | 2026-2036
Automotive Spark Plug Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Spark Plug Market Analysis
Platinum is realigning spark plug economics as manufacturers blend it with iridium to balance thermal conductivity and cost. NGK Spark Plug Co., Ltd. leverages its ceramic insulator expertise to dominate OEM supply chains in Japan. Robert Bosch GmbH anchors European aftermarket distribution through dense service-network coverage. Denso Corporation specializes in ultra-fine wire center electrodes for direct-injection engines.
An automotive spark plug is a threaded electrical device that ignites compressed fuel-air mixtures in internal-combustion engines, typically featuring a metal shell, ceramic insulator, and electrodes with gap settings between 0.6 and 1.3 millimeters. Its primary function is to deliver timed high-voltage discharge across the combustion chamber to initiate power strokes. Iridium products command premium positioning due to extended service intervals and superior erosion resistance under lean-burn conditions. Copper segments retain volume leadership in price-sensitive commercial-vehicle fleets where replacement frequency remains high. Racing applications represent a concentrated margin pool despite small absolute volume, driven by custom heat-range specifications and short replacement cycles.
EPA emission mandates and Euro 7 standards are forcing tighter ignition-system tolerances that elevate demand for precision-engineered plugs. China's MIIT fuel-consumption regulations and India's BIS automotive component standards further shape product certification requirements across major manufacturing hubs. Stakeholders must monitor the pace of hybridization and synthetic-fuel compatibility testing, as these trajectories will determine whether spark plug demand stabilizes or contracts faster than engine production volumes suggest.
Market Dynamics
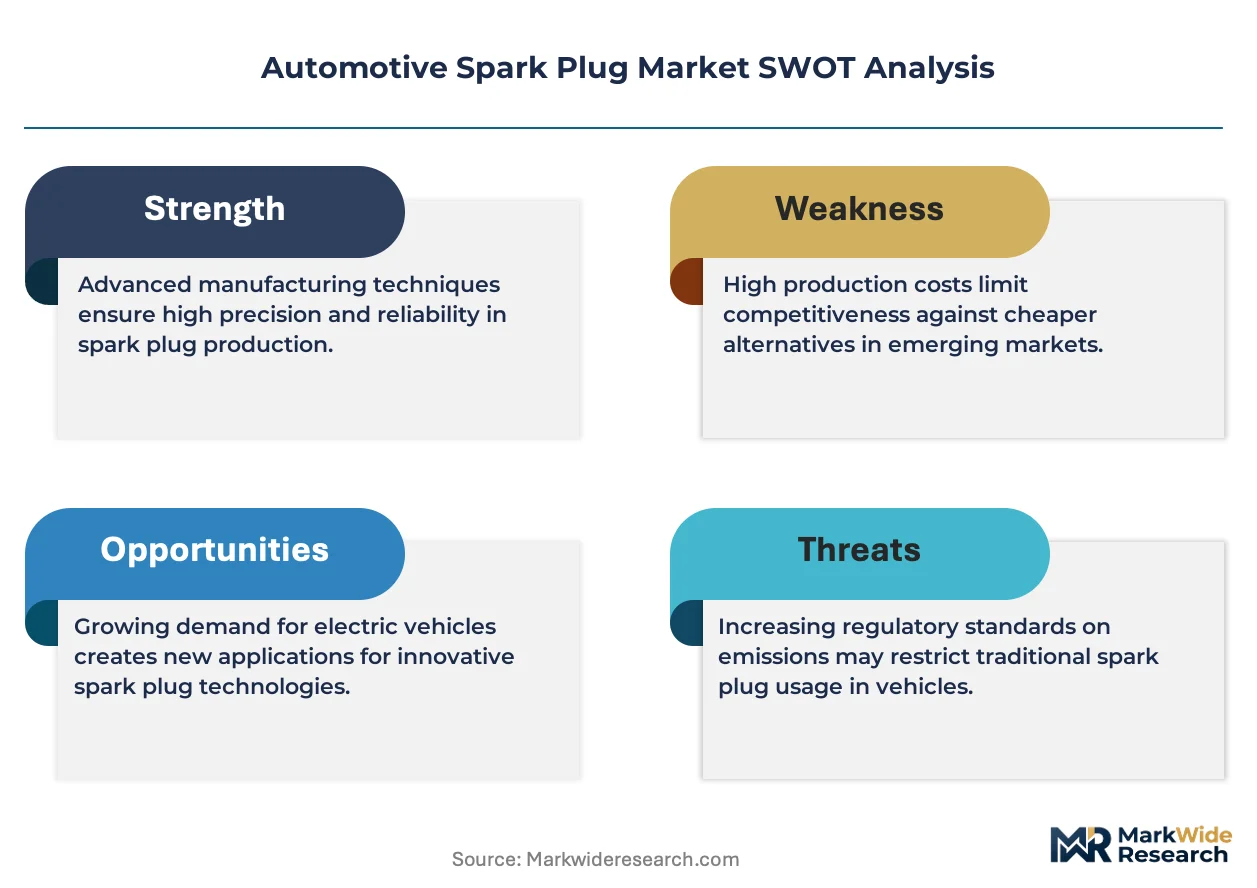
Automotive spark plug demand is bifurcating between premium iridium-tipped units for extended-life applications and high-turnover copper plugs in price-sensitive commercial fleets, creating divergent margin structures across OEM and aftermarket channels.
Growth Catalysts
- Euro 7 Emissions Rules:Tighter ignition-efficiency mandates are forcing engine calibrations that favor precision-engineered spark plugs with tighter gap tolerances and enhanced thermal conductivity.
- Fleet Lifecycle Extension:Commercial vehicle operators in Brazil and India are retaining internal-combustion assets longer, driving aftermarket replacement volume for both standard and premium plug categories.
- Lean-Burn Engine Proliferation:Direct-injection gasoline architectures require iridium center electrodes capable of withstanding higher combustion temperatures and extended service intervals.
Market Restraints
- Platinum Group Metal Volatility:Iridium and rhodium price swings compress margins for manufacturers locked into long-term OEM supply contracts with fixed pricing terms.
- Supplier Concentration in Ceramic Insulators:Technical-grade alumina supply for insulator bodies concentrates among Japanese and German specialty ceramic producers, creating single-source vulnerability.
- Hybrid Powertrain Substitution:Mild-hybrid and full-hybrid vehicles reduce per-vehicle spark plug counts and extend replacement cycles through optimized ignition strategies.
Strategic Opportunities
- Synthetic Fuel Compatibility Testing:E-fuel and hydrogen-blend combustion trials in Germany and Japan are creating demand for spark plug designs with modified heat ranges and electrode materials.
- Racing and Performance Aftermarket:Custom heat-range specifications for motorsport applications command 4-6x standard pricing despite low volume, with concentrated demand in the United States and Australia.
- India BIS Component Standards:Mandatory certification for automotive electrical components is raising compliance barriers that favor established manufacturers with testing infrastructure.
Industry Challenges
- Precision Manufacturing Talent Scarcity:Ultra-fine wire center electrode production requires specialized electrochemical machining expertise that is concentrating among aging workforces in Japan and Germany.
- Legacy Engine Calibration Integration:New plug designs must maintain backward compatibility with ECU spark timing maps across 15-plus model years of vehicle parc, constraining innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Spark Plug Market |
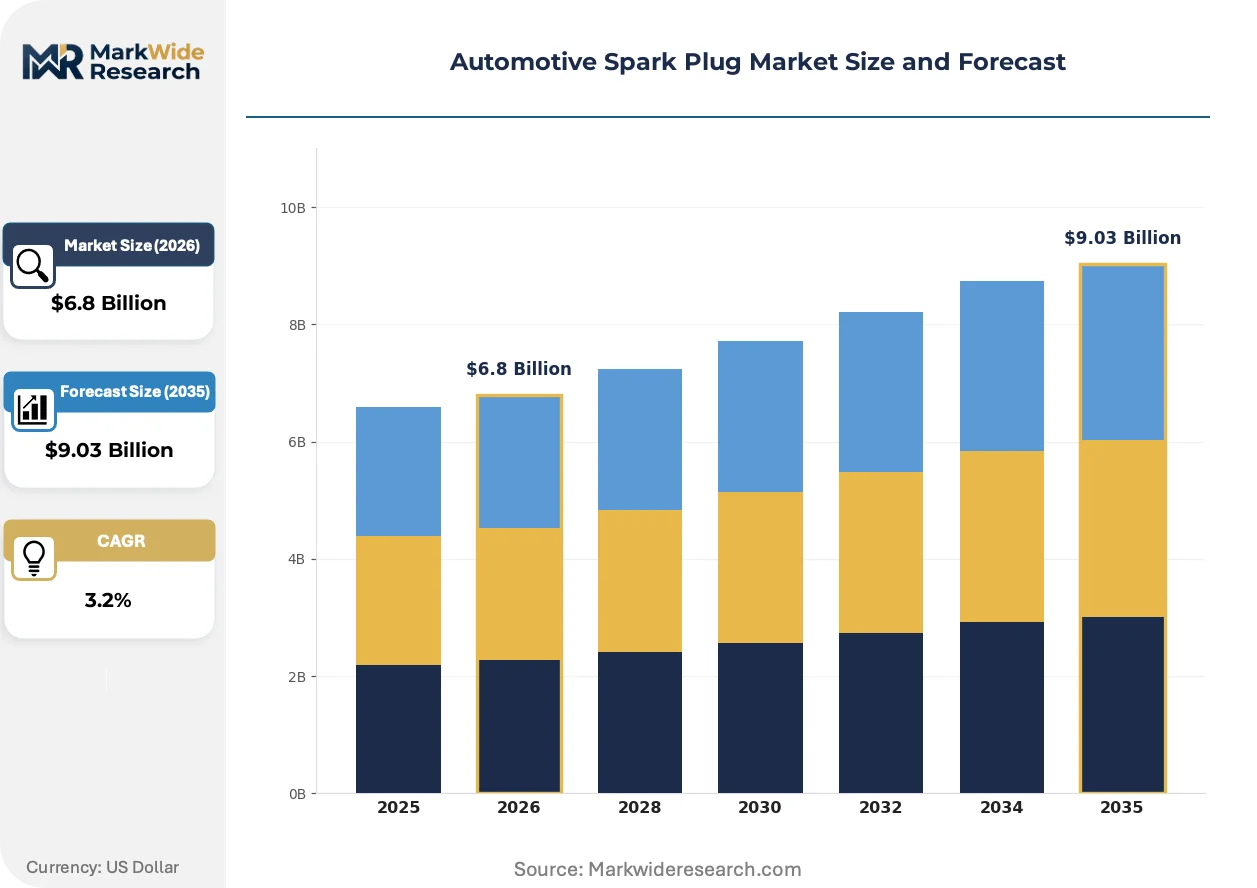
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.03 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iridium, Copper, Platinum, Nickel End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Distributors Technology: Conventional, Laser, Resistor, Non-Resistor Application: Passenger Cars, Commercial Vehicles, Motorcycles, Racing |
| Companies Covered | NGK Spark Plug Co., Ltd., Denso Corporation, Robert Bosch GmbH, Niterra Co., Ltd., BorgWarner Inc., Tenneco Inc., Valeo S.A., Federal-Mogul Corporation, Autolite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Spark Plug Market Emerging Trajectories
Spark plug architecture is fragmenting across thermal-grade specialization, with manufacturers developing application-specific designs rather than universal-fit products to capture premium positioning in tightening emission regimes.
Platinum-iridium alloy center electrodes are modularizing spark plug product architectures by enabling standardized shell designs across multiple thermal grades. OEM procurement teams in Germany and Japan are consolidating supplier lists around platforms that share common metal shell geometries while varying only electrode tip configurations. This standardization is compressing tooling costs and reducing inventory complexity for tier-one ignition system integrators.
EPA tailpipe standards and Euro 7 rules are forcing tighter ignition-system tolerances that elevate demand for precision gap control and erosion-resistant materials. Engine manufacturers in the United States are redesigning cylinder head architectures to accommodate smaller-diameter spark plugs with enhanced cooling characteristics. The direct-injection gasoline segment is responding with dedicated plug families that withstand 280-bar combustion pressures.
Aftermarket distribution is consolidating around diagnostic-linked replacement recommendations, with service networks using cylinder-specific misfire detection data to trigger targeted plug replacement rather than blanket interval-based service. Independent repair chains in China and Brazil are adopting this precision-retail model fastest, unbundling plug sales from bundled tune-up packages and capturing higher margins on single-unit sales matched to actual wear patterns.
Automotive Spark Plug Market Segmentation
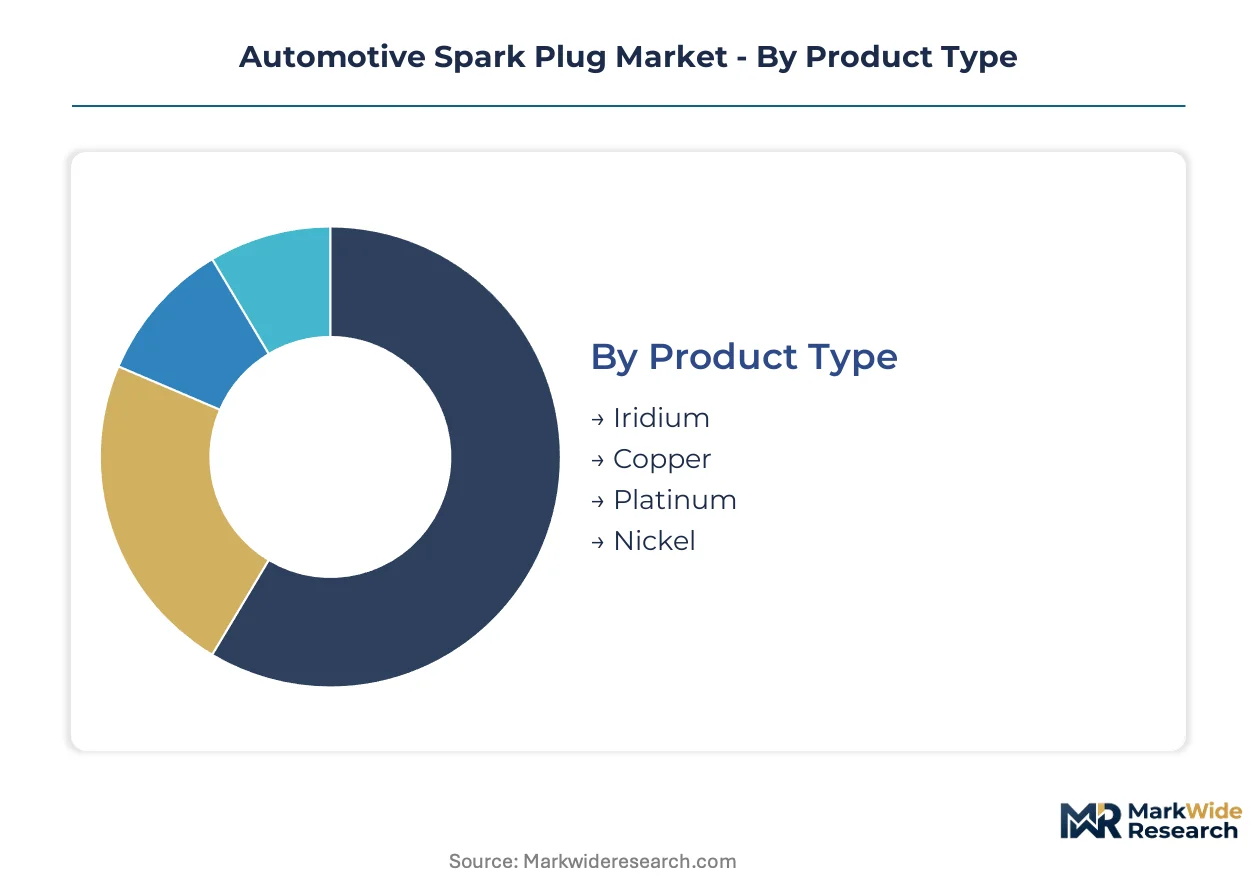
Spark plug manufacturers face divergent margin structures across material grades and channel types. Product metallurgy determines service intervals and pricing power, while end-user segmentation separates stable OEM contracts from volatile aftermarket replacement cycles.
Product Type:
Volume concentrates in copper, while premium positioning belongs to iridium and platinum alloys.
- Iridium:Ultra-fine wire center electrodes withstand 280-bar combustion pressures in direct-injection gasoline architectures. Demand clusters in Germany and Japan where Euro 7 and domestic emission rules mandate extended service intervals and lean-burn compatibility.
- Copper:Nickel-alloy core construction delivers superior thermal conductivity at lower unit cost. Fleet operators in Brazil and India favor this grade for commercial vehicles where high replacement frequency and price sensitivity dominate procurement decisions.
- Platinum:Blended with iridium to balance erosion resistance against material cost volatility. OEM supply contracts in European passenger car production favor this intermediate tier.
- Nickel:Legacy construction for older engine calibrations and developing-market price floors. Remains relevant in aftermarket channels serving 15-plus model year vehicle parc.
Today's leader: Copper. Tomorrow's challenger: Iridium.
End User:
Channel structure separates long-term contract stability from high-turnover replacement demand.
- OEMs:Original equipment procurement locks in multi-year supply agreements with fixed pricing terms. Japanese and German vehicle manufacturers consolidate supplier lists around standardized shell geometries with modular electrode configurations.
- Aftermarket Providers:Independent distribution networks capture margin through diagnostic-linked replacement recommendations. Chinese and Brazilian service chains lead adoption of cylinder-specific misfire detection to trigger targeted plug sales.
- Vehicle Assemblers:Tier-one ignition system integrators source plug families matched to cylinder head architectures. Procurement teams prioritize inventory reduction through platform-shared component designs.
- Distributors:Wholesale channels bridge manufacturer output to regional service networks. Dense coverage in European aftermarket creates competitive moats for established logistics operators.
OEM contracts anchor revenue stability. Aftermarket channels drive margin expansion.
Technology:
Resistor and non-resistor architectures split across electromagnetic interference requirements and performance applications.
- Conventional:Standard suppressor design for mass-market passenger vehicles with moderate radio-frequency shielding needs. Dominates volume production for cost-optimized engine families.
- Resistor:Ceramic composition integrated into the insulator body attenuates ignition noise for sensitive onboard electronics. Required fitment in modern vehicles with advanced driver-assistance system sensor arrays.
- Non-Resistor:Absence of radio-frequency suppression maximizes spark energy delivery. Racing and performance applications in the United States and Australia command premium positioning despite limited volume.
- Laser:Precision gap welding and surface treatment technologies enable ultra-fine electrode geometries. Emerging production method for iridium-tipped plugs targeting Euro 7 emission compliance.
Resistor technology holds installed base dominance. Laser processing enables next-generation precision.
Application:
Passenger car scale contrasts with racing margin concentration across divergent thermal-grade requirements.
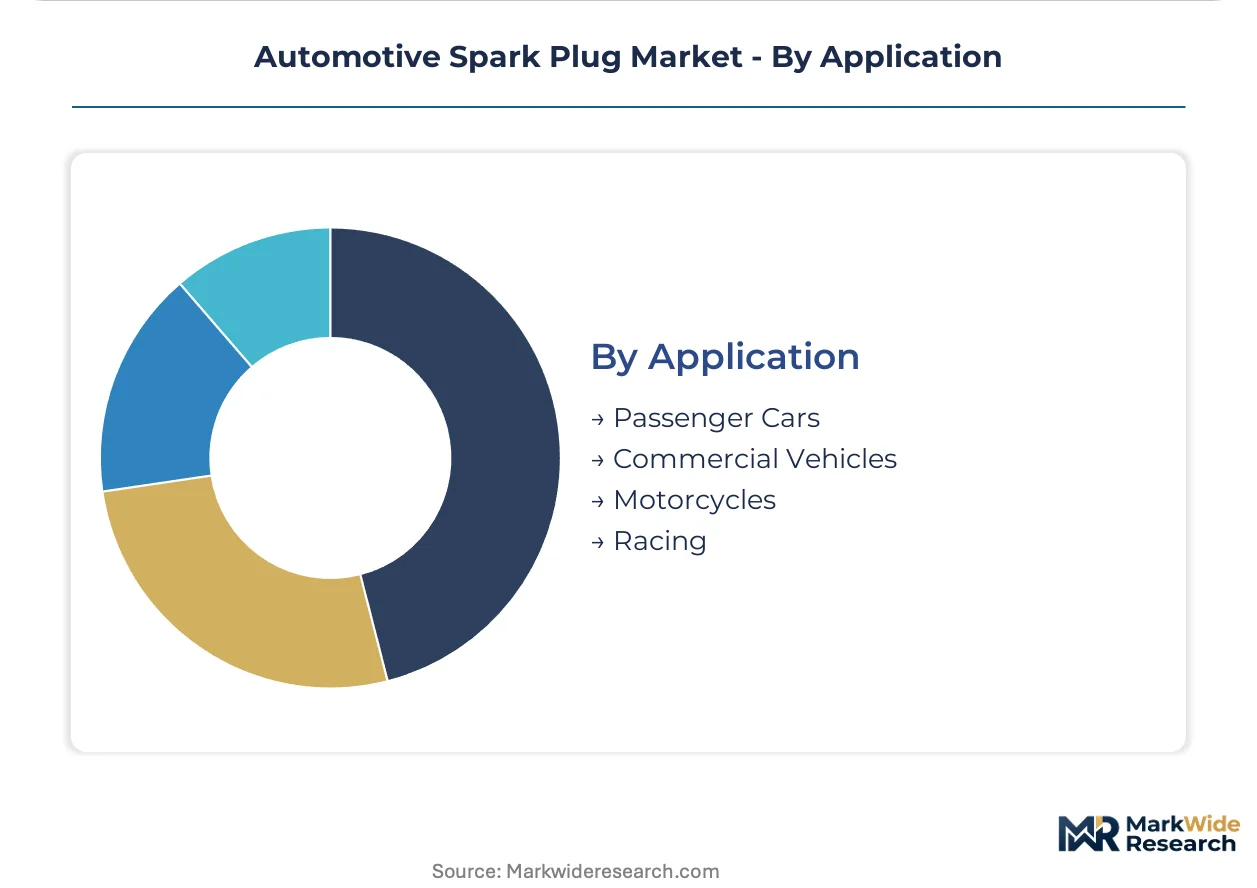
- Passenger Cars:Largest absolute volume segment spanning economy through luxury vehicle classes. Direct-injection gasoline proliferation in China and India drives specification upgrades toward iridium center electrodes.
- Commercial Vehicles:High-turnover replacement cycles in freight and logistics fleets favor copper construction for cost efficiency. Lifecycle extension trends in Brazil sustain aftermarket volume despite electrification headwinds.
- Motorcycles:Compact engine architectures with exposed operating conditions demand specialized heat-range calibrations. Asian manufacturing hubs dominate both production and consumption patterns.
- Racing:Custom heat-range specifications and short replacement intervals generate 4-6x standard unit pricing. Concentrated demand in United States motorsport and Australian V8 Supercars championships.
Passenger cars provide volume foundation. Racing applications deliver margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagoya anchors the industry's ceramic insulator production, with Japanese and German manufacturers supplying precision-engineered electrodes to engine plants across three continents. EPA tailpipe standards and Euro 7 emissions rules are tightening ignition-efficiency requirements in North America and Europe, while China's MIIT fuel-consumption regulations and India's BIS automotive component standards reshape procurement patterns in Asia.
China
Direct-injection gasoline proliferation in passenger car manufacturing drives specification upgrades toward iridium center electrodes. MIIT fuel-consumption regulations mandate lean-burn compatibility testing for new engine certifications. The Yangtze River Delta cluster houses tier-one ignition system integrators sourcing plug families matched to cylinder head architectures.
Germany
Euro 7 emissions rules force engine calibrations favoring precision-engineered spark plugs with tighter gap tolerances. The KBA enforces type-approval standards for aftermarket component certification. Bavarian OEM procurement teams consolidate supplier lists around standardized shell geometries with modular electrode configurations.
United States
Diagnostic-linked replacement recommendations spread through independent repair chains using cylinder-specific misfire detection data. EPA tailpipe standards elevate demand for erosion-resistant materials in lean-burn applications. Detroit-area vehicle assemblers redesign cylinder head architectures to accommodate smaller-diameter spark plugs with enhanced cooling characteristics.
India
Commercial vehicle operators retain internal-combustion assets longer, driving aftermarket replacement volume for copper and premium plug categories. BIS mandatory certification for automotive electrical components raises compliance barriers favoring established manufacturers. Tamil Nadu manufacturing hubs concentrate production for domestic OEM supply and export to Southeast Asian markets.
Brazil
Fleet lifecycle extension in freight and logistics operations sustains high-turnover replacement cycles for cost-optimized copper construction. ANVISA automotive component standards align with Mercosur technical regulations for cross-border trade. São Paulo state anchors distribution networks bridging manufacturer output to regional service networks across South America.
Automotive Spark Plug Market Vendor Landscape
Global majors compete with regional champions across ceramic insulator supply and electrode metallurgy specialization. The vendor base stratifies into three tiers: Japanese and German firms controlling technical-grade alumina supply, diversified automotive suppliers with ignition system integration capabilities, and regional aftermarket distributors with dense service-network coverage. Dominant competitive moves include backward integration into ceramic insulator production and strategic partnerships with engine manufacturers for platform-shared component designs.
Among Japanese specialists, NGK Spark Plug Co., Ltd. and Denso Corporation exemplify the ceramic insulator and ultra-fine wire electrode archetypes respectively. Robert Bosch GmbH anchors European aftermarket positioning through service-network density. These three firms occupy positions that reflect divergent strategic emphases: ceramic material science, precision electrochemical machining, and continental distribution logistics.
| Leading Market Players |
|---|
| NGK Spark Plug Co., Ltd. |
| Denso Corporation |
| Robert Bosch GmbH |
| Niterra Co., Ltd. |
| BorgWarner Inc. |
| Tenneco Inc. |
| Valeo S.A. |
| Federal-Mogul Corporation |
| Autolite |
| Others |
Supply Flow & Price Mechanics
Tier-one ignition system integrators in Germany and Japan concentrate procurement around standardized shell geometries, locking the market into contract-based long-term offtake pricing with fixed material pass-through clauses. This buyer concentration forces manufacturers to absorb platinum group metal volatility within multi-year OEM agreements while capturing margin recovery through aftermarket premium tiers.
Pricing Analysis
Input-cost pass-through from iridium and rhodium spot markets compresses margins for manufacturers locked into fixed-price OEM contracts, while aftermarket channels recover through three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on electrode metallurgy grade and Euro 7 certification tier, with iridium-tipped units commanding substantial premiums over copper construction. Pricing pressure stems from fleet operator procurement consolidation in Brazil and India, where commercial vehicle buyers exhibit highest sensitivity to unit cost. Passenger car OEMs in Germany and Japan show lowest price sensitivity, prioritizing extended service intervals and lean-burn compatibility over per-unit expenditure.
Supply Chain Analysis
Reverse-logistics flows for core collection and electrode material recovery are underdeveloped, leaving value trapped in spent plugs rather than feeding closed-loop iridium reclamation. Geographic supply concentrates in Japan, Germany, and China, with technical-grade alumina for ceramic insulators drawing from Japanese and German specialty ceramic producers. Raw material dependencies center on iridium ore from South Africa, rhodium from Russia, and high-purity alumina from bauxite refining. Single-source vulnerability in ceramic insulator supply creates structural risk, compounded by limited alternative qualified suppliers. Distribution runs through tier-one ignition system integrators to OEM assembly plants, with aftermarket channels fragmenting across regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on iridium-tipped product mix shift toward direct-injection gasoline platforms, with alloy blending protocols offering cost-down pathways that preserve erosion resistance. Fleet lifecycle extension in developing markets sustains replacement volume while premium tier adoption in Euro 7 jurisdictions captures pricing power.
For Market Incumbents: Anticipate hybrid powertrain substitution by accelerating backward integration into ceramic insulator production, securing captive supply of technical-grade alumina against Japanese and German specialty producer concentration. Consolidate supplier lists around platform-shared component designs to compress tooling costs and inventory complexity. Defend against emerging Chinese competitors by investing in BIS certification infrastructure for Indian market access, raising compliance barriers that favor established testing capabilities.
For New Entrants and Emerging Players: Euro 7 emissions rules in Germany open a window for precision-engineered plug specialists targeting tighter gap tolerance specifications that incumbent volume producers under-serve. White-space targets include synthetic fuel compatibility testing services for German and Japanese e-fuel trials, and custom heat-range motorsport applications in United States and Australian racing championships. Go-to-market execution should anchor on diagnostic-linked replacement recommendation platforms, unbundling plug sales from bundled service packages to capture higher single-unit margins.
For Investors and Strategic Acquirers: Diversified automotive suppliers with ignition system integration capabilities are the most active acquirer in this space, seeking electrode metallurgy expertise to complement existing ceramic insulator positions. Long-term viability over the intermediate horizon rests on synthetic fuel and hydrogen-blend combustion trajectory, with spark plug demand stabilizing if e-fuel penetration outpaces pure electrification. Acquisition target archetype: ultra-fine wire electrochemical machining specialists with aging workforce concentration in Japan and Germany. Signal to monitor: KBA type-approval standard revisions for aftermarket component certification, which would accelerate supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM procurement teams in Bavaria consolidate supplier lists around modular electrode configurations. |
| Backward Integration | Ceramic insulator production capture reduces single-source vulnerability to Japanese specialty producers. |
| Synthetic Fuel Compatibility Testing | German e-fuel trials create demand for modified heat-range spark plug designs. |
| Diagnostic-Linked Distribution | Chinese service chains adopt cylinder-specific misfire detection to trigger targeted plug replacement. |
| BIS Certification Investment | Indian mandatory standards raise barriers favoring established manufacturers with testing infrastructure. |
Methodological Framework
Bottom-up vehicle parc modeling reconciled against top-down ignition system production tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance directors combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA certification filings, and KBA type-approval records. Stakeholder triangulation cross-referenced OEM supply contract structures against aftermarket channel inventory patterns.
Historical trendline analysis of spark plug content per vehicle across passenger car, commercial vehicle, and motorcycle segments established baseline penetration rates. The projection framework models material grade mix, end-user channel split, and regional regulatory cluster adoption patterns across the analysis window. CAGRs derive from segment-level volume trajectories weighted by iridium, platinum, and copper pricing tier contributions, with direct-injection gasoline proliferation and Euro 7 emission rule implementation as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated hybridization or synthetic fuel breakthrough scenarios. Practitioners should monitor MIIT fuel-consumption regulation revisions in China, ANVISA automotive component standard updates in Brazil, and platinum group metal spot price volatility for early signals of trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Tailgate Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Hardware Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Straps Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Wiper Blades Market