
 Global Automotive Noise Filter Market | 2026-2036
Global Automotive Noise Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Noise Filter Market Intelligence
Software-defined adaptive filtering, which adjusts suppression characteristics based on real-time vehicle operating conditions, is consolidating the value proposition away from purely passive hardware. Robert Bosch GmbH leverages its system integration expertise to embed filtering within broader electronic control unit platforms. Murata Manufacturing Co., Ltd. specializes in high-frequency, miniature components like ferrite beads and multilayer ceramic capacitors for dense circuit boards. Continental AG positions its solutions by integrating advanced noise suppression directly into its safety-critical systems and powertrain modules.
An automotive noise filter is an electronic component or circuit designed to suppress electromagnetic interference (EMI) generated by a vehicle's electrical systems. These devices, often utilizing materials with high magnetic permeability like ferrite, prevent electrical noise from disrupting sensitive components such as infotainment or safety control units. Passive filtering components like ferrite beads and capacitors form the market's volume foundation, though active filtering technology commands a significant price premium. Applications in electric drive systems and infotainment systems are expanding rapidly, overtaking demand from traditional powertrain components.
Compliance with electromagnetic compatibility (EMC) standards is mandatory, governed by regulations such as FCC Part 15 rules in the United States and the CE marking directives in Europe. In Asia, automakers and their suppliers must adhere to specific requirements like China's GB standards and Japan's VCCI rules, which dictate permissible emission and immunity levels. The primary strategic decision for suppliers involves balancing investment in high-margin active filtering technologies against the manufacturing scale required for commoditized passive components.
Market Dynamics
The proliferation of high-frequency electronics within electric vehicle powertrains is the central force shaping the market. This shift creates complex electromagnetic interference challenges, elevating noise filters from simple passive components to critical system-level enablers for vehicle performance and safety.
Growth Catalysts
- Stricter EMC Standards:Mandatory compliance with regulations like the EU's CE marking directives and China's GB standards for vehicles forces automakers to incorporate more advanced and effective filtering solutions to achieve market access.
- EV Powertrain Complexity:The increasing density of power inverters, battery management systems, and onboard chargers in electric vehicles generates significant electromagnetic noise, necessitating robust filtering to protect sensitive control electronics.
- Advanced Infotainment and ADAS:The adoption of high-bandwidth data connections for infotainment and safety-critical sensors for autonomous driving features requires superior noise suppression to ensure signal integrity and reliable operation.
Market Restraints
- Raw Material Price Volatility:The cost of high-permeability materials like ferrite, a core component in passive filters, is subject to fluctuations in iron oxide and other mineral markets, impacting component manufacturer margins.
- Performance Limits of Passive Filters:Traditional passive components like ferrite beads and capacitors struggle to effectively suppress common-mode noise at the higher switching frequencies found in modern silicon carbide inverters.
- On-Chip Integration:A long-term substitution threat exists as semiconductor manufacturers increasingly integrate basic filtering functionalities directly onto integrated circuits, potentially reducing the need for discrete external filters.
Strategic Opportunities
- Software-Defined Adaptive Filtering:Development of active filtering systems that can adjust their suppression characteristics in real-time offers a significant high-margin opportunity beyond commoditized passive hardware components.
- Expansion into Charging Infrastructure:The global build-out of DC fast-charging stations creates a new application segment for high-power EMI filters needed to ensure grid stability and prevent interference.
- Aftermarket Solutions for V2G:The emergence of Vehicle-to-Grid applications will require specialized aftermarket filters to manage the bidirectional flow of power and associated electromagnetic noise, creating a new service and hardware market.
Industry Challenges
- System Integration Complexity:Ensuring that filters from various suppliers work harmoniously within a single, dense electronic control unit without creating new interference pathways is a major engineering challenge for automotive Tier 1 suppliers.
- Multi-Standard Compliance Burden:Manufacturers face long and expensive validation cycles to certify products against a diverse set of global standards, including FCC Part 15 in the US, CE marking in Europe, and VCCI in Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Noise Filter Market |
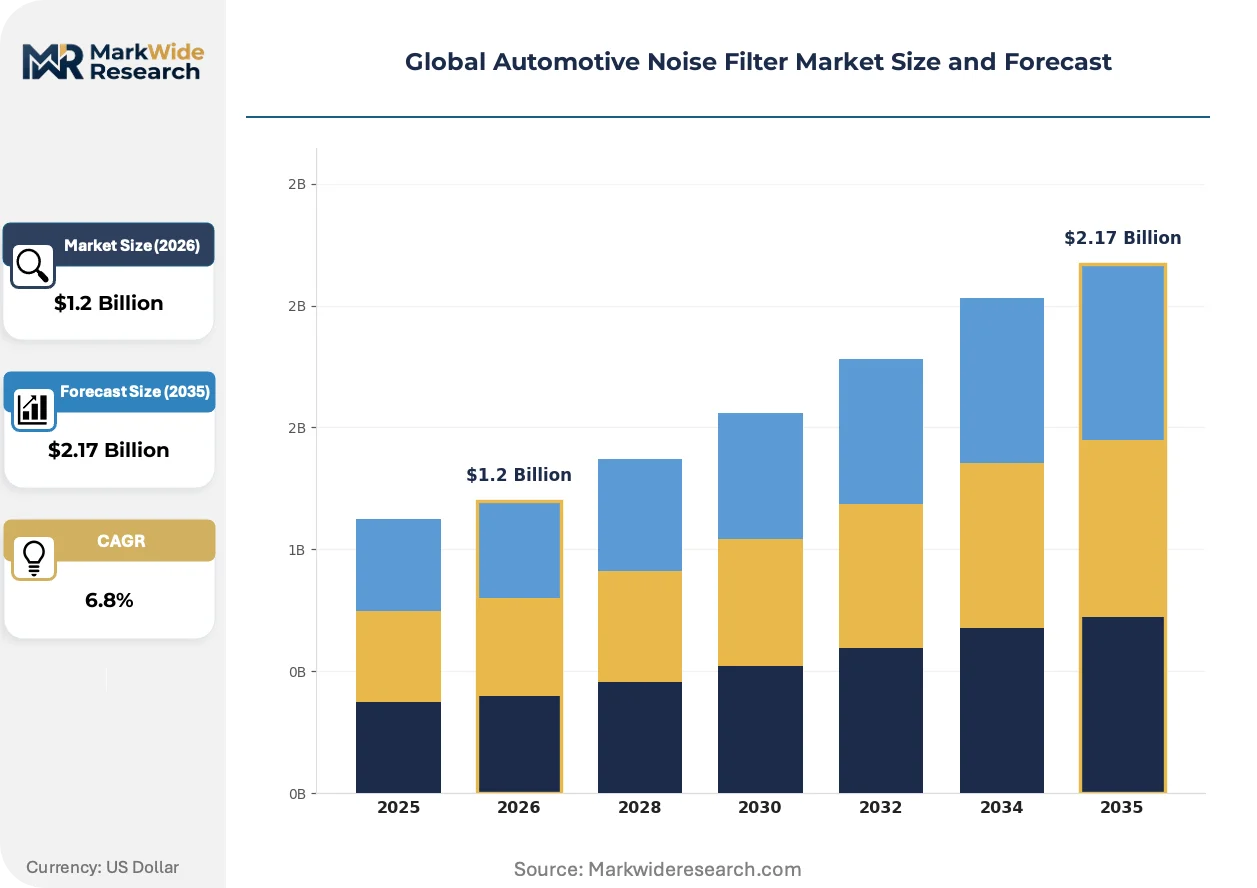
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
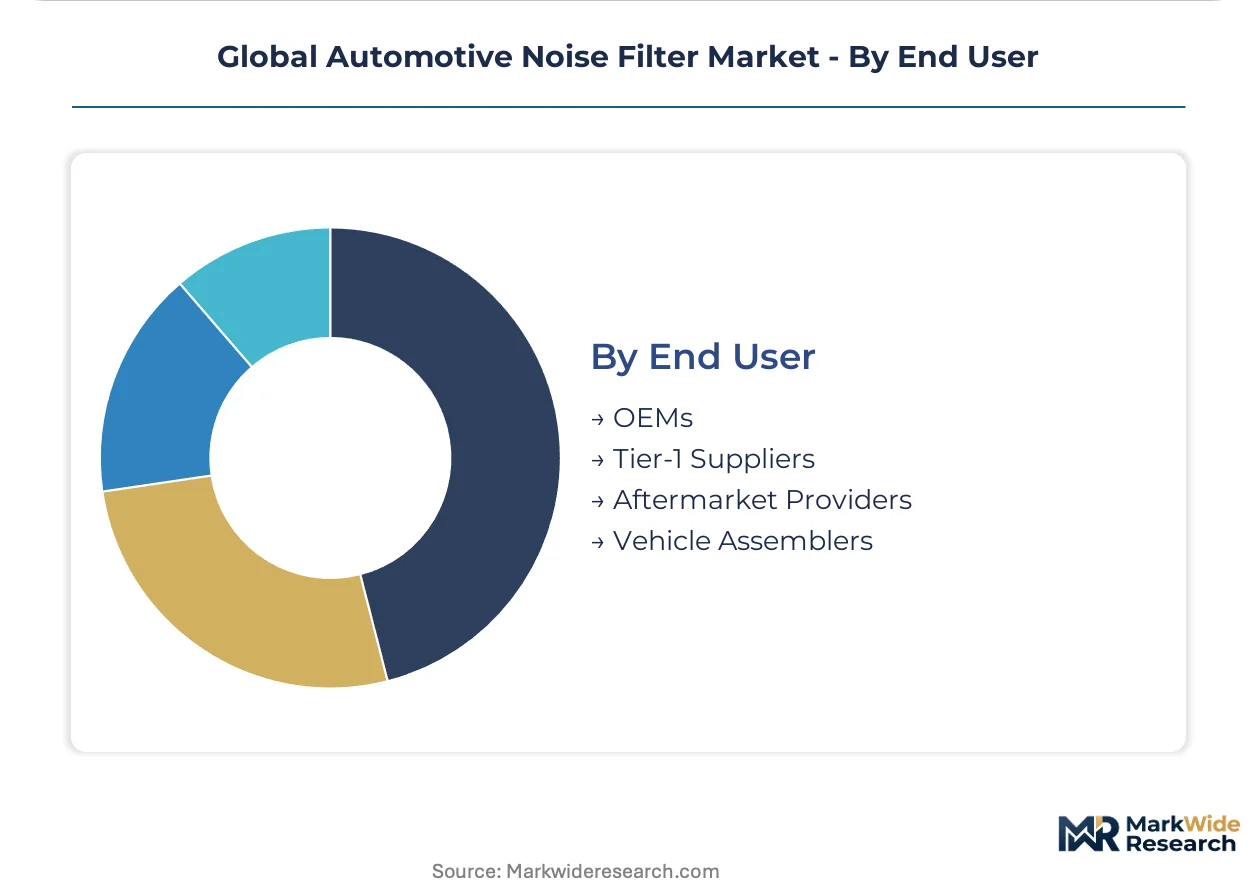
| Segmentation | Product Type: Ferrite Bead, EMI Suppressor, Capacitor, Inductor, RC Network Technology: Passive Filtering, Active Filtering, Hybrid Filtering, Adaptive Filtering Application: Electric Drive Systems, Infotainment Systems, Safety Control Units, Powertrain Components, Body Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, TDK Corporation, Murata Manufacturing Co., Ltd., Bose Corporation, Johnson Controls, Trelleborg AB, 3M Company, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Noise Filter Market Strategic Shifts & Innovations
The market's evolution is defined by a move toward intelligent and integrated noise suppression solutions. This transition prioritizes system-level electromagnetic compatibility over the performance of discrete components, responding to the complex electronic architectures of modern connected and electric vehicles.
Active filtering technology provides dynamic noise cancellation using signal processing. High-performance electric vehicles and premium automotive brands are the primary adopters due to the technology's cost and complexity. This advanced capability is integrating filtering directly with power management and system diagnostics, creating a single, intelligent module that optimizes performance across the entire electronic subsystem.
China's increasingly stringent GB standards for automotive electromagnetic compatibility are a significant regulatory driver. These rules impose strict limits on radiated and conducted emissions from vehicles, particularly electric models. Consequently, component suppliers targeting the vast Chinese automotive market must engineer higher-performance filters to ensure their products can be designed into vehicles built by both domestic and international OEMs.
Automaker procurement is evolving from sourcing individual passive components to specifying pre-validated filter modules integrated within larger systems. This shift favors large Tier 1 suppliers with deep system integration expertise over smaller, specialized component makers. The trend is most visible in the development of electric powertrain and battery management systems, where ensuring EMC is critical for safety and operational reliability.
Global Automotive Noise Filter Market Segmentation
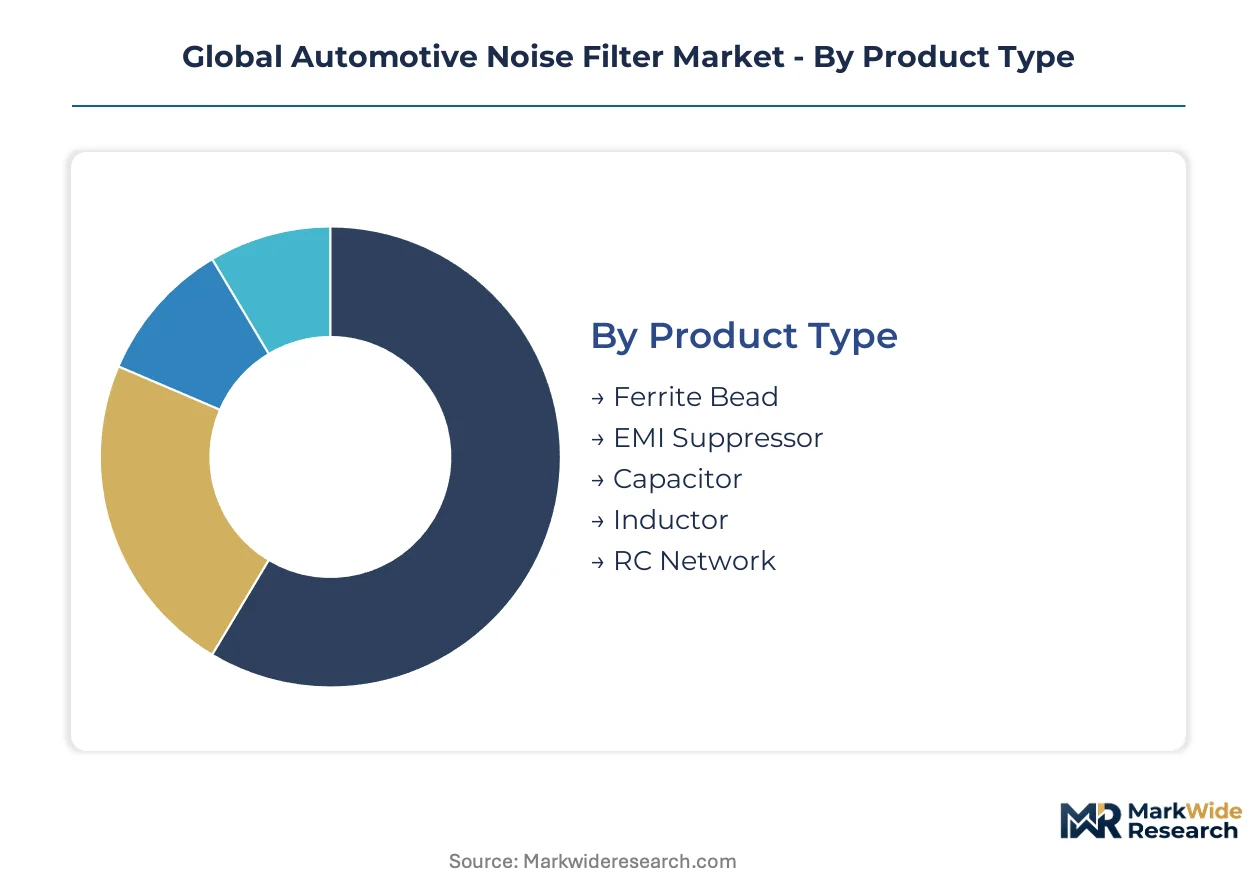
Understanding the segmentation of the global automotive noise filter market is crucial for identifying areas of concentrated demand and technological evolution. This detailed breakdown highlights how product types, technologies, applications, and end-users shape the competitive landscape and investment priorities within the industry.
Product Type:
Supply concentration in the global automotive noise filter market for product types reflects the specialized manufacturing processes required for high-performance materials and miniaturization.
- Ferrite Bead:Ferrite beads utilize high magnetic permeability materials, primarily iron oxides, to absorb high-frequency noise and dissipate it as heat. Demand for these cost-effective components concentrates in China's rapidly expanding EV manufacturing sector, where they provide essential EMI suppression in power electronics.
- Capacitor:Capacitors store and release electrical energy, effectively shunting high-frequency noise to ground, with multilayer ceramic capacitors being prevalent in dense circuit boards. European automakers integrate these components extensively within infotainment systems to maintain signal integrity against increasing EMI.
- EMI Suppressor:EMI suppressors combine multiple passive components into a single package, offering a consolidated solution for complex noise profiles.
- Inductor:Inductors store energy in a magnetic field, blocking high-frequency noise while allowing lower frequencies to pass, essential in power supply filtering.
- RC Network:RC networks combine resistors and capacitors to create simple, broadband noise filters, frequently used for transient voltage suppression.
Today's leader: Ferrite Bead. Tomorrow's challenger: EMI Suppressor.
Technology:
Margin structures across noise filter technologies vary significantly, reflecting the complexity and intellectual property embedded in each solution.
- Passive Filtering:Passive filtering relies on components like capacitors, inductors, and resistors to attenuate noise without external power sources, forming the market's volume foundation. Its widespread application in traditional powertrain components and basic electronic systems in India ensures consistent demand.
- Active Filtering:Active filtering dynamically cancels noise by generating an out-of-phase signal, requiring sophisticated signal processing and external power. Premium automotive brands in Germany prioritize active filtering for their high-performance electric vehicles due to its superior noise cancellation capabilities.
- Hybrid Filtering:Hybrid filtering combines passive and active techniques to optimize performance and cost, addressing specific noise profiles in complex systems.
- Adaptive Filtering:Adaptive filtering adjusts its suppression characteristics in real-time based on vehicle operating conditions, offering advanced and flexible noise management.
Active Filtering exhibits the steepest expansion trajectory, while Passive Filtering maintains the largest installed base.
Application:
The volume of noise filter deployment is directly proportional to the electronic content within various automotive applications.
- Electric Drive Systems:Electric drive systems, encompassing inverters, motors, and battery management units, generate significant high-frequency electromagnetic interference, demanding robust filtering solutions. Chinese EV manufacturers are heavily integrating advanced filters into these systems to comply with stringent GB standards.
- Infotainment Systems:Infotainment systems, with their high-bandwidth data connections and sensitive audio/visual components, require superior noise suppression to ensure signal clarity and user experience. Automakers in the United States increasingly specify filters for these systems to prevent interference from adjacent power electronics.
- Safety Control Units:Safety control units, such as ABS and ESC, require precise noise filtering to guarantee reliable operation and prevent false signals.
- Powertrain Components:Traditional powertrain components, including engine control units and fuel injection systems, utilize noise filters to ensure stable communication and sensor accuracy.
- Body Electronics:Body electronics, covering lighting, power windows, and climate control, incorporate filters to prevent electrical glitches and ensure consistent functionality.
Electric Drive Systems are experiencing the most rapid growth in filter integration, while Powertrain Components represent a mature, high-volume segment.
End User:
Customer type dictates the procurement patterns and specification requirements for automotive noise filters across the value chain.
- OEMs:Original Equipment Manufacturers directly integrate noise filters into their vehicle designs and often dictate precise specifications to their suppliers. German luxury car brands prioritize custom-engineered solutions to maintain their brand's performance and reliability standards.
- Tier-1 Suppliers:Tier-1 suppliers procure and integrate noise filters into larger modules and electronic control units before supplying them to OEMs, leveraging their system integration expertise. Japanese Tier-1 companies focus on high-volume, cost-effective solutions for diverse vehicle platforms.
- Aftermarket Providers:Aftermarket providers supply noise filters for vehicle repairs, upgrades, and specialized applications, catering to existing vehicle fleets.
- Vehicle Assemblers:Vehicle assemblers integrate pre-assembled modules containing noise filters into the final vehicle, focusing on efficient installation processes.
Tier-1 Suppliers dominate current procurement volume, while Aftermarket Providers address niche replacement and upgrade demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs and varying market demands create an arbitrage opportunity for automotive noise filter production across geographies. This dynamic influences manufacturing site selection and market access strategies for component suppliers. Automakers seek optimal solutions balancing performance with cost-effectiveness.
China
China's rapidly expanding electric vehicle manufacturing sector drives significant demand for advanced noise filters. The country's strict GB standards for electromagnetic compatibility necessitate high-performance filtering solutions for market entry. EV production hubs in the Yangtze River Delta continue to integrate these critical components into new vehicle platforms.
Germany
German luxury automotive brands prioritize superior noise cancellation for their high-performance electric vehicles. Compliance with the EU's CE marking directives is mandatory for all electronic components sold within the European Union. Automotive R&D centers in Bavaria focus on integrating advanced active filtering technologies.
United States
Demand for advanced infotainment systems and ADAS features in the United States requires robust noise suppression for signal integrity. FCC Part 15 rules govern permissible emission levels for electronic devices, including automotive components. Michigan's automotive innovation centers focus on integrating filters into next-generation vehicle architectures.
Japan
Japanese Tier-1 suppliers focus on delivering high-volume, cost-effective noise filter solutions for diverse vehicle platforms. VCCI rules dictate permissible emission and immunity levels for electronic equipment, influencing design choices. Automotive component manufacturing clusters near Nagoya specialize in miniaturized, high-frequency components.
India
India's automotive sector maintains consistent demand for passive filtering components in traditional powertrain and basic electronic systems. The Bureau of Indian Standards (BIS) influences quality and performance requirements for automotive electrical parts. Chennai's automotive manufacturing cluster integrates these filters into locally produced vehicles.
Global Automotive Noise Filter Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the global automotive noise filter market. The industry exhibits a tiered structure, with large system integrators dominating high-value active filtering solutions and specialized component makers supplying passive filters. Strategic partnerships and technology licensing agreements represent dominant competitive moves among key players.
German-based firms Robert Bosch GmbH and Continental AG exemplify the trend towards deeply integrated filtering solutions within broader electronic control unit platforms. Japanese specialist Murata Manufacturing Co., Ltd. occupies a position as a leading supplier of high-frequency, miniature passive components. These companies reflect the market's dual nature, encompassing both system-level integration and specialized component manufacturing.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| TDK Corporation |
| Murata Manufacturing Co., Ltd. |
| Bose Corporation |
| Johnson Controls |
| Trelleborg AB |
| 3M Company |
| Delphi Technologies |
| Others |
Cost & Logistics Intelligence
Tier-1 supplier procurement patterns influence the prevalent contract-based pricing model for automotive noise filters. This structure emphasizes long-term agreements over spot market transactions.
Pricing Analysis
Capacity additions in China are reshaping price floors for passive filtering components. The dominant pricing model remains contract-based long-term offtake for Tier-1 suppliers and OEMs. Price differentiation stems from performance tier, distinguishing high-margin active solutions from commoditized passive components, and stringent certification levels like CE marking. Pricing softness stems from the manufacturing scale required for passive components. Aftermarket Providers exhibit the highest price sensitivity, while German luxury car brands prioritize performance over cost.
Supply Chain Analysis
China's GB standards, requiring localized production, are reshaping sourcing for high-performance filters. Supply concentration centers on manufacturing hubs in China, Japan, and Germany. The industry draws from specific raw materials like ferrite and ceramic capacitors. Raw material price volatility, particularly for iron oxides, represents a structural supply chain risk. Distribution primarily runs through Tier-1 suppliers to automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive noise filter market presents a late-cycle quality story, driven by the shift towards advanced infotainment and ADAS requiring superior signal integrity. This evolution prioritizes performance and reliability over basic functionality.
For Market Incumbents:
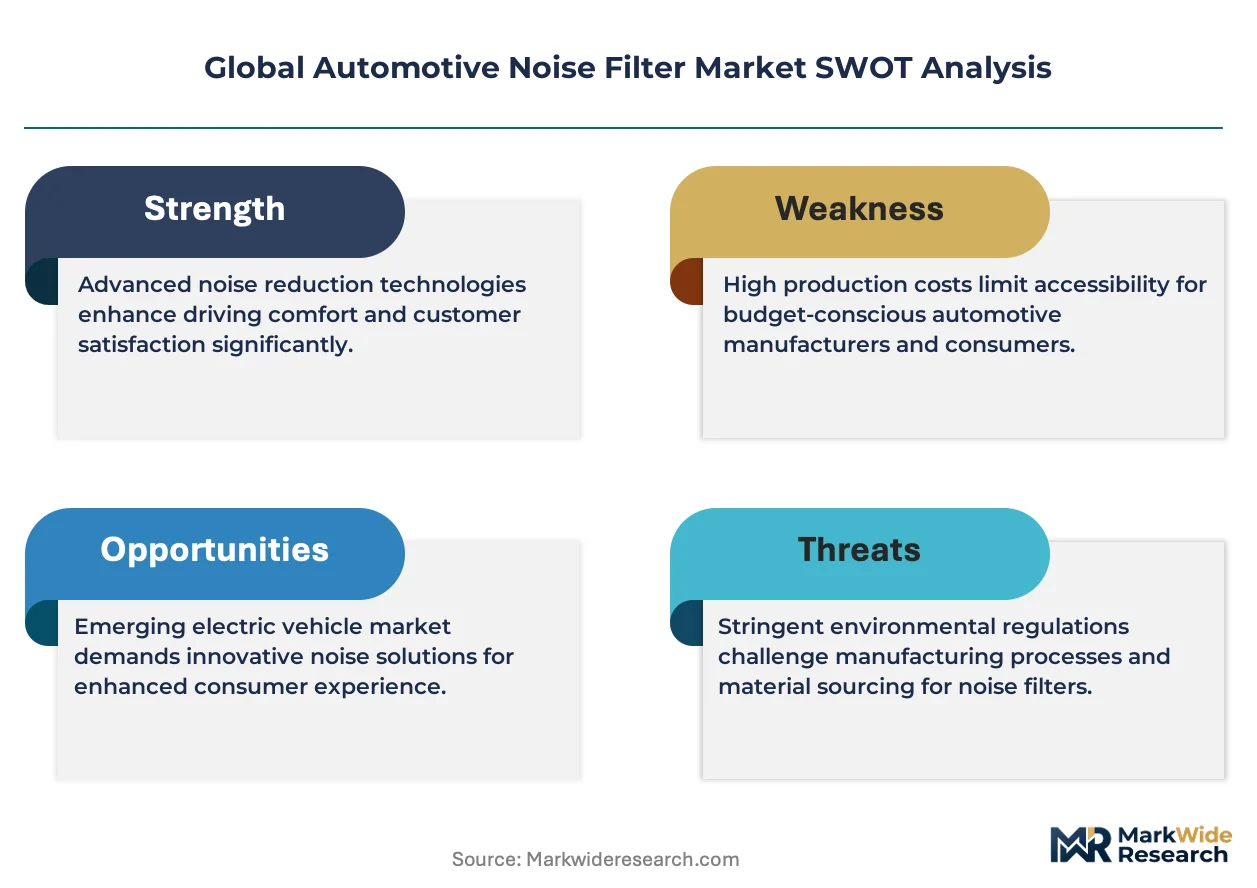
Deploy system integration expertise to embed advanced filtering within broader electronic control unit platforms. Invest in R&D for software-defined adaptive filtering to counter the long-term threat of on-chip integration. Consolidate market share by providing pre-validated filter modules to OEMs, leveraging existing relationships. This strategy mitigates margin pressure from commoditized passive components.
For New Entrants and Emerging Players:
Capture white-space opportunities in aftermarket solutions for Vehicle-to-Grid (V2G) applications. Target the build-out of DC fast-charging stations, which require specialized high-power EMI filters for grid stability. The charging infrastructure segment offers a penetrable market due to its nascent stage. Go-to-market strategies should emphasize robust, application-specific solutions.
For Investors and Strategic Acquirers:
Tier-1 suppliers are the most active acquirers in this space, seeking to deepen their system integration capabilities. The market exhibits long-term viability over the next decade, driven by sustained EV proliferation and stricter EMC standards. Acquisition targets should be specialized component makers with expertise in high-frequency, miniature solutions. The adoption rate of silicon carbide inverters serves as a key inflection indicator for advanced filtering demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Software-Defined Filtering R&D | Drives high-margin growth by offering dynamic noise cancellation for advanced EV powertrains. |
| Expand into EV Charging Infrastructure | Accesses a new, high-growth application segment for high-power EMI filters. |
| Strengthen System Integration Capabilities | Positions suppliers to deliver pre-validated filter modules for complex electronic control units. |
| Develop Miniaturized High-Frequency Components | Meets demand from dense circuit boards in advanced infotainment and ADAS systems. |
| Pursue Global EMC Standard Certifications | Ensures market access and compliance across diverse regulatory environments like EU CE marking and China GB standards. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform this analysis. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, R&D directors, and regulatory compliance specialists provided deep insights. Secondary validation utilized vehicle production databases, customs/trade data, EMC standard publications, and company annual reports. A bottom-up and top-down triangulation approach ensured data consistency.
Segment-weighting across product type, technology, application, end-user, and vehicle class formed the analytical framework over the projection horizon. Compound annual growth rates (CAGRs) were derived from historical trends and projected market dynamics. Key industry-specific forecast inputs included electric vehicle production volumes and the increasing electronic content per vehicle. This model accounts for evolving regulatory landscapes.
Raw material price volatility, shifts in global EV policy, and rapid technological advancements in semiconductor integration are the dominant revision risks for these forecasts. These projections reflect assumptions based on current market conditions and regulatory trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Headliners Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Automotive Glass Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Automobile Accessories Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Brackets Market
Automotive Components
North America Automotive Heat Shield Market