
 India Automotive Stamping Market | 2026-2036
India Automotive Stamping Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Stamping Market Outlook
Tier-1 supplier networks is reconfiguring as OEMs consolidate vendor bases around full-service stamping partners. Gestamp Automobile India Private Limited leverages its hot-stamping expertise to anchor programs for premium SUV platforms. Tata Autocomp Systems Limited sustains dominance through backward integration into die design and toolroom operations. JBM Group differentiates via dedicated lines serving electric vehicle skateboard architectures.
Automotive stamping employs mechanical or hydraulic presses to shape sheet metal blanks into structural and cosmetic vehicle components, typically achieving tolerances within 0.1 mm for Class A body panels. The process serves as the foundational manufacturing stage for vehicle crash structures, closure panels, and powertrain enclosures. Body Panels command the largest value pool due to complexity and surface-quality requirements, while Chassis Components represent the fastest-expanding segment as electric vehicles demand novel subframe geometries. Steel retains volume leadership, though Aluminum is gaining share where OEMs pursue mass reduction for battery range extension.
BIS certification and ARAI homologation govern material grades and dimensional repeatability for stamped safety-critical parts, while PLI scheme incentives shape capital allocation toward high-tonnage press investments. The Ministry of Road Transport and Highways mandates offset and side-impact compliance, elevating requirements for advanced high-strength steel forming. Stakeholders must monitor how Bharat NCAP progression and state-level EV manufacturing policies redirect tooling budgets toward aluminum-capable and multi-material press configurations.
Market Dynamics
Crashworthiness mandates from ARAI and BIS are compressing supplier qualification timelines while OEMs simultaneously consolidate vendor bases around full-service stamping partners capable of multi-material forming.
Growth Catalysts
- Bharat NCAP progression:Offset and side-impact compliance deadlines are forcing OEMs to source advanced high-strength steel components from certified stampers, expanding the addressable market for safety-critical parts.
- PLI scheme for automotive manufacturing:Capital subsidies for high-tonnage press investments are accelerating capacity expansion among domestic suppliers serving electric vehicle programs.
- Tamil Nadu and Maharashtra clustering:Vehicle assembly concentration in these states anchors supplier ecosystems, reducing logistics costs and enabling just-in-time delivery contracts.
Market Restraints
- Aluminum price volatility:Input cost swings for lightweight alloys compress margins on EV chassis programs where OEMs lock pricing multi-year.
- Die import dependence:Precision tooling for Class A surface panels relies heavily on German and Japanese suppliers, creating currency exposure and extended lead times.
- BIS certification bottlenecks:Material grade approvals and dimensional repeatability testing create 6-12 month qualification delays for new part introductions.
Strategic Opportunities
- Gujarat and Karnataka expansion:Emerging EV manufacturing corridors in these states lack mature stamping ecosystems, creating first-mover advantages for relocating suppliers.
- Hot-stamping aluminum:Convergence of heat treatment and high-speed forming technologies enables complex geometries previously restricted to steel, opening battery enclosure applications.
- ARAI homologation services:Stamping houses with in-house testing capabilities can capture value from OEMs seeking bundled design-validation-production contracts.
Industry Challenges
- Toolroom technician scarcity:Die maintenance and repair functions face acute shortages of skilled machinists trained on five-axis CNC equipment.
- Multi-material press integration:Legacy mechanical lines require costly retrofitting to handle aluminum without galling, stretching capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Stamping Market |
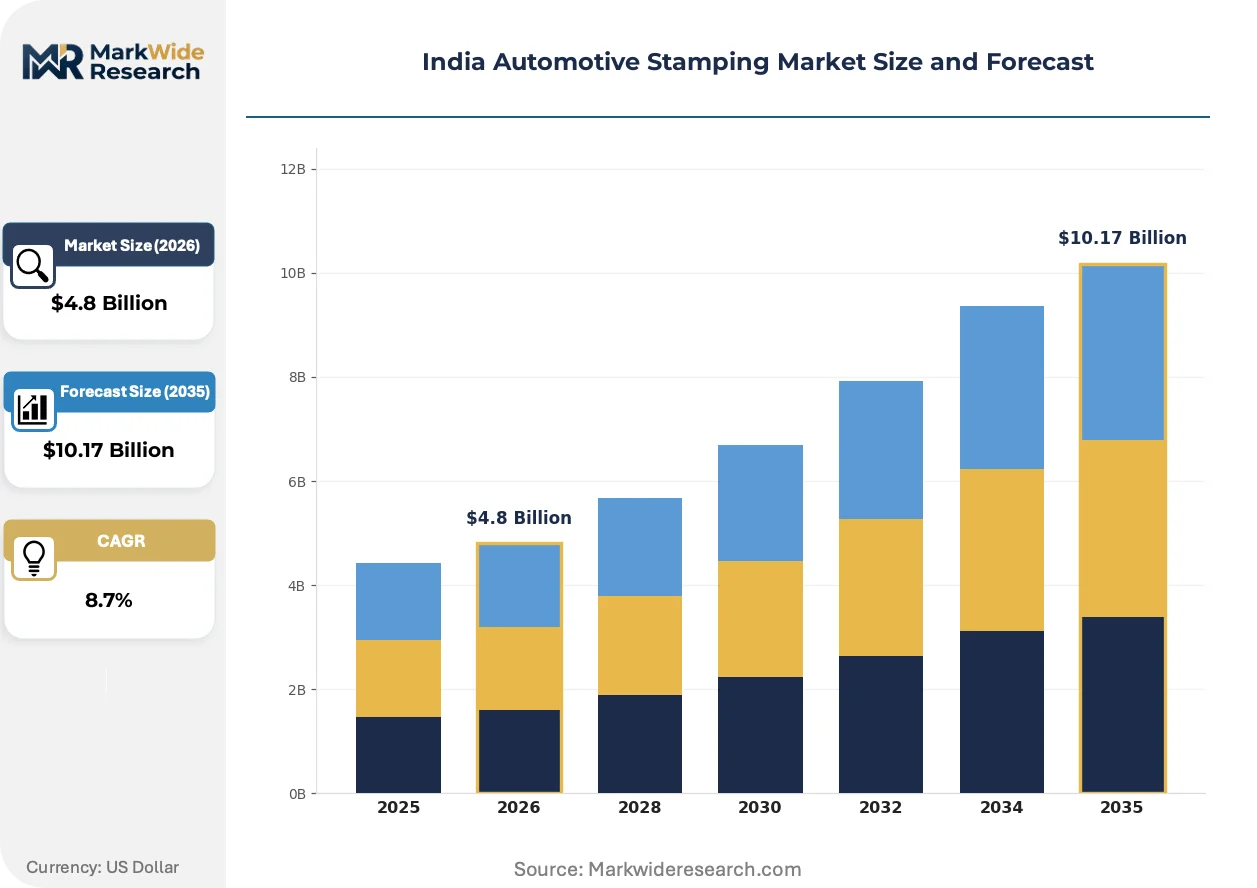
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Panels, Chassis Components, Engine Parts, Transmission Cases Material: Steel, Aluminum, Composite, Plastic Technology: Stamping, Hydroforming, Deep Drawing, Blanking End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Omax Auto Ltd., Gestamp Automobile India Private Limited, Automotive Stampings and Assemblies Ltd., Klt Automotive And Tubular Products Limited, Cosma International (India) Private Limited, JBM Group, Tata Autocomp Systems Limited, Autocomp Corporation Panse Pvt. Ltd., Mahindra CIE Automotive Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Stamping Market Strategic Shifts
Digital twin simulation and servo-electric press controls are compressing die tryout cycles while enabling real-time quality feedback loops that reduce scrap rates in high-volume production.
Servo-electric press technology replaces flywheel-driven mechanical systems with programmable torque curves that optimize slide velocity for each forming stage. Maruti Suzuki and Hyundai Motor India are specifying these systems for new body-in-white investments. Conventional knuckle-joint presses are rendering obsolete for complex draw operations requiring velocity profiling.
BIS amended its automotive steel standards in 2023 to mandate Charpy impact testing for structural grades used in passenger safety cells. The revision disqualifies uncertified imports and elevates domestic mill qualifications. Tier-1 stampers in Pune and Chennai are absorbing compliance costs through dedicated metallurgical labs.
Fleet operators and shared mobility platforms now specify component traceability from melt source to finished part, replacing commodity purchasing with audit-intensive supplier development programs. This behavior shift concentrates procurement among stampers with ERP-to-OEM data integration. Mahindra's electric SUV sourcing exemplifies the pattern in Maharashtra's manufacturing belt.
India Automotive Stamping Market Segmentation
Segmentation in automotive stamping reveals how tooling investments, certification requirements, and supply chain proximity concentrate value capture among specific product-material combinations. Understanding these divisions exposes where BIS compliance costs and PLI subsidies reshape competitive positioning across the supplier base.
Product Type:
After-sales service intensity varies dramatically across stamped component categories, with collision repair networks driving replacement demand for cosmetic panels while powertrain parts rely on warranty channels.
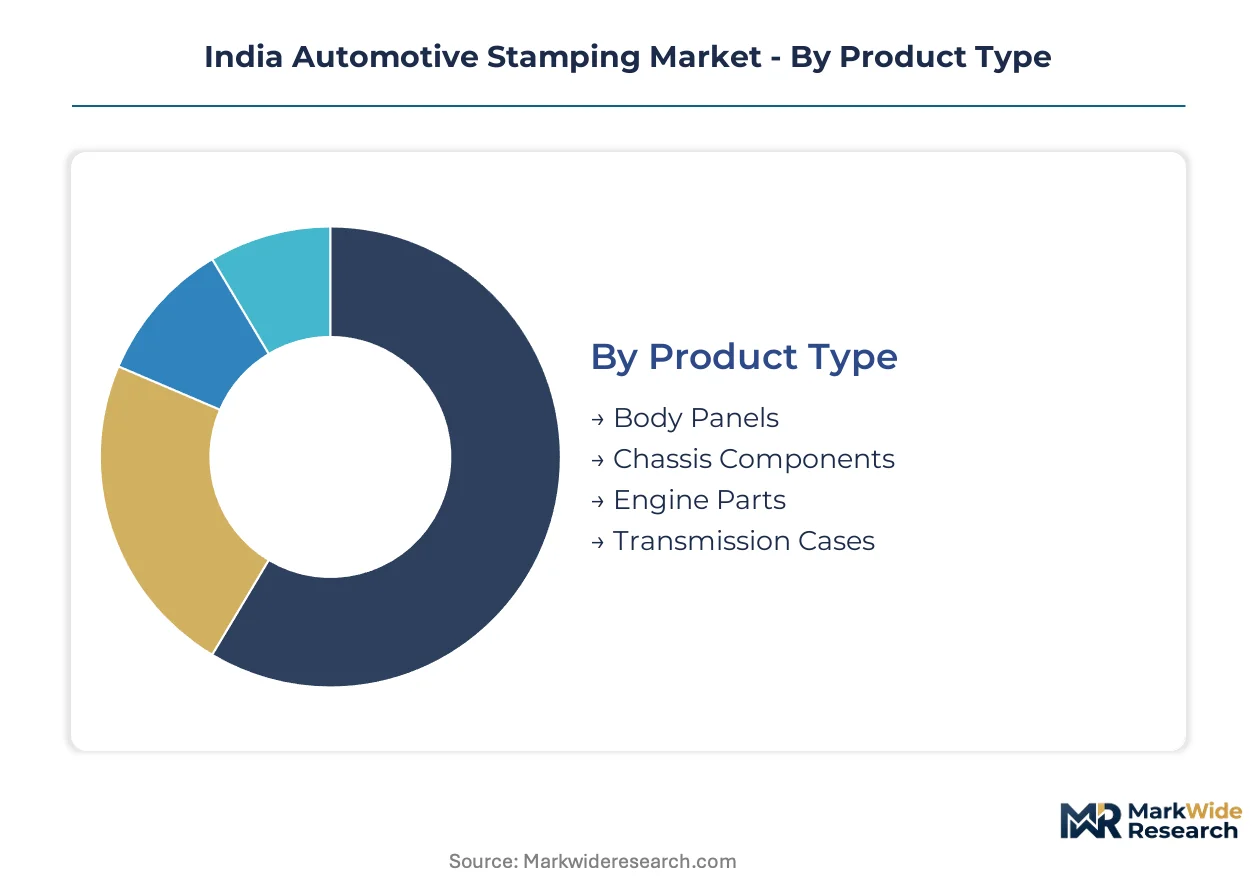
- Body Panels:Class A surface components including hoods, doors, fenders, and roof skins require 0.1 mm tolerances and specialized press lines for cosmetic finish quality. Demand concentrates in Tamil Nadu and Maharashtra assembly corridors where Maruti Suzuki and Hyundai Motor India anchor supplier ecosystems, though BIS surface defect standards compress margin recovery on warranty claims.
- Chassis Components:Subframes, crossmembers, and suspension mounts for electric vehicle skateboard platforms demand novel geometries with aluminum compatibility. Pune and Chennai stampers are capturing battery enclosure programs as OEMs consolidate vendor bases around full-service partners capable of multi-material forming.
- Engine Parts:Oil pans, valve covers, and timing chain housings retain steel dominance in internal combustion platforms.
- Transmission Cases:Clutch housings and gear casings face declining volumes as electrification displaces mechanical drivetrains.
Body Panels holds the largest share; momentum sits with Chassis Components.
Material:
Raw material selection directly determines press line configuration, with aluminum-capable equipment requiring servo-electric retrofits that stretch capital cycles beyond mechanical steel-dedicated systems.
- Steel:Advanced high-strength grades dominate passenger safety cells under Bharat NCAP progression, with AHSS and UHSS now mandatory for offset impact compliance. Domestic mills in Jamshedpur and Bhilai are upgrading Charpy certification capabilities to meet BIS 2023 amendments.
- Aluminum:Battery tray stampings and closure panels for range extension drive fastest expansion, though price volatility compresses margins on locked OEM contracts. Hot-stamping aluminum convergence enables complex geometries previously restricted to steel.
- Composite:Glass-mat thermoplastics appear in non-structural interior brackets.
- Plastic:Polymer alternatives displace metal in fascia and trim applications.
Steel retains volume leadership; aluminum gains share fastest.
Technology:
Process selection reflects the tension between legacy mechanical press utilization and servo-electric investments demanded by velocity profiling for complex draws.
- Stamping:Conventional mechanical and hydraulic presses remain foundational for high-volume body-in-white production, with knuckle-joint systems rendering obsolete for complex operations. Maruti Suzuki specifications now mandate servo-electric controls for new press investments.
- Hydroforming:Fluid-pressure shaping enables hollow structural sections with variable wall thickness for crash-optimized subframes. ARAI homologation requirements for hydroformed safety parts extend qualification timelines.
- Deep Drawing:Multi-stage forming for fuel tanks and wheel wells requires dedicated transfer press lines.
- Blanking:Precision shearing operations feed progressive die sequences for high-speed bracket production.
Stamping commands installed capacity; hydroforming climbs the fastest.
End User:
Customer type determines contract structure, with OEM direct relationships demanding ERP integration and traceability while aftermarket channels tolerate longer lead times.
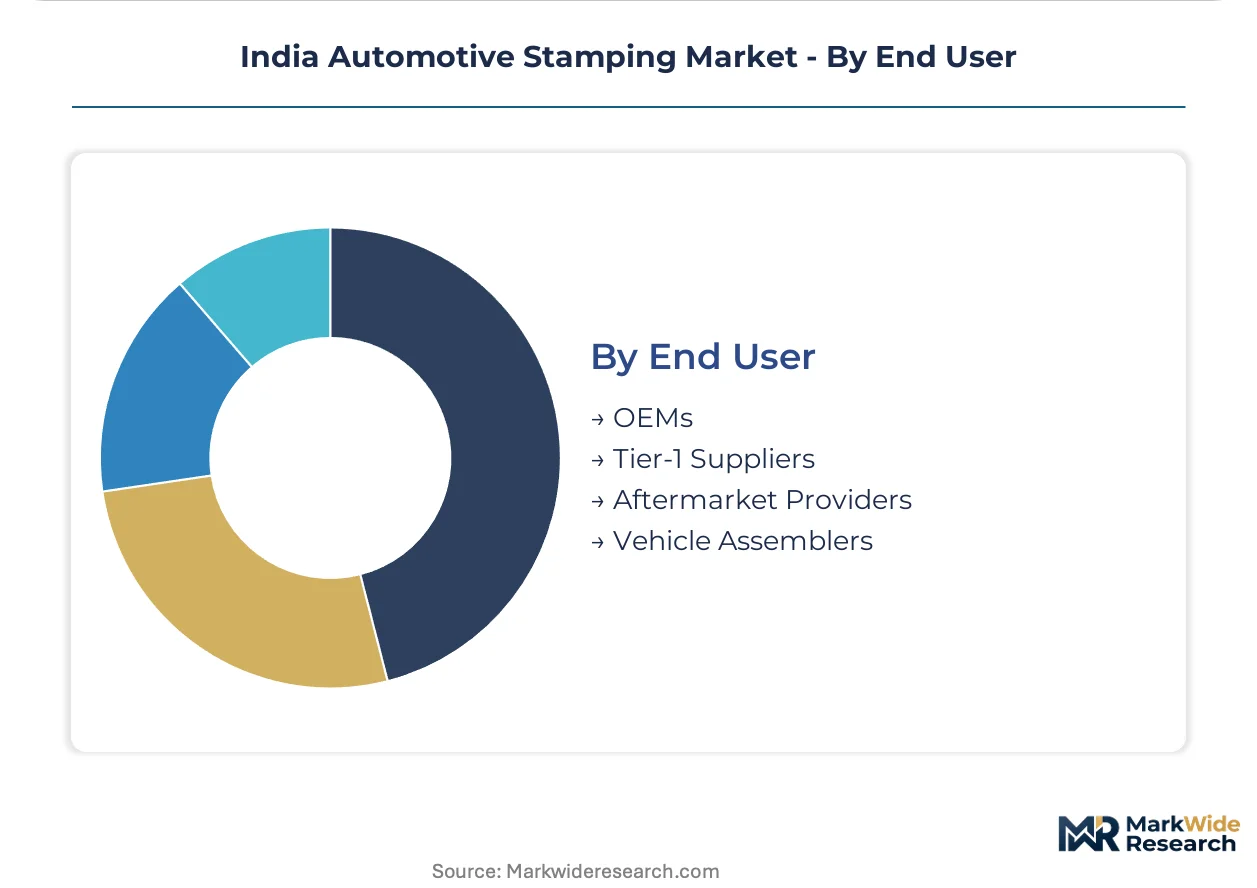
- OEMs:Maruti Suzuki, Tata Motors, and Mahindra specify full-service stamping partners with in-house die design and ARAI testing capabilities, consolidating vendor bases around tier-1 integrators. Fleet operators now mandate melt-source traceability through ERP data integration.
- Tier-1 Suppliers:Gestamp and Tata Autocomp Systems leverage backward integration into toolroom operations to capture bundled design-validation-production contracts from vehicle assemblers.
- Aftermarket Providers:Collision repair networks source certified replacement panels through authorized distributor channels.
- Vehicle Assemblers:Contract manufacturers and shared mobility platforms procure standardized components through consolidated procurement programs.
OEMs anchor value capture; tier-1 suppliers are expanding scope fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust and Chennai Port anchor automotive component logistics corridors that feed stamping clusters across peninsular India. Dedicated freight corridors and expressway networks now compress supplier delivery windows to vehicle assembly plants. State-level EV manufacturing policies are redrawing supplier geography beyond traditional strongholds.
Maharashtra
Pune and Chakan anchor India's densest automotive supplier ecosystem, with Maruti Suzuki and Tata Motors assembly plants driving demand for Class A body panels. The state's EV manufacturing policy offers capital subsidies for high-tonnage press investments. Aurangabad and Nashik are emerging as secondary clusters for chassis component stampers serving electric SUV platforms.
Tamil Nadu
Chennai, Sriperumbudur, and Oragadam form the southern manufacturing belt where Hyundai Motor India and Renault-Nissan anchor supplier networks. The Tamil Nadu EV policy mandates local value addition thresholds that favor stampers with in-house die design capabilities. Coimbatore toolrooms supply precision dies to Tier-1 integrators concentrated around the Chennai metropolitan area.
Gujarat
Sanand and Halol lack mature stamping ecosystems despite hosting Tata Motors and MG Motor assembly operations. The state's EV manufacturing incentives attract first-mover suppliers seeking to establish captive capacity before competitor entry. Mundra Port's container handling infrastructure reduces import lead times for precision tooling from German and Japanese sources.
Karnataka
Bengaluru and Hosur concentrate electric two-wheeler and three-wheeler assembly, creating demand for lightweight aluminum chassis stampings. The Karnataka EV policy prioritizes battery and component manufacturing zones around Doddaballapur and Narasapura. Supplier gaps persist for high-tonnage press capacity capable of body-in-white production.
Haryana
Manesar and Gurgaon host Maruti Suzuki's largest manufacturing complex, sustaining a captive supplier base for steel-intensive vehicle programs. The Delhi-Mumbai Industrial Corridor freight link reduces inbound material costs for Jamshedpur-sourced steel. Stampers here face pressure to retrofit lines for aluminum compatibility as OEMs diversify powertrain portfolios.
India Automotive Stamping Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in a vendor base consolidating around full-service stamping partners. The competitive structure reflects a tension between legacy mechanical press operators and servo-electric investors. Three archetypes dominate: multinational Tier-1 integrators with hot-stamping expertise, domestic conglomerates with backward die design integration, and mid-cap specialists serving EV skateboard architectures. Competitive moves center on capacity expansion in emerging EV corridors and strategic partnerships for aluminum forming technology licensing.
Among India-based fabricators, Tata Autocomp Systems Limited and JBM Group exemplify the conglomerate-backed integrator archetype with captive toolroom capabilities. Gestamp Automobile India Private Limited occupies a position representing multinational hot-stamping specialists anchoring premium SUV programs. These three entities collectively illustrate how supplier qualification timelines and BIS certification requirements favor established players with dedicated metallurgical testing infrastructure.
| Leading Market Players |
|---|
| Omax Auto Ltd. |
| Gestamp Automobile India Private Limited |
| Automotive Stampings and Assemblies Ltd. |
| Klt Automotive And Tubular Products Limited |
| Cosma International (India) Private Limited |
| JBM Group |
| Tata Autocomp Systems Limited |
| Autocomp Corporation Panse Pvt. Ltd. |
| Mahindra CIE Automotive Limited |
| Others |
Value Chain & Pricing Dynamics
Aluminum price volatility determines both pricing tier spreads and supply chain shape in the India automotive stamping market. Cost compression in battery enclosure programs forces tier-1 stampers to absorb input swings while OEMs lock multi-year pricing, widening spreads between steel-dedicated and aluminum-capable press lines.
Pricing Analysis
Volume-discount tiering separates full-service integrators from commodity bracket suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification grade and ARAI homologation depth. Price differentiation hinges on die design backward integration and in-house metallurgical testing capabilities. Pricing pressure stems from locked OEM contracts on EV chassis programs where aluminum input costs swing independently. Fleet operators and shared mobility platforms show highest price sensitivity through consolidated procurement programs, while premium SUV platforms tolerate premium tiering for hot-stamped safety cells.
Supply Chain Analysis
Extended payment terms from OEMs strain supplier-financing capacity, forcing stampers to rely on supply-chain finance facilities for die import cycles. Precision tooling for Class A surface panels draws from German and Japanese sources, creating currency exposure and extended qualification timelines. Raw material dependencies rest on Jamshedpur and Bhilai steel mills for AHSS grades, plus imported aluminum billet for battery tray programs. Single-source vulnerability concentrates in die design capabilities where Coimbatore toolrooms feed Chennai integrators. Distribution runs through just-in-time contracts anchored to Tamil Nadu and Maharashtra assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as electric vehicle platform diversification splinters demand across novel chassis geometries and multi-material forming requirements. Supplier consolidation around full-service partners leaves white space for specialists in emerging corridors.
For Market Incumbents: Build certification moats through captive ARAI homologation infrastructure. Tata Autocomp Systems and Gestamp Automobile India Private Limited anchor competitive positioning through backward integration into die design and metallurgical testing. Incumbents should expand servo-electric press capacity in Gujarat before competitor entry locks corridor access. Threat of aluminum price volatility demands hedging mechanisms or steel-aluminum hybrid process capabilities.
For New Entrants and Emerging Players: Pursue first-mover positioning in Karnataka's battery component manufacturing zones where high-tonnage press capacity gaps persist. White space concentrates in aluminum hot-stamping for battery enclosures and electric two-wheeler chassis stampings. Go-to-market angle should bundle BIS certification services with production contracts, capturing OEM demand for bundled design-validation-production partnerships.
For Investors and Strategic Acquirers: Bharat NCAP progression reshapes the acquisition landscape toward stampers with advanced high-strength steel forming capabilities and in-house testing infrastructure. Long-term viability favors platform integrators with die design backward integration over commodity bracket suppliers. Acquisition target archetype: mid-cap specialists with aluminum-capable press lines and established OEM relationships in emerging EV corridors. Signal to watch is PLI scheme capital subsidy disbursement rates indicating capacity expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Press Investment | Maruti Suzuki and Hyundai Motor India specifications now mandate programmable torque curves for complex draw operations. |
| ARAI Homologation Infrastructure | In-house testing capabilities capture bundled contracts from OEMs consolidating vendor bases around full-service partners. |
| Aluminum Hot-Stamping Capability | Convergence of heat treatment and high-speed forming opens battery enclosure applications previously restricted to steel. |
| Gujarat Corridor Expansion | Sanand and Halol lack mature stamping ecosystems despite hosting Tata Motors and MG Motor assembly operations. |
| Die Design Backward Integration | Coimbatore toolroom proximity to Chennai integrators creates captive supply advantages for tier-1 positioning. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and die design specialists and refined through secondary validation. Primary fieldwork combined structured interviews with plant managers at Pune and Chennai stamping facilities alongside channel discussions with dealership operations. Secondary sources encompassed BIS certification databases, ARAI homologation records, vehicle production data from IHS Markit, and PLI scheme disbursement filings. Bottom-up capacity assessments across 15+ press facilities were triangulated against top-down demand modeling from OEM platform rollout schedules.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompassed product type, material grade, press technology tier, end-user contract structure, and regional production cluster. CAGRs were derived from production volume trajectories weighted by content-per-vehicle assumptions for electric versus internal combustion platforms. Industry-specific forecast inputs included Bharat NCAP compliance timelines and state-level EV manufacturing policy incentive structures.
Sensitivities concentrate around aluminum price volatility, BIS certification bottleneck durations, and PLI scheme capital subsidy continuity. Forecasts reflect documented assumptions regarding OEM vendor consolidation velocity and die import lead time stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Silencer Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
China Automotive Composites Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive Hardware Market