
 Automotive Bushing Market | 2026-2036
Automotive Bushing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bushing Market Intelligence
The traditional separation between mechanical engineering and polymer science expertise is collapsing as component design requires integrated knowledge. This shift favors suppliers with deep material science capabilities. Freudenberg Sealing Technologies GmbH & Co. KG leverages its extensive polymer portfolio to meet evolving NVH requirements. Continental AG competes by integrating advanced bushing solutions within its broader chassis and safety systems, while AB SKF specializes in high-performance bearing and bushing assemblies.
An automotive bushing is a mechanical component that isolates vibration and allows for limited movement between two vehicle parts. Typically constructed from rubber, polyurethane, or other elastomers bonded to a metal sleeve, it dampens noise and absorbs shock from road imperfections. Polyurethane bushings are a high-growth product category, valued for their durability and performance characteristics in suspension systems. The OEM segment remains the largest channel, with Tier-1 manufacturers supplying directly to vehicle assembly lines for new builds.
Product specifications are influenced by multiple regulatory frameworks, including the EU's REACH regulations on chemical substances and the US EPA's vehicle safety and emissions standards. In China, compliance with GB standards for automotive components is mandatory for market access. Stakeholder success depends on adapting material formulations to meet divergent regional performance and environmental compliance mandates.
Market Dynamics
The convergence of material science and mechanical engineering is the central force redefining the automotive bushing market. Component design now demands integrated expertise, shifting value toward suppliers capable of formulating advanced polymers to meet specific NVH and lightweighting targets for electric vehicle platforms.
Growth Catalysts
- Electric Vehicle Platforms:The higher bushing content required for advanced multi-link suspensions and battery pack isolation in electric vehicles stimulates significant demand for high-performance elastomers and polyurethanes.
- Stringent NVH Standards:The silent operation of EVs makes passengers more sensitive to road noise, compelling OEMs to invest in sophisticated bushing solutions that offer superior noise, vibration, and harshness dampening.
- Regulatory Mandates on Materials:Chemical regulations like the EU's REACH framework are pushing manufacturers to develop and adopt new, compliant elastomer formulations, creating opportunities for material innovators.
Market Restraints
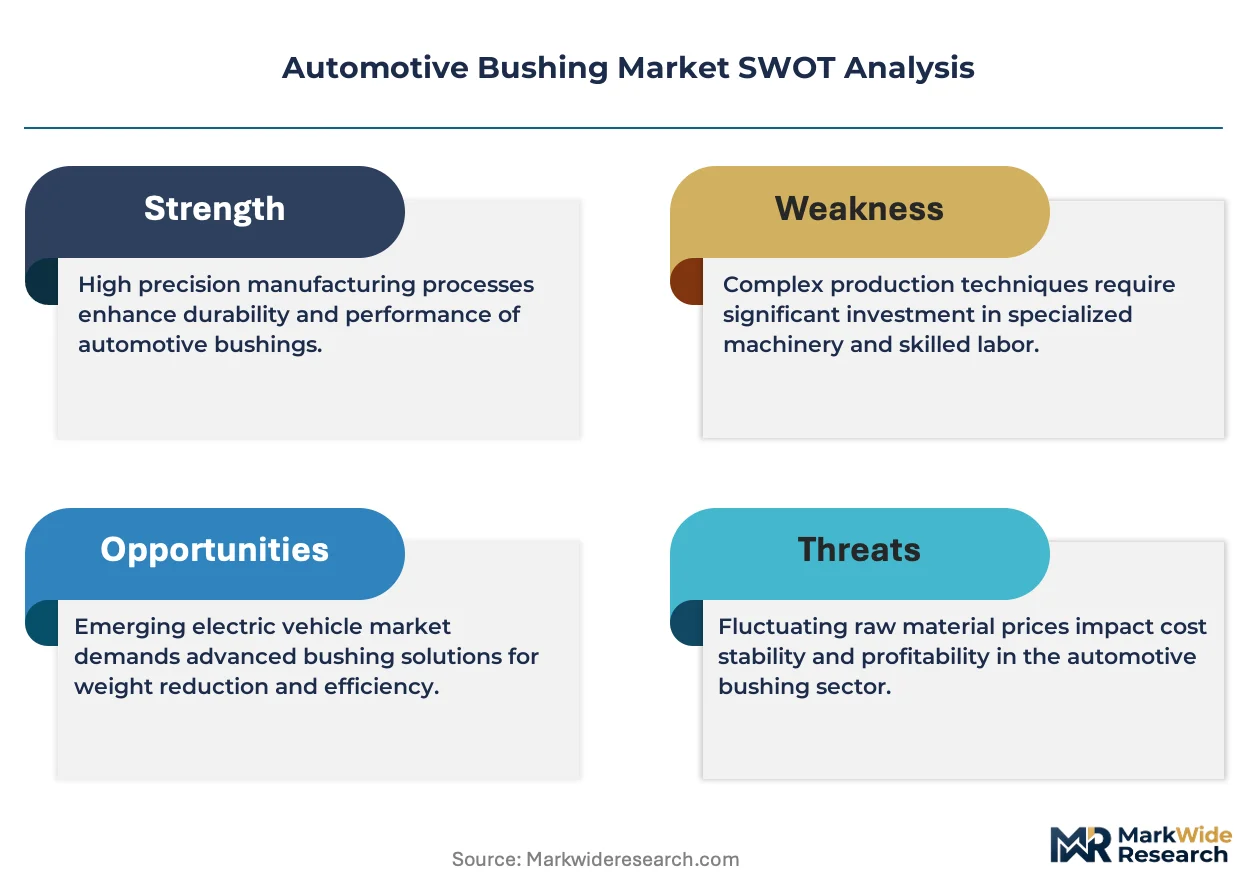
- Raw Material Price Volatility:Fluctuations in the cost of key inputs, such as natural rubber, synthetic elastomers, and specialty polymers, create margin pressure and complicate long-term supply contracts with OEMs.
- Performance Trade-Offs:A fundamental technical constraint exists where enhancing bushing durability and stiffness, often with polyurethane, can compromise its ability to absorb high-frequency vibrations, creating design challenges.
- Threat from Active Systems:The development of advanced active and semi-active suspension systems can reduce the reliance on passive bushings for vibration control, posing a long-term substitution risk in high-end vehicle segments.
Strategic Opportunities
- Bio-Based and Recycled Materials:Developing bushings from sustainable, bio-based, or recycled elastomers creates a strong value proposition for OEMs focused on meeting corporate sustainability goals and regulations like the EU Green Deal.
- Aftermarket for Aging Fleets:Expanding into the aftermarket in regions like Latin America and Southeast Asia offers growth, as an aging vehicle parc requires a steady stream of replacement suspension components.
- Thermal Management Applications:The need to isolate and manage vibration in EV battery packs and associated cooling systems opens a new application category for specialized, thermally resistant bushing components.
Industry Challenges
- Integrated Engineering Skills Gap:A scarcity of talent possessing dual expertise in polymer chemistry and mechanical dynamics impedes the rapid development of next-generation, system-integrated bushing solutions.
- Divergent Global Standards:Managing compliance across disparate regulatory regimes, including China's GB standards, EU's REACH, and US EPA rules, increases the complexity and cost of product development and testing.
- Tooling and Manufacturing Adjustments:Shifting production to advanced materials like cast polyurethanes requires significant capital investment in new molding equipment, processes, and quality control systems, creating a barrier for smaller suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bushing Market |
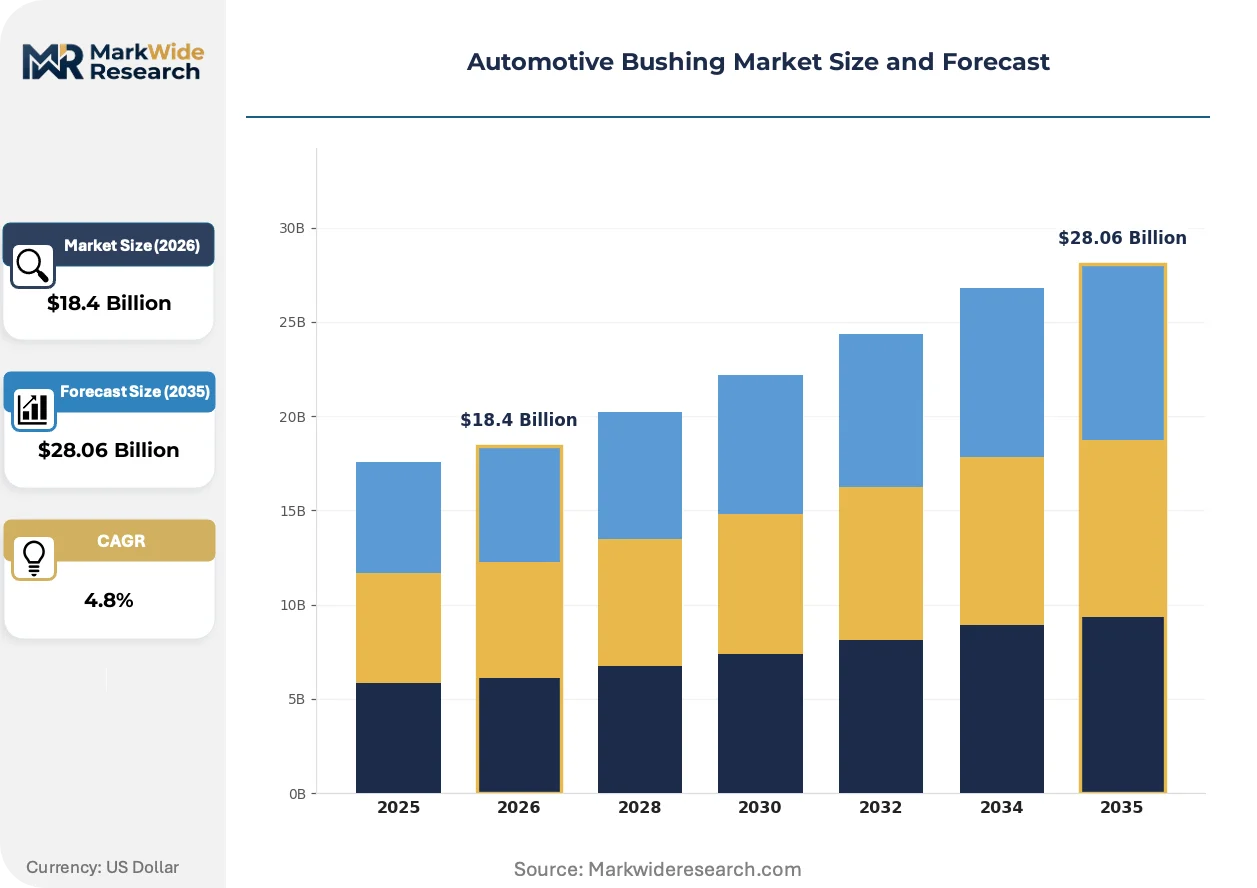
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bushings, Polyurethane Bushings, Metal Bushings, Plastic Bushings End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Aftermarket Retailers Application: Suspension Systems, Steering Systems, Engine Mounts, Transmission Mounts Installation Type: Vehicle Assembly, Retrofit, Maintenance, Replacement |
| Companies Covered | Freudenberg Sealing Technologies GmbH & Co. KG, AB SKF, Continental AG, ZF Friedrichshafen AG, Dana Incorporated, Vibracoustic GmbH, Sumitomo Riko Co., Ltd., MAHLE GmbH, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bushing Market Strategic Shifts & Innovations
Material science is fundamentally re-engineering the function of bushings beyond simple vibration dampening. Innovations in polymer formulation and component design are transforming these parts into critical enablers of vehicle dynamics, acoustic comfort, and overall platform efficiency, particularly within electric vehicles.
Self-sensing bushings embedded with miniature sensors represent a significant technological evolution. These components provide real-time feedback on road load and suspension articulation, a feature being adopted by premium automotive brands for use in adaptive suspension systems. The introduction of this capability is fragmenting the traditional component landscape, creating a distinct and higher-value segment for active, intelligent bushings alongside conventional passive ones.
The EU's End-of-Life Vehicles (ELV) Directive is accelerating a design-for-recycling movement. This mandate pressures suppliers to move away from traditional thermoset rubber bonded to metal, which is difficult to separate and recycle at the end of a vehicle's life. Material specialists are actively developing advanced thermoplastic elastomers (TPEs) that offer comparable performance but can be more easily melted and reused, directly addressing the circular economy goals of European regulators.
A notable shift in OEM sourcing strategy involves moving from purchasing individual components to procuring complete, pre-assembled modules. This evolution disrupts the business model for pure-play bushing manufacturers, as it favors large Tier-1 suppliers capable of integrating bushings into entire sub-frames or corner suspension modules. This trend is especially visible in North America and Europe, where platform consolidation by major automakers drives demand for modularity to streamline final assembly lines.
Automotive Bushing Market Segmentation
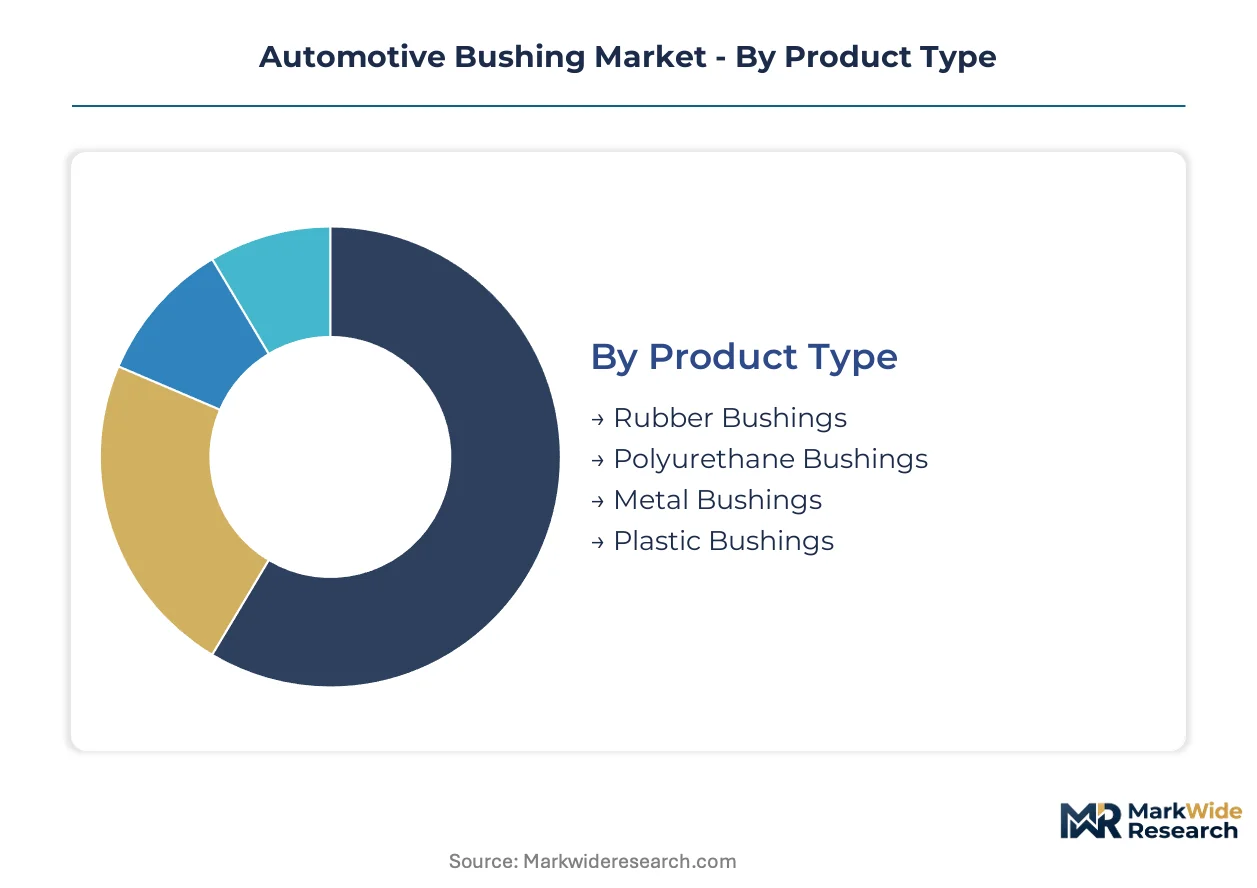
The automotive bushing market exhibits diverse segmentation driven by material science advancements, evolving vehicle architectures, and distinct end-user requirements. Understanding these segments is crucial for stakeholders to align product development and market strategies with prevailing industry demands and regulatory landscapes.
Product Type:
The automotive bushing market faces substitution pressure as advanced material formulations challenge traditional component choices.
- Polyurethane Bushings:These components utilize advanced synthetic polymers, offering superior durability, load-bearing capacity, and resistance to chemicals. Demand concentrates in electric vehicle platforms for enhanced suspension performance and battery isolation, driven by stringent NVH targets.
- Rubber Bushings:Constructed from natural or synthetic rubber bonded to metal, these bushings provide effective vibration dampening and cost-effectiveness. The OEM segment in established automotive manufacturing hubs like Germany and Japan maintains high demand for rubber bushings due to their proven reliability in conventional powertrains.
- Metal Bushings:These rigid components are typically used in applications requiring high stiffness and minimal deflection, often found in heavy-duty or specialized vehicle systems.
- Plastic Bushings:Lightweight and corrosion-resistant, plastic bushings serve niche applications where reduced weight and self-lubrication are critical, such as interior mechanisms.
Rubber Bushings anchor the volume base while Polyurethane Bushings gain share at the steepest rate.
End User:
Supply chain configurations dictate procurement patterns across various end-user segments.
- OEMs:Original Equipment Manufacturers integrate bushings directly into new vehicle production lines, demanding components that meet rigorous performance, durability, and cost specifications. Demand for OEM bushings is strongest in China's expansive automotive assembly plants, driven by new vehicle output.
- Tier-1 Manufacturers:These large suppliers design and assemble complex sub-systems, incorporating bushings from specialized producers before delivering to OEMs. European Tier-1s like Continental AG emphasize integrated chassis solutions, driving demand for advanced bushing assemblies.
- Aftermarket Suppliers:These entities provide replacement parts to distributors and service centers, focusing on compatibility with a wide range of vehicle models and competitive pricing.
- Aftermarket Retailers:Retailers directly serve individual consumers and independent repair shops, offering readily available replacement bushings for vehicle maintenance and repair needs.
Margin differentiation is pronounced between the high-volume OEM segment and the fragmented aftermarket distribution channels.
Application:
Performance requirements vary significantly across different vehicle applications, influencing material selection and design complexity.
- Suspension Systems:Bushings in suspension systems isolate road imperfections and control wheel movement, crucial for ride comfort and handling. Electric vehicle platforms in North America require sophisticated suspension bushings to manage increased weight and quiet cabin expectations.
- Engine Mounts:These components dampen engine vibration and noise before it transmits to the vehicle chassis, contributing significantly to passenger comfort. Demand for advanced engine mount bushings is strong in markets like Japan, where quiet operation and refined driving experiences are prioritized.
- Steering Systems:Bushings within steering systems ensure precise control and reduce unwanted vibrations from the road to the steering wheel, impacting driver feel.
- Transmission Mounts:These components support the transmission and absorb vibrations generated during gear shifts and power delivery, contributing to overall vehicle refinement.
Technological evolution in advanced materials is particularly evident within suspension and engine mount applications.
Installation Type:
The maturity of vehicle fleets and associated service lifecycles define the volume distribution across installation types.
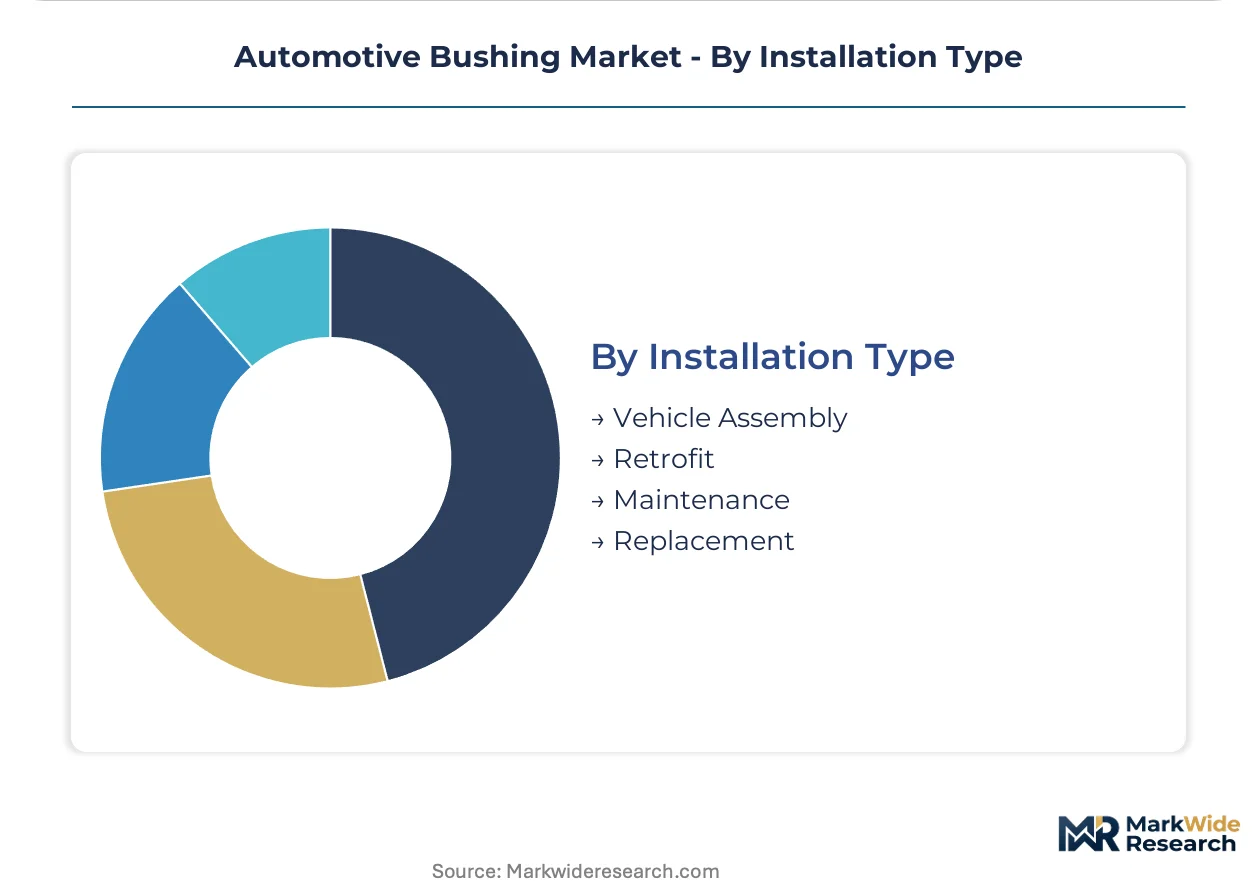
- Vehicle Assembly:This segment involves the initial installation of bushings during the manufacturing of new automobiles on OEM assembly lines. The robust automotive production in China drives substantial demand for bushings in new vehicle assembly.
- Replacement:This category encompasses the installation of new bushings to replace worn-out components during routine vehicle servicing and repair. Aging vehicle fleets in regions like Latin America create a steady and expanding requirement for replacement bushings.
- Maintenance:Bushings used in preventative maintenance ensure optimal vehicle performance and extend component lifespan, often as part of scheduled service intervals.
- Retrofit:This segment involves upgrading existing vehicle systems with enhanced or performance-oriented bushings, often by enthusiasts or for specialized applications.
Vehicle Assembly represents the largest initial demand, while Replacement shows consistent, long-term growth dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for automotive bushings varies significantly by region, reflecting diverse vehicle electrification rates and market maturity. China's expansive automotive manufacturing sector drives substantial demand for OEM bushings, while regions with aging vehicle fleets prioritize aftermarket replacement components. Material innovation and regulatory compliance also influence regional product uptake and market evolution.
China
Demand for OEM bushings concentrates within China's expansive automotive assembly plants, driven by high new vehicle output. Compliance with GB standards for automotive components is mandatory for market access, influencing material specifications. The Yangtze River Delta and Pearl River Delta regions represent major hubs for vehicle production and component sourcing.
Germany
The OEM segment in Germany maintains high demand for rubber bushings, particularly within established automotive manufacturing hubs for conventional powertrains. The EU's REACH framework pushes manufacturers to develop compliant elastomer formulations for new products. Bavaria and North Rhine-Westphalia are key industrial clusters for advanced automotive component development.
United States
Electric vehicle platforms in the United States require sophisticated suspension bushings to manage increased weight and quiet cabin expectations. US EPA vehicle safety and emissions standards influence material selection and performance criteria. Michigan's automotive corridor and California's EV innovation centers drive demand for high-performance solutions.
Japan
Advanced engine mount bushings are in strong demand in Japan, where quiet operation and refined driving experiences are prioritized. JIS standards govern the quality and performance of automotive components across the industry. The Kanto and Chubu regions house significant automotive manufacturing and research facilities.
Brazil
An aging vehicle parc in Brazil creates a steady requirement for replacement bushings, driving growth in the aftermarket segment. Local vehicle safety and emissions standards influence component durability and material choices. São Paulo and Minas Gerais are key areas for automotive assembly and aftermarket distribution.
Automotive Bushing Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the automotive bushing market, reflecting distinct capabilities and market approaches. This tiered structure includes material science innovators, integrated systems providers, and traditional component manufacturers. Companies often pursue strategic partnerships and portfolio diversification to enhance their market position.
Specialists in polymer formulation, such as Freudenberg Sealing Technologies GmbH & Co. KG, leverage extensive polymer portfolios to meet evolving NVH requirements. Continental AG occupies a position as an integrated systems provider, embedding advanced bushing solutions within its broader chassis and safety systems. AB SKF represents an archetype focused on high-performance bearing and bushing assemblies, emphasizing precision engineering.
| Leading Market Players |
|---|
| Freudenberg Sealing Technologies GmbH & Co. KG |
| AB SKF |
| Continental AG |
| ZF Friedrichshafen AG |
| Dana Incorporated |
| Vibracoustic GmbH |
| Sumitomo Riko Co., Ltd. |
| MAHLE GmbH |
| Trelleborg AB |
| Others |
Cost & Logistics Intelligence
The EU's REACH framework gates both material supply qualification and price differentiation for advanced automotive bushing components. This regulation mandates chemical substance compliance, forcing suppliers to invest in new formulations that command a premium in European and global markets.
Pricing Analysis
Long-term offtake agreements dominate pricing for OEM and Tier-1 contracts, ensuring supply stability for critical components. Price differentiation stems from material quality grades, specific NVH performance capabilities, and compliance with regional certification levels like China's GB standards. Pricing pressure stems from raw material price volatility for natural rubber and specialty polymers, impacting overall margins. The aftermarket segment exhibits the highest price sensitivity, while OEMs prioritize performance and reliability.
Supply Chain Analysis
China anchors automotive bushing production for new vehicle assembly, alongside established manufacturing hubs in Germany and Japan. The supply chain draws from raw materials such as natural rubber, synthetic elastomers, and various specialty polymers. A structural risk exists from commodity price volatility, particularly for key elastomer inputs. Distribution runs through a tiered system, with specialized producers supplying Tier-1 manufacturers who then deliver integrated modules to OEMs, alongside a fragmented aftermarket channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive bushing market is undergoing a platform-economics inflection, driven by the integration of advanced suspension systems within electric vehicle architectures. This shift demands new component functionalities and ecosystem interoperability.
For Market Incumbents: Consolidate expertise in polymer science and mechanical engineering to address the integrated engineering skills gap. Acquire material science startups specializing in bio-based or recycled elastomers to meet sustainability mandates like the EU Green Deal. Deepen integration with Tier-1 partners to offer complete sub-assemblies, mitigating the threat from active suspension systems. Invest in R&D for self-sensing bushing technology to capture the higher-value segment.
For New Entrants and Emerging Players: A certification fast-track for compliant bio-based materials creates an entry point for innovative material specialists. Target niche EV applications requiring specialized thermal management bushings, particularly for battery pack isolation. Focus on the aftermarket in aging vehicle fleets within Latin America and Southeast Asia, offering cost-effective, durable replacement solutions. A go-to-market angle emphasizing sustainable material formulations appeals to OEMs focused on corporate environmental goals.
For Investors and Strategic Acquirers: The EU's ELV Directive reshapes the acquisition landscape, favoring companies capable of developing recyclable thermoplastic elastomers. Long-term viability over the next decade centers on firms with dual capabilities in advanced material science and integrated component design. Acquisition targets include specialists in advanced elastomer formulations or manufacturers with established intellectual property in self-sensing technology. The signal to watch is the increasing adoption rate of design-for-recycling principles in OEM platform specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Material R&D | Develops high-performance, compliant elastomers for next-generation EV platforms and stringent NVH targets. |
| Expand Bio-Based Polymer Portfolio | Addresses increasing OEM demand for sustainable materials and compliance with environmental regulations like the EU Green Deal. |
| Develop Self-Sensing Bushing Technology | Creates higher-value components that provide real-time feedback for adaptive suspension systems in premium vehicles. |
| Form Strategic Alliances with Tier-1s | Secures integration into complete sub-frame and suspension modules, aligning with OEM modular sourcing strategies. |
| Target Aftermarket in Emerging Economies | Captures consistent demand from aging vehicle fleets in regions like Latin America, ensuring long-term revenue streams. |
Research Approach
A standing panel of automotive OEM engineers, Tier-1 procurement leads, material science researchers, and aftermarket distributors provided ongoing calibration for market sizing and trend validation. This approach combined insights from primary interviews with extensive secondary validation through vehicle production databases, regulatory filings, and industry association reports. Bottom-up and top-down triangulation ensured data consistency.
Output validation against external benchmarks confirmed the integrity of the forecast framework across the analysis window. Segmentation dimensions modeled included product type, end user, application, installation type, and material formulation. Compound annual growth rates were derived from historical trends, projected market shifts, and expert consensus. Electric vehicle production forecasts and regulatory compliance timelines served as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside unforeseen shifts in raw material supply or rapid adoption of active suspension systems would require recalibration. Forecasts reflect assumptions documented through comprehensive primary and secondary research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Regenerative Suspension System Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Distributor Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Automotive Engine Bearings Market