
 Saudi Arabia Automotive Actuators Market | 2026-2036
Saudi Arabia Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Automotive Actuators Market Analytics
Electrification of vehicle subsystems is reconfiguring actuator architecture across powertrain and chassis domains. Robert Bosch GmbH leverages its integrated mechatronics portfolio to anchor high-volume supply relationships with domestic OEMs. Denso Corporation sustains technology leadership in precision motor-actuator assemblies for thermal management applications. Continental AG competes through specialized electro-hydraulic brake actuators designed for regional climate extremes.
Automotive actuators are electromechanical or fluid-power devices that convert energy into controlled mechanical motion, typically operating at voltage ranges from 12V to 48V in passenger vehicle applications, with stroke lengths from 5mm to 200mm depending on deployment location. Their primary function is to enable automated control of engine airflow, braking force, suspension damping, and HVAC distribution without direct mechanical linkage to the driver. Electric actuators now lead technology adoption as OEMs phase out purely mechanical and hydraulic alternatives, while servo actuator architectures capture margin pools in advanced driver-assistance integrations. Linear actuators dominate volume in power steering and seat adjustment modules, whereas rotary actuator demand accelerates in throttle body and HVAC flap control applications where angular precision requirements are tightening.
SASO technical regulations and SFDA automotive safety standards govern electromagnetic compatibility and functional safety thresholds for actuator systems sold in the Kingdom. The Saudi Energy Efficiency Center mandates fuel-consumption benchmarks that directly incentivize lightweight, low-friction actuator designs in new vehicle platforms. Stakeholders must monitor how domestic content requirements under Vision 2030 industrial policy reshape supplier qualification criteria and localization timelines for electromechanical component manufacturing.
Market Dynamics
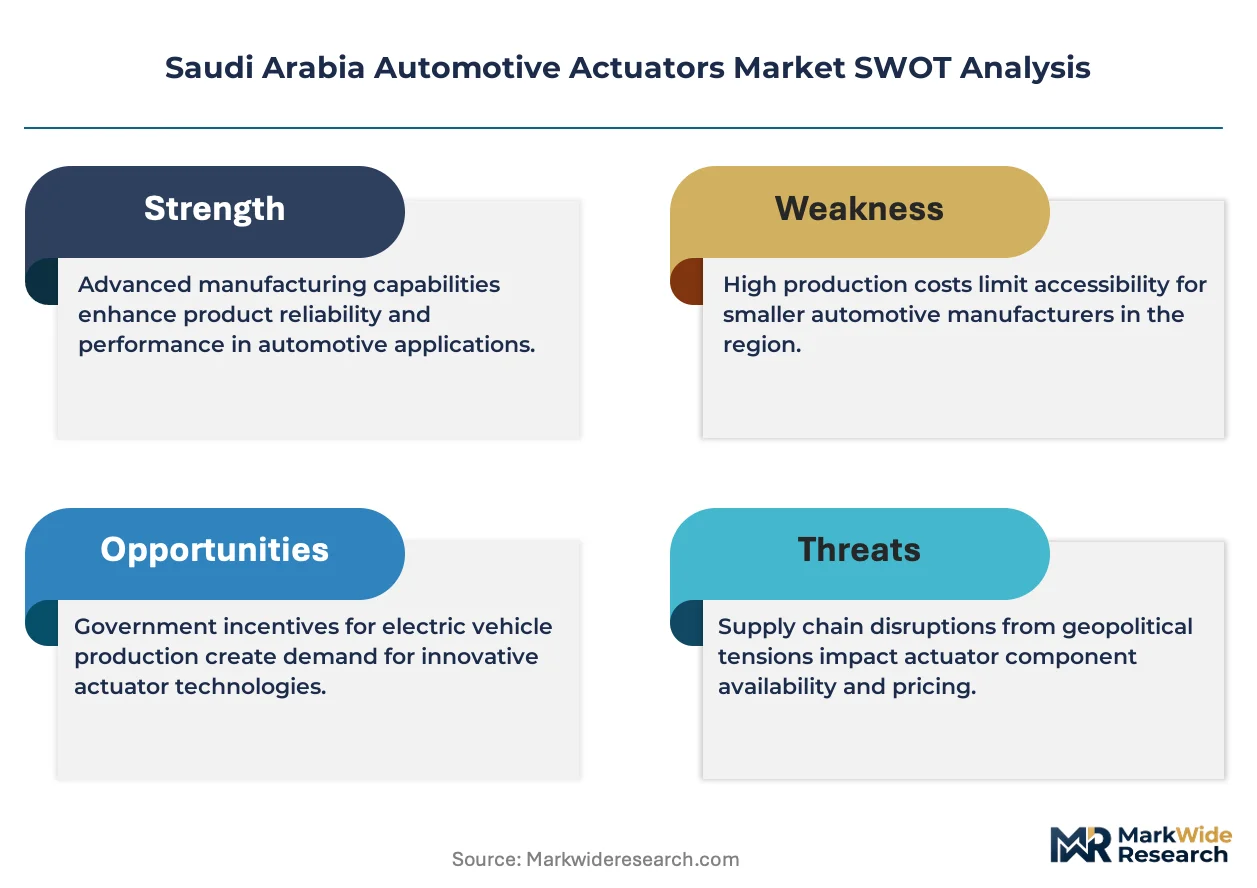
SFDA electromagnetic compatibility mandates and SASO functional safety thresholds are compressing supplier qualification timelines while forcing domestic OEMs to requalify electromechanical subsystems for 48V architectures. This regulatory tightening is accelerating consolidation among tier-one actuator suppliers capable of integrated mechatronics certification.
Growth Catalysts
- SFDA Safety Standards:Electromagnetic compatibility testing requirements for brake-by-wire and steer-by-wire actuators are mandating precision motor-actuator assemblies that domestic assemblers must source from certified tier-one suppliers.
- Riyadh-Jeddah Corridor Clustering:OEM-tier supplier ecosystems concentrating along the Kingdom's primary industrial axis are reducing logistics costs and enabling just-in-time actuator delivery for powertrain and chassis integration.
- 48V Mild-Hybrid Architectures:Voltage platform upgrades across domestic vehicle platforms are expanding addressable market for high-torque electric actuators in thermal management and active suspension modules.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium sourcing dependency on external refining capacity exposes precision motor-actuator margins to raw material price volatility and export restriction risk.
- SASO Certification Timeline Compression:Accelerated technical regulation update cycles are extending product validation periods by four to six months for electro-hydraulic brake actuators targeting regional climate extremes.
- Electromechanical Substitution of Pneumatics:Compressed air actuator systems in heavy commercial vehicle seating and door mechanisms face displacement by compact electric linear actuators with integrated position feedback.
Strategic Opportunities
- Eastern Province Industrial Zones:Jubail and Dammam manufacturing corridors offer greenfield sites for actuator assembly localization under Vision 2030 domestic content incentives.
- ADAS Integration White Space:Servo actuator architectures for lane-keeping torque overlay and automated parking systems remain underpenetrated in domestic mid-vehicle platforms.
- Saudi Energy Efficiency Center Benchmarks:Fuel-consumption mandates are creating procurement preference for lightweight aluminum-housing actuators with low-friction ball-screw mechanisms in HVAC flap control applications.
Industry Challenges
- Mechatronics Engineering Talent Scarcity:Domestic universities produce insufficient graduates with combined mechanical design and embedded control firmware competencies required for smart actuator development.
- Legacy 12V System Integration:Electromechanical actuators designed for 48V architectures must maintain backward compatibility with residual 12V electrical distribution in transitional vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Automotive Actuators Market |
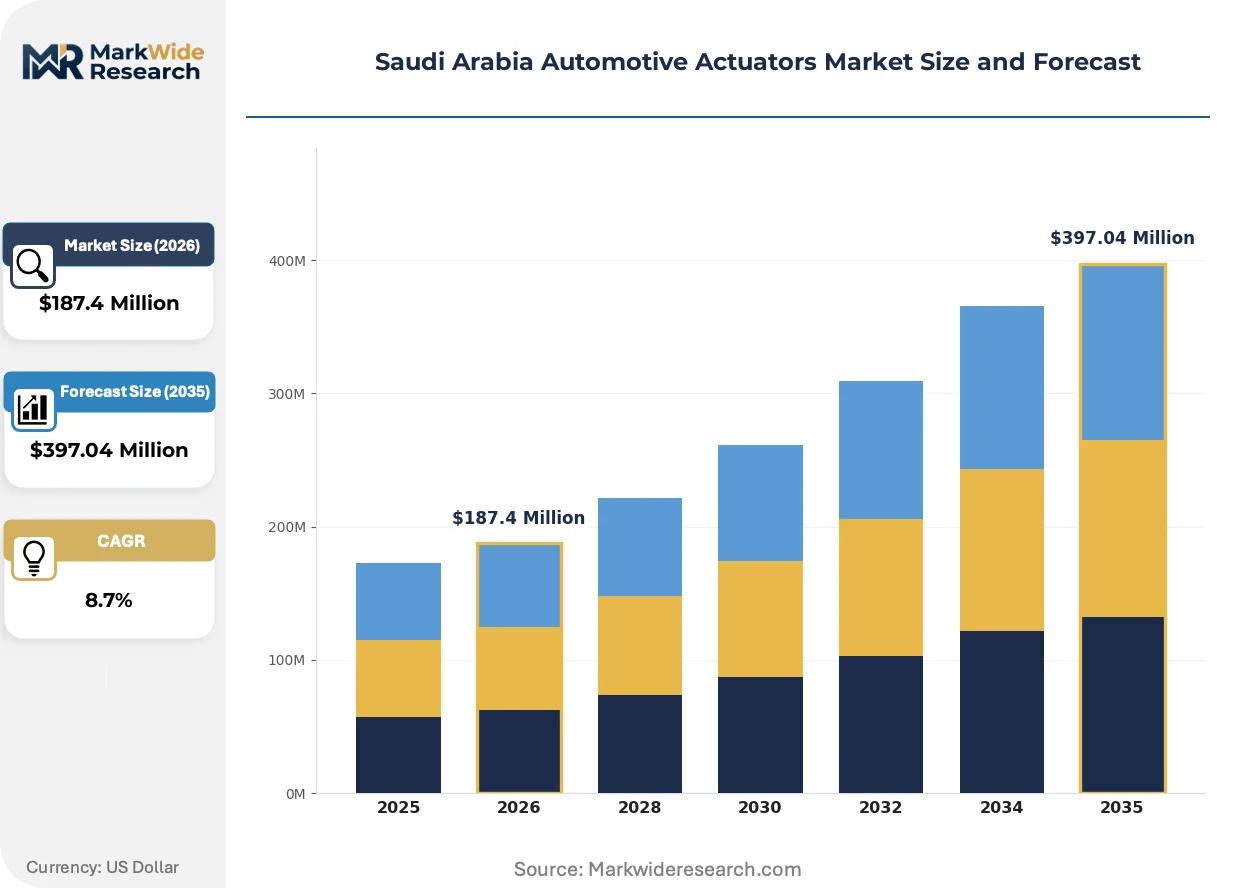
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Pneumatic Actuators, Hydraulic Actuators End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Electric Actuators, Mechanical Actuators, Electro-Hydraulic Actuators, Servo Actuators Application: Power Steering, Brake Systems, Suspension Systems, Climate Control |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, ZF Friedrichshafen AG, Nidec Corporation, Mitsubishi Electric Corp., Aisin Corporation, Hitachi Astemo, Ltd., Johnson Electric Holdings Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Automotive Actuators Market Evolving Landscape
Actuator architecture across Saudi Arabia's vehicle assembly sector is pivoting toward integrated position-sensing and predictive maintenance capability. This shift is compressing the traditional separation between mechanical motion control and vehicle network intelligence.
Brushless DC motor-actuator assemblies with integrated Hall-effect position encoding are rendering obsolete traditional brushed motor designs in throttle body and HVAC applications. Domestic OEMs are adopting these sealed, maintenance-free units for their 100,000-kilometer service life ratings. The technology is rendering obsolete aftermarket actuator replacement revenue streams while shifting supplier value capture toward firmware-locked original equipment.
SASO technical regulations governing electromagnetic interference emissions for safety-critical actuators tightened test severity levels for brake and steering subsystems. Industrial consequence includes mandatory shielded cable architectures and ferrite core integration that add material cost but eliminate field failure liability. Electro-hydraulic brake actuator suppliers targeting regional climate extremes are responding with expanded thermal cycling validation protocols.
Fleet procurement departments at Saudi ride-hailing and last-mile delivery operators are consolidating actuator sourcing through long-term frame agreements with tier-one suppliers. Direct OEM-tier relationships are displacing traditional aftermarket distribution for high-volume wear components in door latch and seat adjustment modules. This concentration is most visible in Riyadh-based fleet management operations where total cost of ownership modeling favors predictive replacement scheduling over failure-driven maintenance.
Saudi Arabia Automotive Actuators Market Segmentation
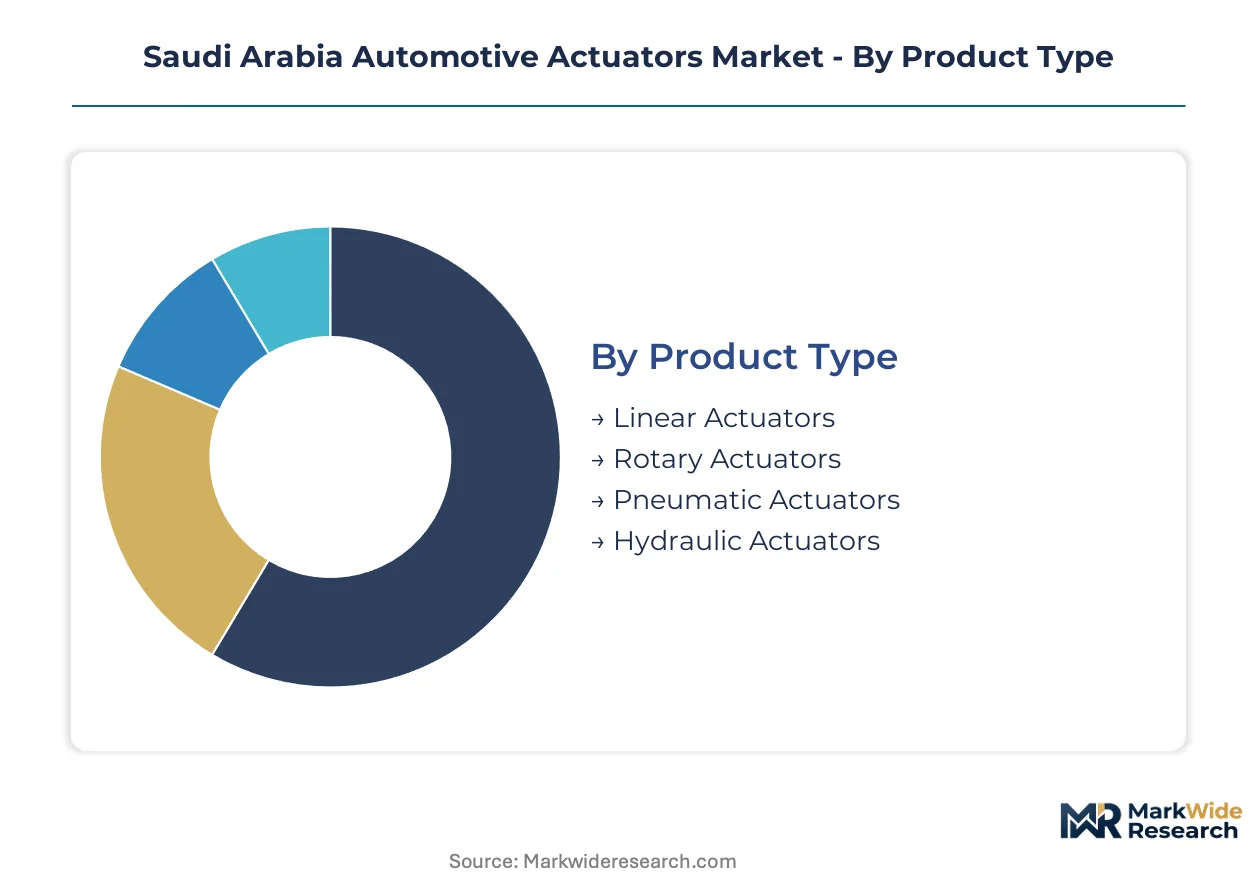
Actuator segmentation in Saudi Arabia reflects divergent technology maturities across vehicle subsystems. Product architecture choices determine supplier qualification pathways under SASO electromagnetic compatibility mandates. End-user concentration along the Riyadh-Jeddah corridor shapes procurement patterns for each segment cluster.
Product Type:
Cost tier differentiation separates precision electromechanical assemblies from legacy fluid-power alternatives in domestic sourcing decisions.
- Linear Actuators:Ball-screw and lead-screw mechanisms convert rotary motor input into precise linear displacement for seat adjustment and power steering columns. Demand concentrates in Riyadh-based OEM assembly plants where SASO functional safety certification for steer-by-wire systems mandates sealed, maintenance-free units with integrated position feedback.
- Rotary Actuators:Brushless DC motor assemblies with Hall-effect encoding deliver angular precision for throttle body and HVAC flap control applications. Jeddah-tier supplier clusters source these for thermal management modules where 48V mild-hybrid architectures expand torque requirements.
- Pneumatic Actuators:Compressed air cylinders serve heavy commercial vehicle door and seating mechanisms. Cost pressure from electric alternatives is compressing addressable volume in new platform designs.
- Hydraulic Actuators:High-force fluid-power units persist in brake and suspension applications requiring rapid response under thermal stress. Climate-specific validation protocols extend product development timelines.
Linear actuators command the established base. The steepest expansion runs through rotary actuator architectures for powertrain electrification.
End User:
Application focus varies sharply across the value chain, with specification authority residing at different tiers.
- OEMs:Domestic vehicle assemblers in the Kingdom hold final specification authority for safety-critical brake and steering actuators. Their procurement teams enforce SASO electromagnetic compatibility thresholds and 48V architecture compatibility requirements across supplier base.
- Aftermarket Providers:Independent distributors and service networks handle replacement demand for wear components in door latch and seat adjustment modules. Fleet operators in Riyadh are consolidating sourcing through direct tier-one frame agreements, compressing traditional aftermarket channels.
- Tier-1 Suppliers:Integrated mechatronics specialists manage subsystem certification and just-in-time delivery to assembly plants. Their engineering teams bridge OEM specification and component manufacturer capability.
- Vehicle Assemblers:Contract manufacturers for regional brands execute platform integration under licensor technical oversight. Their sourcing decisions track domestic content requirements under Vision 2030 industrial policy.
OEMs command the established base. The steepest expansion runs through tier-1 supplier consolidation as integrated mechatronics certification barriers rise.
Technology:
Maturity gradients separate established electric architectures from emerging servo integrations in advanced driver-assistance applications.
- Electric Actuators:Brushless DC motor assemblies with integrated controllers displace mechanical linkages across powertrain and chassis domains. SFDA safety standards for brake-by-wire and steer-by-wire systems mandate precision motor-actuator assemblies from certified suppliers.
- Mechanical Actuators:Cable and linkage systems persist in economy vehicle platforms where cost minimization overrides electrification benefits. Volume is contracting as OEMs phase out purely mechanical alternatives.
- Electro-Hydraulic Actuators:Hybrid architectures combine electric motor control with hydraulic force multiplication for brake systems. Continental AG specializes in units designed for regional climate extremes with expanded thermal cycling validation.
- Servo Actuators:Closed-loop position control systems enable lane-keeping torque overlay and automated parking functions. Underpenetration in domestic mid-vehicle platforms creates white space for technology suppliers.
Electric actuators command the established base. Servo architectures are gaining share fastest in ADAS integration segments.
Application:
Volume concentration and margin structure diverge across vehicle subsystems based on safety classification and replacement frequency.
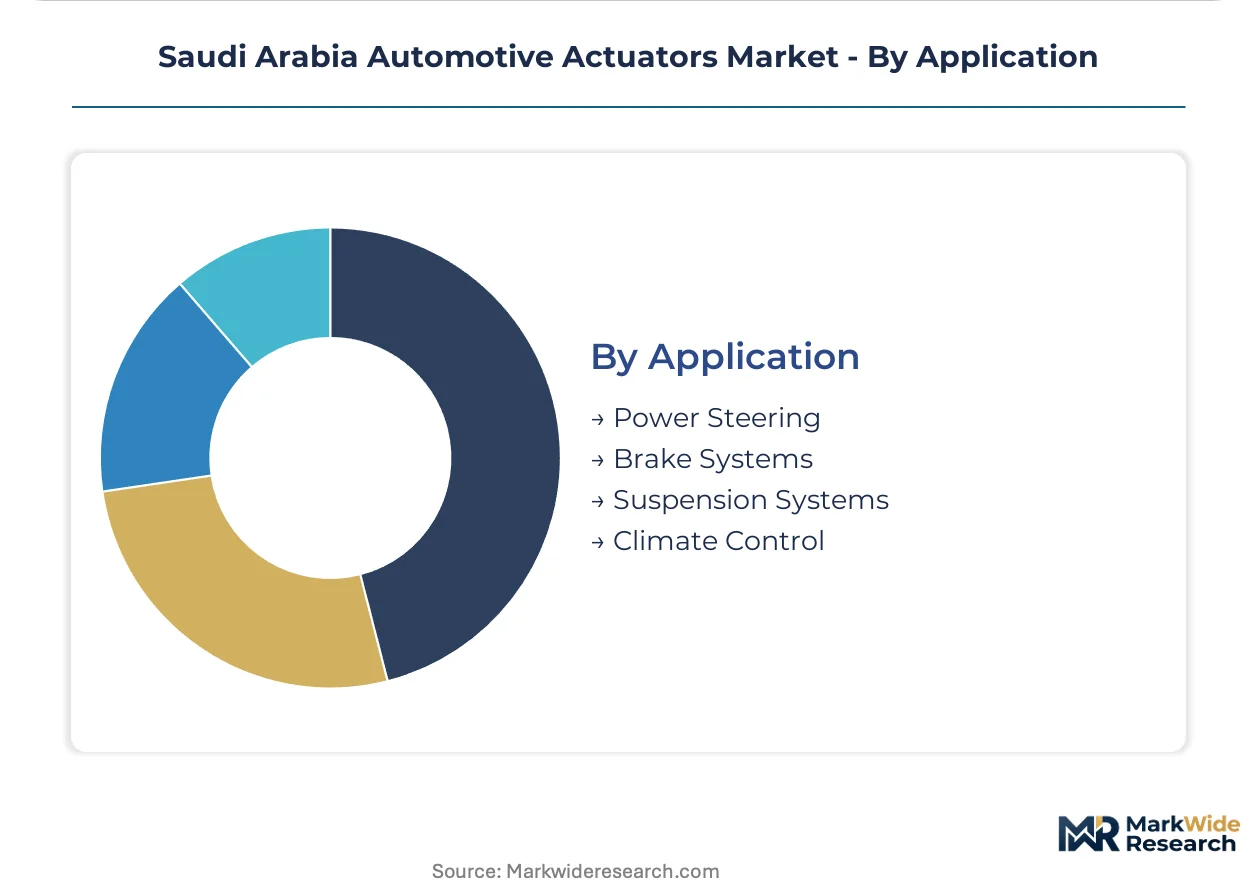
- Power Steering:Electric power steering actuators with torque sensors and brushless motors enable variable assist algorithms. Riyadh-Jeddah corridor OEMs specify these for fuel-economy compliance under Saudi Energy Efficiency Center benchmarks.
- Brake Systems:Electro-hydraulic and electromechanical brake actuators must satisfy SFDA electromagnetic compatibility mandates for safety-critical operation. SASO test severity levels for shielding and ferrite core integration add material cost.
- Suspension Systems:Active damping actuators adjust shock absorber valving in real-time for ride quality optimization. 48V mild-hybrid platform upgrades are expanding addressable market for high-torque electric units.
- Climate Control:HVAC flap actuators with low-friction ball-screw mechanisms reduce energy consumption. Procurement preference for lightweight aluminum-housing designs is tightening under fuel-consumption mandates.
Power steering commands the established base. The steepest expansion runs through brake system electrification as safety standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and domestic OEM procurement teams concentrate demand along three industrial corridors. Their specification authority shapes supplier qualification patterns and just-in-time delivery requirements.
Riyadh
Electric power steering actuator demand accelerates as domestic OEMs enforce fuel-economy compliance under Saudi Energy Efficiency Center benchmarks. SFDA electromagnetic compatibility mandates for brake-by-wire systems compress supplier certification timelines. The Riyadh-based OEM assembly plants anchor tier-one supplier ecosystems with integrated mechatronics capabilities.
Eastern Province
Jubail and Dammam manufacturing corridors attract greenfield actuator assembly investments under Vision 2030 domestic content incentives. The Saudi Energy Efficiency Center fuel-consumption mandates create procurement preference for lightweight aluminum-housing designs. Supplier clusters forming in Dammam industrial zones serve powertrain electrification programs.
Western Region
Jeddah-tier supplier networks source rotary actuator architectures for thermal management modules serving 48V mild-hybrid platforms. SASO technical regulations governing electromagnetic interference emissions tighten test severity levels for climate-specific validation. The Jeddah industrial corridor enables reduced logistics costs for HVAC flap control actuator delivery.
NEOM Northwest
Next-generation mobility testbeds in the northwest development zone specify servo actuator architectures for automated parking and lane-keeping integrations. Vision 2030 industrial policy incentives reshape localization timelines for electromechanical component manufacturing. NEOM procurement frameworks favor predictive maintenance-capable actuator systems with integrated position sensing.
Saudi Arabia Automotive Actuators Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated mechatronics specialists with SASO certification capabilities anchor relationships with domestic OEMs. Component manufacturers with rare earth magnet supply security occupy defensive positions. Regional distributors with fleet frame agreements consolidate aftermarket volume. Dominant competitive moves include backward integration into precision motor manufacturing and strategic partnerships for 48V architecture compatibility.
Within the integrated mechatronics tier, Robert Bosch GmbH, Denso Corporation, and Continental AG exemplify archetypes competing through differentiated technical positioning. Bosch leverages its German engineering heritage and broad automotive portfolio to anchor high-volume supply relationships. Denso represents Japanese precision manufacturing specialization in motor-actuator assemblies. Continental occupies a position defined by climate-adapted electro-hydraulic systems for regional thermal extremes.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Nidec Corporation |
| Mitsubishi Electric Corp. |
| Aisin Corporation |
| Hitachi Astemo, Ltd. |
| Johnson Electric Holdings Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity in precision motor-actuator assembly lines across East Asian manufacturing hubs compresses supplier pricing power while forcing Saudi tier-one procurement teams toward long-term offtake contracts with indexed rare-earth adjustments. This utilization dynamic tightens margins for brushed-motor legacy producers while rewarding certified mechatronics specialists with SASO electromagnetic compatibility credentials.
Pricing Analysis
Cost-plus contracts with neodymium and dysprosium indexation dominate procurement frameworks between domestic OEMs and precision motor suppliers. Price differentiation hinges on SASO certification tier and volume scale, with safety-critical brake-actuator assemblies commanding substantial premiums over HVAC flap-control units. Cost compression in pneumatic-to-electric substitution segments intensifies as fleet operators consolidate frame agreements. Aftermarket distributors exhibit highest price sensitivity, whereas OEM platform engineering teams prioritize certification compliance over unit cost.
Supply Chain Analysis
Export-control regimes restricting rare-earth refining technology transfers limit neodymium magnet flows from Chinese state-owned enterprises to Saudi assembly operations. Geographic concentration centers on China for magnet raw material, Japan for precision motor manufacturing, and Germany for electro-hydraulic system design. Supply chain risk rests on single-source vulnerability for dysprosium-heavy high-torque actuators. Distribution runs through Riyadh-Jeddah corridor tier-one clusters with just-in-time delivery to domestic OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's automotive actuator market fragments across certification tiers, creating niche opportunities as 48V mild-hybrid platform upgrades multiply specification variants beyond incumbent capacity.
For Market Incumbents: Build certification moats around integrated mechatronics capabilities for SFDA brake-by-wire mandates. Deepen backward integration into rare-earth magnet supply through offtake agreements with Australian and Vietnamese refining capacity. Anchor high-volume relationships with Riyadh-based OEMs before tier-two suppliers achieve SASO electromagnetic compatibility qualification. For New Entrants and Emerging Players: Build out servo actuator architectures for lane-keeping torque overlay in domestic mid-vehicle platforms where penetration remains minimal. Target Eastern Province industrial zones under Vision 2030 domestic content incentives for greenfield assembly localization. Pursue direct fleet frame agreements with Riyadh ride-hailing operators as the primary go-to-market channel, bypassing traditional aftermarket distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electro-hydraulic brake actuator segments as climate-specific validation protocols extend development timelines. Long-term viability favors integrated mechatronics specialists with captive rare-earth supply and SASO certification capabilities. Monitor tier-two supplier qualification success rates as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive dysprosium sourcing insulates margins from Chinese export restriction volatility under SFDA procurement mandates. |
| SASO Electromagnetic Compatibility Certification Investment | Certified suppliers anchor exclusive relationships with domestic OEMs for safety-critical brake and steering actuators. |
| Eastern Province Manufacturing Footprint Expansion | Jubail and Dammam greenfield sites qualify for Vision 2030 domestic content incentives and reduce logistics costs. |
| 48V Architecture Compatibility Development | High-torque electric actuator designs capture thermal management and active suspension module demand from mild-hybrid platforms. |
| Fleet Frame Agreement Consolidation | Direct tier-one relationships with Riyadh ride-hailing operators displace aftermarket channels for high-volume wear components. |
Research Methodology
Cross-validation between OEM platform engineering interviews and tier-one supplier procurement disclosures anchors the qualitative findings in this analysis. Primary fieldwork encompassed discussions with actuator subsystem engineers, SASO certification specialists, fleet procurement directors at Riyadh-based operators, and rare-earth supply chain managers. Secondary sources included Saudi Energy Efficiency Center fuel-consumption benchmark filings, SASO technical regulation updates, IHS Markit vehicle production databases for the Kingdom, and customs records tracking neodymium magnet import flows. Bottom-up segment sizing triangulated against top-down OEM platform content-per-vehicle estimates.
Calibration against historical adoption curves for 48V mild-hybrid architectures in comparable Middle Eastern markets refined the projection framework. Segmentation dimensions modeled encompass product type, application subsystem, technology maturity, and end-user procurement authority across the analysis window. CAGRs derived from logistic diffusion curves fitted to electrification penetration patterns, with explicit incorporation of SFDA regulatory mandate timelines and Vision 2030 localization incentive phase-ins. Industry-specific inputs included rare-earth price volatility indices and OEM platform engineering headcount allocations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-owned magnet producers or accelerated SFDA timeline compression would shift outcomes. Material shifts in Saudi rare-earth refining partnership structures or SASO electromagnetic compatibility test severity revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Auto Fender Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Automotive Commutator Market
Automotive Components
Automotive Filters Market