
 Egypt Automotive Lubricants Market | 2026-2036
Egypt Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Automotive Lubricants Market Foresight
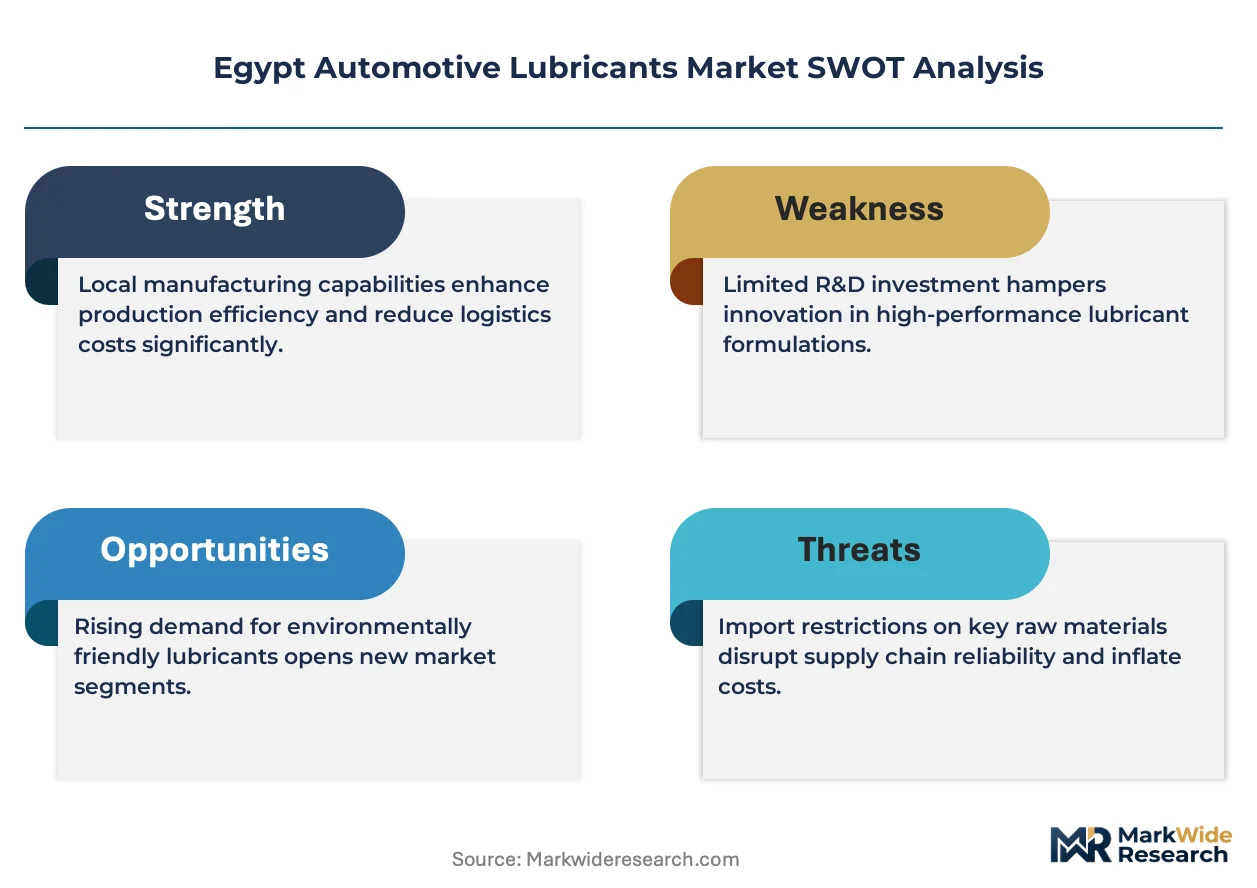
Asset-light leasing and pay-per-use lubricant service models is fragmenting competitive access across Egypt's aftermarket, allowing smaller distributors to challenge legacy supply chains without heavy balance-sheet commitments. Shell plc leverages its integrated refining and blending presence in the Suez Canal Economic Zone to secure feedstock cost advantages. TotalEnergies anchors its position through an extensive service-station network that doubles as a controlled retail channel. Misr Petroleum competes on state-backed procurement relationships with public transit and government fleet operators.
Egypt automotive lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and transmission systems, with viscosity grades typically ranging from SAE 0W-20 to SAE 15W-40 for passenger applications. Their primary commercial purpose is to extend engine operational life and maintain manufacturer warranty compliance under high-temperature, dusty operating conditions prevalent across North African climates. Engine oil dominates volume throughput due to universal replacement cycles across all vehicle classes, while transmission fluid commands margin premiums tied to specialized synthetic formulations. Heavy-duty trucks generate disproportionate demand intensity per unit, creating concentrated revenue pools in the commercial end-user segment despite smaller fleet counts.
Egypt's Ministry of Environment enforces emission and waste-oil handling protocols that elevate compliance costs for informal blenders and channel volume toward certified producers. The Egyptian General Petroleum Corporation coordinates with the Ministry of Trade and Industry on import licensing for base oil feedstocks, shaping domestic supply security and pricing dynamics. Stakeholders must monitor how Cairo's industrial zone expansion and Red Sea port modernization alter distribution economics and regional blending capacity placement.
Market Dynamics
Egypt's enforcement of Euro 5 emission-equivalent standards through the Ministry of Environment is compressing formulation windows for legacy mineral oils while elevating synthetic blend specifications across the aftermarket.
Growth Catalysts
- Fleet operator expansion:Commercial logistics fleets in Greater Cairo and Alexandria are extending vehicle utilization cycles, shortening drain intervals and amplifying lubricant throughput per unit.
- Base oil import licensing coordination:The Egyptian General Petroleum Corporation's alignment with the Ministry of Trade and Industry on feedstock import protocols is stabilizing domestic supply security for certified blenders.
- Waste-oil handling mandates:Ministry of Environment protocols on used lubricant collection and re-refining are channeling volume away from informal collectors toward registered processors with compliant infrastructure.
Market Restraints
- Base oil price volatility:Feedstock costs fluctuate with Suez Canal transit volumes and Red Sea shipping disruptions, squeezing margin predictability for independent blenders without captive supply.
- Informal sector persistence:Uncertified mixers in Delta governorates and Upper Egypt continue capturing price-sensitive demand through unregulated channels, fragmenting volume capture for compliant producers.
- Synthetic additive import dependency:Performance additive packages for API SP and ACEA C-grade formulations rely on foreign suppliers, exposing formulators to currency risk and lead-time variability.
Strategic Opportunities
- Pay-per-use service models:Asset-light leasing arrangements for bulk lubricant supply and used-oil retrieval are opening aftermarket access for distributors without heavy balance-sheet commitments.
- Red Sea port modernization:Sokhna and Safaga terminal expansions are shortening inland distribution legs for imported base stocks, altering optimal blending capacity placement toward coastal zones.
- Public fleet electrification pilots:Cairo's municipal bus electrification roadmap is creating demand for thermal management fluids and e-axle lubricants distinct from conventional engine oils.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-SAPS (sulfated ash, phosphorus, sulfur) additive chemistry for emission-compliant grades remains concentrated among multinational technical centers.
- Certification timeline compression:API and ACEA license acquisition for new viscosity grades requires extended testing protocols that lag behind regulatory implementation deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Automotive Lubricants Market |
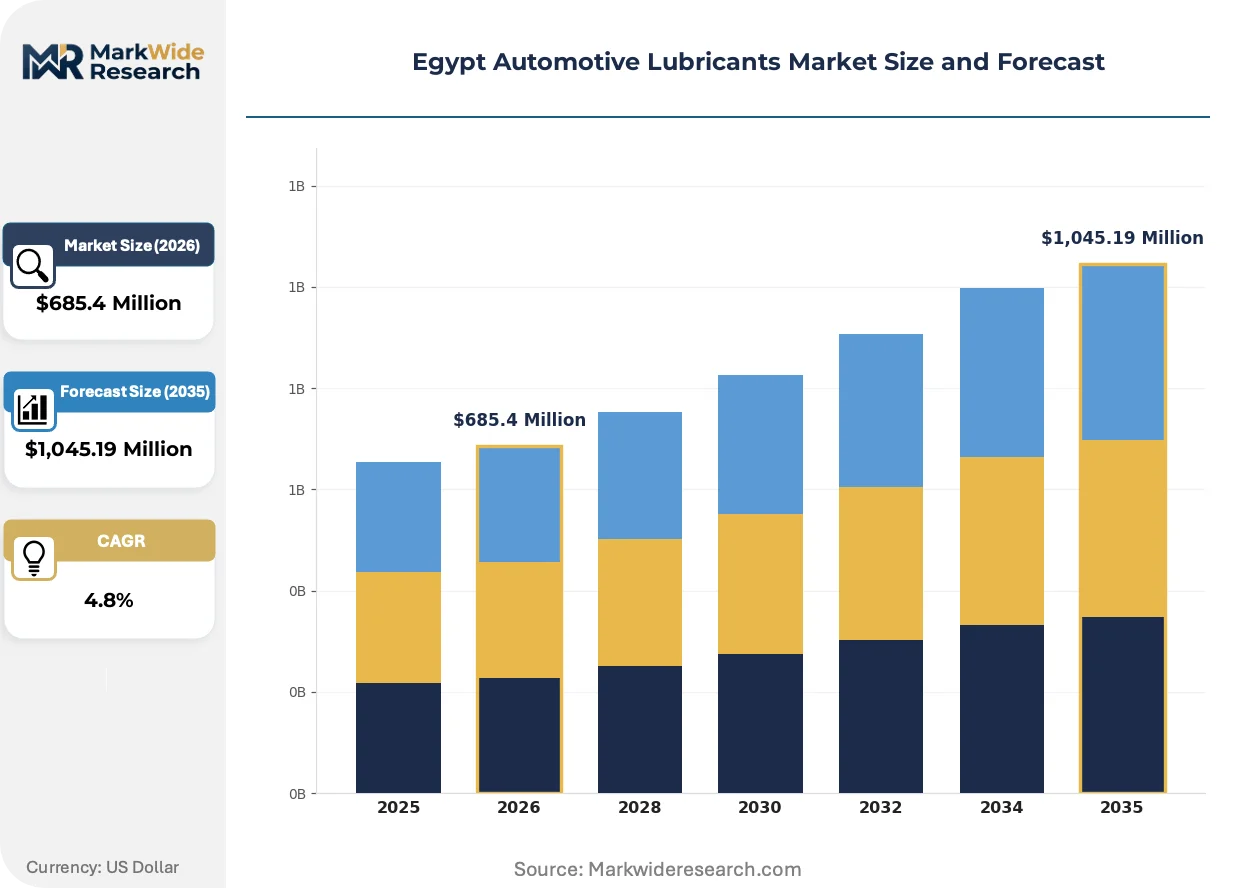
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
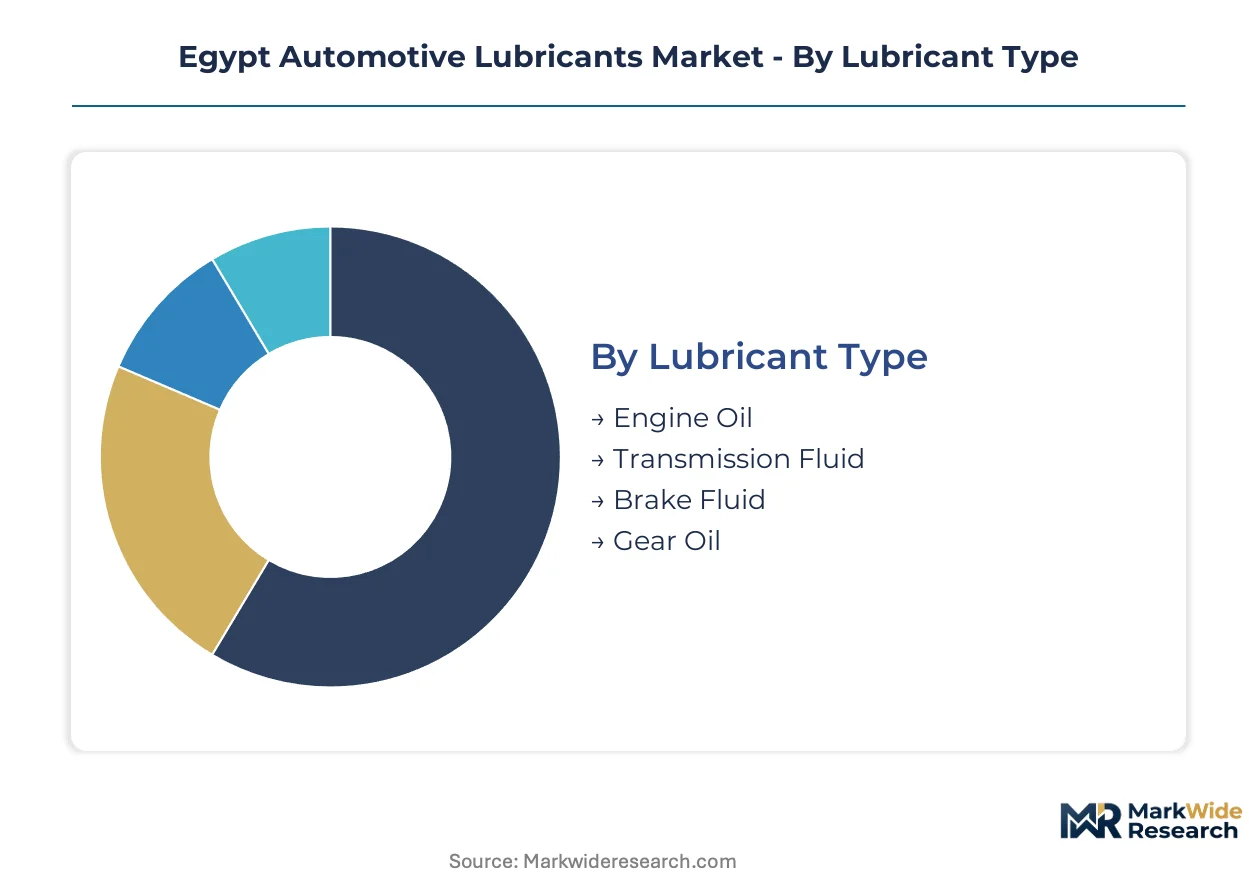
| Segmentation | Lubricant Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Distribution Channel: Retail Outlets, Online Sales, Service Stations, Wholesalers Application: Automotive Maintenance, Performance Enhancement, Fuel Efficiency Improvement, Engine Protection |
| Companies Covered | Shell plc, TotalEnergies, ExxonMobil Corporation, BP plc, Misr Petroleum, Chevron Corporation, FUCHS, Arabian Oil Company, Petromin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Automotive Lubricants Market Shifts & Advancements
Synthetic and re-refined base oil technologies are restructuring Egypt's lubricant value chain, compressing the viable shelf life of conventional mineral formulations while opening new service-model possibilities for agile distributors.
Group III+ and PAO (polyalphaolefin) synthetic base stocks are penetrating passenger car motor oil formulations as OEM fill specifications tighten. Fleet operators in Alexandria's container transport corridor are adopting extended-drain synthetics to minimize downtime. Mineral-based 15W-40 grades for older vehicle parcs is rendering obsolete for warranty-compliant service bays.
Egypt's Ministry of Environment is tightening enforcement of waste-oil handling protocols that mandate licensed collection and re-refining. Compliance costs for informal blenders are rising while certified processors gain volume access. Public transit and government fleet tenders now require documented chain-of-custody for used lubricant disposal, shifting procurement criteria beyond unit price.
Service-station networks are unbundling lubricant sales from mechanical labor, creating standalone fluid retail formats. Quick-lube bays in Greater Cairo shopping complexes are capturing time-sensitive consumers through 15-minute drain-and-fill operations. Fleet maintenance managers in the 10th of Ramadan industrial zone are consolidating supplier relationships around integrated fluid-plus-filtration contracts with telemetry-linked reorder systems.
Egypt Automotive Lubricants Market Segmentation
Egypt's automotive lubricants market fragments along lubricant chemistry, vehicle duty cycles, and channel access economics. Segment-level profitability varies sharply with formulation complexity and replacement frequency across Greater Cairo's dense service infrastructure.
Lubricant Type:
Replacement intervals stretch from 5,000 kilometers for mineral engine oils to 100,000 kilometers for sealed transmission systems, creating divergent inventory velocity profiles across distributor networks.
- Engine Oil:Formulated from Group I-III base stocks with detergent-dispersant additive packages, this category commands universal fitment across all combustion architectures. Demand concentrates in Greater Cairo's independent workshop corridors where drain-and-fill services turn inventory weekly. Fleet operators in Alexandria's logistics hub are compressing service intervals amid rising vehicle utilization rates.
- Transmission Fluid:Synthetic ATF and CVT formulations incorporate friction modifiers and shear-stable viscosity index improvers for precision clutch engagement. Specialized service bays in 10th of Ramadan industrial zone capture margin premiums on dual-clutch and CVT servicing. OEM warranty compliance mandates are channeling volume away from generic mineral substitutes.
- Brake Fluid:Glycol-ether and silicone-based formulations with elevated dry/wet boiling point specifications serve hydraulic actuation systems. Uptake clusters in government fleet maintenance depots with documented safety audit protocols.
- Gear Oil:Extreme-pressure additive packages protect hypoid gear sets in differential and manual transmission applications. Heavy-duty mining and construction equipment in Eastern Desert operations drives specification toward SAE 80W-90 and 85W-140 grades.
Engine oil dominates installed base throughput. Transmission fluid is where margin expansion concentrates.
End User:
Cost-to-serve economics stratify sharply between fragmented retail consumers and consolidated fleet procurement desks with telemetry-linked reorder systems.
- Passenger Cars:Individual owners in Cairo and Alexandria governorates prioritize price accessibility over specification compliance, sustaining demand for mineral 15W-40 grades. Quick-lube formats in shopping mall precincts capture time-sensitive service occasions.
- Commercial Vehicles:Light-duty vans and minibuses operating intercity routes generate steady demand for semi-synthetic 10W-40 formulations. Service networks along the Cairo-Alexandria agricultural corridor maintain dedicated bulk storage for high-frequency customers.
- Two-Wheelers:Motorcycle and scooter parcs in Delta governorates rely on small-pack mineral oils distributed through informal retail channels. Price elasticity sustains unbranded mixer penetration despite quality variability.
- Heavy-Duty Trucks:Euro 5-equivalent emission compliance is forcing adoption of low-SAPS CJ-4 and CK-4 diesel engine oils with extended drain intervals. Fleet operators in Sokhna port logistics are consolidating supplier relationships around integrated fluid-plus-filtration contracts.
Passenger cars anchor volume scale. Heavy-duty trucks concentrate value capture per unit.
Distribution Channel:
Channel control determines formulation authenticity assurance and used-oil retrieval compliance in a market with persistent informal sector activity.
- Retail Outlets:Independent auto parts shops in Ataba and Mosky districts stock 1-liter and 4-liter packs for walk-in DIY consumers. Inventory turns accelerate during Ramadan and pre-holiday maintenance seasons.
- Online Sales:E-commerce platforms are penetrating Cairo's upper-income districts with delivered-to-door lubricant packs. Verification challenges sustain preference for established brand storefronts over marketplace aggregators.
- Service Stations:Integrated fuel-and-fluid retail formats leverage captive vehicle traffic for high-margin synthetic upsells. Misr Petroleum and TotalEnergies networks dominate this channel with controlled product placement.
- Wholesalers:Bulk distributors serving Upper Egypt and Sinai governorates aggregate demand across dispersed workshop networks. Credit terms and delivery reliability determine supplier loyalty in cash-constrained markets.
Service stations control premium positioning. Wholesalers extend geographic reach into underpenetrated governorates.
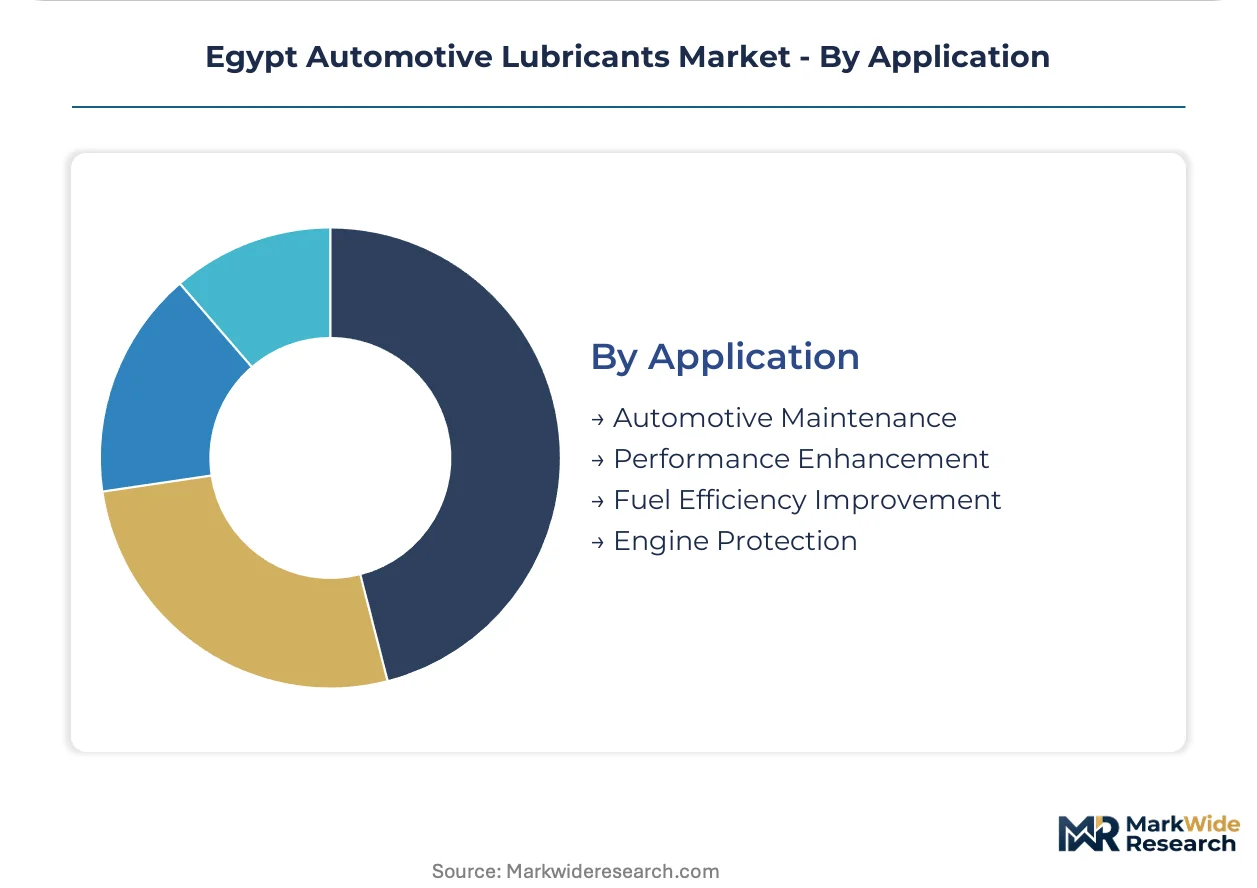
Application:
Functional value propositions align lubricant selection with owner priorities ranging from warranty preservation to operating cost minimization.
- Automotive Maintenance:Scheduled drain intervals prescribed by OEM service manuals drive baseline replacement demand. Compliance documentation requirements in government fleet tenders elevate certified product preference.
- Performance Enhancement:Racing and modified vehicle enthusiasts in Cairo's automotive clubs seek high-viscosity synthetic formulations for thermal stability under extreme load. Volume remains niche but commands 3-4x per-liter premiums.
- Fuel Efficiency Improvement:Low-viscosity 0W-20 and 5W-30 grades targeting CAFE-equivalent consumption standards are penetrating hybrid and downsized turbocharged vehicle parcs. New vehicle sales trends in Alexandria's affluent suburbs support gradual uptake.
- Engine Protection:Wear-prevention and deposit-control claims dominate marketing communications for aging vehicle parcs in Delta agricultural zones. Detergent package differentiation sustains brand switching incentives.
Automotive maintenance anchors replacement demand. Fuel efficiency improvement is gaining share fastest among specification-conscious owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo commands premium pricing power through dense service infrastructure, while Upper Egypt governorates trade at discount spreads due to logistics friction and informal sector penetration.
Greater Cairo
Fleet operators in the 10th of Ramadan industrial zone are compressing drain intervals amid rising vehicle utilization rates. The Ministry of Environment enforces Euro 5 emission-equivalent standards that elevate synthetic blend specifications. Quick-lube formats in shopping mall precincts capture time-sensitive consumers through 15-minute service operations.
Alexandria
Container transport corridors generate concentrated demand for extended-drain synthetics that minimize equipment downtime. Waste-oil handling protocols mandate licensed collection and re-refining for government fleet tenders. Sokhna port logistics operations are consolidating supplier relationships around integrated fluid-plus-filtration contracts.
Delta Governorates
Agricultural vehicle parcs sustain demand for mineral 15W-40 grades through price-sensitive owner preferences. Uncertified mixers continue capturing volume through unregulated retail channels despite quality variability. Informal distribution networks in Mansoura and Tanta cluster around traditional auto parts markets.
Upper Egypt
Dispersed workshop networks in Assiut and Sohag rely on bulk wholesalers with extended credit terms and unreliable delivery schedules. Base oil price volatility squeezes margin predictability for independent blenders without captive supply arrangements. Cash-constrained markets sustain demand for small-pack mineral oils distributed through informal retail channels.
Suez Canal Economic Zone
Integrated refining and blending presence secures feedstock cost advantages for certified producers serving export and domestic markets. Red Sea port modernization at Sokhna and Safaga shortens inland distribution legs for imported base stocks. Coastal blending capacity placement is shifting toward these terminal zones to optimize logistics economics.
Egypt Automotive Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and additive packages. The market structure consolidates around multinational oil majors with captive supply chains, mid-scale regional blenders, and state-backed distributors serving public fleet procurement. Three archetypes dominate: integrated majors with refining presence, national oil companies leveraging government relationships, and agile independents exploiting service-model innovation. Competitive moves concentrate on pay-per-use leasing arrangements and coastal blending capacity expansion.
Among integrated majors, Shell plc anchors the premium synthetic tier through its Suez Canal Economic Zone refining footprint. TotalEnergies occupies a position in controlled retail through extensive service-station networks. Misr Petroleum exemplifies the state-backed archetype with procurement relationships anchoring public transit and government fleet segments.
| Leading Market Players |
|---|
| Shell plc |
| TotalEnergies |
| ExxonMobil Corporation |
| BP plc |
| Misr Petroleum |
| Chevron Corporation |
| FUCHS |
| Arabian Oil Company |
| Petromin Corporation |
| Others |
Supply & Pricing Matrix
Base oil import licensing through the Egyptian General Petroleum Corporation concentrates upstream procurement leverage among certified blenders with Ministry of Trade and Industry approvals. This feedstock gatekeeping funnels margin capture toward integrated majors operating in the Suez Canal Economic Zone while squeezing independent formulators exposed to Red Sea shipping volatility.
Pricing Analysis
Configured-to-order pricing for synthetic blend formulations commands spreads of 40-60 percent above standard mineral grades in Greater Cairo service bays. Three-tier pricing structure across premium, standard, and economy levels stratifies by API certification tier and drain-interval guarantees. Cost compression in the mineral tier is intensifying because informal Delta governorates mixers undercut registered processors on unbranded 15W-40 volumes. Fleet procurement desks with telemetry-linked reorder systems exhibit lowest price sensitivity; individual DIY consumers in Upper Egypt show highest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration sits with integrated refiners in the Suez Canal Economic Zone and coastal blending facilities at Alexandria. Geographic supply concentration spans the UAE, Saudi Arabia, and Singapore for Group II-III base stock imports. Raw material dependencies include polyalphaolefin synthetic feedstocks, detergent-dispersant additive packages, and viscosity index improvers. Single-source vulnerability runs through Suez Canal transit routes where Red Sea disruptions extend lead-time variability. Distribution runs through Misr Petroleum and TotalEnergies service-station networks for premium positioning, with bulk wholesalers extending reach into cash-constrained Upper Egypt governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's automotive lubricants market represents a service-attach opportunity where pay-per-use leasing and used-oil retrieval contracts expand faster than standalone product sales. Recurring-revenue layers around telemetry-linked inventory management and integrated fluid-plus-filtration contracts now outpace hardware volume growth in fleet segments.
For Market Incumbents: Pre-empt displacement by informal sector mixers through captive used-oil collection infrastructure that satisfies Ministry of Environment chain-of-custody mandates. Lock in Sokhna port logistics operators with extended-drain synthetic formulations before electrification pilots erode engine oil demand. Certification investment in API SP and ACEA C-grade licenses anchors warranty-compliant positioning against price-aggressive challengers. For New Entrants and Emerging Players: Build out asset-light pay-per-use service models targeting 10th of Ramadan industrial zone fleet maintenance managers with bulk supply-plus-retrieval contracts. The most penetrable white space sits in Upper Egypt governorates where dispersed workshop networks lack reliable wholesaler relationships. A go-to-market angle combining extended credit terms with documented waste-oil compliance addresses cash-constrained buyer priorities. For Investors and Strategic Acquirers: Capital is best deployed toward coastal blending specialists with Red Sea port access and established relationships with the Egyptian General Petroleum Corporation on feedstock licensing. Long-term viability hinges on positioning for thermal management fluid formulations as Cairo's municipal bus electrification roadmap matures. The signal to watch is Ministry of Environment enforcement intensity against informal Delta governorates collectors.| Strategic Initiative | Industry Significance |
|---|---|
| Coastal Blending Capacity Expansion | Red Sea port modernization at Sokhna shortens inland distribution legs for imported base stocks. |
| Used-Oil Retrieval Infrastructure Buildout | Licensed collection networks satisfy Ministry of Environment mandates and lock in fleet procurement criteria. |
| Synthetic Formulation Certification Investment | API SP and ACEA C-grade licenses anchor warranty-compliant positioning in Euro 5-equivalent compliance. |
| Pay-per-Use Service Model Launch | Asset-light leasing arrangements open aftermarket access without heavy balance-sheet commitments. |
| Integrated Fluid-Plus-Filtration Contracts | Telemetry-linked reorder systems consolidate supplier relationships with high-utilization fleet operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance managers, independent workshop owners, lubricant formulators, Ministry of Environment compliance officers, and Egyptian General Petroleum Corporation procurement leads. Secondary validation drew from customs and trade data on base oil imports, Ministry of Trade and Industry licensing records, Suez Canal Authority transit statistics, and API certification registries. Bottom-up volume estimates from distributor channel audits were triangulated against top-down macroeconomic indicators and vehicle parc projections.
Calibration against historical price elasticity and drain-interval compression patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include lubricant chemistry tier, vehicle duty cycle classification, distribution channel type, and regional governorates cluster. CAGRs were derived from trend extrapolation of synthetic penetration rates and fleet utilization intensity. Industry-specific forecast inputs incorporated Euro 5-equivalent regulatory implementation timelines and electrification pilot expansion scenarios.
Stress conditions across Suez Canal shipping disruptions, Egyptian pound volatility against base oil import costs, and informal sector enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory implementation pace and fleet operator consolidation trends. Quarterly review of Ministry of Environment inspection activity, Red Sea freight rate indices, and public transit tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Key Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Silencer Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Automotive Defroster Market
Automotive Components
Automotive Fender Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Brake Cooling Duct and Hose Market