
 Automotive Brackets Market | 2026-2036
Automotive Brackets Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brackets Market Outlook
The EU Green Deal is restructuring procurement priorities for chassis and powertrain brackets across European automotive value chains. Magna International Inc. leverages its stamping and aluminum forming expertise to supply structural brackets for battery electric vehicle platforms. Thyssenkrupp AG anchors its position through advanced high-strength steel processing capabilities serving German OEM architectures. Gestamp Automoción specializes in hot-stamped bracket solutions that reduce mass while maintaining crash performance thresholds.
Automotive brackets are load-bearing structural components fabricated from stamped steel, cast aluminum, or fiber-reinforced composites, designed to secure engines, transmissions, suspension assemblies, and battery packs to vehicle frames with specified torque tolerances and vibration resistance. Mounting brackets and support brackets dominate current volume given their ubiquity across internal combustion and electric powertrains, while adjustable brackets represent the fastest-growing category as modular platform designs proliferate. Aluminum brackets command premium positioning due to density advantages and recyclability credentials, whereas composite brackets remain niche but carry outsized margin potential in motorsport and luxury electric segments.
NHTSA crashworthiness standards, EPA fuel economy benchmarks, and ECE R94/R95 regulations collectively dictate bracket material thickness, joint geometry, and failure-mode requirements across major production regions. The EU AI Act and emerging battery passport traceability rules under CSRD will extend compliance obligations to bracket provenance and embodied carbon documentation. Stakeholders must monitor evolving platform standardization strategies at Ford, Volkswagen, and BYD to anticipate volume shifts between universal and vehicle-specific bracket specifications.
Market Dynamics
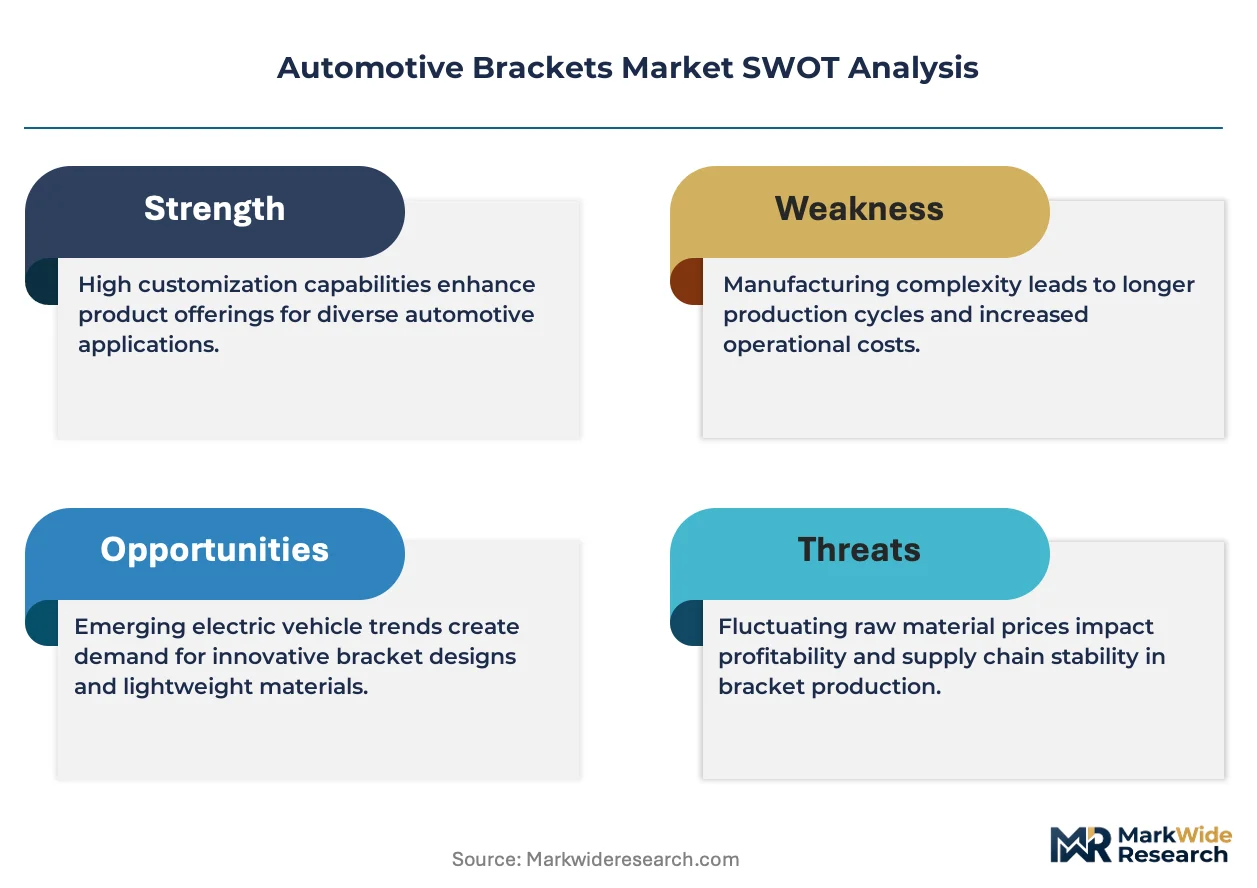
Platform electrification is compressing bracket specification cycles as OEMs migrate from stamped steel engine mounts to aluminum and composite battery enclosures, forcing suppliers to retool forming lines and recertify joint geometries within compressed vehicle development timelines.
Growth Catalysts
- EU Green Deal decarbonization mandates:Embodied carbon thresholds for automotive components are redirecting procurement toward recyclable aluminum brackets across German and French OEM supply chains.
- Battery electric vehicle platform proliferation:Dedicated BEV architectures require 40-60% more structural brackets per vehicle than internal combustion equivalents, concentrating demand among Tier-1 stamping specialists.
- Hot-stamping process maturation:Advanced high-strength steel forming techniques enable 25-30% mass reduction in crash-critical bracket applications without sacrificing ECE R94/R95 compliance.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations above historical bands compress margin structures for bracket suppliers locked into annual OEM pricing agreements.
- Carbon fiber precursor concentration:PAN-based composite bracket feedstocks depend on Japanese and US chemical suppliers, creating single-source exposure for motorsport and luxury EV programs.
- Welding qualification bottlenecks:ISO 3834 and EN 1090 certification requirements for structural aluminum joints extend new supplier onboarding timelines beyond typical platform development windows.
Strategic Opportunities
- CSRD battery passport traceability:Mandatory embodied carbon documentation for EV components creates service revenue streams for bracket suppliers with lifecycle assessment capabilities.
- Modular platform standardization:Volkswagen's MEB and Ford's GE1 architectures favor adjustable bracket designs that accommodate multiple battery pack configurations across vehicle segments.
- Closed-loop aluminum recycling:OEMs in Germany and Sweden are piloting take-back programs for end-of-life brackets, securing recycled content quotas under EU circular economy action plans.
Industry Challenges
- Multi-material joining expertise scarcity:Adhesive bonding and mechanical fastening of aluminum-to-composite bracket assemblies requires specialized process engineers in short supply across European stamping operations.
- Simultaneous engineering timeline compression:BEV platform development cycles now span 24-30 months versus 48-60 months for legacy architectures, collapsing bracket design-validation-production ramp sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brackets Market |
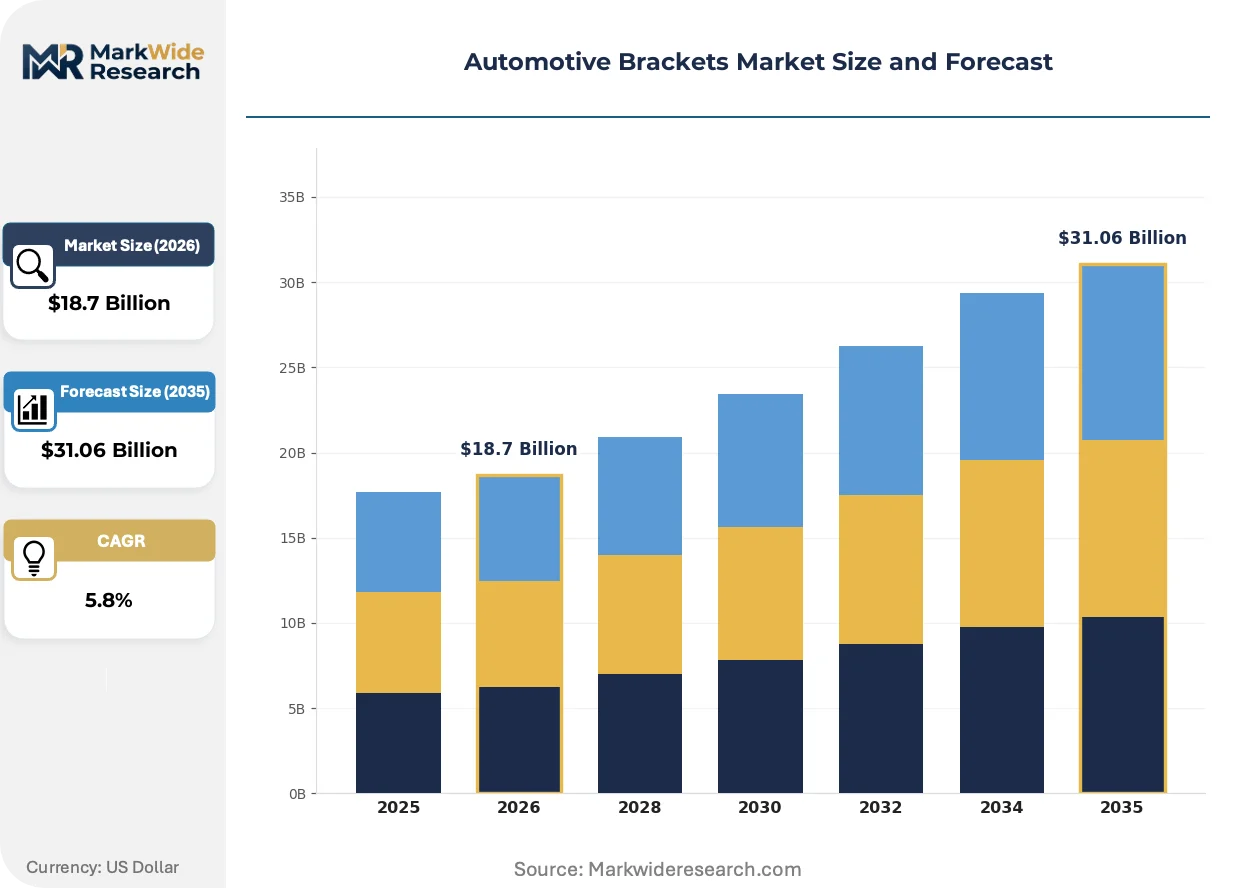
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mounting Brackets, Support Brackets, Stabilizer Brackets, Adjustable Brackets Material: Steel, Aluminum, Plastic, Composite End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Stamping, Casting, Machining, Injection Molding |
| Companies Covered | Aisin Seiki Co., Ltd., Tower International, Magna International Inc., Continental AG, Martinrea International, Denso Corporation, Gestamp Automoción, Thyssenkrupp AG, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brackets Market Strategic Shifts
Digital thread integration is collapsing the traditional separation between bracket design, forming simulation, and quality validation, compressing iteration cycles while embedding regulatory compliance checkpoints earlier in development workflows.
Carbon fiber-reinforced polymer brackets are expanding into structural battery pack applications previously reserved for aluminum extrusions. Premium EV manufacturers in Germany and California are qualifying pultruded composite designs for module support rails. This shift is expanding into secondary bracket categories as automated fiber placement reduces cycle times and scrap rates.
REACH substance restriction amendments are forcing reformulation of bracket surface treatments across European supply chains. Hexavalent chromium conversion coatings face phase-out timelines, compelling suppliers to qualify trivalent alternatives and plasma electrolytic oxidation processes. Stamping operations in Poland and the Czech Republic are absorbing the bulk of retooling costs to maintain ECE compliance.
Consolidated procurement desks at major OEMs are compressing supplier bases for commodity bracket categories. Volkswagen's Industrial Procurement division now mandates single-source accountability for platform-level bracket families, displacing fragmented multi-supplier arrangements. German and Chinese OEMs lead this concentration, with Tier-1 integrators capturing expanded scope through design-to-cost engineering commitments.
Automotive Brackets Market Segmentation
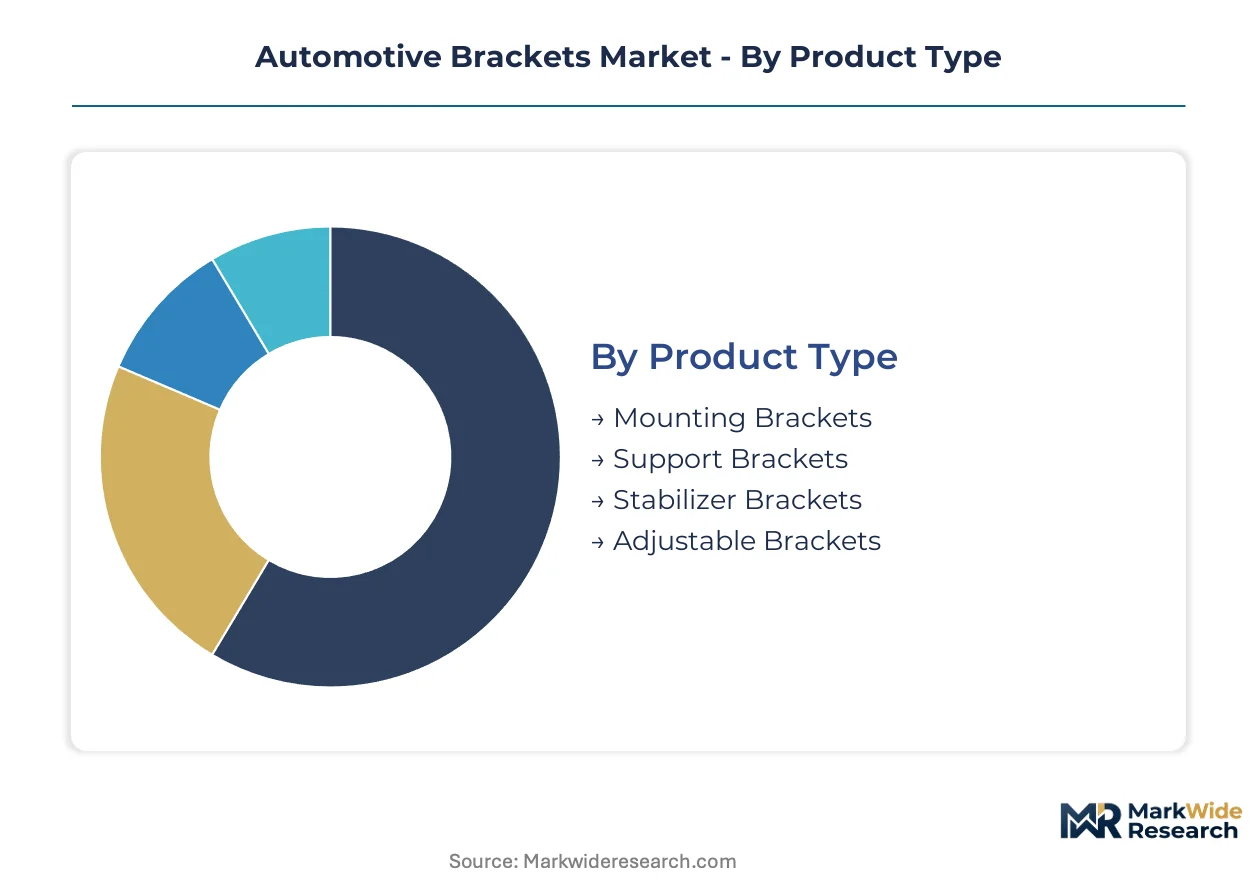
Bracket specification diversity demands granular segmentation tracking. Material selection and manufacturing process choices determine capital deployment patterns and margin structures across supplier tiers.
Product Type:
Mounting and support bracket categories require the heaviest upfront tooling investment given their volume scale and precision stamping requirements.
- Mounting Brackets:These components secure engines, transmissions, and battery packs to vehicle chassis with specified torque tolerances. German and Chinese OEMs concentrate procurement for BEV platforms where battery mounting complexity has multiplied bracket counts per vehicle.
- Support Brackets:Structural reinforcements that maintain alignment of suspension assemblies and crash management systems. Hot-stamped steel variants dominate in high-volume German production while aluminum extrusions gain share in California EV manufacturing.
- Stabilizer Brackets:Anti-roll bar attachments requiring fatigue-resistant joint geometries. Tier-1 suppliers in Michigan and Bavaria maintain dedicated production cells for these safety-critical components.
- Adjustable Brackets:Modular designs accommodating multiple battery pack configurations. Volkswagen's MEB and Ford's GE1 architectures favor these for platform flexibility.
Mounting brackets absorb the bulk of installed capacity; adjustable brackets are expanding most quickly.
Material:
Raw material cost tiers dictate supplier margin sensitivity and hedging strategies across the value chain.
- Steel:Advanced high-strength grades processed through hot-stamping enable 25-30% mass reduction in crash-critical applications. Thyssenkrupp AG anchors German supply for ECE R94/R95 compliant architectures.
- Aluminum:Density advantages and recyclability credentials command premium positioning. LME price volatility above historical bands compresses margins for suppliers locked into annual OEM agreements.
- Plastic:Injection-molded nylon and polypropylene variants serve non-structural routing and retention functions in interior and underhood applications.
- Composite:Carbon fiber-reinforced polymer brackets penetrate motorsport and luxury EV segments. PAN-based precursor dependence on Japanese chemical suppliers creates single-source exposure.
Steel retains dominant volume share; aluminum is gaining share fastest in electrified platforms.
End User:
Customer type determines design authority location and contract structure complexity.
- OEMs:Volkswagen, Ford, and BYD maintain direct bracket specification control for platform-defining components. Consolidated procurement desks now mandate single-source accountability for platform-level bracket families.
- Tier-1 Suppliers:Magna International and Gestamp Automoción capture expanded scope through design-to-cost engineering commitments. These integrators bridge OEM architectures with stamping specialists.
- Aftermarket Providers:Replacement bracket demand concentrates in collision repair channels. Catalog breadth requirements favor standardized geometries over vehicle-specific designs.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations source brackets through Tier-1 intermediaries rather than direct mill relationships.
Tier-1 suppliers intermediate the majority of production volume; OEM direct procurement is climbing the fastest as platform standardization advances.
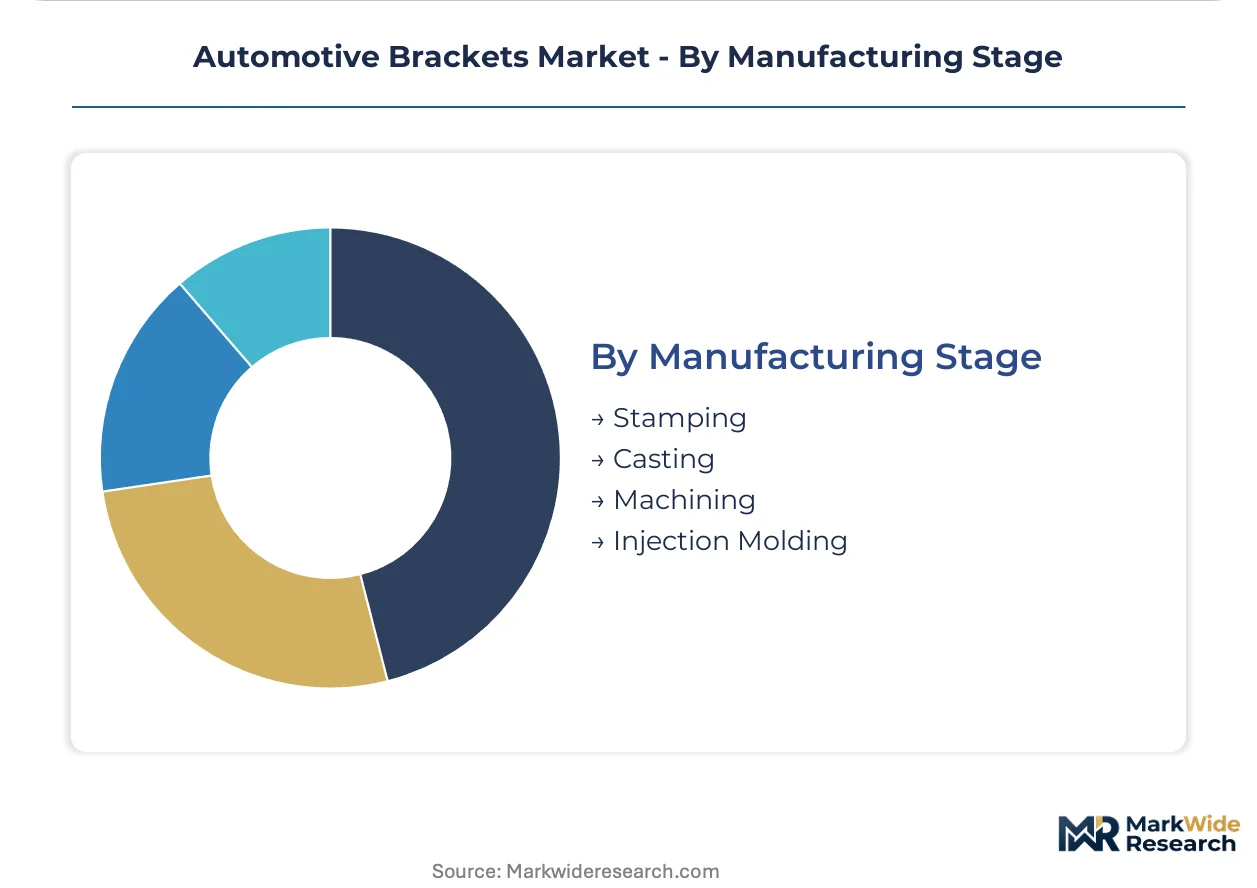
Manufacturing Stage:
Process selection locks in equipment amortization schedules and workforce skill requirements.
- Stamping:Progressive die and transfer press operations form the backbone of high-volume bracket production. Hot-stamping process maturation enables mass reduction without sacrificing crash performance.
- Casting:High-pressure aluminum die casting serves complex geometries in battery enclosure and motor mount applications. Tooling lead times extend 16-24 weeks for qualification.
- Machining:CNC operations finish critical surfaces and precision bores on cast or forged blanks. This stage adds cost but enables tight tolerance brackets for motorsport and luxury segments.
- Injection Molding:Thermoplastic processing for non-structural brackets favors low-cost regions with available resin supply chains.
Stamping commands the largest installed equipment base; casting is expanding most rapidly for BEV thermal management and battery structural components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the densest concentration of automotive bracket engineering, with German OEM procurement desks dictating material specifications across European supply chains.
Germany
Battery electric vehicle platform proliferation drives bracket demand at Volkswagen and BMW assembly plants. The EU Green Deal's embodied carbon thresholds redirect procurement toward recyclable aluminum architectures. Suppliers cluster along the Stuttgart-Munich corridor, where hot-stamping specialists retool for ECE R94/R95 compliant battery enclosures.
China
BYD and CATL expansion programs multiply structural bracket counts per vehicle under MIIT dual carbon mandates. GB standards for crashworthiness and battery safety dictate joint geometry specifications. Yangtze River Delta stamping operations absorb the bulk of capacity additions for domestic EV platforms.
United States
Ford's GE1 and GM's Ultium architectures concentrate procurement among Michigan-based Tier-1 integrators. NHTSA crashworthiness standards and EPA fuel economy benchmarks shape material thickness requirements. Detroit-area suppliers manage the transition from stamped steel engine mounts to aluminum battery structural components.
Japan
Toyota and Honda electrification roadmaps sustain demand for precision-formed brackets in hybrid powertrain applications. METI carbon neutrality targets accelerate aluminum adoption in chassis assemblies. Nagoya-area fabricators specialize in fatigue-resistant stabilizer brackets for export programs.
South Korea
Hyundai Motor Group's E-GMP platform standardization favors adjustable bracket designs across Ioniq and Genesis lineups. MFDS automotive safety regulations align with ECE frameworks for structural component qualification. Busan-Ulsan manufacturing complexes host dedicated production cells for battery pack support systems.
Automotive Brackets Market Competitive Environment
The competitive structure tilts toward Tier-1 integrators with design-to-cost engineering capabilities. Consolidated procurement desks at major OEMs compress supplier bases, displacing fragmented multi-source arrangements. Two archetypes dominate: full-service stamping specialists with hot-forming expertise, and diversified automotive suppliers leveraging modular platform relationships. Capacity expansion and strategic partnerships represent the primary competitive vectors as BEV platform cycles compress.
Among diversified automotive suppliers, Magna International Inc. and Continental AG occupy positions bridging OEM architectures with fabrication specialists. Tower International exemplifies the scale-driven stamping archetype. Thyssenkrupp AG anchors German supply for advanced high-strength steel processing. Gestamp Automoción sits within the hot-forming specialist tier serving crash-critical applications.
| Leading Market Players |
|---|
| Aisin Seiki Co., Ltd. |
| Tower International |
| Magna International Inc. |
| Continental AG |
| Martinrea International |
| Denso Corporation |
| Gestamp Automoción |
| Thyssenkrupp AG |
| Valeo SA |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement desks at major OEMs now mandate single-source accountability for platform-level bracket families, compressing supplier margins through design-to-cost engineering commitments and annual volume-based pricing agreements. This buyer concentration forces Tier-1 integrators to absorb raw material volatility while competing on total landed cost across aluminum and advanced high-strength steel grades.
Pricing Analysis
Value-based pricing anchored to crashworthiness performance and mass reduction outcomes dominates premium bracket tiers serving German and California EV platforms. Pricing stratifies across premium, standard, and economy tiers based on material certification grade and joint geometry complexity. Cost compression in commodity steel brackets is intensifying because OEMs are consolidating supplier bases for non-structural categories. Aftermarket collision repair channels exhibit the highest price sensitivity, while motorsport and luxury EV programs prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese chemical suppliers for PAN-based carbon fiber precursors used in motorsport and luxury EV bracket applications. Manufacturing concentration clusters in Germany, China, and the United States for high-volume stamping and aluminum forming operations. Raw material flows draw from LME-linked aluminum smelters, advanced high-strength steel mills, and specialized composite feedstock producers. Tariff exposure on Chinese aluminum extrusions threatens margin structures for battery enclosure brackets. Distribution runs through Tier-1 integrator hubs co-located with OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive brackets market sits in a technology-transition phase as hot-stamped aluminum and carbon fiber-reinforced polymer designs displace legacy stamped steel engine mounts under platform electrification mandates.
For Market Incumbents: Hedge against primary aluminum price volatility through backward integration into recycled content streams and closed-loop take-back programs with German OEMs. Secure ISO 3834 and EN 1090 welding certifications ahead of compressed BEV platform timelines to defend qualification bottlenecks against emerging competitors. Prioritize hot-stamping capacity additions in the Stuttgart-Munich corridor to maintain proximity to Volkswagen and BMW procurement desks. For New Entrants and Emerging Players: Begin with adjustable bracket designs for modular BEV platforms where Volkswagen's MEB and Ford's GE1 architectures favor flexible specifications across vehicle segments. Target battery pack support systems as the most penetrable white space, given 40-60% bracket count expansion per vehicle versus internal combustion equivalents. Pursue design-to-cost engineering partnerships with Tier-1 integrators lacking in-house aluminum forming expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor hot-forming specialists with ECE R94/R95 certified production cells in Germany and South Korea as platform standardization compresses supplier margins. Long-term viability hinges on lifecycle assessment capabilities enabling CSRD battery passport compliance. Watch for inflection signals in OEM aluminum recycling program announcements as recycled content quotas harden under EU circular economy action plans.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen's MEB and Ford's GE1 architectures favor adjustable bracket designs reducing tooling redundancy. |
| Battery Supply Agreement | Direct mill relationships with aluminum smelters secure volume commitments for BEV structural enclosures. |
| Software-Defined Vehicle Investment | Digital thread integration collapses design-validation cycles for compressed 24-30 month BEV development timelines. |
| Geographic Manufacturing Footprint | Stuttgart-Munich corridor proximity reduces logistics costs for German OEM just-in-time procurement. |
| Charging Infrastructure Partnership | Secondary bracket demand from charging station OEMs diversifies revenue beyond passenger vehicle platforms. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from publicly traded Tier-1 suppliers, complemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and stamping operations managers. Secondary validation drew from ECE R94/R95 regulatory documentation, EU Green Deal implementation guidance, and MIIT dual carbon policy frameworks. Bottom-up bracket content-per-vehicle estimates triangulated against top-down market value projections.
Segment-level outputs across material type, manufacturing process, product category, and end-user tier were generated through the projection horizon using vehicle platform rollout schedules and electrification penetration assumptions. CAGRs were derived from slope analysis of year-over-year value trajectories. Industry-specific forecast inputs included BEV platform bracket count multiples, aluminum price band assumptions, and hot-stamping process adoption curves.
Primary aluminum price volatility, welding qualification timeline extensions, and OEM platform standardization strategy shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on material substitution rates and regulatory compliance phase-in schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Automotive Differential Market
Automotive Components
Automobile Accessories Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Drive System Market
Automotive Components
Metal Forming for Automotive Market