
 Brazil Automotive Adaptive Lighting System Market | 2026-2036
Brazil Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Adaptive Lighting System Market Outlook
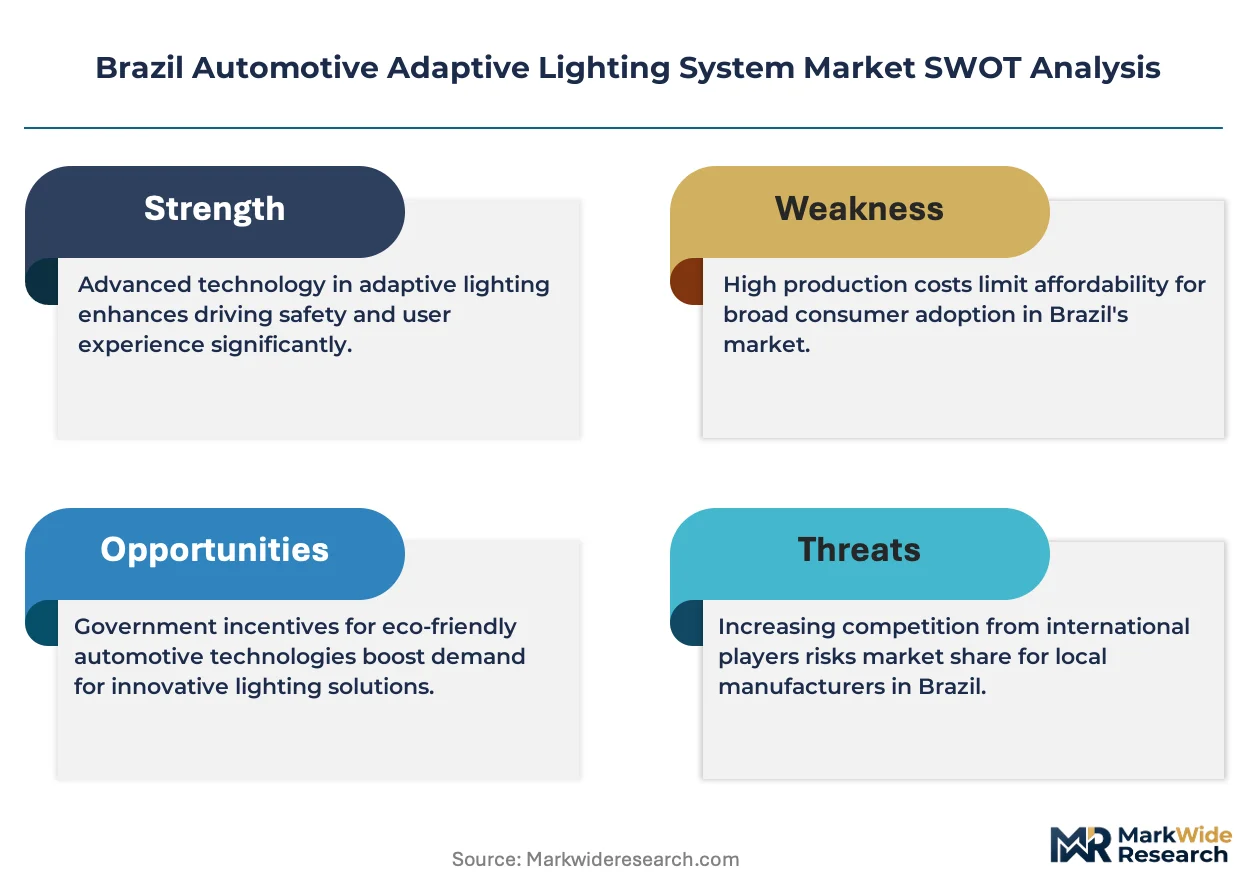
OEM buyer concentration among Brazil's premium vehicle assemblers is pivoting toward tier-1 suppliers with localized matrix LED capability. Hella KGaA Hueck & Co. sustains technology leadership through its adaptive front-lighting module specialization for Latin American road conditions. Koito Manufacturing Co., Ltd. anchors production scale advantages via its established Brazilian manufacturing footprint. Valeo Group differentiates through integrated sensor-to-lighting software stacks that reduce calibration complexity for domestic OEMs.
Automotive adaptive lighting systems modulate beam pattern, intensity, and direction in real time using camera inputs, steering angle sensors, and vehicle speed data to optimize road illumination without glare to oncoming traffic. Matrix LED arrays employ individually addressable diodes—typically 25 to 100 per headlamp—controlled by algorithms that extinguish specific segments to mask opposing vehicles while maintaining full beam elsewhere. LED product types dominate Brazil's installed base due to thermal efficiency and declining unit costs, though matrix LED configurations capture expanding margin pools as OEMs specify premium trims. AFS technology leads technology adoption among domestic manufacturers, while dynamic curve lighting gains penetration in imported luxury vehicle segments where regulatory compliance with Mercosur safety standards drives specification upgrades.
ANVISA coordinates with Brazil's national traffic department and Mercosur technical regulations to enforce headlamp photometric performance standards that mandate adaptive capability in new vehicle categories. INMETRO certification requirements for automotive lighting components create compliance barriers that favor established suppliers with local testing infrastructure. Stakeholders must monitor convergence between Brazil's regulatory trajectory and European ECE R48 amendments to anticipate specification divergence or harmonization that reshapes product development roadmaps.
Market Dynamics
Matrix LED technology migration from halogen platforms is compressing supplier qualification timelines while ANVISA alignment with Mercosur safety protocols redefines OEM sourcing criteria for Brazil's premium vehicle assemblers.
Growth Catalysts
- Mercosur Safety Protocol Harmonization:ANVISA coordination with regional technical regulations mandates adaptive capability in new vehicle categories, forcing specification upgrades across imported and domestic luxury segments.
- São Paulo Industrial Corridor Concentration:Premium sedan and SUV manufacturers cluster manufacturing operations in this state, creating localized demand density that accelerates tier-1 supplier investment in matrix LED production lines.
- LED Thermal Efficiency Gains:Declining unit costs for LED components reduce bill-of-material pressure on domestic OEMs, enabling adaptive lighting penetration into mid-tier vehicle trims previously served by static halogen systems.
Market Restraints
- INMETRO Certification Barriers:Automotive lighting component testing requirements favor established suppliers with captive local infrastructure, raising capital thresholds for new market entrants.
- Import Dependency for Matrix Controllers:Algorithm-intensive sensor-to-lighting software stacks rely on semiconductor inputs subject to cross-border supply volatility, compressing margin buffers for domestic assemblers.
- Halogen Platform Inertia:Economy vehicle segments retain static lighting architectures due to price-sensitive buyer profiles and limited regulatory enforcement in entry-level categories.
Strategic Opportunities
- Southern Brazil Assembly Belt Expansion:Vehicle manufacturing clusters in Rio Grande do Sul and Santa Catarina states remain underpenetrated by adaptive lighting suppliers with localized matrix LED capability.
- Dynamic Curve Lighting Specification:Imported luxury vehicle segments show accelerating adoption of cornering-optimized beam patterns, creating margin expansion potential for suppliers with integrated steering-angle sensor calibration.
- ECE R48 Amendment Convergence:Brazil's regulatory trajectory toward European headlamp photometric standards opens export pathway development for domestic suppliers meeting dual-certification requirements.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time beam-pattern algorithms require specialized firmware engineers with automotive functional-safety expertise, a skill set concentrated among tier-1 suppliers with multinational R&D networks.
- Legacy Electrical Architecture Integration:Domestic OEM vehicle platforms designed for static lighting systems require harness redesign and gateway module upgrades to support camera-input data streams for adaptive functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Adaptive Lighting System Market |
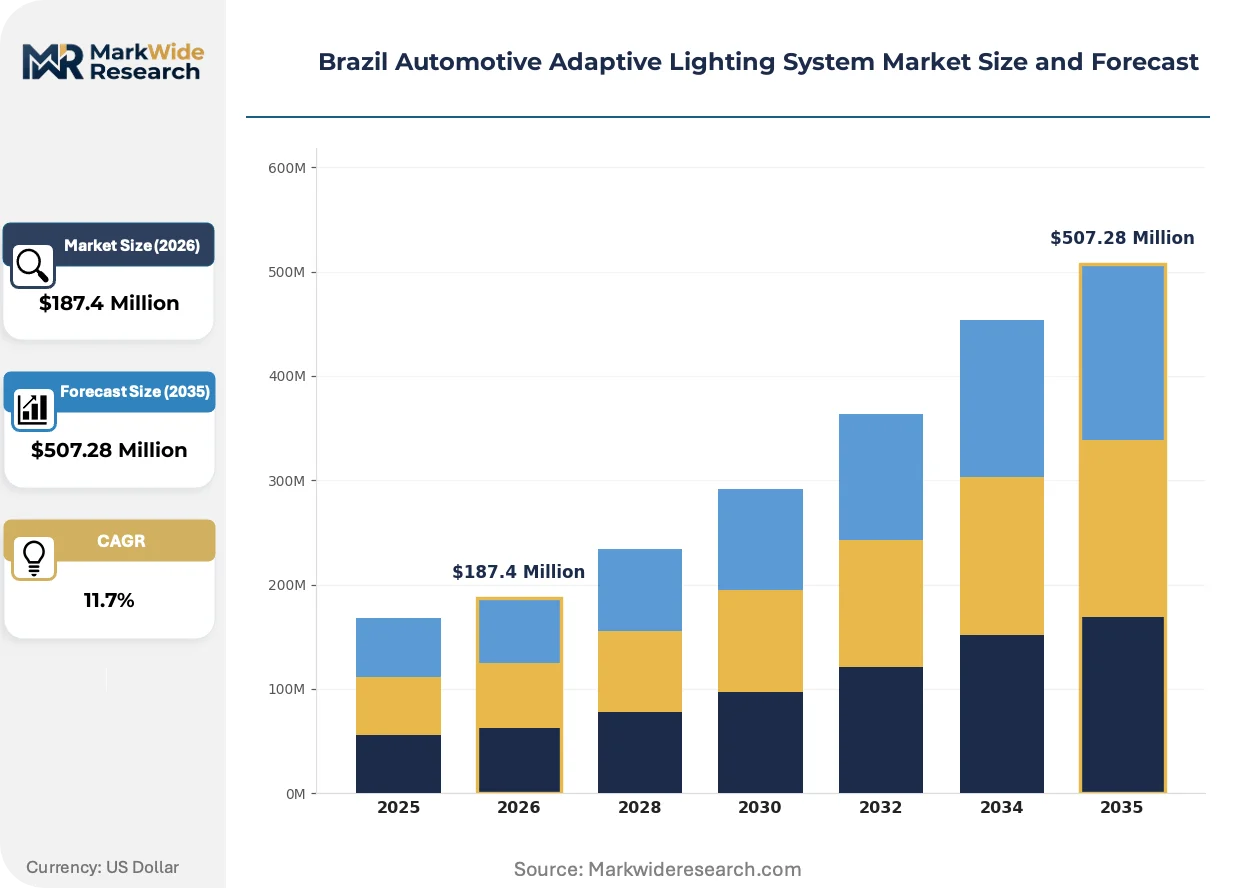
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LED, Adaptive Xenon, Laser Light, LED End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Auto High Beam, Dynamic Curve, AFS, Cornering Light Vehicle Type: SUVs, Sedans, Hatchbacks, Luxury Vehicles |
| Companies Covered | Stanley Electric Co., Ltd., Koninklijke Philips N.V., Hella KGaA Hueck & Co., Denso Corporation, Hyundai Mobis, Valeo Group, Osram Licht AG, Magneti Marelli S.p.A., Koito Manufacturing Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Adaptive Lighting System Market Strategic Shifts
Technology roadmaps for Brazil's automotive lighting sector center on three vectors: semiconductor-intensive beam control, regulatory specification convergence, and procurement model compression that favors vertically integrated tier-1 suppliers.
Matrix LED arrays with individually addressable diodes are electrifying headlamp architectures by enabling real-time segment extinction that masks opposing vehicles while maintaining full-beam illumination elsewhere. Premium SUV and sedan manufacturers in São Paulo state's industrial corridor specify these configurations at accelerating rates for flagship trims. This electrification is compressing the competitive window for halogen-tier suppliers unable to fund algorithm development and thermal management R&D.
ANVISA enforcement of Mercosur automotive safety protocols is mandating adaptive front-lighting capability in new vehicle categories above defined weight thresholds. The industrial consequence is specification divergence between domestic economy platforms and imported luxury segments, with compliance timelines compressing product development cycles. Southern Brazil's vehicle assembly belt shows the most pronounced response, with assemblers accelerating pre-certification testing to secure INMETRO approval ahead of regulatory phase-in dates.
Buyer concentration among Brazil's premium vehicle OEMs is consolidating procurement decisions toward tier-1 suppliers with captive matrix LED manufacturing and localized software calibration capability. Direct sourcing relationships are displacing traditional tier-2 component distribution channels for adaptive lighting modules. This channel compression is most visible in São Paulo state's industrial corridor, where OEM technical teams co-locate engineering resources with qualified suppliers to reduce integration timeline risk.
Brazil Automotive Adaptive Lighting System Market Segmentation
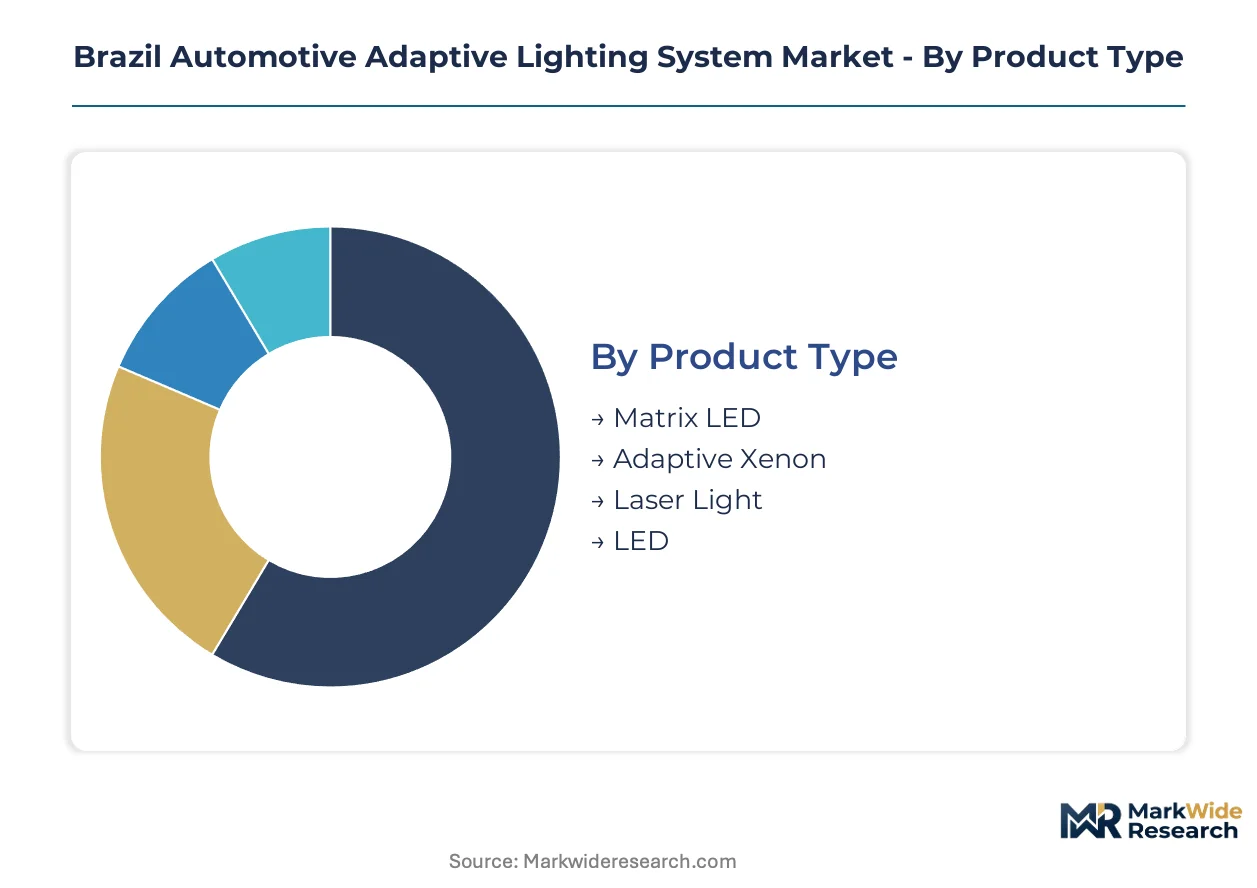
Brazil's adaptive lighting market fragments across four dimensions that determine supplier qualification requirements and margin capture potential. Product type and technology segments define the semiconductor and software intensity of procurement decisions, while end-user and vehicle type categories shape channel strategy and geographic targeting.
Product Type:
Integration depth varies sharply across this category, with embedded matrix configurations demanding full vehicle-electronics redesign versus standalone LED retrofits.
- Matrix LED:Individually addressable diode arrays of 25 to 100 units per headlamp enable real-time segment extinction algorithms. São Paulo state's premium SUV and sedan assemblers specify these for flagship trims where ANVISA compliance deadlines compress development timelines.
- LED:Solid-state architectures deliver thermal efficiency advantages that reduce cooling system complexity for domestic OEMs. Southern Brazil's vehicle assembly belt shows concentrated retrofit demand as economy-tier manufacturers phase out halogen platforms ahead of regulatory phase-in dates.
- Adaptive Xenon:Gas-discharge systems with motorized reflector positioning retain niche specification in imported luxury segments where legacy platform continuity limits LED migration speed.
- Laser Light:Semiconductor-pumped phosphor configurations extend beam throw distance for highway-optimized vehicle categories, though thermal management complexity restricts adoption to ultra-premium manufacturers with captive R&D resources.
LED leads volumes today; Matrix LED is gaining share fastest.
End User:
Customer-type concentration determines pricing power and contract duration, with captive OEM relationships commanding multi-year supply agreements versus spot-market aftermarket transactions.
- OEMs:Original equipment manufacturers in São Paulo's industrial corridor specify adaptive modules at the platform-design stage, embedding lighting control within domain-centralized electrical architectures.
- Vehicle Assemblers:Final-assembly operations in Rio Grande do Sul and Santa Catarina states source complete headlamp modules from tier-1 suppliers with localized INMETRO certification infrastructure.
- Tier-1 Suppliers:Integrated module producers with captive matrix LED manufacturing and software calibration capability capture procurement decisions as direct OEM relationships displace traditional distribution channels.
- Aftermarket Providers:Independent retrofit specialists serve price-sensitive economy-vehicle owners in Brazil's interior states where regulatory enforcement remains uneven and halogen platform inertia persists.
Vehicle Assemblers dominate procurement volumes; Tier-1 Suppliers are climbing the fastest as channel compression accelerates.
Technology:
Functional sophistication tiers separate regulatory-mandated baseline capability from premium-specification differentiation that commands margin expansion.
- AFS:Adaptive Front-lighting Systems modulate beam direction via steering-angle sensor inputs, forming the baseline specification for ANVISA compliance in new vehicle categories above defined weight thresholds.
- Dynamic Curve:Cornering-optimized beam patterns integrate vehicle-speed data with lateral-acceleration sensors to illuminate road curvature before steering input, penetrating imported luxury segments where Mercosur safety protocol alignment drives specification upgrades.
- Auto High Beam:Camera-based opposing-vehicle detection automates beam switching between full and dipped states, reducing driver workload on Brazil's underlit rural highway network.
- Cornering Light:Static or slow-speed supplemental illumination activates at low vehicle speeds to enhance maneuvering visibility in urban environments, specified primarily for compact SUV categories.
AFS anchors installed volumes today; Dynamic Curve shows the steepest expansion trajectory.
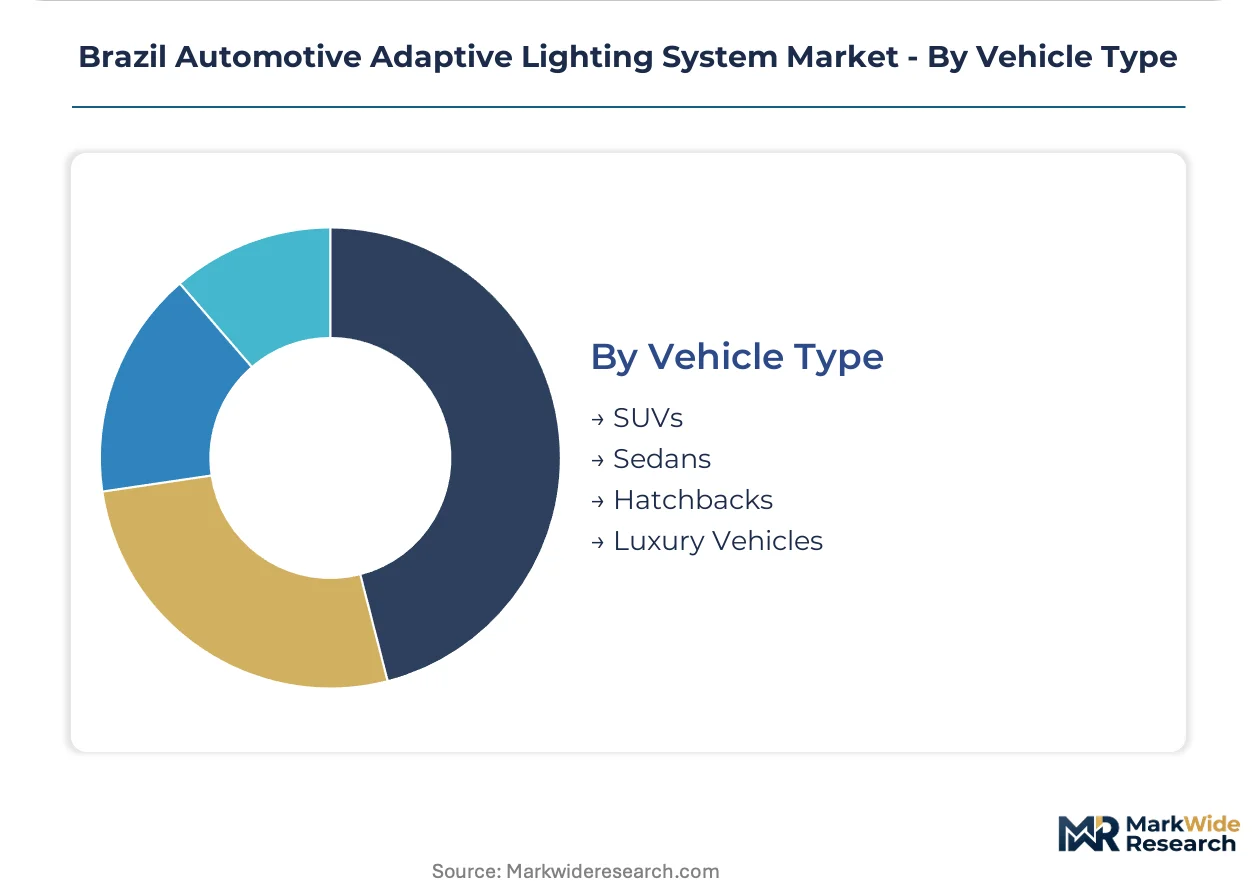
Vehicle Type:
Platform architecture and buyer-price tolerance segment this category, with body-style determination of electrical-system upgrade feasibility and trim-level specification authority.
- SUVs:Higher ride heights and premium trim-mix ratios enable adaptive lighting penetration at volume scale, with São Paulo-state manufacturers specifying matrix LED for mid-tier configurations previously served by static systems.
- Luxury Vehicles:Imported sedan and SUV categories from European and Japanese manufacturers carry specification baselines that exceed ANVISA minimums, creating technology-transfer pathways for domestic tier-1 suppliers.
- Sedans:Three-box configurations in Brazil's fleet and executive segments balance aerodynamic efficiency with lighting-module packaging constraints, favoring slim-profile LED arrays over bulkier xenon reflector systems.
- Hatchbacks:Compact body styles with price-constrained buyer profiles retain halogen dominance in entry-level categories, though B-segment premium variants in southern Brazil show emerging adaptive specification.
SUVs command the largest addressable base; Luxury Vehicles are expanding most quickly on import-segment specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium automotive lighting engineering density, while Brazil concentrates adaptive system assembly for Latin American vehicle platforms. Both markets operate under divergent regulatory timelines that reshape supplier investment priorities.
São Paulo
Matrix LED procurement concentrates among premium SUV and sedan manufacturers along the state's industrial corridor. ANVISA enforces Mercosur safety protocol alignment through phased adaptive capability mandates. São Paulo city hosts tier-1 supplier engineering co-location with OEM technical teams to compress integration timelines.
Rio Grande do Sul
Vehicle assemblers in this southern state source complete headlamp modules from suppliers with localized INMETRO certification infrastructure. The national traffic department coordinates with ANVISA on headlamp photometric performance enforcement. Porto Alegre anchors pre-certification testing acceleration ahead of regulatory phase-in dates.
Minas Gerais
Economy-tier manufacturers in this interior state retain halogen platform inertia due to price-sensitive buyer profiles. INMETRO certification barriers favor established suppliers with captive local testing infrastructure. Belo Horizonte's industrial periphery shows limited adaptive lighting penetration outside premium fleet segments.
Santa Catarina
Imported luxury vehicle distribution channels concentrate in this southern state, driving dynamic curve lighting specification upgrades. ANVISA alignment with European ECE R48 amendments opens dual-certification pathways for domestic suppliers. Joinville and Florianópolis assembly operations accelerate technology transfer from European OEM specification baselines.
Brazil Automotive Adaptive Lighting System Market Competitive Environment
German producers anchor the premium-tier supplier base; Japanese specialists hold manufacturing scale advantages in localized production. The vendor base concentrates among tier-1 integrators with captive matrix LED capability and embedded software stacks. Three archetypes dominate: vertically integrated lighting module producers, sensor-to-software platform integrators, and regional assembly specialists with regulatory certification depth. Competitive moves center on engineering co-location with OEM technical teams and backward integration into semiconductor controller sourcing.
Within the integrated module tier, Hella KGaA Hueck & Co. and Valeo Group exemplify European engineering density with localized Latin American adaptation capability. Koito Manufacturing Co., Ltd. occupies a position representing Japanese manufacturing scale with established Brazilian production footprint. These three anchors illustrate the geographic split between European specification leadership and Asian production economics that defines supplier qualification dynamics for Brazil's premium vehicle assemblers.
| Leading Market Players |
|---|
| Stanley Electric Co., Ltd. |
| Koninklijke Philips N.V. |
| Hella KGaA Hueck & Co. |
| Denso Corporation |
| Hyundai Mobis |
| Valeo Group |
| Osram Licht AG |
| Magneti Marelli S.p.A. |
| Koito Manufacturing Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive matrix LED manufacturing by tier-1 suppliers anchors both supply security and pricing power in Brazil's adaptive lighting sector, with localized production footprints enabling premium positioning against import-dependent competitors serving ANVISA-mandated specification upgrades.
Pricing Analysis
Capacity additions in São Paulo state's industrial corridor are reshaping price floors for matrix LED modules as Hella, Valeo, and Koito expand localized production lines. Three-tier pricing structure across premium, standard, and economy levels separates flagship SUV configurations from mid-tier sedan trims and halogen-retrofit aftermarket segments. Cost compression in economy-tier LED retrofits is intensifying because southern Brazil's vehicle assemblers source complete modules from tier-1 suppliers with captive INMETRO certification infrastructure. Fleet buyers and economy-vehicle owners show highest price sensitivity, while premium SUV manufacturers demonstrate lowest sensitivity due to regulatory compliance deadlines and trim-mix optimization.
Supply Chain Analysis
Semiconductor controller supply rests on German and Japanese specialty producers, with algorithm-intensive sensor-to-lighting software stacks drawing from Taiwan and South Korea for embedded processing components. Raw material dependencies span high-brightness LED dies, thermal management substrates, and automotive-grade camera sensors. Single-source vulnerability in matrix controller firmware creates exposure to cross-border supply volatility, particularly for domestic assemblers lacking backward integration into semiconductor sourcing. Distribution runs through direct OEM procurement relationships that displace traditional tier-2 component channels, with engineering co-location agreements compressing integration timelines for São Paulo-based premium vehicle manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's adaptive lighting market functions as a geographic-arbitrage play where European specification leadership meets Asian manufacturing economics, with ANVISA's Mercosur alignment creating regulatory pull that justifies premium pricing against halogen-platform inertia in economy segments.
For Market Incumbents: Extend software calibration capability through embedded firmware talent acquisition in Porto Alegre and Joinville engineering clusters, countering the threat of semiconductor supply volatility by securing captive controller sourcing from established Asian foundry relationships. Deepen backward integration into thermal management substrate production to defend margin position against LED die cost fluctuations.
For New Entrants and Emerging Players: Enter via southern Brazil's underpenetrated Rio Grande do Sul and Santa Catarina assembly belts, where vehicle manufacturers lack localized matrix LED suppliers with INMETRO certification infrastructure. Target dynamic curve lighting specification for imported luxury SUV segments, leveraging steering-angle sensor integration partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for tier-1 module integrators with captive software stacks because channel compression is accelerating direct OEM relationships that displace traditional distribution. Focus acquisition screening on Brazilian-based suppliers with dual ECE R48 and ANVISA certification capability. Watch for inflection in Mercosur regulatory harmonization timelines that would trigger specification upgrade cycles across domestic economy platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Matrix LED Manufacturing Localization | São Paulo production footprint reduces INMETRO certification timelines for premium OEMs. |
| Sensor-to-Software Vertical Integration | Captive algorithm development insulates margin from semiconductor controller volatility. |
| Dual-Certification Pathway Investment | ECE R48 alignment opens export channels for Brazilian tier-1 suppliers. |
| Engineering Co-Location Agreements | OEM technical team proximity compresses platform integration risk. |
| Thermal Management R&D Expansion | LED thermal efficiency gains enable mid-tier trim penetration beyond flagship specifications. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and ANVISA regulatory affairs specialists with secondary validation from vehicle production databases, INMETRO certification records, Mercosur technical regulation filings, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market value estimates derived from tier-1 supplier revenue disclosures.
Segment-weighting approaches modeled technology adoption curves across AFS and dynamic curve lighting configurations, vehicle class stratification from economy hatchbacks to premium SUVs, and regional production cluster differentiation between São Paulo's industrial corridor and southern Brazil's assembly belt. CAGRs were derived from installation rate projections tied to ANVISA regulatory phase-in schedules and OEM platform redesign cycles, with inputs including LED component cost decline trajectories and matrix LED content-per-vehicle assumptions across trim levels.
The model holds under sustained Mercosur regulatory harmonization and stable semiconductor supply conditions; deviation in ANVISA enforcement timelines or cross-border controller availability would shift volume trajectories. A small set of named triggers warrants ongoing watch: ECE R48 amendment convergence pace, tier-1 supplier capacity expansion announcements, and embedded software talent migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market