
 Automotive Evaporative Emission Control (EVAP) System Market | 2026-2036
Automotive Evaporative Emission Control (EVAP) System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Evaporative Emission Control (EVAP) System Market Analysis
California LEV III certification-grade hardware is redrawing supplier priorities across the EVAP value chain. Plastic Omnium Group leverages its fuel system integration expertise to anchor European OEM contracts for low-permeation tank assemblies. Tenneco Inc. competes through specialized purge valve manufacturing that sustains North American aftermarket channels. Denso Corporation dominates integrated sensor-canister modules for Japanese and Korean vehicle platforms.
An automotive evaporative emission control system captures fuel vapors from the tank and carburetor, routing them through activated charcoal canisters for adsorption before controlled purge into the engine intake; modern assemblies operate at pressure thresholds below 2.5 kPa to prevent hydrocarbon escape during diurnal temperature cycling. Charcoal canister designs occupy the largest margin pool as carbon loading specifications tighten under regulatory test protocols. Purge valve assemblies represent the fastest-growing product category as pulse-width modulation precision replaces legacy vacuum-operated designs. Active carbon adsorption technology leads the technology dimension while integrated ECUs with pressure cycling diagnostics capture premium positioning in hybrid vehicle applications.
EPA tailpipe and evaporative standards together with CARB enforcement in California shape hardware specifications that OEMs must certify before market entry. NHTSA safety integration rules further constrain fuel system architecture choices for domestic vehicle production. Stakeholders must monitor pending revisions to federal test procedures and state-level zero-emission vehicle mandates that will redefine canister capacity and leak detection thresholds.
Market Dynamics
EPA Tier 3 and CARB LEV III hydrocarbon limits are compressing canister capacity specifications while hybrid powertrain proliferation demands sealed fuel systems that operate across intermittent combustion cycles. This regulatory-technology intersection is restructuring supplier qualification criteria and procurement timelines across OEM engineering departments.
Growth Catalysts
- CARB LEV III Certification Mandates:California's zero-emission vehicle framework tightens evaporative emission thresholds, forcing hardware upgrades across all gasoline-powered vehicle categories sold in the state.
- Activated Carbon Loading Advances:Enhanced carbon adsorption materials extend canister service intervals while meeting stricter diurnal breathing loss test protocols under federal procedures.
- Hybrid Architecture Expansion:Plug-in hybrid vehicles require robust EVAP systems capable of managing extended fuel storage periods with minimal vapor escape during electric-only operation modes.
Market Restraints
- Specialized Carbon Feedstock Concentration:High-grade activated carbon for automotive canisters concentrates among limited suppliers, exposing procurement to petrochemical derivative price volatility.
- Precision Manufacturing Bottlenecks:Sub-2.5 kPa pressure threshold compliance demands specialized purge valve production equipment with extended qualification lead times.
- Cross-Border Certification Friction:Divergent EPA and CARB test procedures create redundant validation requirements that extend product launch timelines for multi-market OEM programs.
Strategic Opportunities
- Integrated ECU-Diagnostic Convergence:Pressure cycling diagnostic modules combined with purge valve control electronics capture premium positioning in hybrid vehicle architectures.
- Aftermarket Channel Digitization:Direct-to-installer platforms for purge valve and canister replacement parts bypass traditional distributor markups in North American service networks.
- China NEV Subsidy Alignment:Extended-range electric vehicle incentives under MIIT guidelines create specification pull for advanced EVAP hardware in domestic Chinese platforms.
Industry Challenges
- Embedded Systems Integration Complexity:Merging pressure sensors, purge valves, and engine control unit communication protocols demands rare cross-functional engineering talent spanning mechanical and software domains.
- Validation Timeline Compression:Accelerated vehicle development cycles strain traditional 18-month certification schedules for new canister designs under evolving EPA test procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Evaporative Emission Control (EVAP) System Market |
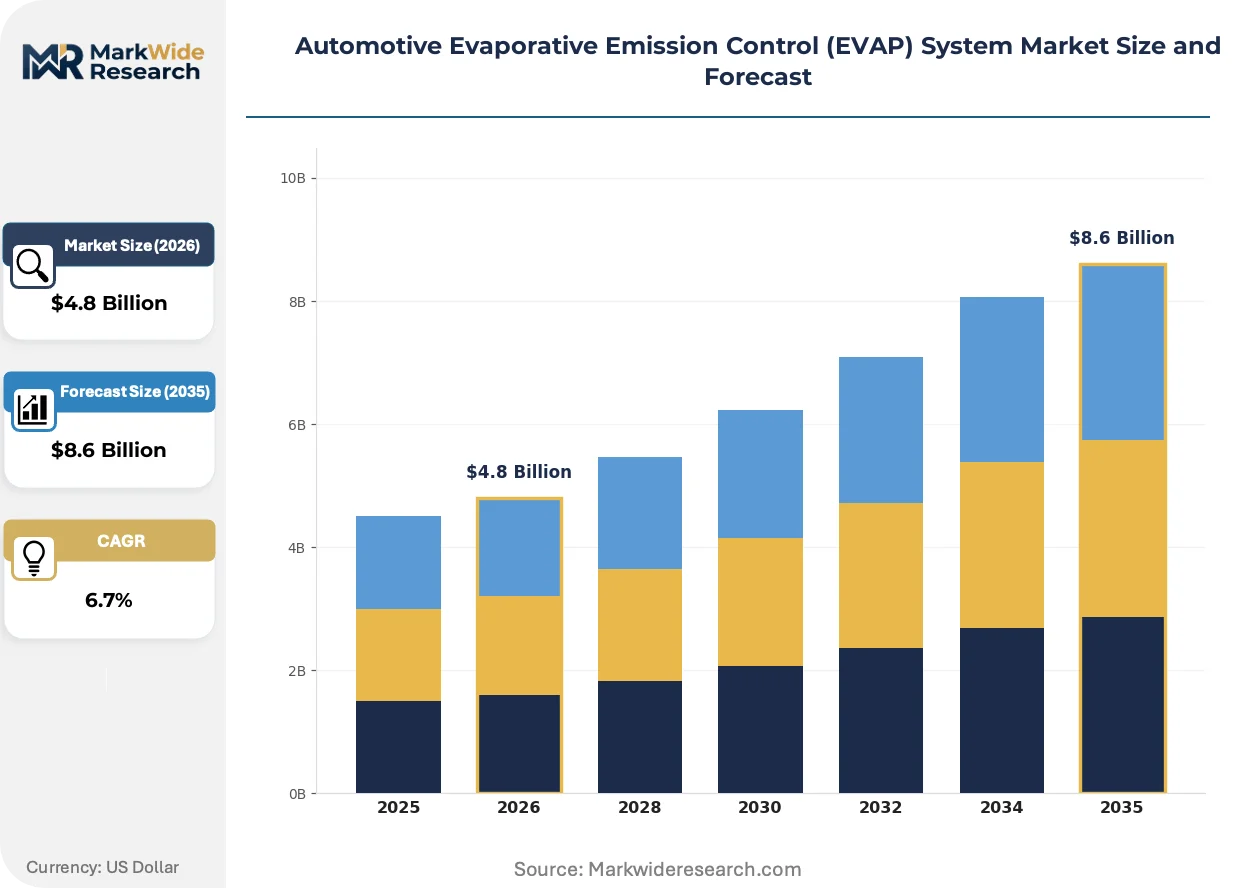
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Tank Vent Valve, Charcoal Canister, Purge Valve, Electronic Control Unit Application: Passenger Vehicles, Commercial Vehicles, Light Duty Trucks, Heavy Duty Vehicles End User: OEMs, Aftermarket, Aftermarket Suppliers, Vehicle Assemblers Technology: Active Carbon Adsorption, Pressure Cycling, Vacuum Systems, Integrated ECUs |
| Companies Covered | Plastic Omnium Group, Tenneco Inc., Delphi Technologies, TI Automotive, Faurecia, Denso Corporation, Continental AG, BorgWarner Inc., Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Evaporative Emission Control (EVAP) System Market Emerging Trajectories
Pulse-width modulation control architectures are replacing legacy vacuum-operated purge mechanisms, while integrated sensor modules embed diagnostic capabilities directly into canister assemblies. These shifts compress component counts and enable predictive maintenance interfaces.
Electronic solenoid purge valves with millisecond-response pulse-width modulation are supplanting diaphragm-actuated vacuum valves in new vehicle programs. OEM powertrain engineers specify these units for hybrid platforms requiring precise fuel vapor metering across intermittent engine operation. This supplanting action is collapsing the addressable market for purely mechanical purge actuators and elevating firmware development to core supplier competency.
EPA's pending revisions to federal test procedures for evaporative emissions will extend diurnal temperature cycling requirements and tighten leak detection thresholds. Hardware suppliers must redesign canister capacity and seal interfaces to certify under the expanded protocol scope. Small-volume OEMs with limited validation resources face disproportionate compliance burdens relative to integrated Tier 1 system providers.
Buyer concentration among electrifying OEMs is consolidating procurement authority into centralized powertrain engineering groups, displacing historical component-level sourcing decisions. Tier 1 system integrators now negotiate directly with platform architects rather than fuel system sub-teams. This pattern is most pronounced in German and Japanese OEM organizations where hybrid volume targets dominate capital allocation committees.
Automotive Evaporative Emission Control (EVAP) System Market Segmentation
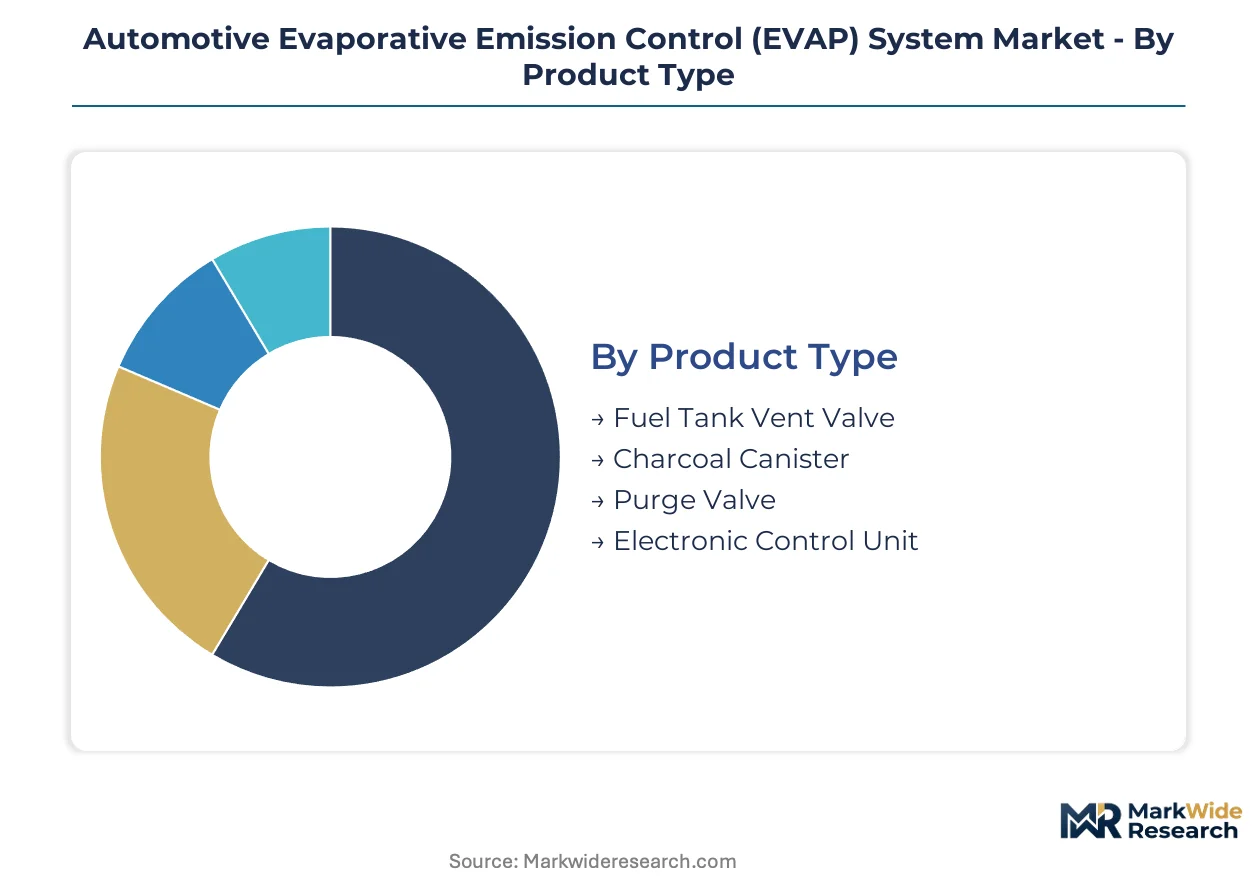
EVAP system segmentation reveals divergent margin structures across hardware categories, with charcoal canister and purge valve assemblies commanding premium positioning under tightening EPA Tier 3 and CARB LEV III certification protocols. Technology integration intensity varies sharply by application, creating distinct supplier qualification tiers that reshape procurement authority across OEM engineering organizations.
Product Type:
Margin pools concentrate in canister and valve assemblies where activated carbon loading specifications and pulse-width modulation precision determine certification outcomes.
- Charcoal Canister:Activated carbon assemblies adsorb hydrocarbon vapors from fuel tanks under diurnal temperature cycling below 2.5 kPa pressure thresholds. Demand concentrates among German and Japanese OEMs certifying hybrid architectures for extended electric-only storage periods where vapor accumulation risks are highest.
- Purge Valve:Electronic solenoid designs with millisecond-response pulse-width modulation replace legacy vacuum-actuated mechanisms, enabling precise fuel vapor metering across intermittent combustion cycles in plug-in hybrid powertrains. Procurement timelines extend due to specialized manufacturing equipment requirements.
- Fuel Tank Vent Valve:Pressure relief mechanisms maintain sealed system integrity during thermal expansion events.
- Electronic Control Unit:Integrated diagnostic modules embed pressure cycling detection and engine communication protocols.
The dominant share belongs to Charcoal Canister, while Purge Valve is closing the gap fastest.
Application:
Volume distribution tracks electrification intensity, with hybrid-capable segments pulling advanced EVAP specifications ahead of conventional combustion-only categories.
- Passenger Vehicles:Light-duty platforms dominate procurement volumes as CARB LEV III mandates apply across all gasoline-powered categories sold in California, forcing hardware upgrades even for entry-level segments. Chinese and German OEMs concentrate specification authority for sealed fuel systems in this category.
- Light Duty Trucks:Pickup and van architectures in North American markets face dual pressure from EPA Tier 3 evaporative limits and extended-range electric variants requiring robust vapor containment during prolonged electric operation modes.
- Commercial Vehicles:Fleet operators prioritize service interval extension over initial hardware cost.
- Heavy Duty Vehicles:Diesel-dominated segments apply EVAP requirements selectively based on fuel type and operating cycle.
Passenger Vehicles retains the volume lead, though Light Duty Trucks shows the steepest specification upgrade trajectory.
End User:
Procurement authority is consolidating into centralized powertrain engineering groups, displacing historical component-level sourcing decisions.
- OEMs:Original equipment manufacturers negotiate directly with Tier 1 system integrators for platform-level fuel system architecture, particularly in German and Japanese organizations where hybrid volume targets dominate capital allocation. Certification liability concentrates at this tier.
- Vehicle Assemblers:Contract manufacturing operations in China and Mexico source pre-certified module assemblies rather than discrete components, reducing validation burden but limiting supplier switching flexibility.
- Aftermarket:Service channel demand concentrates in North American replacement cycles for purge valve failures.
- Aftermarket Suppliers:Distributor networks face digitization pressure from direct-to-installer platforms.
OEMs command the procurement hierarchy, while Aftermarket channels are gaining pricing transparency fastest.
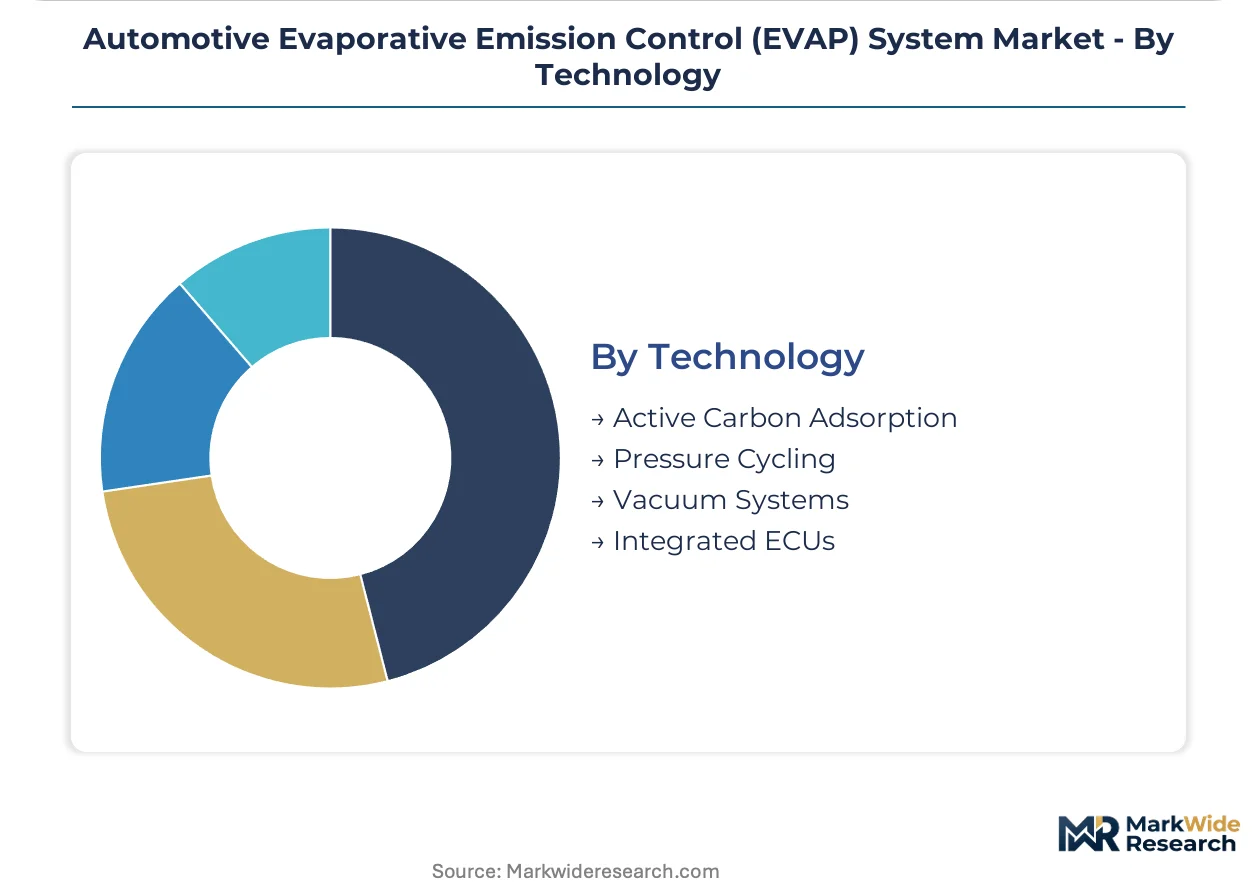
Technology:
Technology selection determines regulatory compliance pathway, with integrated architectures capturing premium positioning in hybrid applications.
- Active Carbon Adsorption:High-grade activated carbon materials remain the foundational vapor capture mechanism, with carbon loading specifications tightening under extended diurnal breathing loss test protocols. Feedstock concentration among limited petrochemical derivative suppliers exposes procurement to price volatility.
- Integrated ECUs:Combined pressure sensor, purge valve control, and diagnostic communication modules embed predictive maintenance interfaces directly into canister assemblies. Japanese and Korean platforms specify these units for hybrid architectures requiring seamless engine control unit coordination.
- Pressure Cycling:Diagnostic protocols detect micro-leaks below revised EPA thresholds.
- Vacuum Systems:Legacy diaphragm-actuated mechanisms face collapsing addressable market as electronic solenoids supplant them.
Active Carbon Adsorption holds the installed base advantage, though Integrated ECUs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports EVAP system components to hybrid vehicle programs across China and the United States, establishing the primary trade-flow corridor for sealed fuel system technology. This transnational supply pattern concentrates procurement authority in German engineering centers while driving specification harmonization across EPA and MIIT regulatory frameworks.
United States
CARB LEV III mandates in California force hardware upgrades across all gasoline-powered vehicle categories, tightening hydrocarbon vapor limits below 2.5 kPa thresholds. EPA Tier 3 federal test procedures extend diurnal temperature cycling requirements nationwide. Detroit's automotive engineering clusters anchor Tier 1 supplier qualification programs for sealed tank assemblies serving plug-in hybrid architectures.
Germany
Baden-Württemberg and Bavaria concentrate fuel system integration expertise for European OEM hybrid platforms. KBA enforcement aligns with EU Green Deal decarbonization timelines for evaporative emission hardware. Stuttgart's supplier engineering centers coordinate charcoal canister specifications across extended-range electric vehicle programs targeting Chinese export markets.
China
MIIT new energy vehicle subsidies create specification pull for advanced EVAP hardware in domestic plug-in hybrid platforms. Extended-range electric vehicle incentives under national dual carbon goals tighten carbon loading requirements. Yangtze River Delta manufacturing clusters scale activated carbon canister production for both local OEMs and German vehicle assembly joint ventures.
Japan
METI fuel efficiency standards intersect with evaporative emission protocols for hybrid-dominant vehicle fleets. Integrated sensor-canister modules capture premium positioning as Japanese OEMs specify seamless engine control unit coordination. Nagoya's automotive component belt concentrates purge valve manufacturing with millisecond-response pulse-width modulation capabilities.
South Korea
MFDS-aligned environmental regulations and national K-EV100 electrification targets compress canister capacity specifications for domestic hybrid platforms. Seoul Capital Area engineering centers specify sealed fuel systems capable of managing extended electric-only storage periods. Busan-Ulsan manufacturing corridors export integrated ECU-diagnostic modules to North American vehicle assembly operations.
Automotive Evaporative Emission Control (EVAP) System Market Vendor Landscape
Listed leaders compete with private specialists across fuel system integration and precision valve manufacturing dimensions, creating a tiered structure where scale-driven conglomerates anchor platform-level contracts while niche engineering houses capture aftermarket channels. Strategic archetypes divide into integrated system providers, specialized component fabricators, and electronics-integrated module developers. Dominant competitive moves include backward integration into activated carbon feedstock sourcing and technology licensing agreements for pulse-width modulation control architectures.
Among European-based system integrators, Plastic Omnium Group exemplifies the fuel system consolidation archetype, while Faurecia occupies a position within emissions-integrated cockpit module development. Denso Corporation anchors the Asia-Pacific electronics convergence tier alongside Continental AG, which represents the German diversified automotive supplier model. These three entities sit within distinct competitive vectors—fuel tank integration, sensor-electronics fusion, and multi-domain automotive supply—rather than direct product overlap.
| Leading Market Players |
|---|
| Plastic Omnium Group |
| Tenneco Inc. |
| Delphi Technologies |
| TI Automotive |
| Faurecia |
| Denso Corporation |
| Continental AG |
| BorgWarner Inc. |
| Robert Bosch |
| Others |
Supply Flow & Price Mechanics
EPA Tier 3 and CARB LEV III certification protocols gate both supplier qualification timelines and price differentiation across hardware tiers simultaneously. OEM procurement teams face compressed negotiation windows as activated carbon feedstock scarcity and precision manufacturing bottlenecks concentrate cost pressure in canister and purge valve assemblies.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across CARB LEV III certification grade, volume scale, and carbon loading specification tiers. Price differentiation hinges on EPA Tier 3 compliance grade and pulse-width modulation precision capability. Cost compression in entry-level canister assemblies is intensifying because activated carbon feedstock draws from concentrated petrochemical derivative suppliers. Fleet operators and contract vehicle assemblers exhibit highest price sensitivity; German and Japanese OEM platform engineers show lowest sensitivity where hybrid architecture mandates override unit cost concerns.
Supply Chain Analysis
Germany and China anchor charcoal canister fabrication and integrated ECU module assembly for global hybrid vehicle programs. High-grade activated carbon feedstock sources from limited petrochemical derivative suppliers; electronic solenoid purge valves rest on specialized semiconductor and precision coil winding inputs. Single-source vulnerability concentrates in activated carbon feedstock where three suppliers control automotive-grade material specifications. Distribution runs through Tier 1 system integrators directly to OEM powertrain engineering groups, bypassing historical component-level distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
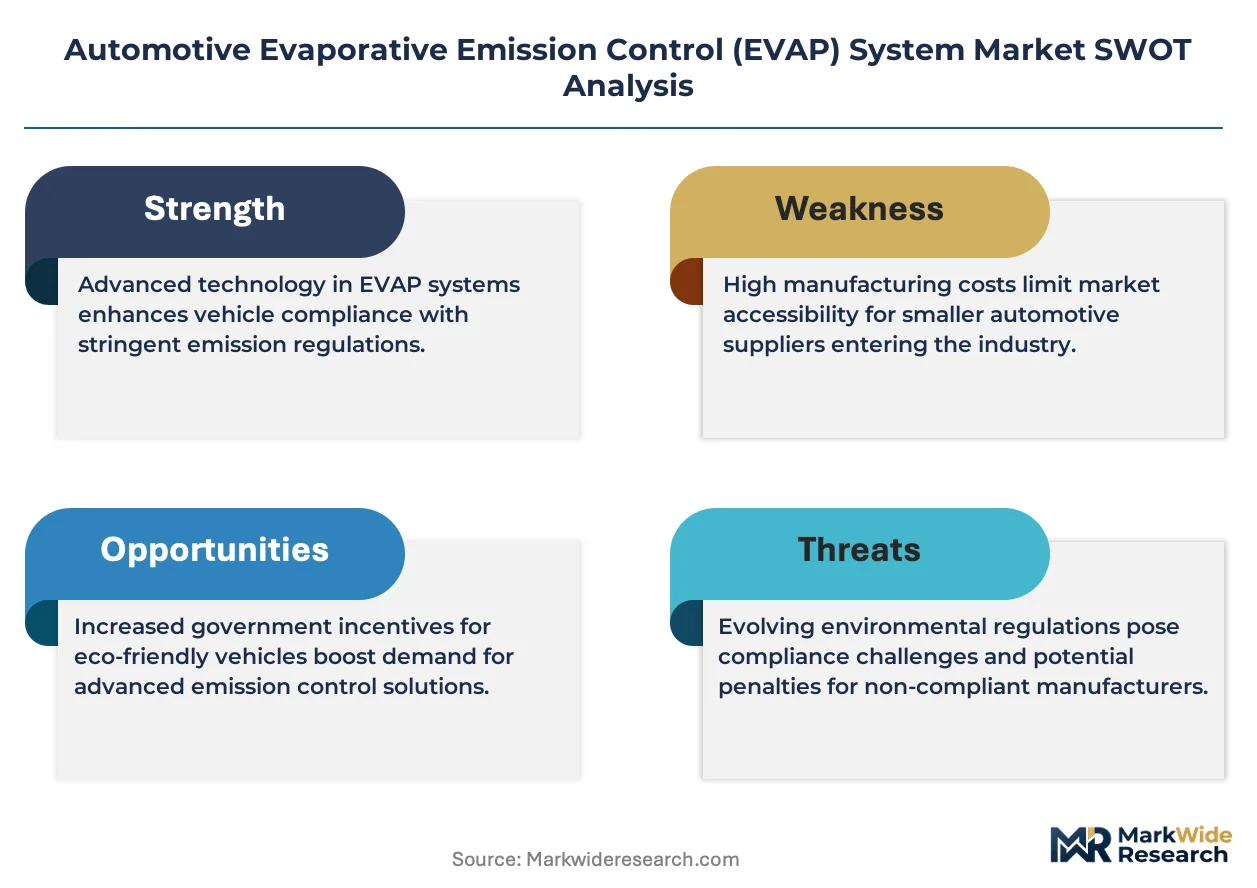
Full battery electric vehicle proliferation threatens evaporative emission control hardware demand as plug-in hybrid volumes face substitution pressure from zero-tailpipe architectures. Incumbents must navigate this technology transition while defending hybrid platform content per vehicle.
For Market Incumbents: Fortify backward integration into activated carbon feedstock sourcing to secure supply continuity against petrochemical derivative price volatility. Deepen firmware development capabilities for pulse-width modulation control architectures as electronic solenoid purge valves supplant legacy vacuum mechanisms. CARB LEV III threshold tightening and battery electric vehicle substitution represent parallel threats requiring dual-track investment in hybrid-optimized hardware and adjacent emission control technologies.
For New Entrants and Emerging Players: Anchor in aftermarket channel digitization for purge valve replacement cycles where North American service networks seek direct-to-installer procurement transparency. Target China NEV subsidy-aligned extended-range electric vehicle platforms where MIIT guidelines create specification pull for advanced canister designs. A go-to-market angle through integrated ECU-diagnostic module development for Korean and Japanese hybrid architectures offers white-space penetration with lower qualification barriers than German OEM direct supply.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated sensor-canister module manufacturing as hybrid vehicle architectures demand embedded diagnostic capabilities. Long-term viability over the next decade hinges on supplier positioning within electrifying OEM platform roadmaps where sealed fuel system content per vehicle compresses but specification value concentrates. Acquisition target archetypes include precision purge valve specialists with pulse-width modulation firmware assets and activated carbon canister fabricators with captive feedstock arrangements. The signal to watch is EPA federal test procedure revision timing, which would trigger accelerated hardware redesign cycles and consolidation pressure on small-volume validation-limited suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Activated Carbon Feedstock | Captive supply of high-grade carbon material secures margin protection against petrochemical derivative volatility. |
| Pulse-Width Modulation Firmware Development | Millisecond-response solenoid control capability captures hybrid platform specifications from Japanese and Korean OEMs. |
| Integrated ECU-Diagnostic Module Launch | Combined pressure sensing and engine communication protocols embed predictive maintenance interfaces for premium positioning. |
| Aftermarket Channel Digitization | Direct-to-installer platforms bypass distributor markups in North American purge valve replacement cycles. |
| China NEV Subsidy Alignment | MIIT extended-range electric vehicle incentives create specification pull for advanced canister hardware in domestic platforms. |
Methodological Framework
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and activated carbon material specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA regulatory filings, CARB certification databases, vehicle production registries, and customs trade records for evaporative emission hardware categories. Bottom-up segment sizing and top-down market reconciliation anchored triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level growth trajectory modeling informed projections throughout the forecast period. Key inputs included hybrid vehicle platform rollout schedules, EPA test procedure revision timelines, and activated carbon feedstock capacity expansion announcements.
Decision-makers should treat outputs as directional under assumptions of sustained hybrid vehicle volume growth and stable regulatory enforcement intensity; material deviation in battery electric vehicle substitution rates or federal test procedure scope expansion would warrant model refresh. Recalibration cycles align with material shifts in EPA rulemaking, CARB LEV III enforcement actions, and OEM platform electrification announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Automotive Metal Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Differential Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Automotive Emblem Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Gudgeon Pin Market