
 Autonomous Vehicle Management Services Market | 2026-2036
Autonomous Vehicle Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Vehicle Management Services Market Outlook
Level 4 autonomy certification is unwinding legacy fleet management conventions across the autonomous vehicle management services landscape. Waymo leverages its extensive real-world testing database to sustain operational leadership in rider-facing deployments. Baidu Apollo anchors its position through deep integration with Chinese smart-city infrastructure. Aurora Innovation differentiates via its FirstLight LiDAR platform and highway-focused logistics specialization.
Autonomous vehicle management services encompass the software, connectivity, and operational oversight systems that coordinate self-driving fleets, incorporating real-time sensor telemetry, over-the-air update protocols, and predictive maintenance algorithms to ensure safe, efficient commercial transport. Fleet management and cloud services segments currently capture the largest revenue pools as operators prioritize centralized visibility across distributed vehicle assets. AI algorithms within the technology dimension represent the fastest-expanding capability layer, though sensor fusion retains critical importance for redundancy in safety-critical applications.
NHTSA in the United States, the EU AI Act in Europe, and MIIT standards in China collectively impose stringent validation requirements on autonomous fleet operators, directly shaping product development timelines and market access conditions. The Federal Aviation Administration's overlapping jurisdiction for drone-based last-mile integration adds complexity to multi-modal service architectures. Stakeholders must monitor evolving liability frameworks that transfer responsibility from human drivers to fleet operators and software vendors.
Market Dynamics
Level 4 autonomy certification is dismantling legacy fleet management architectures as operators confront new liability frameworks that transfer accountability from human drivers to software vendors and fleet operators.
Growth Catalysts
- EU AI Act compliance mandates:European logistics providers are accelerating platform upgrades to meet algorithmic transparency requirements for autonomous decision-making systems in commercial transport.
- Freight corridor densification:Dedicated autonomous lanes along major highway networks in Germany, California, and China justify capital deployment in centralized operations centers.
- Edge computing infrastructure:Real-time sensor fusion at the vehicle level reduces latency for safety-critical maneuvers in urban delivery applications.
Market Restraints
- LiDAR sensor supply concentration:Production of high-fidelity optical components remains concentrated among a limited supplier base, creating input cost volatility for fleet operators.
- NHTSA validation timelines:Extended federal review periods for autonomous vehicle exemptions delay commercial deployment schedules and compress revenue recognition windows.
- Human-in-the-loop redundancy:Regulatory requirements for remote operator oversight sustain labor cost structures that offset autonomy-driven efficiency gains.
Strategic Opportunities
- Indian logistics corridors:Underpenetrated long-haul freight routes between Delhi-Mumbai and Chennai-Bengaluru present first-mover advantages for autonomous trucking platforms.
- Battery-electric convergence:Integration of autonomous management systems with electric drivetrain optimization creates unified fleet efficiency platforms for sustainability-focused shippers.
- Drone-last-mile hybrid networks:FAA Part 135 certification pathways for aerial delivery expand multi-modal service architectures beyond ground-based transport.
Industry Challenges
- Functional safety engineering talent:Shortage of ISO 26262-certified systems engineers constrains platform development velocity for safety-critical software modules.
- Legacy fleet integration:Retrofit complexity for existing telematics infrastructure delays unified visibility across mixed autonomous and human-driven assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Vehicle Management Services Market |
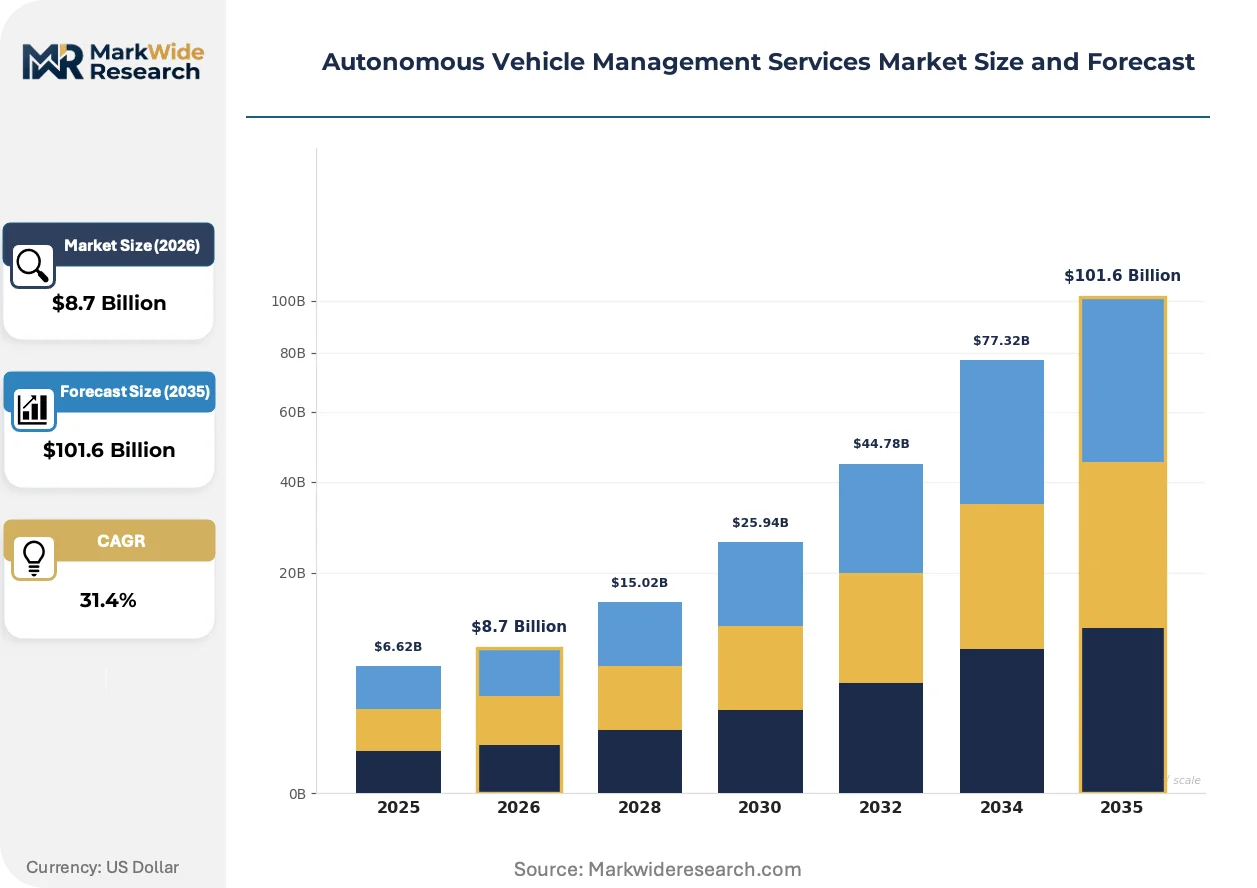
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fleet Management, Tracking Solutions, Cloud Services, Maintenance Support Technology: LiDAR, Computer Vision, AI Algorithms, Sensor Fusion End User: Logistics Providers, Public Transport Agencies, Ride-Sharing Platforms, Delivery Services Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Waymo, Cruise, Tesla, Baidu Apollo, Aurora Innovation, Mobileye, Pony.ai, Inceptio Technology, Zoox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Vehicle Management Services Market Strategic Shifts
Autonomous vehicle management services are undergoing architectural transformation as edge intelligence, regulatory harmonization, and procurement rationalization reshape operational models across commercial transport.
Sensor fusion architectures are fragmenting traditional centralized processing models. Distributed computing nodes at the vehicle level handle real-time obstacle detection and path planning, reducing dependency on continuous cloud connectivity. Logistics operators in high-latency corridors are prioritizing these edge-capable platforms for reliability-critical freight movements.
REACH chemical safety standards in Europe are extending to autonomous vehicle sensor materials and battery chemistries, forcing component suppliers to reformulate optical coatings and thermal management fluids. Fleet operators sourcing EU-certified hardware face extended qualification timelines but gain preferential access to continental logistics contracts.
Shippers are consolidating vendor relationships around integrated platform providers capable of unified visibility across autonomous and conventional assets. This rationalization displaces point-solution telematics vendors in North American freight procurement. Large retail distributors now mandate API-native fleet management stacks as a condition of carrier qualification.
Autonomous Vehicle Management Services Market Segmentation
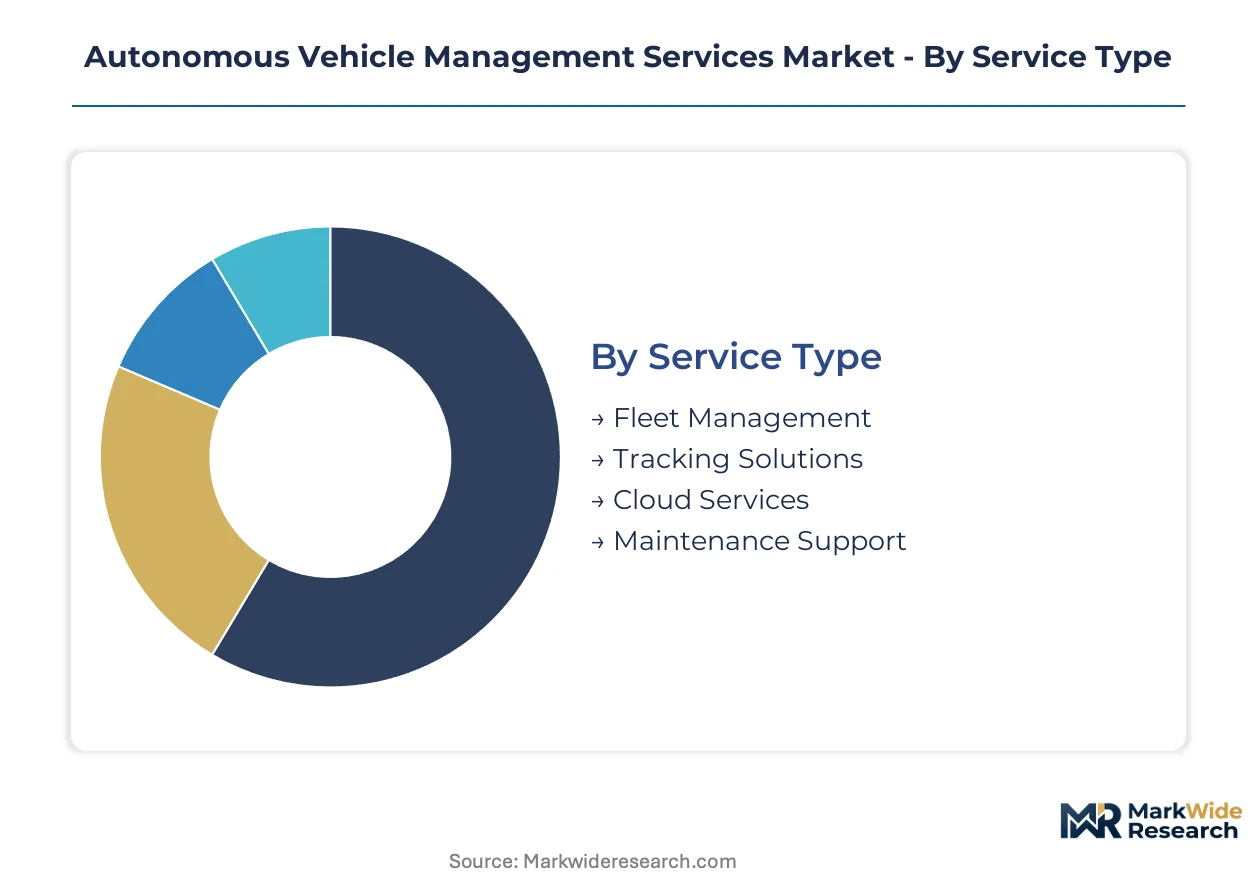
Segmentation in autonomous vehicle management services reveals how regulatory complexity fragments procurement patterns across fleet operators. Divergent compliance requirements for sensor validation, algorithmic transparency, and data sovereignty reshape vendor selection criteria by service tier and deployment architecture.
Service Type:
NHTSA guidelines, EU AI Act mandates, and MIIT standards in China each impose distinct documentation burdens that favor certain service configurations over others.
- Fleet Management:Centralized platforms coordinate vehicle dispatch, route optimization, and driver monitoring across distributed assets. Logistics providers in Germany and California prioritize these systems for dense freight corridors where regulatory scrutiny of operational logs is most intense.
- Cloud Services:Scalable infrastructure delivers over-the-air updates, telemetry storage, and predictive analytics without captive data center investment. Ride-sharing platforms expanding across multiple jurisdictions favor cloud-native architectures to satisfy data residency requirements without rebuilding core systems per market.
- Tracking Solutions:Real-time location and status monitoring for asset visibility.
- Maintenance Support:Predictive diagnostics and remote troubleshooting capabilities.
Established volume favors Fleet Management; emerging adoption favors Cloud Services.
Technology:
Cost tier differentiation separates premium sensor configurations from software-centric alternatives as operators balance redundancy requirements against capital constraints.
- AI Algorithms:Machine learning models process perception data, predict traffic patterns, and optimize routing decisions in real time. Delivery services in urban corridors deploy these capabilities most aggressively where edge-case density demands continuous learning from operational data.
- Sensor Fusion:Multi-modal integration of LiDAR, radar, and camera inputs delivers redundancy for safety-critical applications. Public transport agencies mandate this technology tier for passenger-carrying deployments where single-sensor failure modes carry unacceptable liability exposure.
- LiDAR:High-fidelity optical ranging for precise obstacle detection and mapping.
- Computer Vision:Camera-based perception systems for lane detection and object classification.
Sensor Fusion commands premium pricing in passenger transport; AI Algorithms expand most quickly in last-mile logistics.
End User:
Application-specific requirements fragment procurement around payload type, duty cycle intensity, and regulatory exposure tolerance.
- Logistics Providers:Long-haul freight operators manage high-asset-count fleets across interstate and international corridors. These customers in the United States and China drive demand for highway-optimized platforms with extended operational design domains and minimal remote operator intervention.
- Delivery Services:Last-mile operators navigate dense urban environments with frequent stops and complex pedestrian interactions. Regulatory frameworks in California and Germany accommodate these use cases through dedicated testing permits and geofenced operational approvals.
- Public Transport Agencies:Municipal and regional authorities operating fixed-route passenger services.
- Ride-Sharing Platforms:On-demand mobility providers deploying robotaxi services in designated service areas.
Logistics Providers dominate current platform revenue; Delivery Services are gaining share fastest on unit deployment velocity.
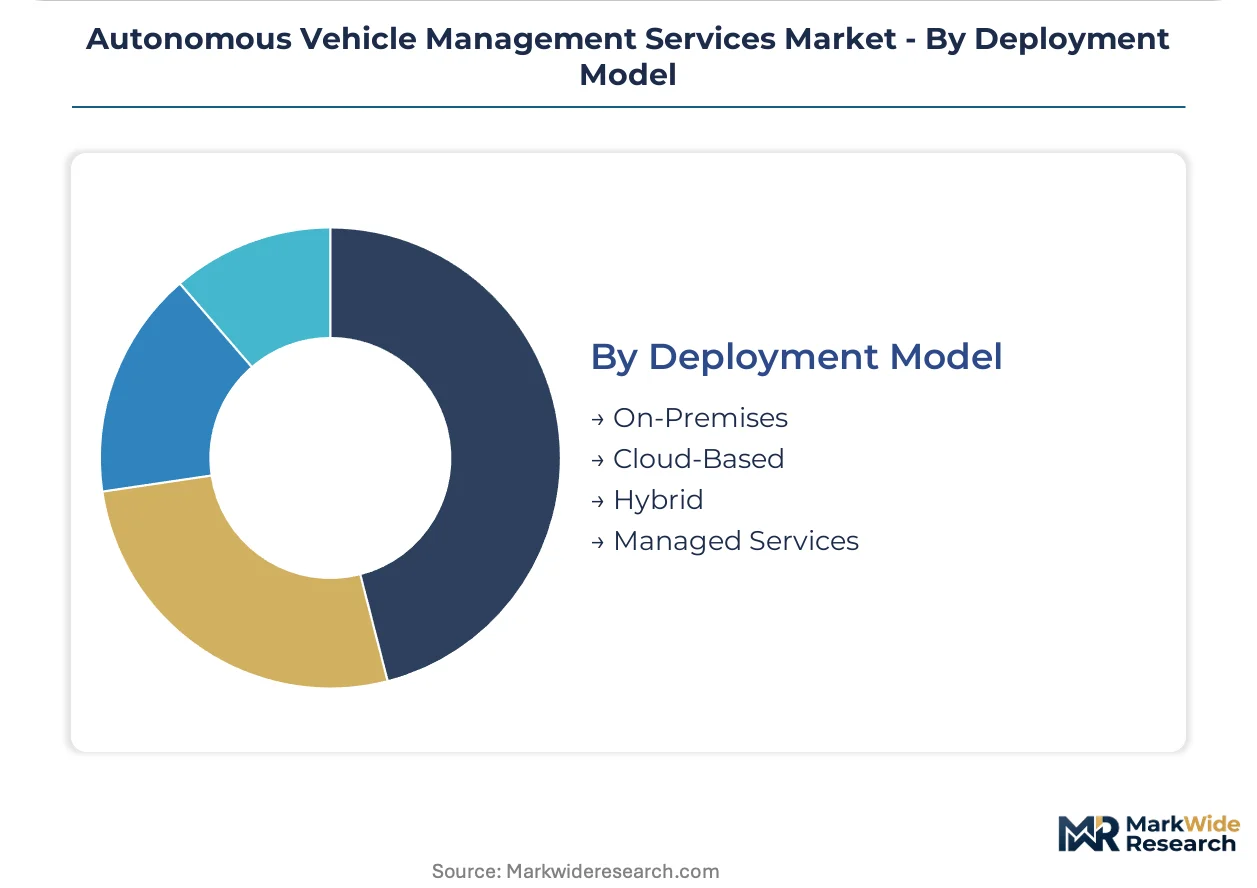
Deployment Model:
Customer type and data sovereignty priorities determine architecture selection across sovereign fleet operators and multi-tenant platform users.
- Cloud-Based:Fully managed infrastructure eliminates capital expenditure and accelerates time-to-deployment for emerging operators. Ride-sharing platforms and delivery services expanding across European markets favor this model to satisfy GDPR data processing requirements through EU-region cloud instances.
- Hybrid:Split architectures retain sensitive operational data on-premises while leveraging cloud scale for non-critical workloads. Public transport agencies in Germany and the United States adopt this configuration to maintain direct control over passenger safety records while outsourcing fleet optimization analytics.
- On-Premises:Captive infrastructure for maximum data control and air-gapped security.
- Managed Services:Outsourced operations center staffing and 24/7 monitoring support.
Cloud-Based deployments lead new customer acquisition; Hybrid architectures capture the steepest expansion trajectory among established fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in autonomous vehicle management services favor net technology exporters in North America and Asia-Pacific, while European logistics providers import platform capabilities to satisfy EU AI Act compliance mandates. Capital flows concentrate where regulatory clarity permits fleet deployment at scale.
United States
Freight corridor densification along Interstate 10 and Interstate 40 corridors drives demand for highway-optimized autonomous platforms. NHTSA exemption processes and state-level testing permits in California, Arizona, and Texas shape deployment timelines. Waymo operates commercial robotaxi services in Phoenix and San Francisco, while Aurora Innovation targets Dallas-Houston freight lanes with dedicated autonomous trucking infrastructure.
Germany
Industrial logistics clusters in Bavaria and North Rhine-Westphalia anchor European demand for fleet management platforms serving automotive and manufacturing supply chains. The EU AI Act imposes algorithmic transparency requirements that favor European-certified vendors. Stuttgart and Munich host concentrated testing zones where public transport agencies evaluate Level 4 autonomy for fixed-route passenger services.
China
Smart-city infrastructure investments in Beijing, Shanghai, and Shenzhen create integrated deployment environments for autonomous fleet operators. MIIT standards mandate data localization and cybersecurity certification for connected vehicle platforms. Baidu Apollo leverages municipal partnerships in Wuhan and Chongqing to expand robotaxi coverage across dense urban cores.
India
Long-haul freight routes between Delhi-Mumbai and Chennai-Bengaluru present underpenetrated corridors for autonomous trucking platforms. The country's national automotive regulator develops safety frameworks for commercial vehicle autonomy. Logistics parks in Gujarat and Maharashtra attract pilot programs targeting hub-to-hub container movements on dedicated highway segments.
Autonomous Vehicle Management Services Market Competitive Environment
Concentration sits with technology-integrated platform providers commanding end-to-end fleet management capabilities. The vendor base spans three tiers: vertically integrated autonomy developers, specialized fleet software vendors, and telematics incumbents extending into connected vehicle services. Strategic moves center on sensor supply partnerships and regulatory pre-certification investments to accelerate market access timelines.
Within the integrated autonomy tier, Waymo and Baidu Apollo represent divergent geographic anchoring strategies, with the former exemplifying US-centric rider-facing deployment and the latter demonstrating state-backed infrastructure integration. Aurora Innovation occupies a position among highway-focused logistics specialists targeting freight density corridors. Mobileye anchors the Tier 1 supplier archetype, providing perception hardware and software stacks to OEMs rather than operating captive fleets.
| Leading Market Players |
|---|
| Waymo |
| Cruise |
| Tesla |
| Baidu Apollo |
| Aurora Innovation |
| Mobileye |
| Pony.ai |
| Inceptio Technology |
| Zoox |
| Others |
Value Chain & Pricing Dynamics
Long-term fleet management contracts lock in both LiDAR sensor access and subscription pricing visibility for logistics operators navigating NHTSA validation timelines. These multi-year service agreements insulate autonomous fleet deployers from spot-market volatility in optical component supply while committing vendors to fixed per-vehicle software licensing rates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under ISO 26262 functional safety tiers and volume scale separate premium sensor-fusion packages from stripped-down computer-vision alternatives. Cost compression in economy-tier fleet management subscriptions is intensifying because cloud-native entrants are undercutting legacy telematics incumbents. Delivery services expanding across European markets exhibit highest price sensitivity, while public transport agencies in Germany accept premium positioning for passenger-safety redundancy.
Supply Chain Analysis
Strait of Malacca transit underwrites critical semiconductor and optical component flows for autonomous vehicle management platforms. High-fidelity LiDAR production concentrates in China, Germany, and the United States, with sensor fusion processors drawing from Taiwan and South Korea. Single-source vulnerability in indium phosphide substrates for long-range optical ranging creates exposure to export licensing shifts. Distribution runs through Tier 1 automotive supplier networks rather than direct OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous vehicle management services sit in early-cycle expansion as Level 4 certification pathways mature across Germany, California, and China. Freight corridor densification and EU AI Act compliance mandates are accelerating platform procurement decisions among logistics providers.
For Market Incumbents: Compound data network effects by integrating real-world testing telemetry from Phoenix and San Francisco deployments into predictive maintenance algorithms. Deepen backward integration into edge computing hardware to defend margin position against cloud-native entrants. Prioritize NHTSA pre-certification investments to compress exemption timelines.
For New Entrants and Emerging Players: Anchor in underpenetrated Indian logistics corridors between Delhi-Mumbai and Chennai-Bengaluru where autonomous trucking platforms lack established competition. Target hub-to-hub container movements in Gujarat and Maharashtra with battery-electric autonomous fleet bundles. Pursue API-native fleet management certification as a condition of carrier qualification with large retail distributors.
For Investors and Strategic Acquirers: Highway-focused logistics specialists with captive LiDAR development and dedicated freight corridor partnerships represent prime acquisition targets. Long-term viability hinges on regulatory pre-clearance velocity rather than technology differentiation alone. Watch FAA Part 135 certification pathways for drone-last-mile hybrid networks as the inflection signal for multi-modal platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Supply Partnership | Secures LiDAR allocation from concentrated German and Chinese optical component vendors. |
| Regulatory Pre-Certification Investment | Accelerates NHTSA exemption timelines for commercial deployment in California and Texas corridors. |
| Cloud-Native Platform Migration | Satisfies GDPR data residency requirements for European ride-sharing expansion. |
| Edge Computing Infrastructure Deployment | Reduces latency for safety-critical maneuvers in urban delivery applications. |
| Multi-Modal Service Architecture | Integrates FAA Part 135 drone certification with ground-based autonomous fleet management. |
Study Parameters
A standing panel of fleet operations directors, autonomous vehicle safety engineers, logistics procurement leads, and regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with platform developers and secondary validation against SEC filings, NHTSA exemption dockets, EU AI Act implementation guidance, and MIIT connected vehicle standards anchored data integrity. Bottom-up deployment counts triangulated against top-down addressable fleet estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, technology tier, end-user application, and deployment architecture alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with freight corridor densification rates and algorithmic transparency compliance timelines serving as key forecast inputs.
Underlying assumptions cover NHTSA exemption approval velocity, EU AI Act implementation consistency, and LiDAR sensor cost trajectories, with deviation risk concentrated in regulatory timeline extensions and single-source component supply disruptions. Practitioners should keep alternative scenarios live as autonomous liability frameworks and remote operator staffing requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
China Autonomous Navigation Market