
 North America Automotive Heat Shield Market | 2026-2036
North America Automotive Heat Shield Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Heat Shield Market Intelligence
IATF 16949 certification is collapsing the supplier base as Tier-1 and Tier-2 manufacturers face escalating audit costs and documentation burdens. Dana Incorporated leverages its vertically integrated aluminum supply chain to sustain cost advantages across exhaust shield programs. Tenneco Inc. anchors its position through specialized turbocharger heat shield engineering for performance powertrains.
Automotive heat shields are engineered thermal barriers, typically fabricated from aluminum alloys, stainless steel, or ceramic-fiber composites, designed to maintain operational temperatures within specified ranges and protect adjacent components from radiant and conductive heat transfer in vehicle powertrain and exhaust systems. The metallic product category dominates current production volumes due to established stamping infrastructure and recyclability, while composite formulations are capturing expanded share in electric vehicle battery pack protection where weight reduction intersects with thermal runaway containment requirements. Engine application segments retain the largest installed base, though turbocharger shielding exhibits the fastest structural growth as downsized boosted powertrains proliferate across passenger and commercial vehicle portfolios.
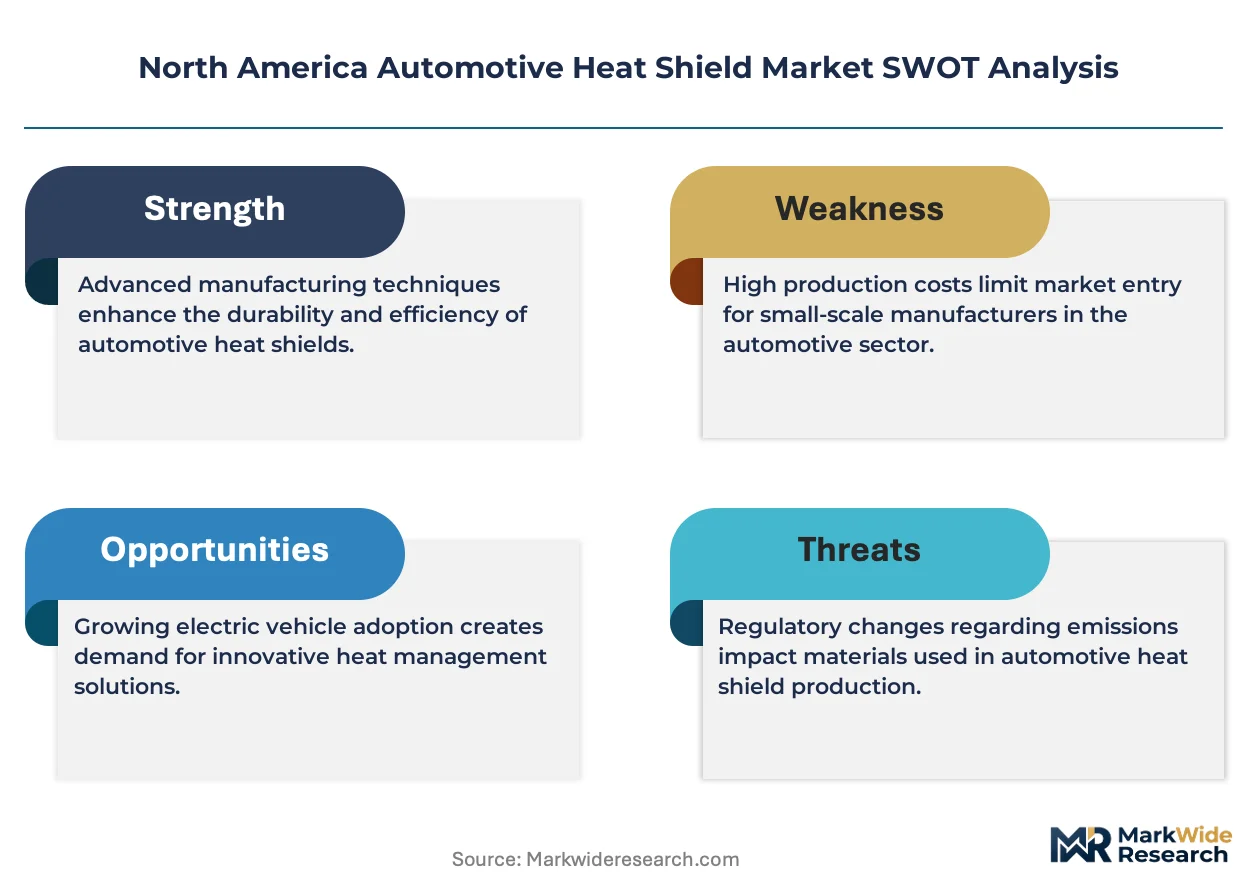
EPA tailpipe emissions standards and NHTSA Corporate Average Fuel Economy regulations are compelling heat shield manufacturers to certify materials for higher continuous operating temperatures and reduced mass. The US Department of Transportation's vehicle safety protocols additionally mandate specific flame-resistance performance for underhood components. Stakeholders must monitor evolving EV thermal management architectures, as battery electric platforms redefine heat load distribution and eliminate traditional exhaust-system shielding demand while creating new protection requirements for power electronics and high-voltage cabling.
Market Dynamics
The transition to battery electric platforms is fundamentally restructuring thermal protection demand, eliminating exhaust-system shielding while creating new specifications for power electronics and high-voltage cabling protection across US and Canadian assembly plants.
Growth Catalysts
- EPA Tier 3 Emissions Standards:These regulations mandate tighter particulate control and higher exhaust temperatures, forcing OEMs to specify advanced ceramic-composite shields for gasoline particulate filters and close-coupled catalysts.
- Turbocharger Proliferation:Downsized boosted powertrains now dominate light-truck and SUV segments, multiplying heat shield count per vehicle and expanding the addressable hardware base.
- Alabama-Tennessee-South Carolina Manufacturing Corridor:Concentrated OEM and Tier-1 investment across this southeastern cluster creates localized demand density and just-in-time supply requirements.
Market Restraints
- Aluminum Price Volatility:Primary aluminum input costs fluctuate with LME trading patterns and energy pricing, compressing margin stability for stamped-metal shield producers.
- IATF 16949 Audit Burden:Escalating documentation and third-party certification costs are forcing smaller Tier-2 suppliers to exit, reducing competitive diversity.
- Stainless Steel Substitution Pressure:Ferritic stainless grades compete for underbody exhaust applications where corrosion resistance requirements are moderate.
Strategic Opportunities
- Mexico Nearshoring Expansion:OEM capacity additions in Aguascalientes and Guanajuato create demand for localized heat shield fabrication and assembly.
- Battery Pack Thermal Runaway Containment:EV cell-to-pack architectures require engineered barriers between modules, opening composite shield applications absent in conventional powertrains.
- US Inflation Reduction Act Domestic Content:Battery and EV assembly incentives are pulling shield sourcing into North American supply chains to satisfy assembly qualification thresholds.
Industry Challenges
- CAE Simulation Talent Scarcity:Thermal modeling for multi-physics battery pack protection requires specialized finite-element expertise that outpaces current workforce development.
- Dual-Platform Tooling Complexity:Suppliers must simultaneously serve ICE exhaust programs and EV battery architectures without duplicating capital equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Heat Shield Market |
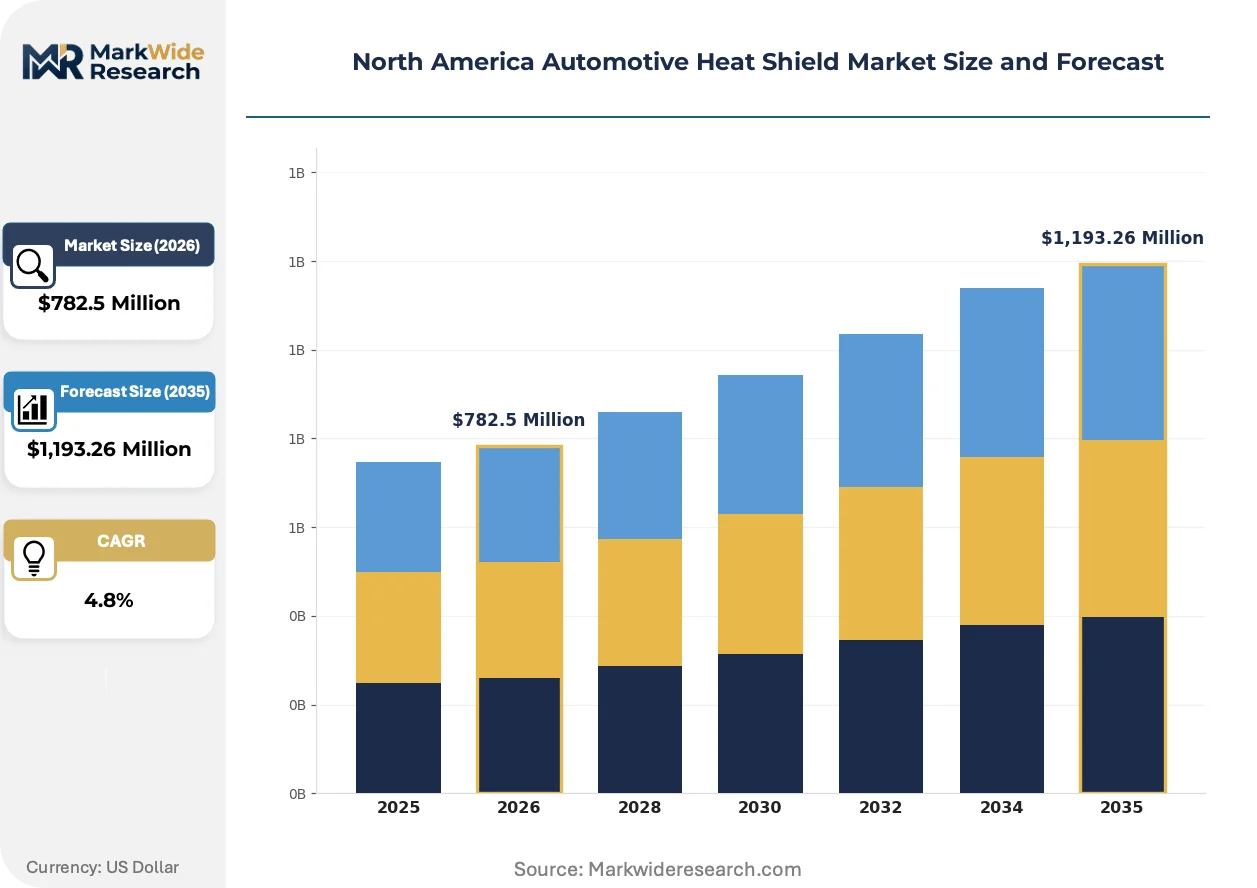
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,193.26 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
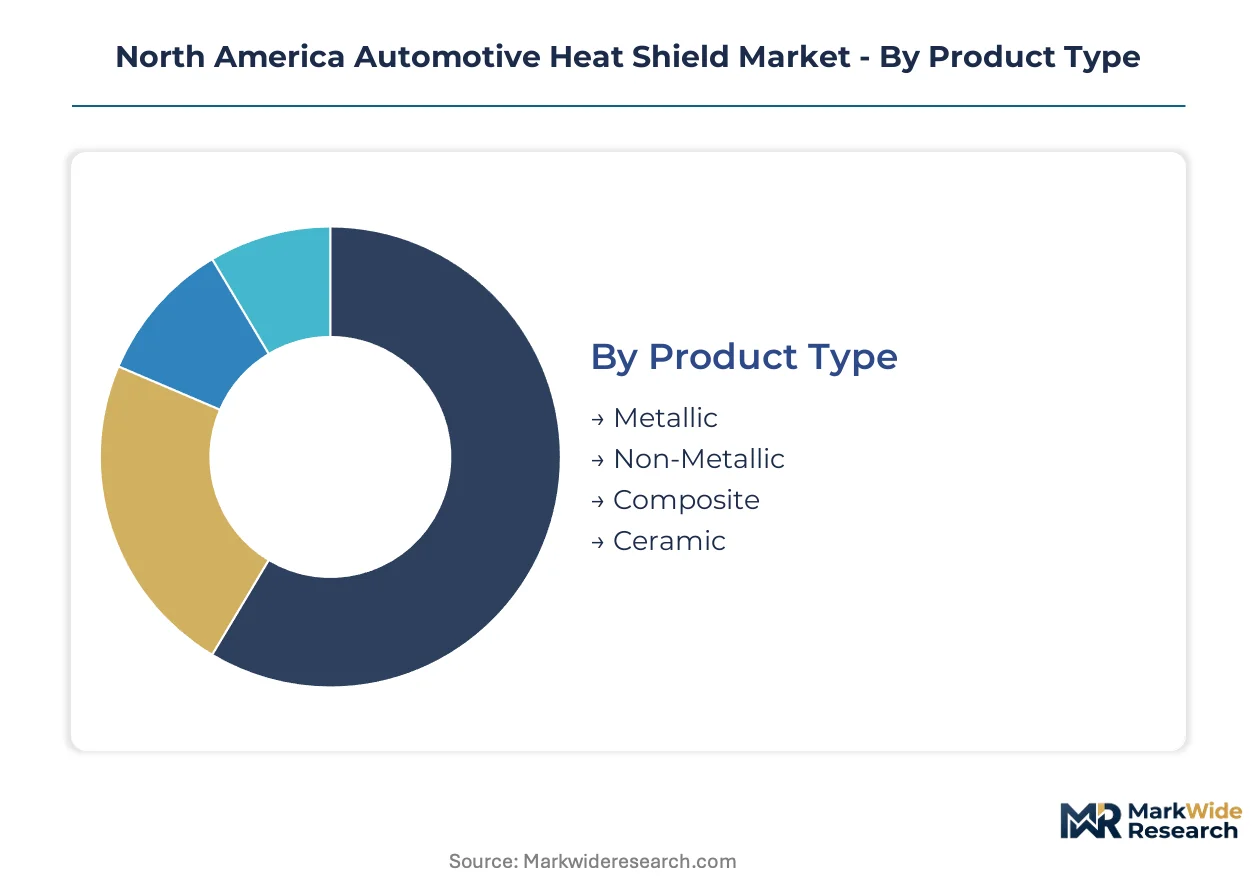
| Segmentation | Product Type: Metallic, Non-Metallic, Composite, Ceramic Application: Engine, Exhaust, Turbocharger, Transmission End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Heavy-Duty Trucks Material: Aluminum, Stainless Steel, Fiberglass, Thermoplastics |
| Companies Covered | Dana Incorporated, Tenneco Inc., ElringKlinger AG, Autoneum Holding AG, BorgWarner Corp., Parker Hannifin Corporation, Alkegen, Morgan Advanced Materials, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Heat Shield Market Strategic Shifts & Innovations
Material science advances and regulatory temperature requirements are accelerating specification changes across the supplier base, with lightweight composites gaining traction in applications once reserved for stamped metals.
Mica-paper and aerogel-composite laminates are supplanting traditional aluminum-steel bimetallic shields in battery pack applications. EV manufacturers in Michigan and California are specifying these materials for cell-to-cell barriers. The shift is compressing unit volumes for conventional stamping while expanding addressable content per vehicle in electric platforms.
NHTSA fuel economy rules and EPA greenhouse gas standards are tightening continuously. These frameworks now require heat shield mass reduction to contribute toward fleet-wide compliance. Turbocharger and underbody shielding categories face the most aggressive lightweighting mandates, driving specification reviews at Ford, GM, and Stellantis powertrain divisions.
Automakers are consolidating supplier relationships around full-system thermal management responsibility rather than component-level procurement. Tier-1 integrators in the US Southeast are absorbing heat shield specification authority previously held by exhaust system suppliers. This consolidation is most visible in Tennessee and South Carolina, where OEM technical centers are co-locating thermal engineers with preferred module suppliers.
North America Automotive Heat Shield Market Segmentation
Heat shield specification in North America fragments across material chemistry, thermal load severity, and powertrain architecture. Procurement teams at OEMs and Tier-1 integrators segment sourcing strategies to align with IATF 16949 certification tiers and EPA emissions compliance pathways.
Product Type:
EPA Tier 3 temperature mandates and NHTSA mass reduction rules differentiate shield categories by certification burden and thermal performance thresholds.
- Metallic:Stamped aluminum and stainless steel alloys dominate exhaust manifold and catalytic converter applications. Established stamping infrastructure across Tennessee and Alabama sustains cost competitiveness for high-volume ICE programs.
- Non-Metallic:Mica-paper and ceramic-fiber formulations address battery pack cell-to-cell barriers in Michigan and California EV assembly plants. These materials satisfy thermal runaway containment specifications absent in conventional powertrain shielding.
- Composite:Multi-layer laminates combining metallic foils with insulating cores serve turbocharger housings where space constraints limit single-material solutions.
- Ceramic:Rigid ceramic shields protect gasoline particulate filters and close-coupled catalysts from exhaust temperatures exceeding metallic material limits.
Established volume favors Metallic; emerging adoption favors Non-Metallic.
Application:
Cost tiering separates commodity exhaust shielding from engineered turbocharger and battery thermal management solutions.
- Engine:Underhood barriers manage radiant heat from cylinder heads and exhaust manifolds. Ford and GM powertrain divisions specify these shields across light-truck portfolios manufactured in Kentucky and Texas.
- Exhaust:Conventional underbody and tunnel shields protect floor pans and fuel lines from catalytic converter heat. This segment faces demand erosion as EV platforms eliminate exhaust systems entirely.
- Turbocharger:Downsized boosted powertrains multiply shield count per vehicle. Stellantis and GM specify specialized multi-layer shields for compressor and turbine housings in SUV and light-truck segments.
- Transmission:Tunnel-mounted shields protect cabin compartments from transmission tunnel heat loads in rear-wheel-drive and all-wheel-drive architectures.
Legacy volume concentrates in Engine; steepest expansion trajectory appears in Turbocharger.
End User:
Customer type determines thermal management architecture complexity and supplier qualification requirements.
- Passenger Vehicles:Sedan and crossover segments drive standardized exhaust shielding volumes with moderate customization requirements.
- Commercial Vehicles:Fleet operators prioritize durability and serviceability in Class 3-6 truck applications across the US Southeast manufacturing corridor.
- Electric Vehicles:Battery pack, power electronics, and high-voltage cabling protection create entirely new shielding categories absent from ICE thermal load maps. California and Michigan OEMs specify these aggressively.
- Heavy-Duty Trucks:Class 8 long-haul applications demand extreme-duty exhaust and aftertreatment shielding for EPA-compliant diesel powertrains.
Current revenue anchors in Passenger Vehicles; technology investment flows toward Electric Vehicles.
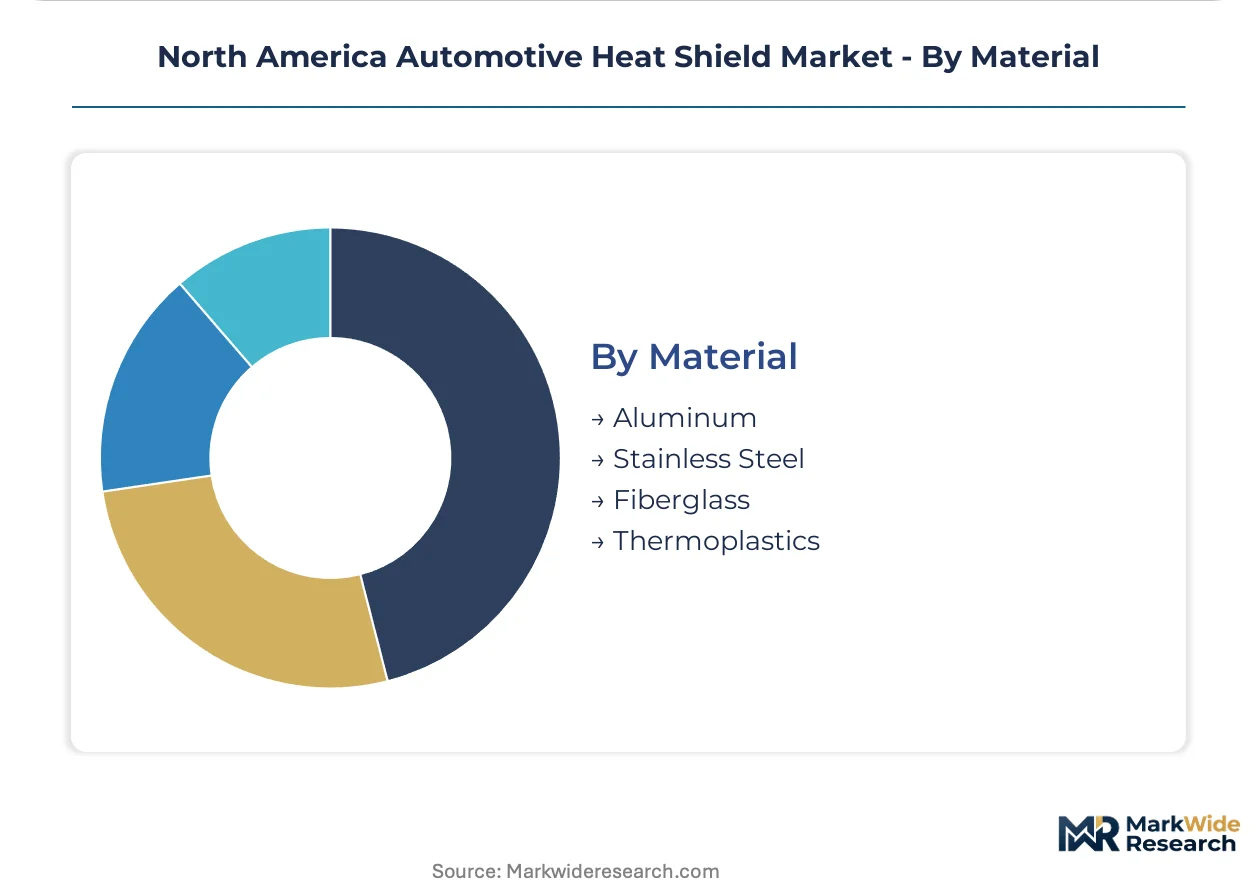
Material:
Supply concentration and LME pricing volatility shape material selection economics across the supplier base.
- Aluminum:Primary grades and recycled alloys dominate stamped shield production. Dana Incorporated leverages captive aluminum supply to defend margin position against LME price swings.
- Stainless Steel:Ferritic grades compete for underbody exhaust applications where corrosion resistance requirements are moderate and cost sensitivity is acute.
- Fiberglass:Glass-fiber reinforced composites serve battery pack applications requiring electrical isolation combined with thermal insulation.
- Thermoplastics:High-temperature polymer formulations penetrate auxiliary shielding roles where metal mass reduction supports NHTSA fuel economy compliance.
Production scale favors Aluminum; specification momentum shifts toward Fiberglass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement teams concentrate in three distinct buyer archetypes: Detroit-based legacy automakers, California EV specialists, and southeastern US truck manufacturers. Each cluster drives divergent thermal management specifications across the continent.
United States
Ford and GM powertrain divisions in Michigan specify turbocharger shields for light-truck portfolios, while California EV startups demand battery pack barriers. EPA Tier 3 emissions standards and NHTSA fuel economy rules tighten material specifications nationwide. The Tennessee-Alabama-South Carolina manufacturing corridor anchors exhaust shield production for ICE programs.
Canada
Toronto-Windsor OEM technical centers influence thermal management sourcing for cross-border assembly programs. Environment and Climate Change Canada aligns vehicle emissions rules with EPA frameworks, reducing certification complexity. Ontario stamping suppliers serve Detroit automakers through integrated Great Lakes supply chains.
Mexico
Aguascalientes and Guanajuato assembly plants generate localized demand for heat shield fabrication and kitting operations. PROFEPA environmental enforcement mirrors EPA temperature and material standards for exported vehicles. Bajío Region Tier-1 investments are pulling shield suppliers south from Texas border states.
North America Automotive Heat Shield Market Key Industry Players
Player mix skews toward diversified automotive suppliers with captive thermal management divisions rather than pure-play shield specialists. Tier-1 integrators absorb specification authority previously held by exhaust system suppliers, compressing the addressable vendor base. Two archetypes dominate: vertically integrated metal formers leveraging captive aluminum supply, and materials science firms pivoting from aerospace insulation to automotive battery barriers. Competitive moves center on dual-platform tooling investments serving concurrent ICE and EV programs, plus IATF 16949 certification acquisition to qualify for OEM direct contracts.
Among North American diversified suppliers, Dana Incorporated and Tenneco Inc. exemplify the integrated-former archetype, while Morgan Advanced Materials occupies a position representing the materials-science pivot toward EV thermal barriers. ElringKlinger AG and Autoneum Holding AG sit within the European-headquartered tier that competes through acoustic-thermal module integration. These five entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Dana Incorporated |
| Tenneco Inc. |
| ElringKlinger AG |
| Autoneum Holding AG |
| BorgWarner Corp. |
| Parker Hannifin Corporation |
| Alkegen |
| Morgan Advanced Materials |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with LME-linked indexation clauses lock in aluminum supply access for Tennessee and Alabama stamping operations while capping price volatility exposure for exhaust shield programs serving Detroit automakers.
Pricing Analysis
Cost-plus agreements indexed to London Metal Exchange aluminum pricing dominate procurement between Tier-1 integrators and raw material suppliers. Price differentiation separates IATF 16949-certified Tier-1 suppliers from uncertified Tier-2 competitors, with volume scale and geographic proximity to the US Southeast manufacturing corridor as secondary tiering factors. Pricing pressure stems from ferritic stainless steel substitution in underbody applications where corrosion requirements moderate. Fleet operators in commercial vehicle segments exhibit acute price sensitivity, while EV battery pack shielding commands premium tolerance due to thermal runaway containment specifications.
Supply Chain Analysis
Inventory buffers spanning 6-8 weeks of aluminum coil stock sustain just-in-time delivery to Tennessee and South Carolina assembly plants despite LME price swings. Supply concentrates in US domestic primary aluminum smelters and Canadian rolling mills, with secondary scrap recovery feeding circular production loops. Raw material dependencies center on primary aluminum ingot, stainless steel strip, and ceramic fiber matting. Single-source vulnerability characterizes specialized mica-paper laminates for EV battery barriers. Distribution runs through Tier-1 module integrators who consolidate specification authority previously held by exhaust system suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finite-element thermal modeling expertise represents the critical capability gap constraining supplier expansion into EV battery pack protection, with CAE talent scarcity outpacing workforce development across Michigan and California technical centers.
For Market Incumbents: Secure captive aluminum supply through backward integration into rolling mill operations or long-term offtake agreements with Quebec smelters, defending margin position against LME volatility. Accelerate IATF 16949 certification acquisition for preferred supplier status as OEMs consolidate procurement around full-system thermal management responsibility rather than component-level sourcing.
For New Entrants and Emerging Players: IATF 16949 fast-track certification programs offer entry into the EV battery pack barrier segment where incumbent metal stampers lack composite materials expertise. Target Michigan and California EV assembly plants with mica-paper and aerogel-composite solutions absent from traditional exhaust shielding portfolios. Lead with cell-to-cell barrier engineering services rather than commodity hardware to bypass established stamping infrastructure advantages.
For Investors and Strategic Acquirers: Capital is best deployed toward materials science firms with aerospace insulation heritage pivoting to automotive battery thermal barriers, as these entities possess composite formulation IP absent from legacy metal formers. Long-term viability hinges on dual-platform tooling capacity serving concurrent ICE exhaust and EV battery architectures. Watch Stellantis and GM powertrain division specification shifts as the signal indicating acceleration or deceleration in turbocharger shielding demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Platform Tooling Investment | Simultaneous ICE exhaust and EV battery capacity serves Stellantis and GM through transition volatility. |
| IATF 16949 Certification Acquisition | Direct OEM contracting eligibility compresses addressable vendor base for Tennessee-Alabama-South Carolina corridor. |
| Composite Materials R&D Partnership | Mica-paper and aerogel formulations address Michigan and California EV thermal runaway specifications. |
| Mexico Nearshoring Footprint Expansion | Aguascalientes and Guanajuato assembly proximity reduces logistics cost for US-Mexico-Canada Agreement compliance. |
| Captive Aluminum Supply Integration | Quebec smelter relationships or in-house rolling defend margin against LME price swings. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering, Tier-1 procurement, and thermal management R&D functions. Primary fieldwork with exhaust system suppliers, battery pack integrators, and materials science firms was cross-referenced against EPA regulatory filings, NHTSA fuel economy rulemakings, vehicle production databases, and SEC disclosures from diversified automotive suppliers. Bottom-up segment sizing triangulated with top-down market reconstruction across metallic, non-metallic, composite, and ceramic product categories.
Across the analysis window, projections incorporated powertrain mix transitions, EPA Tier 3 temperature mandates, and NHTSA mass reduction compliance pathways. Segmentation modeling addressed material chemistry, application severity, end-user architecture, and geographic production cluster dimensions. CAGRs were derived from installed base evolution and content-per-vehicle trajectories for turbocharger, battery pack, and exhaust shielding categories. Aluminum price elasticity and IATF 16949 certification penetration curves informed scenario boundaries.
Decision-makers should treat outputs as directional under sustained EPA emissions tightening and EV adoption assumptions; material deviation in powertrain mix or regulatory enforcement would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Europe Automotive Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Headliners Market