
 Automotive Wiper Blades Market | 2026-2036
Automotive Wiper Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wiper Blades Market Outlook
ECE R48 vehicle equipment certification is redrawing competitive boundaries for wiper system suppliers. Bosch Automotive leverages captive rubber compounding and precision extrusion to sustain quality consistency across European OEM contracts. Valeo dominates integrated wiper motor and blade assemblies, while Denso anchors Asian supply relationships through just-in-sequence manufacturing footprints.
Automotive wiper blades are elastomer-based wiping assemblies mounted on pivoting arms, engineered to maintain optical clarity across windshields through oscillating contact pressures of 10-20 N/cm against glass surfaces treated with hydrophobic coatings. Beam blades with integrated spoiler geometry now lead material substitution trends as silicone compounds displace natural rubber in premium tiers, while conventional hook-type assemblies retain volume in emerging aftermarket channels where price sensitivity governs replacement behavior. Hybrid constructions occupy the mid-tier margin pool by combining metal substructure durability with aerodynamic polymer shells.
Federal Motor Vehicle Safety Standard 104 governs windshield wiping and washing systems in the United States, mandating minimum swept areas that directly determine blade length specifications and arm geometry. The European ECE R48 framework and China's GB 11555 standard enforce comparable visibility zones, creating divergent homologation requirements that fragment global product platforms. Stakeholders must monitor how EPA rubber vulcanization emission rules and REACH substance restrictions on zinc-based activators reshape compound formulations and supplier qualification timelines.
Market Dynamics
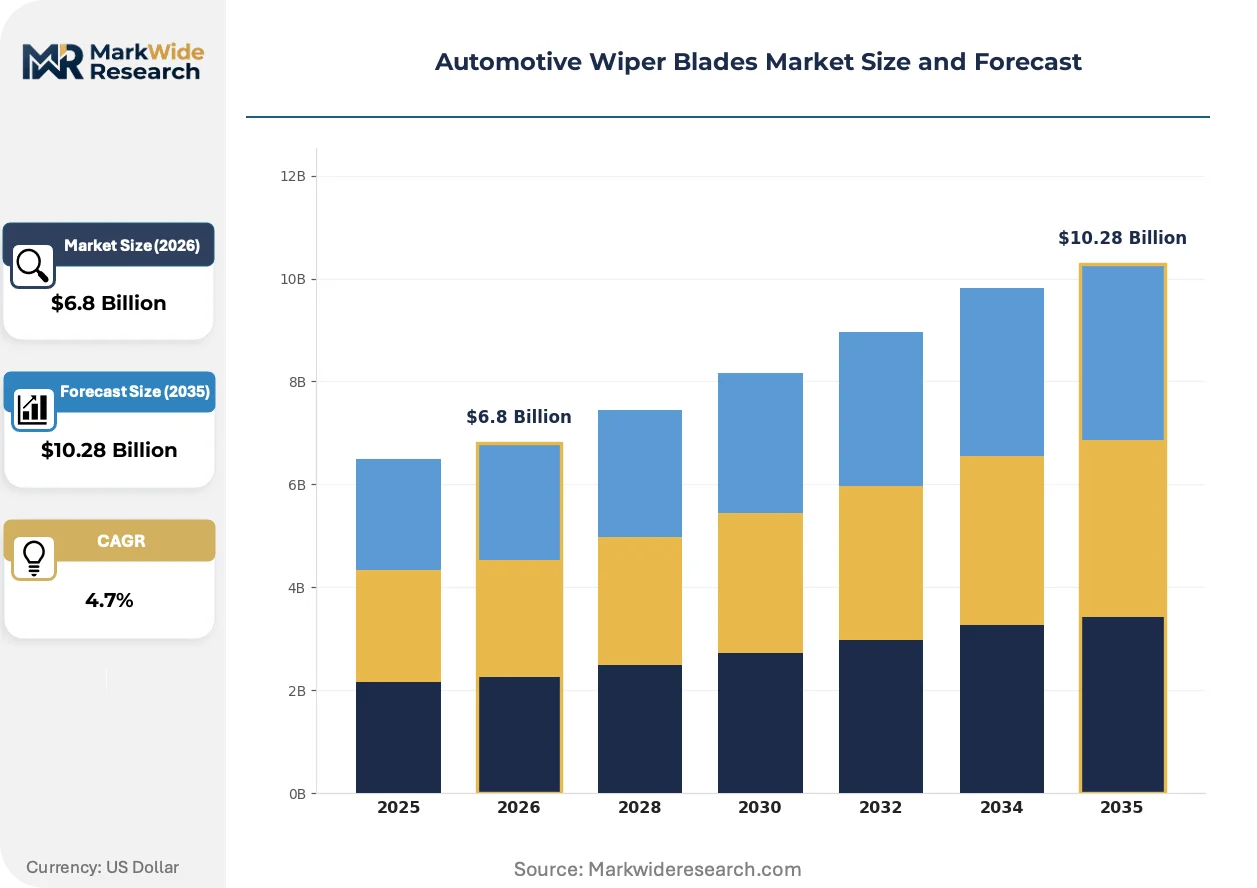
Vehicle parc aging across major economies is pulling replacement volume toward aftermarket channels while ECE R48 visibility standards tighten OEM qualification thresholds, compressing supplier margins and fragmenting global product architectures.
Growth Catalysts
- ECE R48 Certification Expansion:European visibility zone mandates now cover wiper system performance, forcing specification upgrades that sustain premium-tier demand.
- Silicone Compound Substitution:Synthetic elastomer formulations extend blade life in humid subtropical climates, accelerating replacement cycle compression in coastal China.
- India:Domestic OEM production scaling under PLI scheme incentives is absorbing integrated wiper motor-blade assemblies from localized supplier footprints.
Market Restraints
- Natural Rubber Price Volatility:Conventional hook-type blade production remains exposed to commodity swings in Southeast Asian rubber supply.
- Zinc Activator REACH Restrictions:ECHA substance limitations on vulcanization chemistry extend European supplier requalification timelines.
- Beam Blade Manufacturing Concentration:Precision extrusion capability clusters in Germany and Japan, creating single-source risk for spoiler-integrated designs.
Strategic Opportunities
- Brazil ANVISA-Aligned Local Production:Mercosur assembly plant proximity offers tariff-advantaged aftermarket access across South American vehicle parc.
- Dual Carbon Goals in China:MEE emission benchmarks favor low-VOC silicone curing processes, rewarding compound formulation shifts.
- Direct-to-Installer E-Commerce:Specialized B2B platforms bypass traditional distributor tiers in fragmented North American independent repair channels.
Industry Challenges
- Homologation Parallelism:Simultaneous FMVSS 104, ECE R48, and GB 11555 testing requirements fragment R&D bandwidth across incompatible swept-area specifications.
- Legacy Arm Interface Compatibility:Retrofit blade designs must accommodate decades of hook-type, pin-arm, and bayonet standards without inventory proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wiper Blades Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Blades, Beam Blades, Hybrid Blades, Winter Blades Material: Rubber, Silicone, Composite, Metal Vehicle Type: Sedan, SUV, Truck, Van Installation Type: Manual, Automatic, OEM, Aftermarket |
| Companies Covered | Denso, CLWIPER, TRICO, Otto Glas, Michelin, Valeo, ANCO, Scan Top, Bosch Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wiper Blades Market Strategic Shifts
Material science advances and regulatory visibility mandates are restructuring competitive advantage around compound durability and aerodynamic integration rather than arm geometry alone.
Silicone elastomer formulations with integrated hydrophobic surface activation are bifurcating the premium tier from natural rubber alternatives. Luxury OEM specifications in Germany and Japan specify these compounds for reduced noise and extended service intervals. The technology is bifurcating supplier tiers between captive compounders and commodity blade assemblers.
EPA rubber vulcanization emission rules are tightening volatile organic compound thresholds for domestic manufacturing. Compounders must retool curing processes or absorb carbon offset costs. California-based suppliers face the earliest compliance deadlines, compressing qualification windows for new formulations.
Buyer concentration among multi-brand service chains is consolidating aftermarket procurement around private-label programs. Independent distributors lose shelf space to vertically integrated garage networks. This pattern is most visible in Australia's TGA-aligned vehicle service sector, where national chains now specify direct-supply blade contracts.
Automotive Wiper Blades Market Segmentation
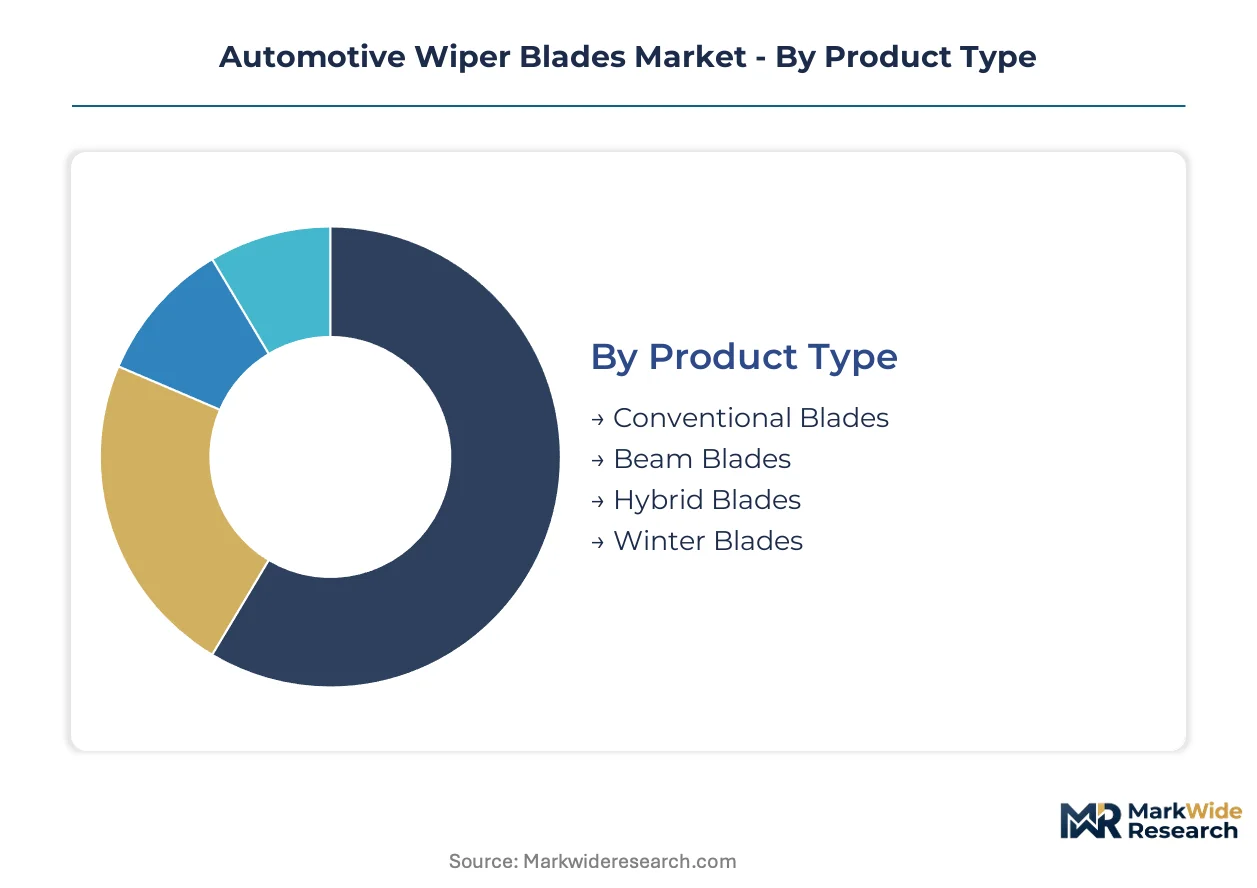
Wiper blade segmentation reveals divergent supply chain architectures across product tiers. Material chemistry and installation channel determine margin capture, while vehicle parc aging redirects volume toward replacement-oriented segments.
Product Type:
Domestic production concentrates on conventional hook-type assemblies for emerging market aftermarket, while beam blade exports flow from German and Japanese precision extrusion clusters.
- Conventional Blades:Metal-framed assemblies with replaceable rubber inserts dominate price-sensitive replacement cycles in India's independent repair channels. Hook-type interfaces accommodate decades of legacy arm standards without inventory proliferation.
- Beam Blades:Integrated spoiler geometry and silicone compounds command premium OEM specifications from German luxury manufacturers. Precision extrusion capability clusters in Stuttgart and Nagoya create single-source supply risk for aerodynamic designs.
- Hybrid Blades:Metal substructures with polymer aerodynamic shells occupy mid-tier margin pools in China's humid subtropical climates.
- Winter Blades:Enclosed-frame designs with enhanced ice-shedding geometry serve Nordic vehicle parc in Sweden and Finland.
Conventional blades hold the largest share; momentum sits with beam blade expansion.
Material:
Cost tiers separate captive compounders from commodity assemblers, with synthetic formulations capturing premium pricing and natural rubber retaining volume scale.
- Rubber:Natural elastomer formulations remain exposed to Southeast Asian commodity swings, anchoring economy-tier production in Thailand and Indonesia.
- Silicone:Synthetic compounds with hydrophobic surface activation extend service intervals in coastal China and Japan, bifurcating supplier tiers between integrated compounders and blade assemblers.
- Composite:Multi-layer constructions blending rubber cores with silicone outer surfaces bridge performance tiers in South Korean OEM supply.
- Metal:Stainless steel substructures provide frame durability for heavy-duty truck applications in Australian mining corridors.
Rubber dominates volume; silicone gains share fastest in premium channels.
Vehicle Type:
Application requirements scale blade length and arm pressure specifications, with commercial segments demanding reinforced construction.
- Sedan:Standard swept-area specifications under FMVSS 104 and ECE R48 govern blade lengths from 16 to 26 inches across passenger car parc.
- SUV:Elevated windshield profiles require longer blade assemblies with enhanced aerodynamic stability at highway speeds.
- Truck:Heavy-duty arm geometries and reinforced rubber compounds withstand 10-20 N/cm contact pressures across commercial fleets.
- Van:Flat windshield angles in commercial delivery vehicles prioritize uniform wiping distribution over aerodynamic integration.
Sedan applications anchor replacement volume; SUV specifications show steepest expansion trajectory.
Installation Type:
Customer type determines procurement channel structure, with independent repair networks fragmenting demand and OEM contracts consolidating specification control.
- Manual:Consumer-replaceable hook-type designs dominate North American auto parts retail, where DIY installation persists in aging vehicle parc.
- Automatic:Integrated rain-sensor systems with motor-blade assemblies anchor luxury OEM contracts in Germany and Japan.
- OEM:Just-in-sequence manufacturing footprints in China and India supply domestic production lines under PLI scheme incentives.
- Aftermarket:Multi-brand service chains in Australia consolidate procurement around private-label programs, displacing independent distributors.
Aftermarket channels absorb the largest volume; OEM specifications command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and dual carbon benchmarks in China are redirecting supplier investments toward localized manufacturing footprints. ECE R48 visibility mandates in Europe and FMVSS 104 specifications in North America fragment homologation requirements across incompatible swept-area standards. Supplier qualification timelines compress as regional regulators tighten compound formulation rules.
China
Domestic OEM production scaling absorbs integrated wiper motor-blade assemblies from localized supplier footprints. MEE emission benchmarks favor low-VOC silicone curing processes, rewarding compound formulation shifts. The Yangtze River Delta hosts precision extrusion clusters serving humid subtropical replacement cycles.
Germany
Luxury OEM specifications specify silicone compounds for reduced noise and extended service intervals. ECE R48 certification redrawing competitive boundaries forces specification upgrades that sustain premium-tier demand. Stuttgart anchors captive rubber compounding and precision extrusion capability for spoiler-integrated beam designs.
United States
FMVSS 104 swept-area mandates directly determine blade length specifications and arm geometry for domestic vehicle parc. EPA rubber vulcanization emission rules tighten volatile organic compound thresholds for domestic manufacturing. California-based suppliers face earliest compliance deadlines, compressing qualification windows.
India
Domestic OEM production scaling under PLI scheme incentives absorbs integrated wiper motor-blade assemblies. BIS standards govern product safety thresholds for localized supply relationships. Tamil Nadu and Gujarat host just-in-sequence manufacturing footprints serving domestic production lines.
Brazil
Mercosur assembly plant proximity offers tariff-advantaged aftermarket access across South American vehicle parc. ANVISA-aligned local production requirements shape supplier qualification protocols. São Paulo state concentrates distribution infrastructure for regional replacement volume.
Automotive Wiper Blades Market Competitive Environment
Player mix skews toward diversified automotive suppliers with captive compound capabilities and specialized blade assemblers serving fragmented aftermarket channels. Tiered competitive structure separates integrated system suppliers from commodity hook-type producers. Strategic archetypes include captive compounders with precision extrusion, integrated motor-blade assemblers, and private-label distributors. Dominant competitive moves center on backward integration into rubber compounding and geographic expansion through localized manufacturing footprints.
Within the diversified automotive supplier tier, Bosch Automotive and Valeo exemplify integrated system capabilities spanning compound formulation through finished blade assembly. Denso anchors Asian supply relationships through manufacturing presence in key production regions. Among specialized aftermarket suppliers, TRICO and ANCO occupy positions serving replacement cycle demand across legacy vehicle parc. CLWIPER represents the Chinese domestic supplier archetype scaling under localized production incentives.
| Leading Market Players |
|---|
| Denso |
| CLWIPER |
| TRICO |
| Otto Glas |
| Michelin |
| Valeo |
| ANCO |
| Scan Top |
| Bosch Automotive |
| Others |
Value Chain & Pricing Dynamics
ECE R48 certification gates both supplier qualification timelines and price tier separation simultaneously, forcing compound reformulation costs onto European manufacturers while OEMs extract specification premiums from certified tiers. Natural rubber commodity swings and REACH substance restrictions on zinc activators compress margin pools for uncertified assemblers.
Pricing Analysis
Certification level creates the primary spread between premium silicone formulations and economy natural rubber alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ECE R48 compliance status, with luxury OEM contracts commanding specification premiums for extended-service-interval compounds. Cost compression in the economy tier intensifies because Southeast Asian rubber price volatility feeds directly into hook-type blade production. Independent repair channels in India exhibit highest price sensitivity, while German luxury OEMs show lowest sensitivity due to bundled service interval positioning.
Supply Chain Analysis
Just-in-sequence manufacturing dominates OEM supply relationships, while aftermarket channels favor strategic stockpiling of legacy hook-type inventory to accommodate decades of arm interface standards. Precision extrusion capability clusters in Germany, Japan, and China's Yangtze River Delta, with beam blade production drawing from captive rubber compounding in Stuttgart and Nagoya. Raw material dependencies rest on Southeast Asian natural rubber, German silicone polymer feedstocks, and Japanese precision steel for spoiler substructures. Single-source vulnerability concentrates in aerodynamic beam extrusion equipment. Distribution runs through multi-brand service chains consolidating private-label procurement in Australia and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting around rain-sensor integration standards, with interoperability between blade assemblies and motor-control modules reshaping supplier value capture.
For Market Incumbents: Fortify backward integration into silicone compounding to offset REACH restriction impacts on zinc-based vulcanization chemistry. Add precision extrusion capacity in China's Yangtze River Delta to defend against localized supplier scaling under MEE emission benchmarks. Channel control through direct-to-installer B2B platforms protects margin position from distributor displacement.
For New Entrants and Emerging Players: Lead with low-VOC silicone curing process specialization targeting China's dual carbon compliance deadlines. Brazil's ANVISA-aligned local production requirements present the most penetrable geographic entry point for Mercosur aftermarket access. A private-label supply contract with Australia's consolidating national service chains offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across beam blade manufacturing as precision extrusion equipment becomes more modular. Long-term viability favors compounders with captive silicone formulation capabilities over pure-play blade assemblers. Acquisition targets should show integrated motor-blade assembly relationships with domestic OEMs in India or China. The signal to watch is PLI scheme incentive renewal timelines for localized supplier qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | REACH compliance on zinc activators favors captive formulation control over outsourced supply. |
| Precision Extrusion Capacity Expansion | Yangtze River Delta clustering supports humid subtropical replacement cycle compression. |
| Rain-Sensor System Interoperability Investment | German and Japanese luxury OEM specifications reward integrated motor-blade module suppliers. |
| Direct-to-Installer E-Commerce Platform Launch | North American independent repair channel fragmentation enables distributor bypass. |
| ANVISA-Aligned Local Production Footprint | Mercosur tariff advantages capture South American vehicle parc aging replacement volume. |
Study Parameters
Desk research of vehicle production databases, customs and trade flow records, and regulatory filing repositories preceded structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution channel heads, and dealership operations managers. Primary fieldwork across Germany, China, India, and the United States validated secondary data on compound formulation shifts and certification timelines. Bottom-up triangulation of replacement cycle frequencies and top-down reconciliation with vehicle parc aging curves anchored volume estimates.
Variance decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type tier, material chemistry grade, vehicle class application, and installation channel structure. CAGRs derived from fitted growth curves incorporating ECE R48 adoption trajectories and PLI scheme incentive phase-ins. Industry-specific forecast inputs encompassed natural rubber futures volatility indices and MEE emission benchmark compliance deadlines.
The analysis sits within stated boundaries; outcomes outside sustained OEM production scaling in China and India or accelerated REACH substance restriction enforcement would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle compression rates and regional regulatory adoption timelines. Revision becomes warranted when natural rubber price volatility crosses threshold levels that trigger formulation substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automobile Accessories Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive Connecting Rod Bearing Market