
 Global Automotive on Board AC-DC Power Inverters Market | 2026-2036
Global Automotive on Board AC-DC Power Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive on Board AC-DC Power Inverters Market Analysis
Commercial fleet electrification is hardening as the dominant demand vector for automotive onboard AC-DC power inverters. Eaton Corporation leverages its power distribution heritage to anchor high-voltage inverter architectures for heavy-duty platforms. Sensata Technologies, Inc. specializes in sensor-integrated power modules that extend thermal management precision across electric drivetrains. Continental AG dominates European OEM supply relationships through its captive semiconductor sourcing and in-house production of switching transistor arrays.
Automotive onboard AC-DC power inverters convert direct current from vehicle batteries into alternating current for auxiliary loads, typically operating at switching frequencies between 20 kHz and 100 kHz with efficiency targets exceeding 95 percent to minimize thermal dissipation in confined engine bays. Pure Sine Wave inverters command premium positioning among OEMs due to compatibility with sensitive medical and computing equipment installed in commercial ambulances and mobile command units. Auxiliary Power Units represent the fastest-growing application segment as refrigerated delivery trucks and construction equipment adopt electric climate control independent of main drivetrain status.
FCC electromagnetic interference standards in the United States, ECE R10 automotive EMC regulations across Europe, and China's GB/T standards for electric vehicle power electronics collectively constrain inverter topology designs and filter component selection. The EPA's Phase 3 greenhouse gas rules for heavy-duty vehicles indirectly amplify inverter demand by expanding electrically driven auxiliary systems that displace mechanical belt drives. Stakeholders must monitor evolving semiconductor export controls and rare earth magnet supply constraints that threaten inductor and transformer cost structures.
Market Dynamics
Commercial fleet electrification is compressing inverter procurement cycles as refrigerated logistics operators and construction equipment manufacturers demand auxiliary power units independent of main drivetrain operation. This demand vector is forcing power electronics suppliers to reconfigure thermal architectures for continuous-duty cycles in confined engine bays.
Growth Catalysts
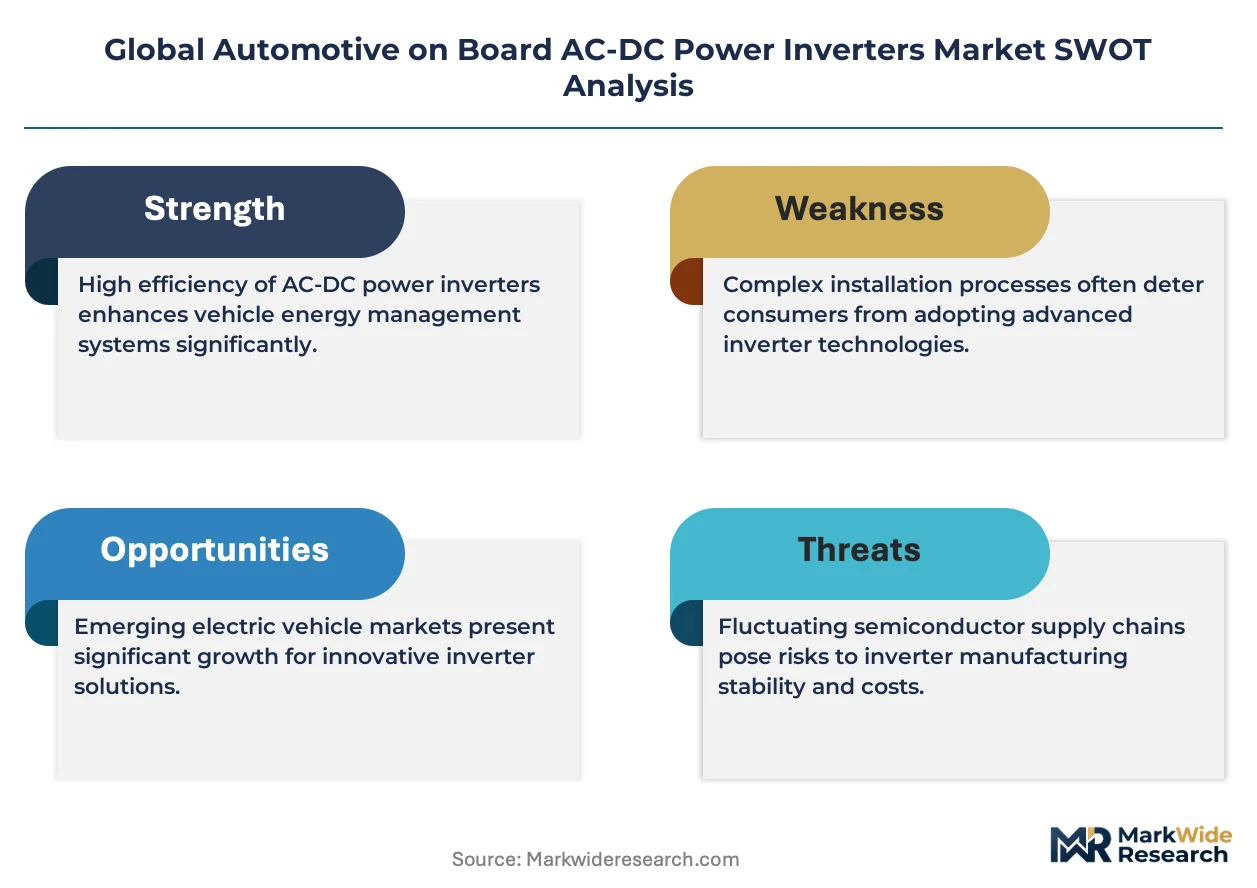
- China's MIIT efficiency mandates:The Ministry of Industry and Information Technology's tightening conversion loss thresholds are compelling domestic EV manufacturers to upgrade from modified sine wave to pure sine wave inverter topologies across heavy-duty platforms.
- Refrigerated delivery electrification:Cold-chain logistics operators in Germany's automotive engineering corridor are retrofitting diesel auxiliary power units with battery-driven electric climate systems requiring high-efficiency AC-DC conversion.
- Silicon carbide MOSFET adoption:Wide-bandgap semiconductor switching devices are enabling inverter designs that slash thermal dissipation by 40 percent compared to legacy IGBT architectures, permitting higher power density in confined installations.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing facilities is inflating inductor and transformer cost structures, compressing margin recovery for European and North American inverter assemblers.
- Semiconductor export control friction:US Bureau of Industry and Security restrictions on advanced node fabrication equipment are extending lead times for automotive-grade power management integrated circuits sourced from Taiwanese foundries.
- Electromagnetic compatibility certification complexity:Simultaneous compliance with FCC Part 15, ECE R10, and China's GB/T 18655 standards is forcing redundant filter component sets that add 12-18 percent to bill-of-material costs.
Strategic Opportunities
- India's PLI scheme for auto components:The Production Linked Incentive program's 18 percent subsidy tier for advanced automotive electronics is attracting inverter module assembly investments in Tamil Nadu and Gujarat manufacturing corridors.
- Vehicle-to-load bidirectional architectures:Integration of onboard inverters with external AC power export capability is creating new revenue streams for OEMs serving mobile command units and emergency response vehicle operators.
- Japan's METI carbon neutrality roadmap:The Ministry of Economy, Trade and Industry's 2035 ICE sales prohibition is accelerating development of integrated power electronics platforms that consolidate inverter, charger, and DC-DC functions.
Industry Challenges
- Power electronics engineering talent scarcity:Shortage of specialists competent in magnetics design, thermal simulation, and EMI mitigation is extending product development cycles by 8-14 months for mid-tier suppliers.
- Legacy 12V electrical system integration:Maintaining backward compatibility with conventional auxiliary loads while delivering 400V-800V high-voltage conversion is multiplying software validation burdens and warranty exposure.
- Automotive safety integrity certification:ISO 26262 ASIL-D compliance for inverter control systems requires fault-tolerant architectures that demand 30-40 percent additional semiconductor content.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive on Board AC-DC Power Inverters Market |
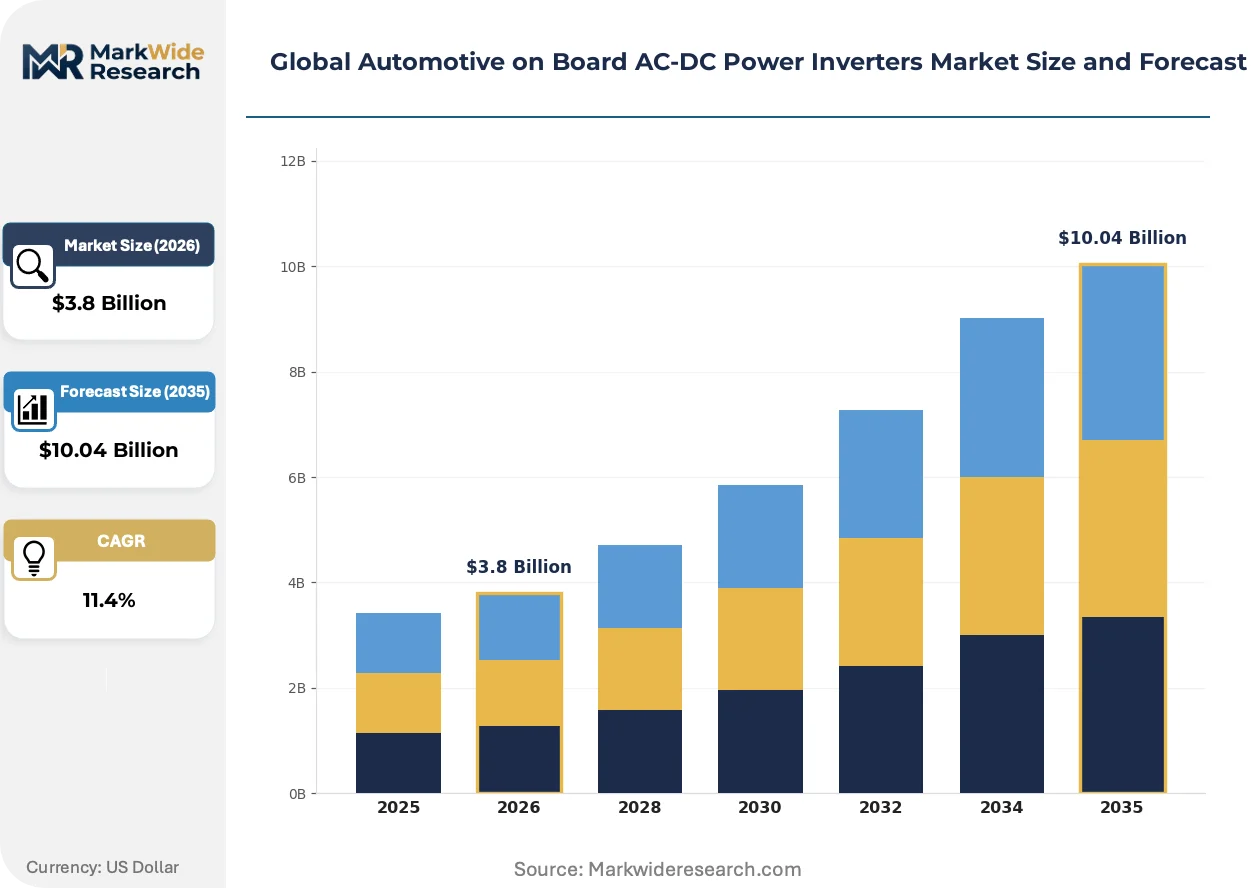
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Sine Wave, Pure Sine Wave, High-Frequency, Low-Frequency Application: Electric Vehicles, Start-Stop Systems, Auxiliary Power Units, Renewable Energy Systems Component: Switching Transistors, Capacitors, Inductors, Transformers End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Eaton Corporation, Calsonic Kansei Corporation, Sensata Technologies, Inc., Koninklijke Philips N.V., Toshiba Electronic Devices & Storage Corporation, Continental AG, Lear Corporation, Delta Electronics, Inc., Samlex America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive on Board AC-DC Power Inverters Market Emerging Trajectories
Gallium nitride and silicon carbide wide-bandgap semiconductors are rewriting thermal and efficiency constraints across automotive power electronics. These material transitions are enabling packaging densities that were physically unattainable with silicon IGBT predecessors.
Silicon carbide MOSFETs enable switching frequencies above 100 kHz with sub-50 nanosecond rise times, collapsing magnetic component volumes by 60 percent. Commercial ambulance manufacturers in Michigan's electrified vehicle supply chain are adopting these devices for mobile medical equipment power conditioning. This frequency capability is converging with integrated magnetics design to eliminate discrete inductor arrays in next-generation auxiliary power units.
Europe's Ecodesign for Energy-Related Products Directive is mandating minimum 96 percent conversion efficiency for onboard power electronics above 3 kW rated output. The regulation is disqualifying legacy hard-switched topologies from new vehicle type approvals. German OEM supply relationships are restructuring around suppliers capable of delivering soft-switching resonant converter architectures with documented efficiency certification.
Fleet operators are consolidating inverter procurement through direct OEM specification rather than aftermarket channel distribution. Refrigerated logistics providers in China's Yangtze River Delta EV cluster are negotiating multi-year supply agreements that embed power electronics within complete electric climate system packages. This bundling pattern is most visible in heavy-duty platforms where auxiliary load power quality directly affects cargo integrity compliance.
Global Automotive on Board AC-DC Power Inverters Market Segmentation
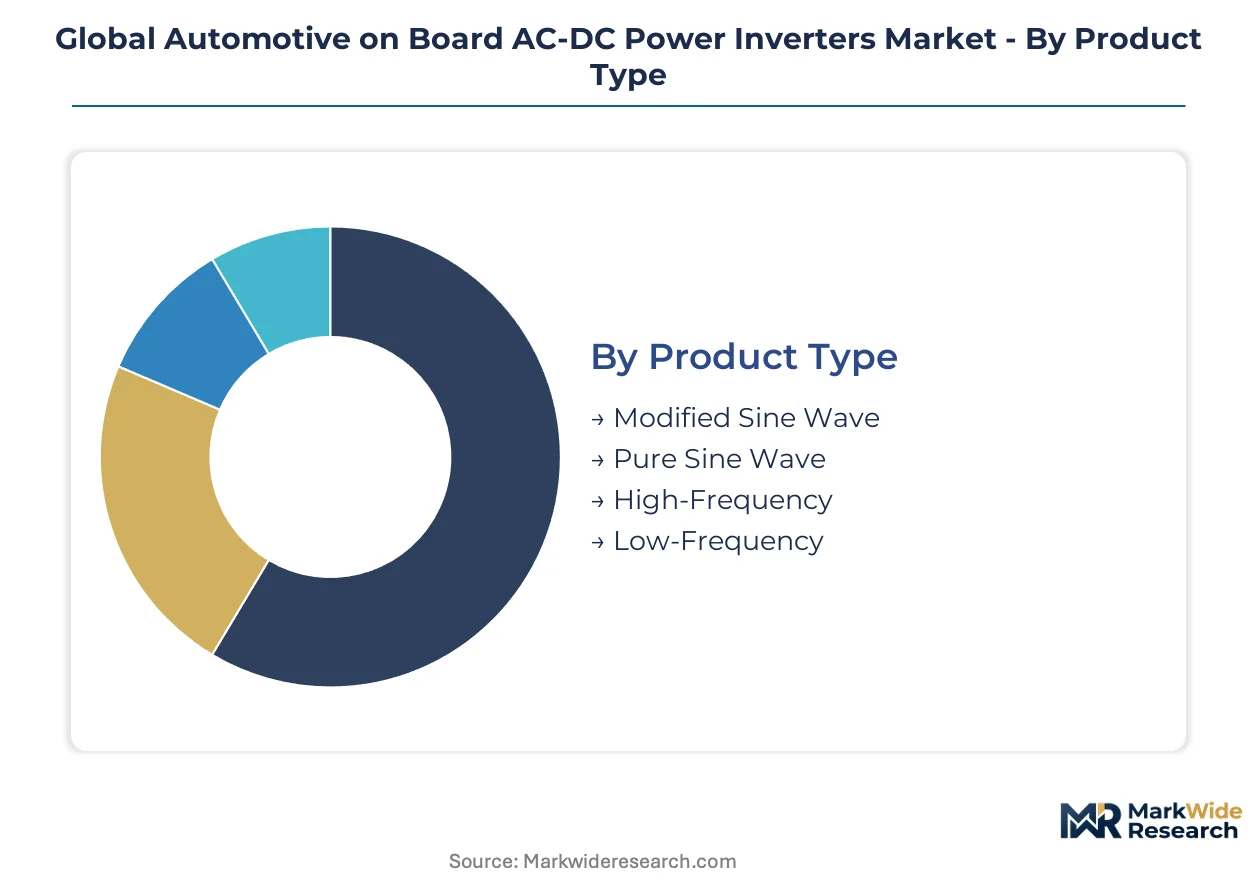
Automotive onboard AC-DC power inverters fragment across four intersecting dimensions that determine thermal architecture, semiconductor content, and certification burden. Procurement patterns diverge sharply between OEM-integrated platforms and aftermarket retrofit channels, while component sourcing strategies vary with switching frequency targets and magnetics requirements.
Product Type:
Customization intensity spans from commodity modified sine wave units to precision-engineered pure sine wave systems with resonant soft-switching topologies.
- Modified Sine Wave:Stair-step waveform approximation using simple pulse-width modulation reduces semiconductor count and control complexity. Demand concentrates in China's Yangtze River Delta EV cluster for entry-level commercial vans where cost sensitivity outweighs power quality requirements.
- Pure Sine Wave:Sinusoidal output through multi-level or resonant conversion architectures achieves total harmonic distortion below 3 percent. Germany's automotive engineering corridor dominates procurement for refrigerated delivery trucks and mobile medical units where sensitive equipment demands clean power.
- High-Frequency:Switching above 50 kHz collapses magnetic component volumes using ferrite core transformers.
- Low-Frequency:Iron-core magnetics at 20-50 kHz prioritize efficiency over power density in heavy-duty continuous-duty cycles.
Leading the category by volume: Modified Sine Wave. Expanding most quickly: Pure Sine Wave.
Application:
Power rating and duty cycle requirements sort applications across passenger electrification, engine restart systems, and auxiliary climate independence.
- Electric Vehicles:Traction battery integration demands 400V-800V input compatibility with isolation ratings exceeding 2.5 kV. Michigan's electrified vehicle supply chain anchors development for integrated power electronics platforms combining inverter, charger, and DC-DC functions.
- Auxiliary Power Units:Battery-driven climate systems independent of drivetrain status require continuous-duty thermal management. Cold-chain logistics operators in Germany retrofit diesel APUs with electric alternatives, driving procurement of high-efficiency conversion modules.
- Start-Stop Systems:12V-48V mild hybrid architectures use compact inverters for belt-driven starter-generator control.
- Renewable Energy Systems:Solar panel integration on commercial vehicle roofs demands maximum power point tracking and grid-synchronization capability.
Category anchor by installed base: Electric Vehicles. Steepest expansion trajectory: Auxiliary Power Units.
Component:
Bill-of-material concentration varies with switching technology transitions and magnetics sourcing constraints.
- Switching Transistors:Silicon carbide MOSFETs and gallium nitride HEMTs displace silicon IGBTs in designs above 6.6 kW, slashing thermal dissipation by 40 percent. Taiwan Semiconductor Manufacturing and STMicroelectronics supply relationships determine lead time exposure for European inverter assemblers.
- Inductors:Powdered iron and ferrite core magnetics filter switching ripple, with neodymium-doped materials facing Chinese processing concentration risk.
- Capacitors:DC-link film capacitors manage voltage ripple across wide temperature ranges.
- Transformers:Planar and toroidal winding configurations isolate high-voltage domains from auxiliary outputs.
Dominant cost concentration: Switching Transistors. Fastest technology transition: Inductors.
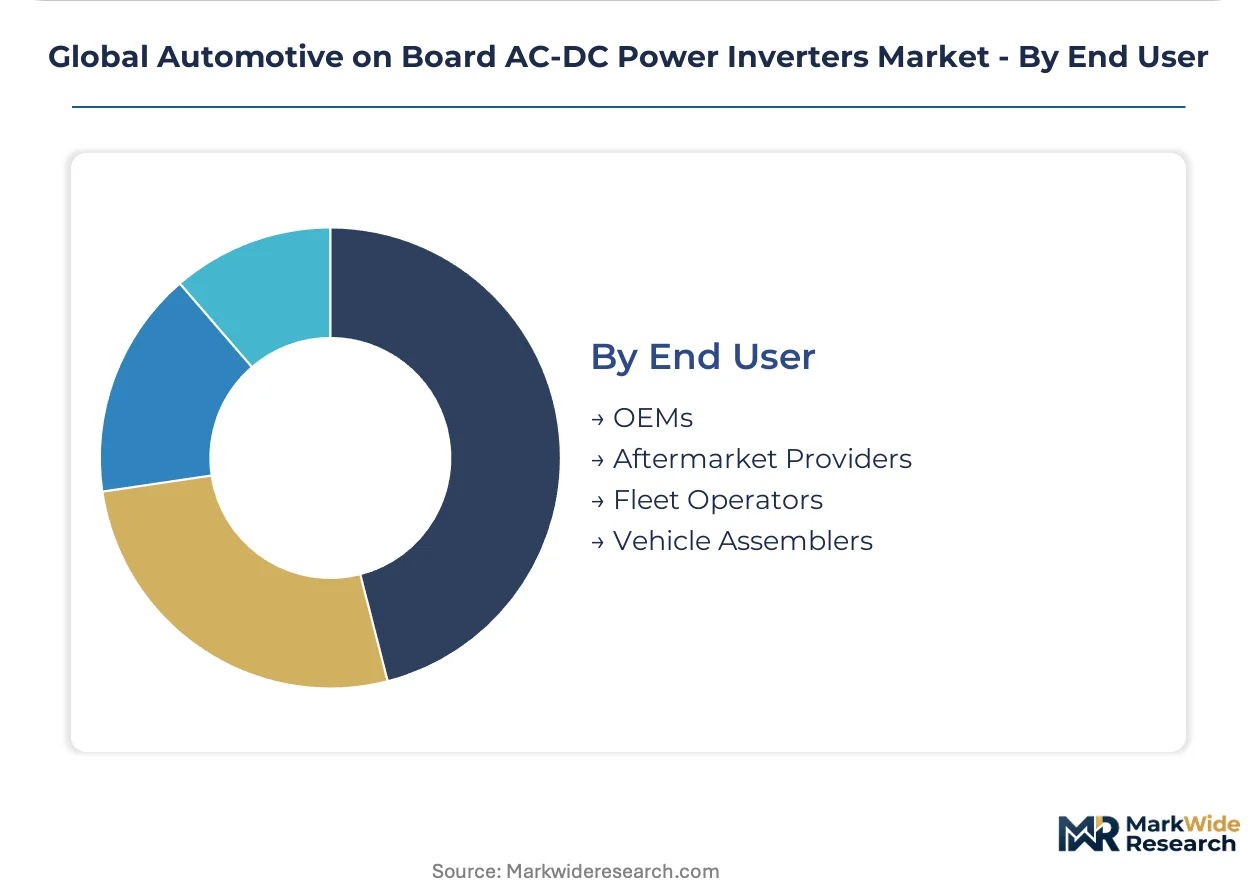
End User:
Specification authority and volume commitment separate captive OEM sourcing from fragmented aftermarket distribution.
- OEMs:Direct specification of inverter modules within complete electric climate system packages hardens procurement relationships. China's MIIT efficiency mandates compel domestic manufacturers toward pure sine wave topologies, eliminating modified sine wave from heavy-duty platform approvals.
- Fleet Operators:Refrigerated logistics providers negotiate multi-year supply agreements embedding power electronics within cargo integrity compliance systems.
- Aftermarket Providers:Retrofit channel serves legacy diesel fleet conversion to electric APUs.
- Vehicle Assemblers:Contract manufacturers integrate inverter subsystems from tier-one power electronics suppliers.
Volume concentration: OEMs. Procurement pattern shift: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Yangtze River Delta EV cluster and Germany's automotive engineering corridor, while consumption spreads across Michigan's electrified vehicle supply chain and India's emerging manufacturing corridors. This geographic split reflects the dominance of Chinese battery supply chains and German precision engineering in upstream component fabrication.
China
Domestic EV manufacturers are accelerating procurement of onboard power electronics as MIIT efficiency mandates tighten conversion loss thresholds. The Ministry of Industry and Information Technology's pure sine wave requirements for heavy-duty platforms are eliminating modified sine wave topologies from new vehicle approvals. Yangtze River Delta EV cluster suppliers are restructuring production lines to meet these mandates while serving both domestic OEMs and export markets.
Germany
Cold-chain logistics operators are retrofitting diesel auxiliary power units with battery-driven electric climate systems requiring high-efficiency AC-DC conversion. ECE R10 automotive EMC regulations constrain inverter topology designs and filter component selection for European type approvals. Stuttgart and Munich engineering corridors anchor development of soft-switching resonant converter architectures that meet Ecodesign Directive efficiency floors.
United States
Commercial ambulance manufacturers in Michigan's electrified vehicle supply chain are adopting silicon carbide MOSFETs for mobile medical equipment power conditioning. FCC Part 15 electromagnetic interference standards govern filter component selection for domestic market entry. EPA Phase 3 greenhouse gas rules for heavy-duty vehicles are expanding electrically driven auxiliary systems that displace mechanical belt drives and amplify inverter demand.
India
The Production Linked Incentive program's subsidy tier for advanced automotive electronics is attracting inverter module assembly investments in Tamil Nadu and Gujarat manufacturing corridors. Bureau of Indian Standards certification requirements for electric vehicle power electronics are aligning with international EMC protocols. Domestic OEMs are leveraging these incentives to localize sourcing previously dependent on Chinese imports.
Japan
METI's carbon neutrality roadmap and 2035 ICE sales prohibition are accelerating development of integrated power electronics platforms. Ministry of Economy, Trade and Industry efficiency benchmarks are consolidating inverter, charger, and DC-DC functions into single architectures. Nagoya and Tokyo metropolitan manufacturing bases are supplying these integrated systems to domestic automakers and Southeast Asian export markets.
Global Automotive on Board AC-DC Power Inverters Market Vendor Landscape
Top-tier vendors anchor OEM direct specification relationships, while mid-tier specialists compete on thermal architecture customization and regional certification speed. The supplier base stratifies between captive semiconductor sourcing capabilities and fabless assembly operations dependent on Taiwanese foundry access. Two archetypes dominate: diversified industrial conglomerates with power distribution heritage, and focused sensor-integrated module specialists. Competitive positioning hardens through backward integration into switching transistor arrays and multi-year fleet operator supply agreements.
Among diversified industrial conglomerates, Eaton Corporation and Continental AG exemplify the premium-tier vector where captive supply chains and in-house production of semiconductor components create sourcing resilience. Sensata Technologies, Inc. occupies a position within the sensor-integrated specialization tier, representing the module-level precision engineering archetype that extends thermal management precision across electric drivetrains. These three entities collectively illustrate the competitive tension between scale-driven vertical control and focused technical specialization in high-voltage inverter architectures.
| Leading Market Players |
|---|
| Eaton Corporation |
| Calsonic Kansei Corporation |
| Sensata Technologies, Inc. |
| Koninklijke Philips N.V. |
| Toshiba Electronic Devices & Storage Corporation |
| Continental AG |
| Lear Corporation |
| Delta Electronics, Inc. |
| Samlex America Inc. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Chinese semiconductor foundries anchor upstream supply of silicon carbide substrates, compressing margin recovery for European and North American inverter assemblers while forcing pricing discipline through captive magnetics sourcing.
Pricing Analysis
Cost-down pressure on pure sine wave modules accelerates because China's MIIT efficiency mandates are disqualifying modified sine wave topologies from heavy-duty platform approvals. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-D certified systems from commercial-grade units and entry-level fleet retrofit offerings. Price differentiation traces to certification grade and volume scale, with fleet operators negotiating multi-year supply agreements that embed power electronics within complete electric climate system packages. Aftermarket providers serving legacy diesel APU conversions exhibit highest price sensitivity, while OEMs prioritize thermal performance and EMC compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries supplying automotive-grade power management integrated circuits, extending lead times for European inverter assemblers facing US Bureau of Industry and Security export control friction. Geographic supply concentration centers on China for neodymium-doped ferrite cores and rare earth magnet processing, Taiwan for silicon carbide MOSFET fabrication, and Germany for precision magnetics engineering. Raw material dependencies rest on neodymium, dysprosium, and high-purity silicon carbide substrates. Distribution runs through direct OEM specification channels rather than fragmented aftermarket distribution, with fleet operators consolidating procurement through embedded electric climate system packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor substrate capacity constraints prop pricing power for incumbents with captive foundry relationships, while rare earth magnet supply concentration creates acquisition targets among magnetics specialists.
For Market Incumbents: Acquire magnetics engineering capabilities to offset rare earth supply concentration risk from Chinese processing facilities. Secure captive silicon carbide substrate supply through long-term offtake agreements with Taiwanese foundries. Defend against emerging fabless competitors by accelerating soft-switching resonant converter certification under Europe's Ecodesign Directive efficiency floors. For New Entrants and Emerging Players: Silicon carbide MOSFET thermal simulation expertise offers entry into refrigerated logistics electrification serving Germany's cold-chain operators. Target India's PLI-subsidized Tamil Nadu and Gujarat manufacturing corridors for inverter module assembly investments. Penetrate through vehicle-to-load bidirectional architectures for mobile command units and emergency response vehicles where power quality requirements exceed incumbent capability. For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless power electronics specialists with ISO 26262 certification progress stalled by semiconductor export control friction. Long-term viability over the next decade hinges on backward integration into switching transistor arrays or upstream magnetics sourcing. Watch for relaxation of US Bureau of Industry and Security restrictions on advanced node fabrication equipment as the inflection signal for foundry-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Captive substrate access from Taiwanese foundries insulates against export control lead time extensions. |
| Magnetics Engineering Acquisition | Neodymium-doped ferrite core design capability offsets Chinese rare earth processing concentration. |
| Soft-Switching Topology Certification | Ecodesign Directive compliance above 96 percent efficiency secures German OEM supply relationships. |
| Vehicle-to-Load Architecture Development | Bidirectional power export creates revenue streams from mobile command unit operators. |
| India PLI Manufacturing Footprint | Tamil Nadu and Gujarat assembly investments capture 18 percent subsidy tier for advanced automotive electronics. |
Methodological Framework
Multi-period observation of MIIT efficiency mandate compliance trajectories and Ecodesign Directive certification timelines anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operator maintenance directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, semiconductor trade flow records, and EPA Phase 3 greenhouse gas rulemaking documentation. Bottom-up segment sizing triangulated against top-down market aggregation across product type, application, component, and end user dimensions.
Segment-weighting approaches distributed value estimates across pure sine wave versus modified sine wave topologies, auxiliary power unit versus traction battery integration applications, and silicon carbide versus silicon IGBT switching technologies. CAGRs were derived from installation rate projections tied to commercial fleet electrification timelines and refrigerated logistics operator procurement cycles. Forecast inputs incorporated rare earth magnet price volatility indices and semiconductor foundry capacity utilization rates.
Several conditions sit outside the modeled scope, including potential relaxation of US Bureau of Industry and Security export controls, abrupt shifts in Chinese rare earth export policy, and breakthroughs in gallium nitride HEMT cost parity. Forecasts reflect documented assumptions about MIIT mandate enforcement consistency and Ecodesign Directive implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Automotive E-Axle Market