
 Automobile Accessories Market | 2026-2036
Automobile Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Automobile Accessories Market Analysis
Online retailers is reconfiguring how automobile accessories reach end buyers, compressing traditional distributor margins and forcing legacy channels to consolidate. Bosch leverages its embedded electronics expertise to dominate connected infotainment modules. AutoZone sustains its brick-and-mortar network while building parallel digital fulfillment capabilities. Thule Group specializes in roof-mounted cargo systems and occupies a defensible position in premium exterior accessories.
Automobile accessories encompass supplementary components, devices, and systems manufactured from leather, plastic, rubber, or fiberglass that attach to or integrate with vehicles post-production to enhance functionality, aesthetics, comfort, or safety. These products typically meet specific technical specifications for temperature resistance, tensile strength, and electromagnetic compatibility to ensure reliable operation within automotive environments. Interior accessories and exterior enhancements represent mature volume categories where margin pools have compressed due to commoditization, while safety equipment and performance add-ons command premium positioning as OEMs and insurers raise baseline requirements. GPS navigation and custom seat covers within the product-type dimension illustrate divergent trajectories, with embedded navigation systems facing displacement by smartphone mirroring technologies even as bespoke upholstery demand rises among luxury vehicle owners.
The US NHTSA and EPA regulate crashworthiness and emissions-related modifications, respectively, creating compliance barriers for performance add-on suppliers seeking market access. Europe's REACH and RoHS frameworks restrict hazardous substances in plastics and electronics, directly shaping material selection for carpets, rubber floor mats, and audio system housings. China's SAMR enforces GB standards for electromagnetic compatibility that aftermarket electronics must satisfy before domestic sale. Stakeholders must monitor how divergent regional certification regimes fragment product architectures and determine whether to maintain modular platform designs or accept market-specific SKUs.
Market Dynamics
Smartphone mirroring protocols are compressing demand for embedded navigation hardware across vehicle segments, forcing suppliers to pivot toward software-integrated cabin ecosystems or cede margin to handset ecosystem providers.
Growth Catalysts
- India's PLI scheme for auto components:Local manufacturing incentives are accelerating domestic production of customization kits and interior upgrade modules, reducing import dependency for fleet operators.
- Fleet operator procurement expansion:Ride-hailing services and commercial fleets are systematically upgrading vehicle interiors and connectivity modules to differentiate passenger experience and improve driver retention.
- Electromagnetic compatibility mandates:China's SAMR enforcement of GB standards for aftermarket electronics is creating compliant product demand that rewards pre-certified suppliers with faster market access.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and ABS resin prices fluctuate with crude oil markets, compressing margins for plastic-intensive accessories like floor mats and trim panels.
- Regional certification fragmentation:Divergent electromagnetic compatibility requirements across China's SAMR, the US FCC, and Europe's CE marking force suppliers to maintain multiple product architectures or forfeit market access.
- Smartphone substitution threat:Handset-based navigation and voice assistants are displacing dedicated GPS hardware and aftermarket infotainment systems in price-sensitive segments.
Strategic Opportunities
- Underpenetrated Indian aftermarket:Rising vehicle ownership in tier-2 and tier-3 cities is creating first-time accessory demand for basic comfort and utility products before premium upgrade cycles begin.
- Regulatory tailwind from safety mandates:India's proposed Bharat NCAP adoption and insurer premium adjustments for safety equipment are expanding addressable market for dashcams, tire pressure monitors, and emergency response systems.
- Convergence of biometric sensing and upholstery:Integration of health monitoring sensors into seat covers and steering wheel wraps is opening premium pricing tiers for wellness-focused vehicle owners.
Industry Challenges
- Embedded systems engineering talent scarcity:Shortage of firmware developers capable of integrating accessory electronics with OEM vehicle networks limits supplier capability to meet connected-car specifications.
- Homologation timeline compression:Accelerated vehicle model refresh cycles from OEMs are shrinking the commercial window for accessory compatibility testing and certification before designs become obsolete.
- Legacy channel inventory reconfiguration:Traditional distributor networks face working capital strain as online direct-to-consumer channels capture growing share of replacement and upgrade purchases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automobile Accessories Market |
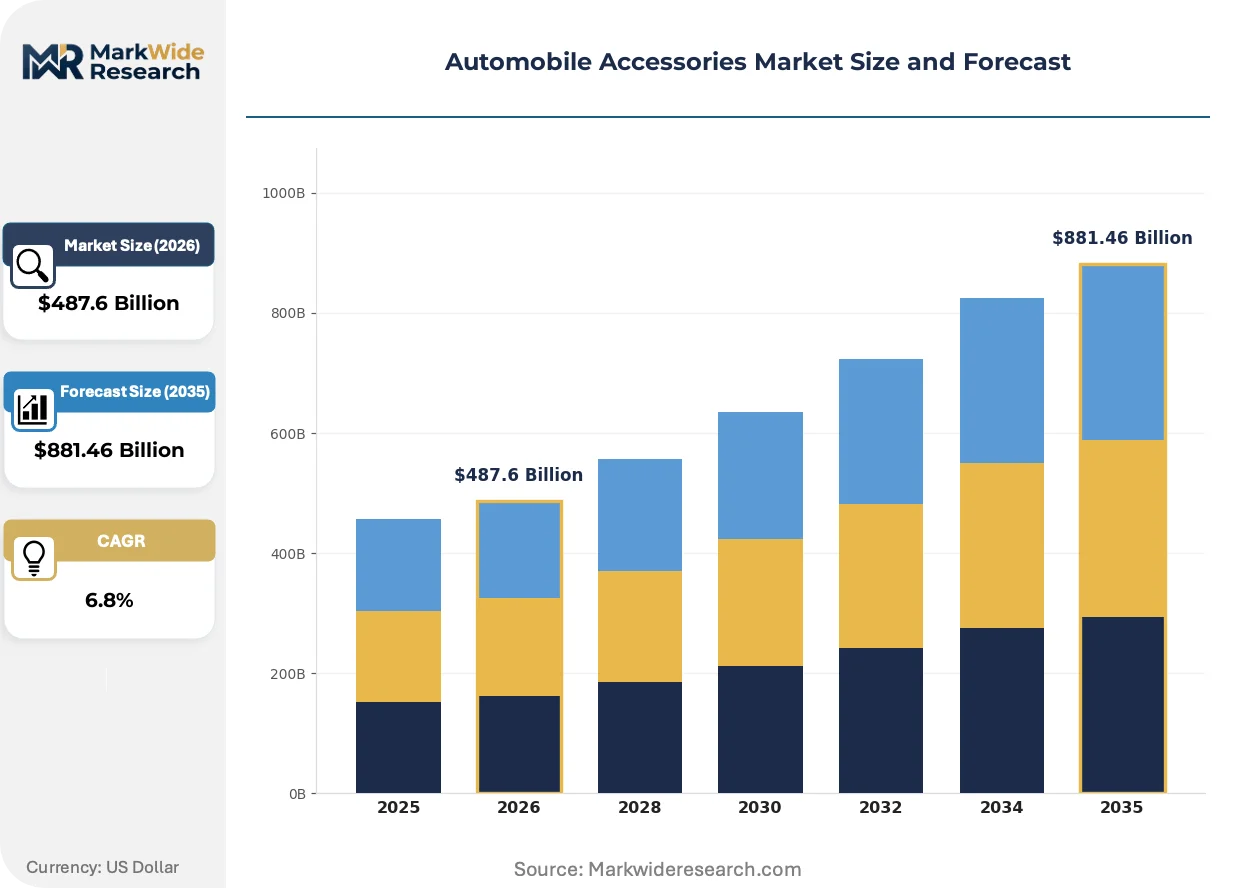
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Systems, GPS Navigation, Carpets, Custom Seat Covers Material: Leather, Plastic, Rubber, Fiberglass Application: Interior Accessories, Exterior Enhancements, Safety Equipment, Performance Add-ons Distribution Channel: Online Retailers, Auto Parts Stores, Dealerships, Trade Shows |
| Companies Covered | Bosch, Denso Corporation, Continental AG, Magna International, Pioneer Corporation, AutoZone, 3M Company, Thule Group, Lear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automobile Accessories Market Emerging Trajectories
Digital twin technologies are virtualizing how accessory suppliers design, test, and validate products before physical prototyping, compressing development cycles and reducing homologation failure rates.
Software-defined vehicle architectures are virtualizing the boundary between factory-installed and aftermarket functionality. Tier-1 electronics suppliers are adopting virtualized development environments that simulate CAN bus integration and thermal performance before tooling investment. Fleet procurement teams now require virtual compatibility demonstrations before approving supplier qualification, compressing traditional sample-based evaluation timelines.
REACH and RoHS frameworks are restricting hazardous substance use in automotive plastics and electronics. European accessory manufacturers must reformulate rubber compounds and PCB substrates to eliminate restricted phthalates and lead-based solder. Upholstery suppliers serving Germany's KBA-certified vehicle converters are accelerating material certification to maintain component-level traceability documentation.
Direct-to-consumer configurators are displacing traditional catalog-based distributor relationships. Specialty exterior accessory buyers now expect 3D visualization tools that render roof racks and body kits on their specific vehicle models before purchase. This channel shift is most pronounced in North American and Australian markets where enthusiast vehicle ownership rates support premium customization spending.
Automobile Accessories Market Segmentation
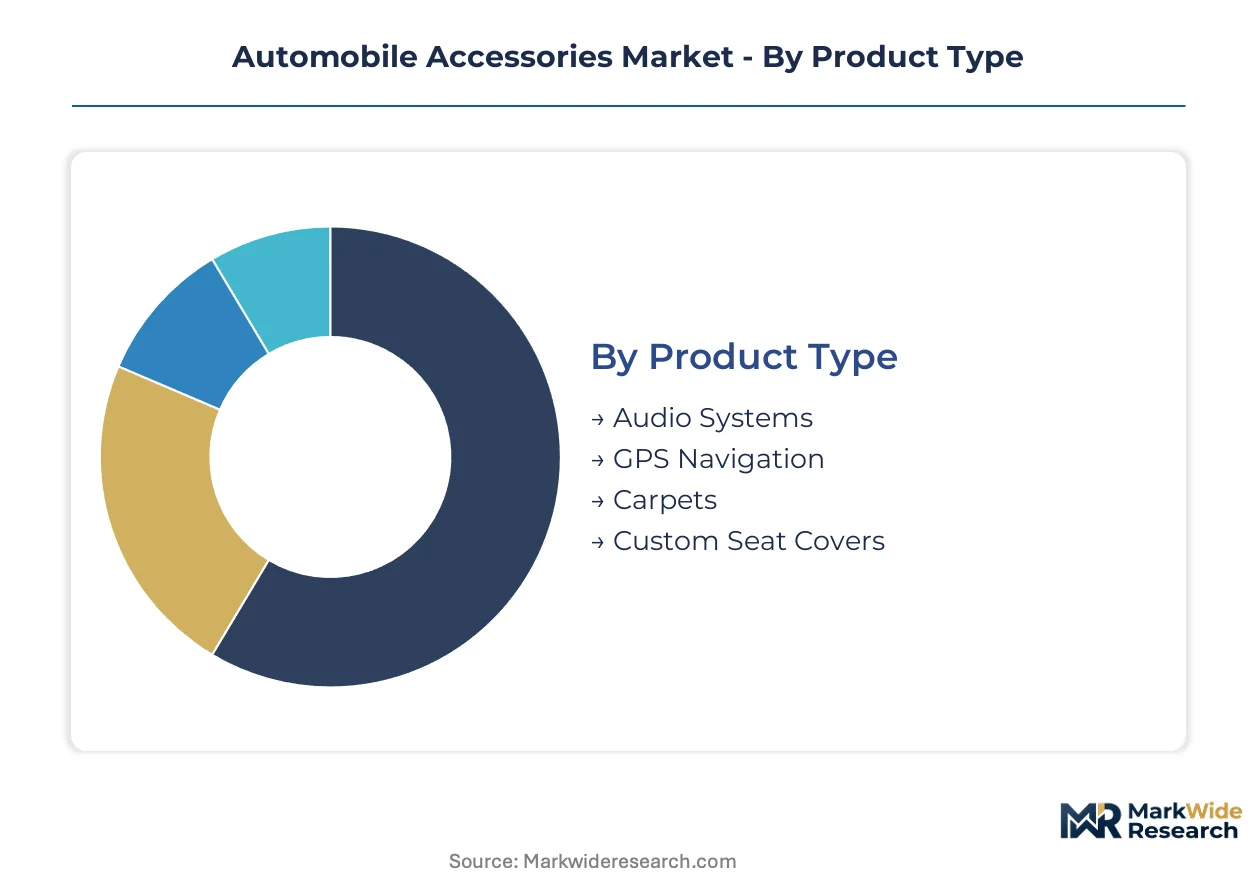
Automobile accessories fragment across four distinct taxonomies that determine procurement patterns, margin profiles, and regulatory exposure. Product type and application dimensions capture the functional hierarchy buyers prioritize, while material composition and distribution channel dictate cost structures and market access velocity.
Product Type:
Mature hardware categories coexist with emerging software-integrated systems, creating divergent investment timelines for suppliers.
- Audio Systems:Aftermarket head units and speaker assemblies incorporate Bluetooth, Wi-Fi, and voice processing chipsets. Fleet operators in India specify these for driver retention programs as ride-hailing competition intensifies. India's PLI scheme for auto components accelerates local assembly of amplifier modules and reduces import duties on DSP chips.
- GPS Navigation:Embedded mapping hardware faces displacement from smartphone mirroring protocols across all vehicle segments. Suppliers pivot toward software-integrated cabin ecosystems or cede margin to Apple CarPlay and Android Auto ecosystem providers.
- Carpets:Molded floor liners from thermoplastic elastomer compounds dominate volume replacement cycles. REACH and RoHS frameworks in Europe restrict phthalate plasticizers, forcing reformulation of PVC backing layers.
- Custom Seat Covers:Bespoke upholstery demand rises among luxury vehicle owners in Germany and the US, with biometric sensor integration opening premium pricing tiers for wellness-focused buyers.
Audio Systems retains volume leadership; Custom Seat Covers holds the steepest expansion curve.
Material:
Cost tier stratification separates commodity feedstocks from performance-engineered substrates.
- Leather:Full-grain hides and synthetic alternatives serve premium upholstery and steering wrap applications. Germany's KBA-certified vehicle converters demand component-level traceability documentation for tanning chemical compliance.
- Plastic:Polypropylene and ABS resin prices fluctuate with crude oil markets, compressing margins for floor mats, trim panels, and audio housings. China's SAMR enforces GB standards for electromagnetic compatibility in plastic-encased electronics.
- Rubber:EPDM and nitrile compounds form weatherstripping, floor mats, and cargo liners. European manufacturers eliminate restricted phthalates to satisfy REACH certification.
- Fiberglass:Reinforced polymer composites enable lightweight body kits and aerodynamic add-ons for performance segments. Specialized layup processes limit supplier base to technical specialists.
Plastic commands absolute volume; Fiberglass climbs the fastest on performance vehicle customization demand.
Application:
Customer type separates fleet procurement patterns from individual enthusiast spending.
- Interior Accessories:Floor mats, seat covers, and ambient lighting modules constitute mature volume categories where margin pools have compressed due to commoditization. India's tier-2 and tier-3 cities generate first-time demand for basic comfort products.
- Exterior Enhancements:Roof racks, body kits, and lighting upgrades occupy defensible premium positions where 3D visualization tools now drive direct-to-consumer conversion in North America and Australia.
- Safety Equipment:Dashcams, tire pressure monitors, and emergency response systems command premium positioning as India's proposed Bharat NCAP adoption and insurer premium adjustments expand addressable market.
- Performance Add-ons:Intake systems, exhaust components, and suspension modules face US NHTSA crashworthiness and EPA emissions compliance barriers that fragment product architectures.
Interior Accessories retains volume leadership; Safety Equipment holds the steepest expansion curve.
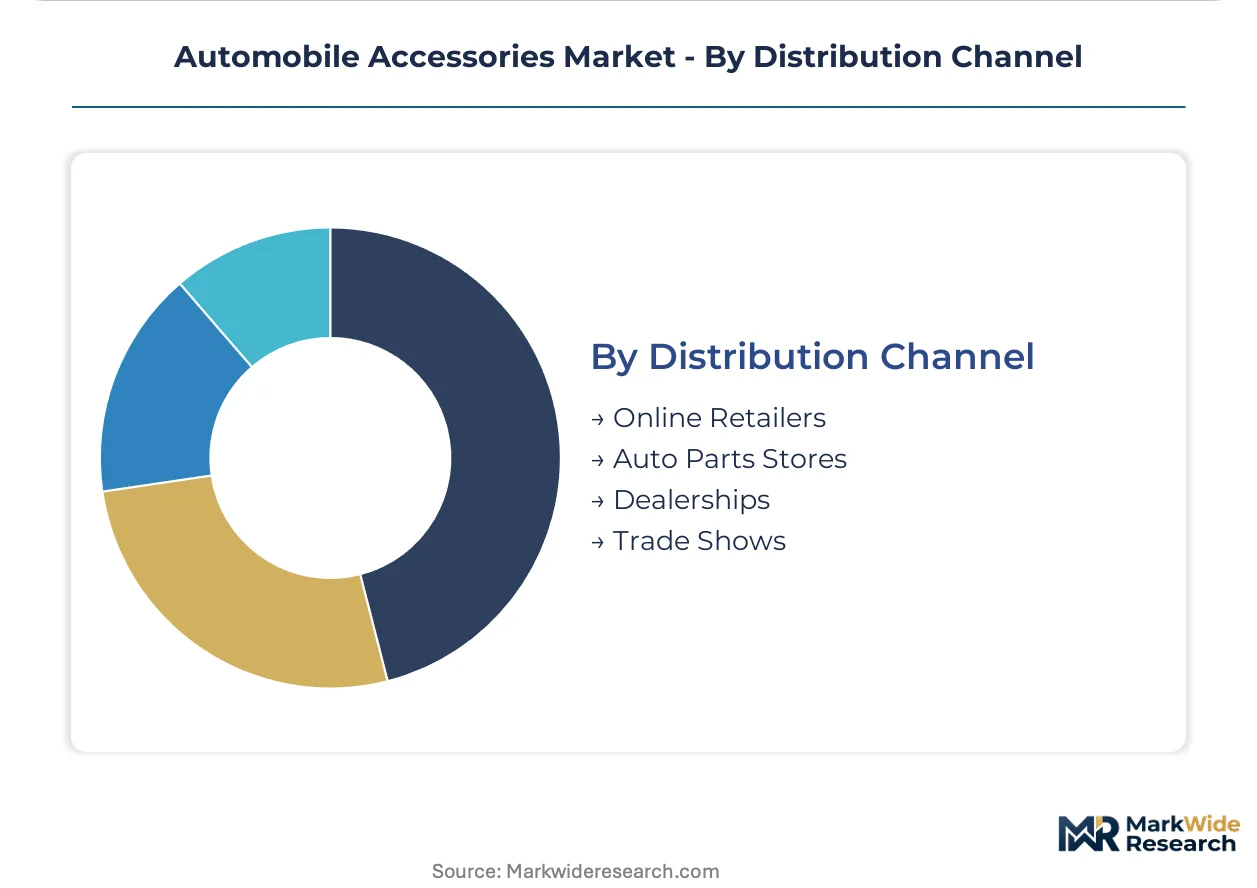
Distribution Channel:
Geography determines channel efficiency, with digital penetration varying sharply by market maturity.
- Online Retailers:Direct-to-consumer configurators with 3D visualization displace catalog-based distributor relationships. AutoZone builds parallel digital fulfillment capabilities alongside its brick-and-mortar network.
- Auto Parts Stores:Traditional distributor networks face working capital strain as online channels capture growing share of replacement purchases. Inventory reconfiguration pressures legacy channel economics.
- Dealerships:OEM-tied channels dominate warranty-integrated accessory sales and financed upgrade packages. China's SAMR and NMPA tightening of safety standards accelerates certified dealer channel preference.
- Trade Shows:SEMA and Automechanika Frankfurt serve as qualification venues where fleet procurement teams require virtual compatibility demonstrations before supplier approval.
Auto Parts Stores retains volume leadership; Online Retailers gains share fastest on digital adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors Asia-Pacific trade flows for containerized auto parts, while the Rhine-Main-Danube waterway corridor underwrites European distribution efficiency for just-in-time accessory supply chains.
China
Domestic EV ownership expansion and fleet electrification are accelerating procurement of cabin connectivity modules and interior upgrade kits. SAMR enforcement of GB electromagnetic compatibility standards for aftermarket electronics compresses supplier qualification timelines. The Yangtze River Delta cluster around Shanghai concentrates molded plastic component fabrication for floor mats and trim panels serving both domestic and export markets.
United States
Enthusiast vehicle ownership in Texas and California sustains premium exterior accessory demand for roof racks and aerodynamic body kits. NHTSA crashworthiness regulations and EPA emissions compliance barriers fragment product architectures for performance add-on suppliers. The Southeast manufacturing corridor spanning Georgia and Tennessee hosts injection molding operations for interior plastic components serving Detroit Three OEM supply chains.
Germany
Luxury vehicle parc density in Bavaria and Baden-Württemberg drives bespoke upholstery demand with biometric sensor integration. KBA certification requirements for vehicle converters mandate component-level traceability documentation for tanning chemical compliance. The Stuttgart industrial basin concentrates leather processing and precision stitching operations for premium seat cover suppliers serving Mercedes-Benz and Porsche owners.
India
Rising vehicle ownership in Maharashtra and Gujarat tier-2 cities generates first-time accessory demand for basic comfort products before premium upgrade cycles begin. The PLI scheme for auto components accelerates local manufacturing of customization kits and reduces import dependency for fleet operators. The Chennai- Bengaluru industrial corridor hosts electronics assembly operations for audio systems and infotainment modules targeting ride-hailing fleet procurement.
Japan
Aging vehicle parc maintenance requirements sustain replacement demand for interior accessories and safety equipment in Kanto and Kansai metropolitan areas. METI energy efficiency guidelines shape material selection for lightweight composite body kits. The Nagoya manufacturing hub concentrates precision plastic molding for OEM-tier floor mat and cargo liner suppliers serving Toyota and Honda aftermarket channels.
Automobile Accessories Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material processing and single-function fabrication. The vendor base stratifies across three tiers: multinational electronics conglomerates with embedded vehicle network expertise, mid-cap interior and exterior specialists with defensible niche positions, and regional fabricators competing on cost for commodity replacement cycles. Consolidation pressure concentrates among legacy distributors as online channels capture share. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with OEMs for co-development of connected cabin ecosystems.
Among diversified electronics conglomerates, Bosch and Denso Corporation exemplify platform integrators leveraging embedded systems expertise for connected infotainment dominance. Continental AG anchors the European tier with regulatory compliance capabilities spanning REACH material certification and CE electromagnetic marking. AutoZone represents the distributor archetype navigating brick-and-mortar network reconfiguration while building parallel digital fulfillment infrastructure. Thule Group occupies a defensible position in premium exterior accessories through specialized roof-mounted cargo system engineering.
| Leading Market Players |
|---|
| Bosch |
| Denso Corporation |
| Continental AG |
| Magna International |
| Pioneer Corporation |
| AutoZone |
| 3M Company |
| Thule Group |
| Lear Corporation |
| Others |
Supply Flow & Price Mechanics
China's Yangtze River Delta cluster concentrates molded plastic component fabrication for floor mats and trim panels, anchoring margin pools in economies of scale rather than material innovation. Fleet procurement teams and ride-hailing operators extract volume discounts that compress distributor markups and force legacy channels toward direct fulfillment models.
Pricing Analysis
Volume-discount tiering separates fleet operators purchasing connectivity modules in thousand-unit batches from individual buyers seeking single custom seat covers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in plastic-intensive categories stems from polypropylene resin volatility. Fleet buyers exhibit highest price sensitivity; luxury vehicle owners purchasing biometric-integrated upholstery show lowest.
Supply Chain Analysis
Extended payment terms from Tier 1 electronics suppliers strain working capital for mid-cap interior specialists serving aftermarket channels. Manufacturing concentrates in China, Germany, and Mexico for molded components, leather processing, and injection molding respectively. Feedstock dependencies span ABS resin, full-grain hides, and EPDM rubber compounds. Single-source vulnerability sits with semiconductor chipsets for infotainment modules. Distribution runs through online direct-to-consumer platforms capturing share from traditional auto parts stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-integrated cabin ecosystems represent a service-attach opportunity expanding faster than hardware sales, with subscription-based connectivity modules and over-the-air update capabilities generating recurring revenue layers beyond initial equipment procurement.
For Market Incumbents: Harden embedded systems engineering capabilities through captive firmware development teams capable of CAN bus integration, insulating against smartphone mirroring displacement. Consolidate distributor relationships in India's tier-2 cities before PLI-accelerated local manufacturing matures. Certification investment in China's SAMR GB standards compliance accelerates market access velocity relative to unprepared competitors. For New Entrants and Emerging Players: Build out direct-to-consumer 3D visualization platforms for exterior accessories in North American and Australian enthusiast markets, where premium customization spending supports digital channel economics. India's underpenetrated tier-3 cities offer first-time accessory demand for basic comfort products before upgrade cycles begin. Fleet procurement bypass strategies targeting ride-hailing operators with pre-certified connectivity modules accelerate initial revenue traction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined accessory categories as virtualized development environments reduce physical prototyping requirements. Five-to-ten year viability favors platform integrators with OEM co-development relationships over component specialists facing commoditization. Acquisition target archetype: mid-cap interior specialists with backward integration into polymer compounding and SAMR pre-certification. Signal to watch: fleet operator consolidation into national procurement consortia altering volume discount structures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Virtualized CAN bus integration capabilities differentiate Tier 1 suppliers from hardware-only competitors. |
| Backward Integration into Polymer Compounding | Captive ABS and polypropylene supply insulates margin from crude oil feedstock volatility. |
| SAMR Pre-Certification Program | GB electromagnetic compatibility compliance accelerates China's aftermarket electronics market entry. |
| Direct-to-Consumer Platform Launch | 3D visualization configurators displace catalog-based distributor relationships in premium exterior segments. |
| Fleet Procurement Partnership | Ride-hailing operator contracts provide volume stability absent in fragmented individual buyer markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and dealership accessory managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SAMR certification filings, and customs trade records for ABS resin and leather feedstock flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Calibration across the projection horizon employed vehicle parc analysis, content-per-vehicle trajectories, and regional regulatory adoption timelines. Segmentation dimensions spanned product type, material composition, application, and distribution channel, with propulsion architecture and OEM tier as automotive-specific overlays. CAGRs derived from fitted growth curves against historical replacement cycle patterns and fleet electrification procurement schedules.
Stress conditions across polypropylene price volatility, smartphone mirroring penetration rates, and India's PLI scheme implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory shifts or technological substitution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market