
 Global Automotive Interior Plastic Components Market | 2026-2036
Global Automotive Interior Plastic Components Market Size, Share, and Industry Trends Forecast 2026-2036
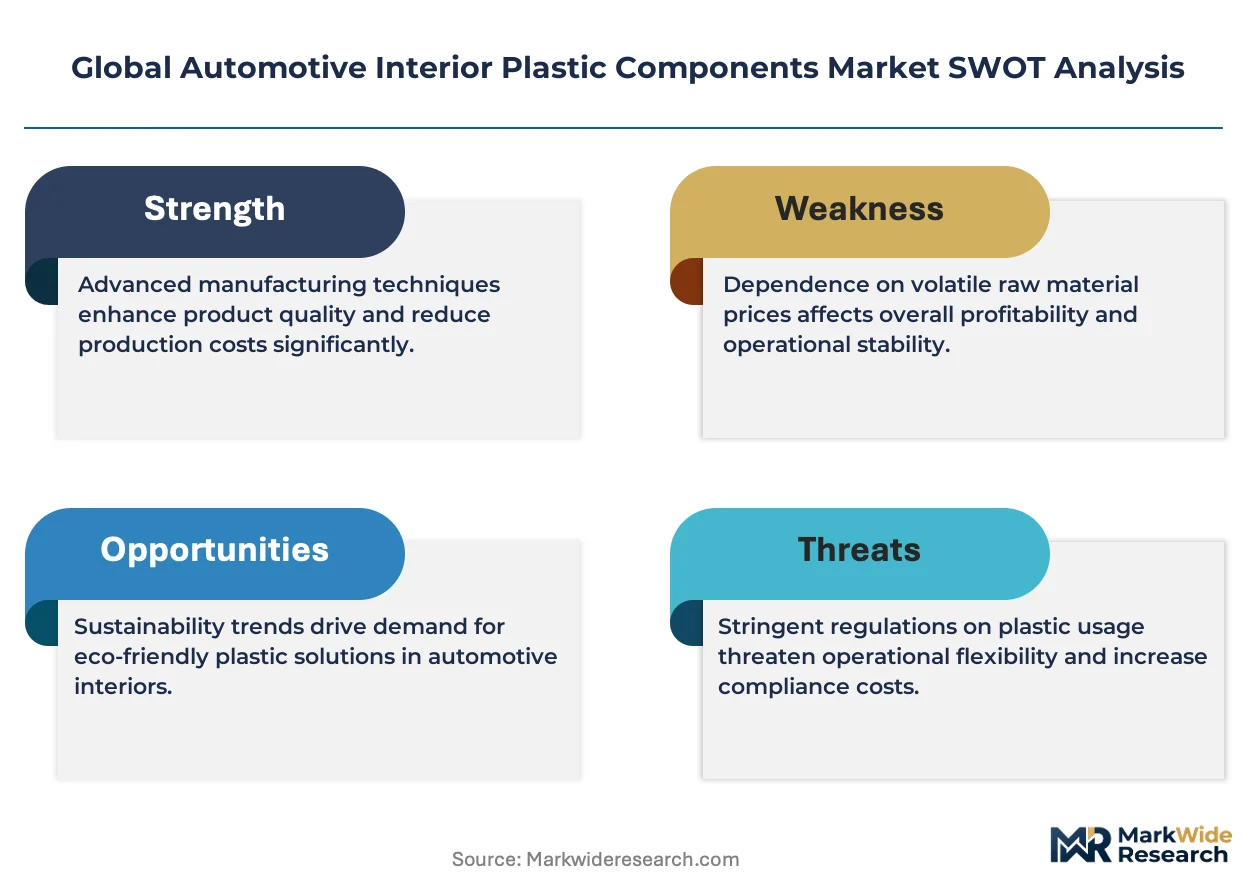
Global Automotive Interior Plastic Components Market Analysis
Supplier consolidation toward vertically integrated module production is shifting procurement dynamics across the automotive interior plastics value chain. Adient plc. leverages its global seating and interiors footprint to control material flows from resin to finished assemblies. Lear Corporation sustains competitive positioning through R&D intensity in smart surface technologies. FORVIA Faurecia anchors European supply relationships while extending manufacturing scale into Asian EV production corridors.
Automotive interior plastic components encompass injection-molded and extruded polymer parts engineered to specified tolerances for cabin modules, typically formulated with polypropylene or ABS blends to achieve weight targets below equivalent metal designs while meeting flammability and VOC emission thresholds. These components serve the primary commercial purpose of reducing vehicle mass to extend electric range and improve fuel efficiency across passenger and commercial platforms. Polypropylene formulations dominate volume demand due to cost-performance balance in dashboard and door panel applications, while thermoplastic elastomers represent the fastest-expanding material category as soft-touch surfaces penetrate mid-tier vehicle segments. Injection molding occupies the central margin pool across manufacturing stages, though 3D printing is gaining structural relevance for low-volume customization in luxury vehicle programs.
The US EPA and NHTSA coordinate fuel economy standards that directly incentivize gram-per-mile weight reduction through interior material substitution. Europe's REACH framework and ECHA substance restrictions are forcing reformulation of plasticizers and flame retardants across dashboard and console supply chains. China's MIIT administers dual carbon goals that tighten embodied emissions requirements for polymers entering domestic vehicle assembly. Stakeholders must monitor how evolving recyclability mandates across these jurisdictions reshape resin selection criteria and supplier qualification protocols.
Market Dynamics
Electric vehicle platform architectures are compressing development cycles for cabin modules, forcing interior plastics suppliers to synchronize resin formulation with battery thermal management specifications. This structural pressure is redrawing qualification timelines and tooling investments across the value chain.
Growth Catalysts
- China's dual carbon goals:MIIT mandates on embodied emissions are accelerating recycled polypropylene adoption in domestic EV assembly lines. Domestic brands now specify post-consumer content thresholds for dashboard substrates.
- Thermoplastic elastomer penetration:Soft-touch surfaces are migrating from luxury segments into mid-tier vehicle interiors as Chinese and European OEMs prioritize haptic differentiation. TPE formulations now cover console trim and door pulls previously served by rigid polymers.
- REACH recycled content quotas:ECHA implementation timelines are compelling European suppliers to requalify supply chains around mechanically recycled ABS blends. Reformulation investments are concentrating in German and French tier-one operations.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins swing with natural gas pricing, compressing margin visibility for polypropylene compounders serving dashboard programs. European and Asian resin buyers face 90-day price exposure windows.
- Flame retardant reformulation costs:ECHA restrictions on halogenated additives force redundant testing cycles for dashboard and console assemblies. Dual qualification tracks for EU and non-EU markets inflate R&D overhead.
- Tooling amortization pressure:Multi-cavity injection molds for door panels require 400,000-unit annual volumes to achieve payback. Low-volume EV platforms strain supplier capital deployment decisions.
Strategic Opportunities
- India's PLI scheme for auto components:Tier-one seating and interior suppliers are qualifying localized polypropylene compounding to serve Maruti Suzuki and Tata Motors EV expansion. Domestic resin sourcing avoids import duty exposure.
- Chemical recycling integration:Pyrolysis-derived feedstocks offer pathway to food-contact-grade recycled content for future cabin applications. Early movers are locking offtake agreements with technology licensors.
- 3D printed customization channels:Luxury vehicle programs are piloting digitally tooled low-volume trim production for limited editions. This bypasses hard-tooling constraints for runs below 10,000 units.
Industry Challenges
- Material data stewardship:Full material disclosure requirements under SCIP database obligations force suppliers to trace additive packages through three-tier supply chains. Documentation gaps block EU market access.
- Cross-platform thermal specification alignment:Battery-adjacent cabin modules must simultaneously satisfy Chinese GB standards and European ECE regulations. Divergent test protocols duplicate validation spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Interior Plastic Components Market |
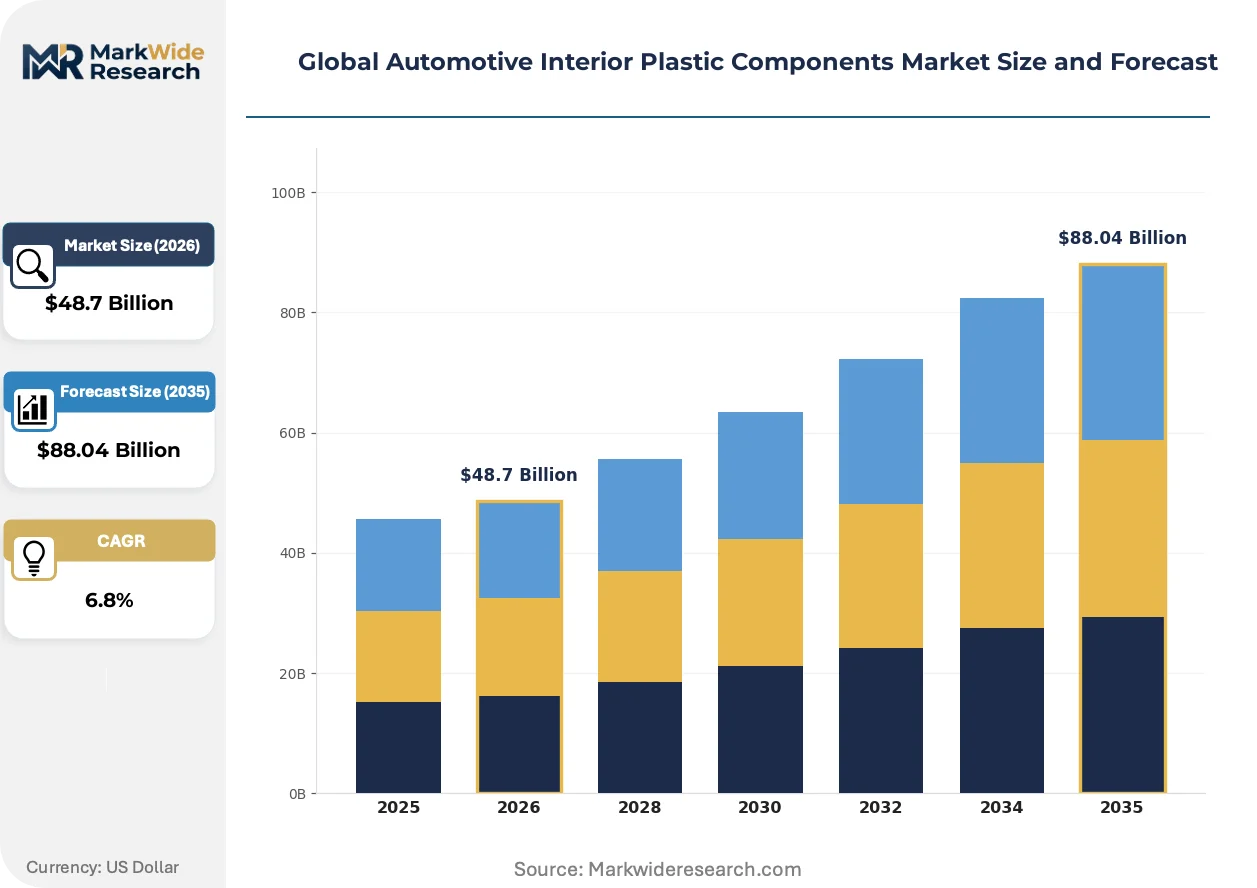
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard, Door Panels, Center Console, Armrest Material: Polypropylene, Polycarbonate, Thermoplastic Elastomers, ABS Application: Luxury Vehicles, SUVs, Sedans, Commercial Vehicles Manufacturing Stage: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | Adient plc., Lear Corporation, FORVIA Faurecia, Continental AG, Yanfeng Automotive Interiors, Toyota Boshoku, Saudi Basic Industries Corporation (SABIC), Magna International, Grupo Antolin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Interior Plastic Components Market Emerging Trajectories
Surface engineering and circular material flows are redefining value capture in automotive interior plastics. Technical differentiation now concentrates on haptic performance and end-of-life traceability rather than commodity cost optimization.
Natural fiber-reinforced polypropylene is electrifying structural panel applications by cutting density 15-20% versus talc-filled grades without sacrificing stiffness. European OEMs led by German premium brands are specifying hemp and flax composites for door panels and seat backs. The technology is electrifying supplier R&D allocation, compressing development resources previously directed toward conventional mineral reinforcement.
REACH Article 33 disclosure obligations are forcing granular supply chain visibility down to 0.1% weight thresholds for Substances of Very High Concern. Dashboard and console manufacturers must now map plasticizer and stabilizer flows through compounders and masterbatch suppliers. Tier-one suppliers with captive resin operations are internalizing compliance costs while external compounders face qualification barriers.
Direct OEM contracting is displacing traditional tier-two supply relationships for critical cabin modules. BYD and NIO in China now specify resin grades and surface treatments directly, compressing tier-one design authority. This pattern concentrates procurement leverage with vehicle assemblers and fragments specification control among legacy interior system suppliers.
Global Automotive Interior Plastic Components Market Segmentation
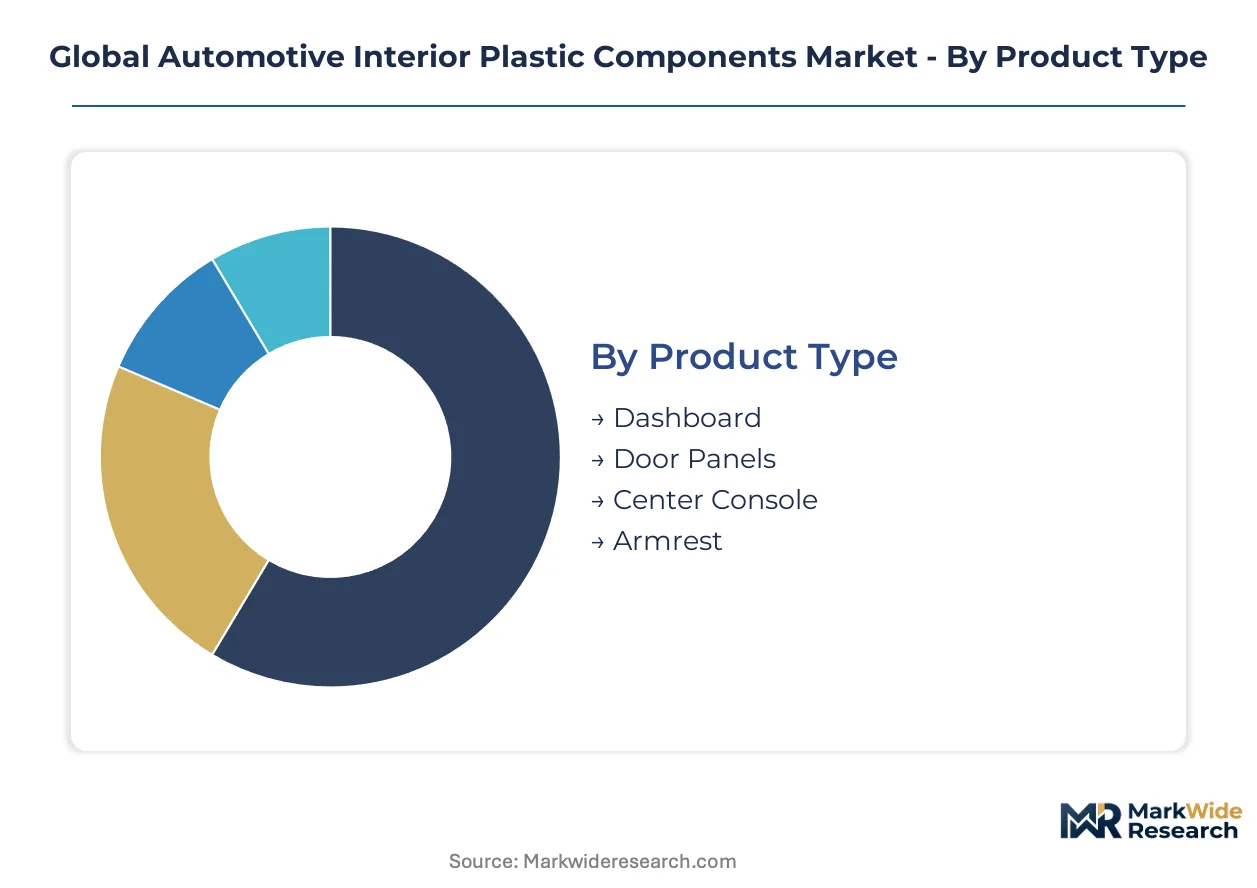
Segmentation in automotive interior plastics reflects divergent technical requirements across cabin modules, material performance thresholds, and manufacturing scale economics. Each axis shapes procurement patterns, supplier qualification protocols, and margin capture potential across vehicle programs.
Product Type:
Structural integration demands and surface finish specifications define competitive positioning across cabin modules.
- Dashboard:Large-format injection-molded assemblies integrating HVAC ducting, instrument clusters, and airbag deployment zones. Polypropylene compounds with mineral reinforcement dominate Chinese EV assembly lines where BYD and NIO specify recycled content thresholds.
- Door Panels:Multi-component assemblies combining rigid substrates with soft-touch inserts and trim attachments. European premium brands specify hemp-fiber-reinforced grades to satisfy REACH embodied emissions criteria while cutting mass versus conventional talc-filled formulations.
- Center Console:Functional modules housing gear selectors, storage compartments, and connectivity interfaces. Haptic differentiation drives specification toward thermoplastic elastomer overmolding in mid-tier Chinese and European segments.
- Armrest:Smaller-volume components prioritizing comfort and durability in high-contact zones. TPE penetration is expanding fastest here as soft-touch expectations migrate downmarket from luxury programs.
Dashboard leads on scale; door panels lead on momentum as natural fiber reinforcement gains specification share.
Material:
Cost-performance balance and regulatory compliance trajectories concentrate procurement leverage around specific polymer families.
- Polypropylene:Dominant volume position through cost efficiency, chemical resistance, and established recycling infrastructure. MIIT mandates on embodied emissions are accelerating post-consumer recycled grade adoption in domestic Chinese EV supply chains.
- ABS:Superior surface aesthetics and paintability sustain demand in premium console and trim applications. ECHA REACH recycled content quotas are forcing European compounders to requalify mechanically recycled blends for dashboard programs.
- Thermoplastic Elastomers:Soft-touch haptic performance without vulcanization costs. Fastest-expanding category as Chinese and European OEMs prioritize tactile differentiation in mid-tier interiors previously served by rigid polymers.
- Polycarbonate:Optical clarity and impact resistance for transparent and structural glazing applications. Limited volume growth constrained by cost premium versus competitive materials in non-critical cabin zones.
Polypropylene leads on scale; thermoplastic elastomers climb the fastest on specification momentum.
Application:
Vehicle class positioning determines material grade thresholds, surface engineering investments, and supplier margin structures.
- Sedans:Highest production volumes with standardized interior architectures supporting multi-platform tooling amortization. Chinese domestic brands concentrate sedan output with aggressive recycled content targets under dual carbon compliance frameworks.
- SUVs:Expanded cabin volumes and premium positioning justify higher material specifications and soft-touch surface coverage. European and North American SUV programs drive thermoplastic elastomer penetration in console and door applications.
- Luxury Vehicles:Unlimited material budgets enabling natural fiber composites, chemical recycling integration, and 3D-printed customization for limited editions. Direct OEM contracting for resin specification is displacing traditional tier-one design authority.
- Commercial Vehicles:Durability and cost minimization priorities favor commodity polypropylene grades with minimal surface engineering. Tooling payback requirements strain supplier participation in low-volume specialized truck platforms.
Sedans lead on scale; luxury vehicles lead on specification innovation velocity.
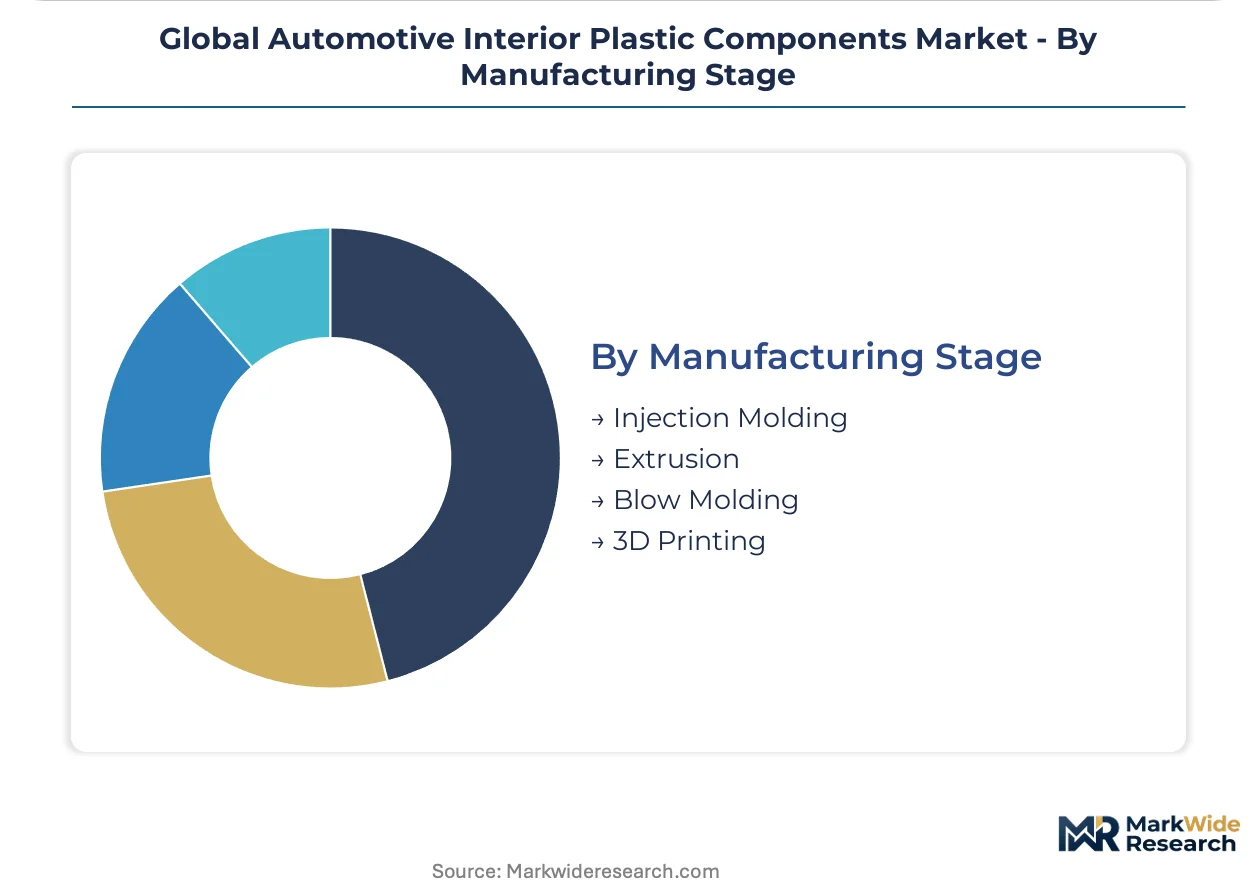
Manufacturing Stage:
Process selection locks in capital intensity, design flexibility, and per-unit economics across production scales.
- Injection Molding:Central margin pool through multi-cavity tooling, cycle time optimization, and established automation. Dashboard and door panel programs in China, Germany, and the United States concentrate volume here.
- 3D Printing:Digitally tooled production bypassing hard-tooling constraints for runs below 10,000 units. Luxury vehicle limited editions pilot this channel for customized trim elements in European and Chinese premium programs.
- Extrusion:Continuous profile production for structural sections and trim components. Lower value capture versus injection molding but essential for specific geometric requirements in sealing and edge applications.
- Blow Molding:Hollow section production for ducting, reservoirs, and structural tubes. Constrained growth as HVAC integration trends favor injection-molded consolidated assemblies over discrete blow-molded components.
Injection molding leads on scale; 3D printing gains share fastest on customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redrawing production geography as suppliers seek cost-of-compliance advantages across jurisdictions with divergent recycled-content mandates and carbon-accounting frameworks.
China
Domestic EV brands BYD and NIO are scaling premium cabin production with aggressive post-consumer recycled polypropylene specifications. MIIT dual carbon goals tighten embodied emissions thresholds for polymers entering vehicle assembly. Yangtze River Delta suppliers in Shanghai and Jiangsu province are consolidating compounding capacity to serve battery-thermal-integrated dashboard programs.
Germany
Premium OEMs are specifying hemp-fiber-reinforced grades for door panels to satisfy REACH embodied emissions criteria. ECHA restrictions on halogenated flame retardants force reformulation of dashboard substrates for EU and export markets. Bavarian and Baden-Württemberg tier-one operations concentrate requalification investments for mechanically recycled ABS blends.
United States
EPA and NHTSA coordinated fuel economy standards incentivize gram-per-mile weight reduction through interior material substitution. Southeast automotive corridors in Tennessee and South Carolina attract polypropylene compounding investments to serve EV platform launches. Domestic suppliers face 90-day feedstock price exposure from propylene volatility.
India
PLI scheme incentives draw tier-one seating and interior suppliers to localize polypropylene compounding for Maruti Suzuki and Tata Motors EV expansion. Domestic resin sourcing avoids import duty exposure on compounded materials. Tamil Nadu and Gujarat industrial clusters concentrate qualification activity for dashboard substrate supply.
Japan
METI carbon-neutrality roadmaps pressure suppliers to requalify supply chains around chemically recycled feedstocks. Toyota Boshoku anchors domestic demand for lightweight structural panels with natural fiber reinforcement. Aichi and Shizuoka prefecture manufacturing bases pilot pyrolysis-derived polymer integration for future cabin applications.
Global Automotive Interior Plastic Components Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smart surface and chemical recycling adjacencies to bypass incumbent tooling advantages. The vendor base concentrates around seating and interiors specialists with captive resin operations, while commodity compounders face margin compression from feedstock volatility. Three archetypes dominate: vertically integrated module assemblers controlling material flows from resin to finished parts; technology licensors monetizing pyrolysis and advanced recycling patents; and regional compounders serving single-OEM programs with localized formulation expertise. Competitive moves center on M&A to secure chemical recycling offtake agreements and strategic partnerships to lock multi-year resin supply contracts ahead of recycled-content mandate deadlines.
Within the integrated-module tier, Adient plc. and Lear Corporation exemplify archetypes with global seating and interiors footprints controlling upstream material specifications. FORVIA Faurecia occupies a position bridging European supply relationships with Asian EV production corridor expansion. These three entities represent distinct strategic postures: Adient plc. leverages scale across resin-to-assembly value chain control; Lear Corporation anchors R&D intensity in haptic surface technologies; FORVIA Faurecia concentrates European regulatory compliance expertise with manufacturing proximity to Chinese battery platform launches.
| Leading Market Players |
|---|
| Adient plc. |
| Lear Corporation |
| FORVIA Faurecia |
| Continental AG |
| Yanfeng Automotive Interiors |
| Toyota Boshoku |
| Saudi Basic Industries Corporation (SABIC) |
| Magna International |
| Grupo Antolin |
| Others |
Supply Flow & Price Mechanics
Captive resin compounding by vertically integrated module assemblers anchors supply position and pricing power across the automotive interior plastics value chain. This integration pattern concentrates procurement leverage with seating and interiors specialists while fragmenting margin pools for external compounders exposed to propylene feedstock swings.
Pricing Analysis
Direct-to-OEM contracting discounts dominate channel economics as vehicle assemblers like BYD and NIO specify resin grades and surface treatments directly. Pricing stratifies across premium natural fiber-reinforced grades, standard talc-filled polypropylene, and economy mineral compounds. Cost compression in commodity grades intensifies because naphtha-cracking margins swing with natural gas pricing. Tier-one seating suppliers show least price sensitivity due to captive compounding; independent compounders serving aftermarket channels face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Shanghai, Stuttgart, and Detroit anchor hub-and-spoke patterns for just-in-time dashboard and door panel delivery. Manufacturing concentrates in China, Germany, and the United States where injection molding capacity clusters around EV platform launches. Feedstock draws from Saudi Arabian and U.S. Gulf Coast propylene supply. Single-source vulnerability concentrates around specialized flame retardant additive packages subject to ECHA REACH restrictions. Distribution runs through tier-one module assemblers with direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive interior plastics offer margin expansion through lightweighting premiums and recycled-content qualification barriers that commoditize non-compliant competitors. Chemical recycling integration and soft-touch surface technologies concentrate value capture with technology-forward suppliers.
For Market Incumbents: Deepen captive resin operations to internalize REACH compliance costs and SCIP database traceability requirements. Lock multi-year offtake agreements with pyrolysis technology licensors before recycled-content mandate deadlines. Defend against direct OEM contracting by controlling formulation intellectual property for battery-thermal-integrated cabin modules.
For New Entrants and Emerging Players: 3D-printed customization channels offer white-space entry for low-volume luxury trim production bypassing hard-tooling constraints. Target Indian PLI scheme incentives for localized polypropylene compounding serving Maruti Suzuki and Tata Motors EV expansion. Lead with digitally tooled production capabilities to secure limited-edition programs below 10,000 units.
For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with localized formulation expertise because OEM qualification timelines create sticky supplier relationships. Monitor ECHA implementation timelines for mechanically recycled ABS blend requalification as inflection indicator for European supply chain restructuring. Prioritize targets with captive testing capabilities for dual GB-ECE thermal specification alignment.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Integration | Pyrolysis-derived feedstocks unlock food-contact-grade recycled content for future cabin applications. |
| Natural Fiber Reinforcement Scale-Up | Hemp and flax composites cut density 15-20% versus talc-filled grades for German premium door panels. |
| Direct OEM Contracting Bypass | Resin specification control migrates to vehicle assemblers, fragmenting tier-one design authority. |
| India PLI Localization | Domestic compounding avoids import duty exposure for Maruti Suzuki and Tata Motors EV programs. |
| 3D Printing Capability Buildout | Digitally tooled production serves luxury limited editions below hard-tooling economic thresholds. |
Methodological Framework
Coverage spans China, Germany, the United States, India, and Japan, with primary inputs from each market cluster. Interviews with tier-one supplier procurement officers, OEM platform engineers, resin compounder technical directors, and aftermarket distributors combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and ECHA substance restriction notifications. Bottom-up segment sizing triangulated against top-down industry value estimates.
Rate-of-change decomposition separates volume growth from value mix-shift across the projection horizon. The analytical framework models vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from regression against historical production correlations with polymer intensity per platform. Forecast inputs include MIIT dual carbon compliance trajectories and REACH recycled content quota implementation schedules.
The model holds under stable regulatory implementation timelines; deviation in ECHA enforcement intensity or propylene feedstock volatility would shift supplier qualification pacing. Forecasts reflect documented assumptions around EV platform launch cadence and recycled resin availability scaling. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive Differential Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Cast Iron Cylinder Head Market