
 Automotive Glass Market | 2026-2036
Automotive Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Glass Market Analysis
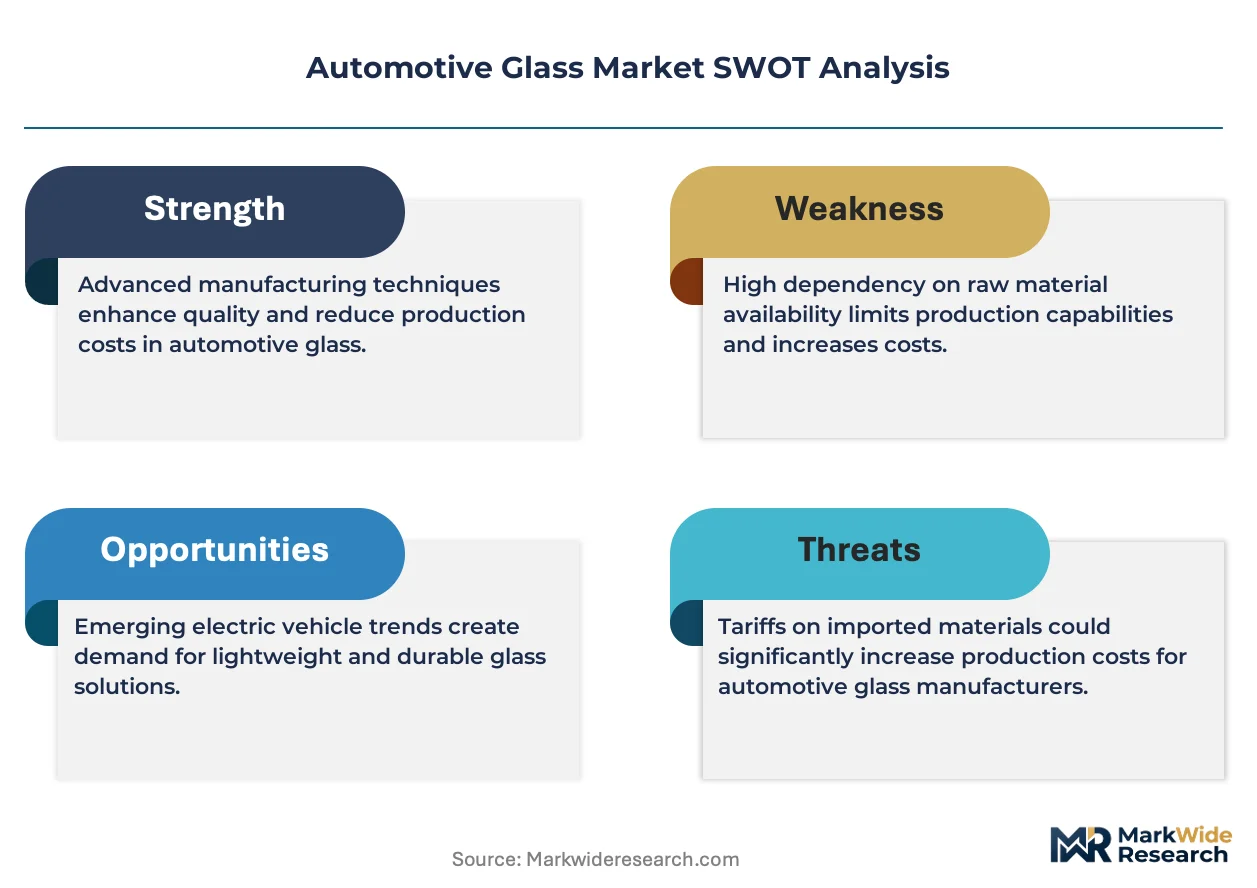
Asset-light leasing models for float glass production lines is tilting competitive dynamics toward capital-efficient entrants. Fuyao Glass leverages its integrated furnace-to-fabrication footprint across multiple continents. Saint-Gobain sustains premium positioning through advanced interlayer chemistry and acoustic laminates. AGC Inc. anchors Japanese OEM supply relationships with specialized thin-glass formulations for weight reduction.
Automotive glass comprises silica-based transparent panels engineered to optical clarity standards, typically laminated with polyvinyl butyral interlayers for impact resistance or tempered through controlled thermal treatment for side and rear applications, serving structural, aerodynamic, and occupant-protection functions in vehicle cabins. Laminated glass dominates windshield applications due to regulatory mandates for occupant retention during collisions, while smart glass technology represents the fastest-expanding margin pool as electrochromic and suspended particle devices command premium pricing in luxury electric vehicle segments. Tempered glass retains cost advantages in high-volume side-window replacement markets where polycarbonate faces scratch-resistance limitations.
FDA guidelines for transportation material safety, ECE R43 standards governing optical properties and fragmentation behavior, and China's GB 9656 national standard for automotive glass collectively shape product certification requirements and cross-border market access protocols. The EU Green Deal's embodied carbon tracking mechanisms are pressuring suppliers to document furnace emissions and recycled content ratios. Stakeholders must monitor evolving head-up display compatibility specifications and determine R&D allocation between augmented-reality windshield integration and structural glass weight reduction pathways.
Market Dynamics
Panoramic sunroof mandates from electric vehicle OEMs are compressing traditional windshield supply chains while forcing laminated glass capacity expansions across tier-one fabricators.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Suppliers documenting furnace emissions and recycled content ratios gain preferential access to German and French OEM procurement programs.
- Head-up display compatibility specifications:Windshield curvature tolerances and wedge-angle precision requirements are pulling advanced optical-grade laminated glass into mid-tier vehicle segments.
- China's dual carbon goals:Domestic NEV manufacturers are specifying low-carbon glass formulations, creating pull-through for float furnaces running hydrogen-enriched natural gas blends.
Market Restraints
- Silica sand supply concentration:High-purity deposits in Wisconsin and Illinois face extraction permitting delays, constraining North American float glass output expansion.
- Polyvinyl butyral interlayer cost volatility:Crude oil derivative pricing swings compress margins for laminated windshield producers locked into annual OEM supply agreements.
- Polycarbonate scratch-resistance limitations:Side-window substitution remains blocked by surface durability failures in automated car wash environments.
Strategic Opportunities
- India PLI scheme for auto components:Localized laminated glass fabrication incentives are attracting furnace investments to serve Maruti Suzuki and Tata Motors NEV platforms.
- Electrochromic-suspended particle device convergence:Smart glass integration with cabin thermal management systems opens premium pricing in luxury electric SUV segments.
- Direct-to-OEM digital specification platforms:Glass fabricators are bypassing traditional tier-two distributors by embedding CAD-compatible windshields into vehicle development portals.
Industry Challenges
- Optical metrology technician scarcity:Precision measurement of wedge angles and optical distortion requires specialized training programs that outpace vocational education output.
- GB 9656-ECE R43 dual certification timelines:Chinese suppliers targeting European OEMs face 18-24 month homologation cycles for laminated windshield variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Glass Market |
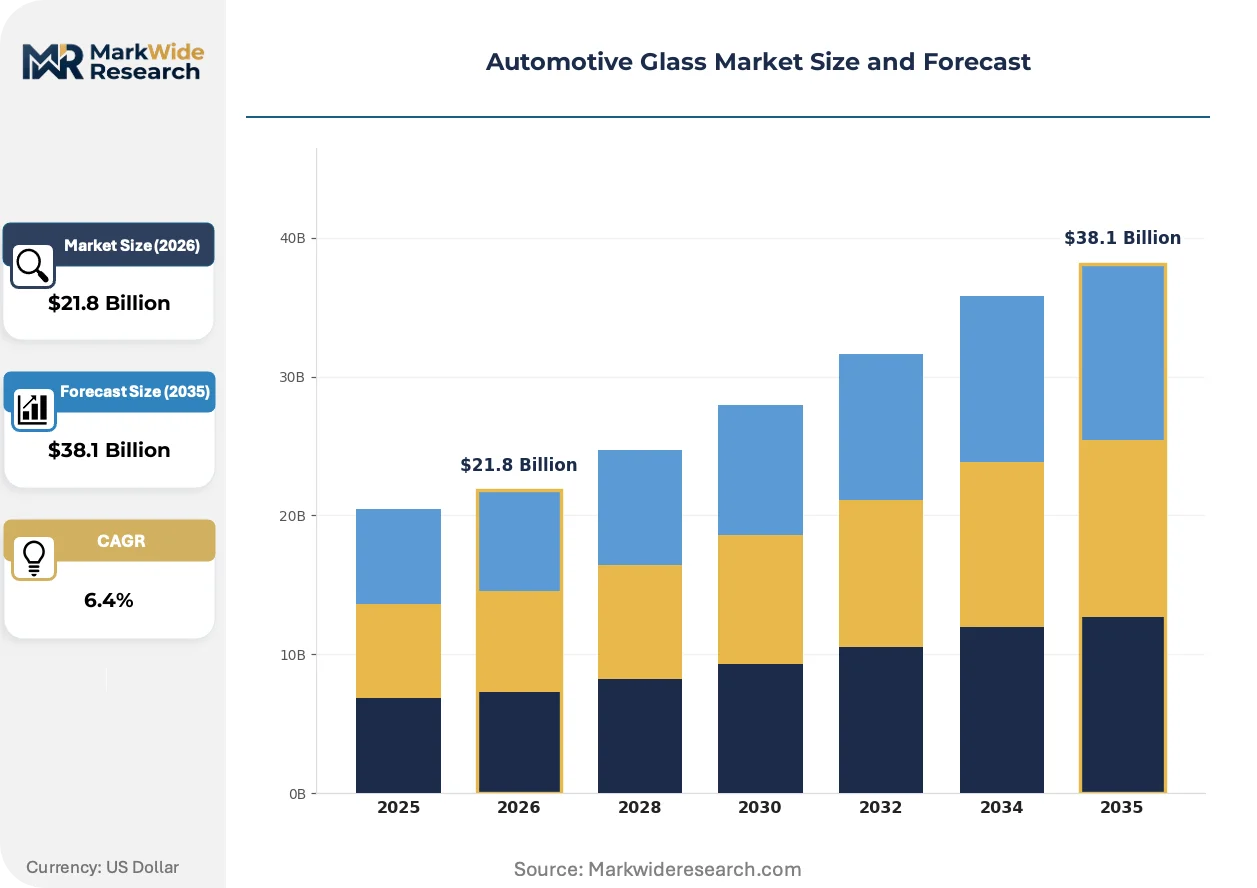
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Windshield, Side Window, Rear Window, Sunroof Material: Tempered Glass, Laminated Glass, Coated Glass, Polycarbonate Application: Passenger Vehicles, Commercial Vehicles, Heavy Trucks, Electric Vehicles Technology: Automated Production, Low-E Glass, Tinted Glass, Smart Glass |
| Companies Covered | Saint-Gobain, Fuyao Glass Industry Group, AGC Inc., Nippon Sheet Glass, Xinyi Glass Holdings, Guardian Industries, Webasto, Corning Incorporated, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Glass Market Emerging Trajectories
Automotive glass is transitioning from passive cabin enclosure to active interface surface, with embedded functionality driving material specification changes across windshield, roof, and side-aperture applications.
Electrochromic glazing is digitizing cabin climate control by enabling real-time tint adjustment without mechanical shades. Mercedes-Benz and BMW are specifying these systems for flagship electric sedans launching 2024-2026. The technology is digitizing traditional HVAC load distribution and compressing premium sunroof supplier margins as electrochromic roof panels displace mechanical assemblies.
REACH SVHC candidate list expansion is forcing reformulation of interlayer plasticizers and edge-seal adhesives used in laminated windshields. European compounders are accelerating bio-based polyvinyl butyral development to preempt authorization requirements. German KBA type-approval processes are extending by 4-6 months for suppliers unable to demonstrate full substance transparency.
Fleet operators are unbundling glass replacement from comprehensive maintenance contracts, creating direct procurement relationships with regional fabrication shops. Rental car and ride-hail aggregators in Texas and Florida are negotiating volume-based pricing for tempered side-window inventory. This channel compression is most visible in high-turnover commercial vehicle segments where OEM dealer networks previously captured aftermarket glass revenue.
Automotive Glass Market Segmentation
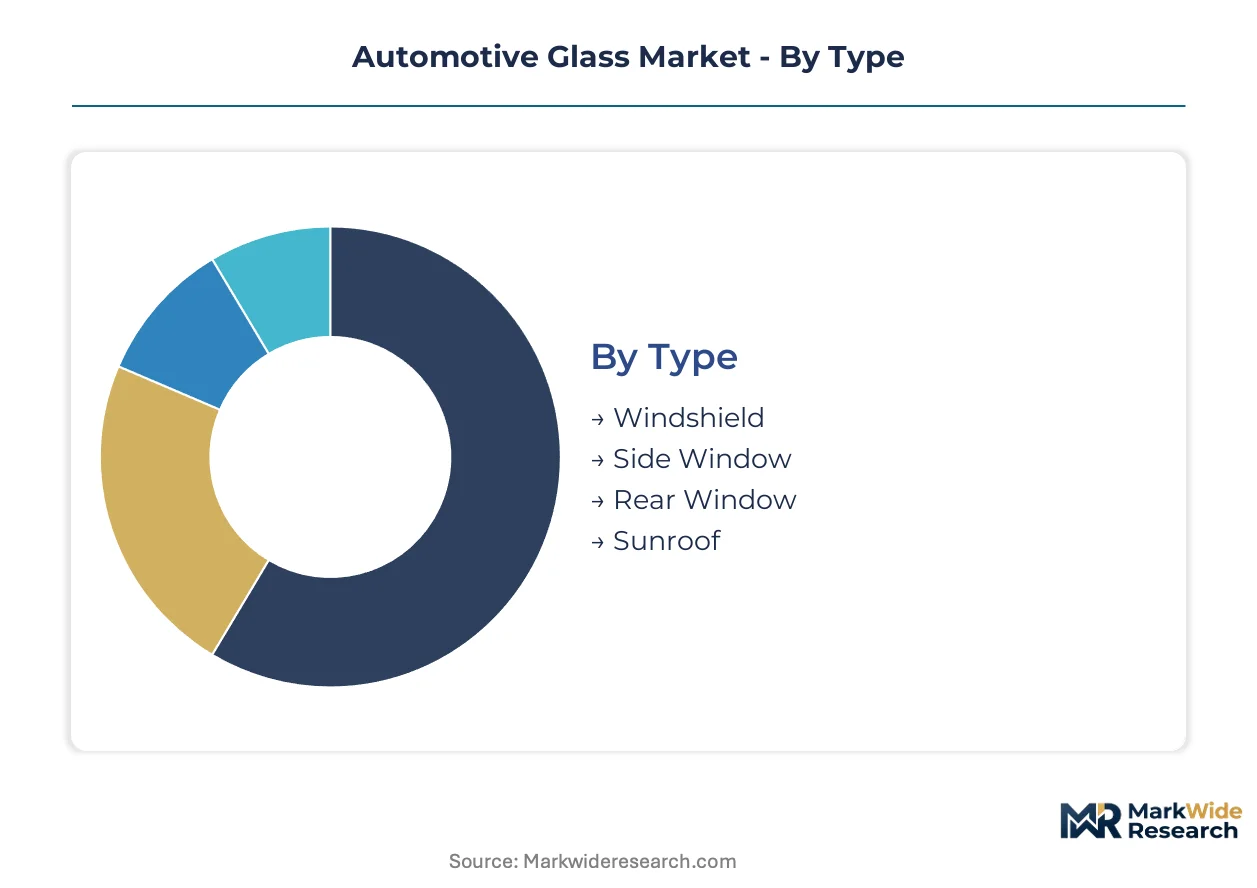
Automotive glass segmentation reveals divergent margin structures across replacement cycles and OEM specifications. After-sales intensity varies dramatically by aperture type and material formulation, dictating inventory positioning and service network density for fabricators.
Type:
Replacement frequency and damage exposure create distinct aftermarket service profiles across vehicle apertures.
- Windshield:Laminated construction with polyvinyl butyral interlayers absorbs road debris impact while maintaining optical clarity for advanced driver assistance systems. Chip repair services and full replacement demand concentrate in high-mileage commercial fleets across Germany and Texas interstate corridors, where stone strike incidence drives recurring revenue for mobile installation networks.
- Sunroof:Expanding panoramic formats in electric vehicle platforms are compressing traditional roof panel supply chains while forcing laminated capacity expansion. Chinese NEV manufacturers specify integrated glass roof modules that merge structural and aesthetic functions, creating pull-through for specialized curvature fabrication equipment.
- Side Window:Tempered construction enables controlled fragmentation patterns for emergency egress, serving high-volume replacement markets where cost sensitivity dominates procurement decisions.
- Rear Window:Defroster-integrated tempered glass carries embedded conductive filaments, limiting supplier switching due to electrical certification requirements.
Windshield holds the largest share; momentum sits with Sunroof.
Material:
Cost tiers separate premium laminated formulations from commodity tempered alternatives.
- Laminated Glass:Dual-pane construction with acoustic interlayers commands specification in luxury segments and regulatory-mandated windshield applications. ECE R43 compliance requirements in European markets and FMVSS 205 in the United States enforce fragmentation standards that only laminated construction satisfies, locking in material choice for forward apertures.
- Smart Glass:Electrochromic and suspended particle device layers enable real-time tint modulation without mechanical shades. Mercedes-Benz and BMW flagship electric sedans specify these systems for cabin thermal management, creating premium pricing pools that offset higher interlayer costs.
- Tempered Glass:Controlled thermal treatment produces surface compression for impact resistance, retaining cost advantages in side and rear applications.
- Coated Glass:Low-emissivity and infrared-reflective layers reduce HVAC load in climate-extreme operating environments.
- Polycarbonate:Lightweight polymer faces scratch-resistance limitations that block adoption in automated car wash environments despite weight reduction benefits.
Laminated Glass holds the largest share; Smart Glass is climbing the fastest.
Application:
Vehicle category determines specification stringency and volume scale.
- Electric Vehicles:Panoramic roof mandates and weight reduction targets are reshaping material specifications across NEV platforms. Chinese manufacturers BYD and NIO specify integrated glass modules that merge structural rigidity with thermal management, creating dedicated supply relationships with furnace operators running low-carbon fuel blends.
- Passenger Vehicles:High-volume production runs favor standardized tempered side-window formats with minimal customization.
- Commercial Vehicles:Fleet operators unbundle glass replacement from comprehensive maintenance contracts, creating direct procurement relationships with regional fabricators.
- Heavy Trucks:Windshield replacement intensity exceeds passenger vehicle norms due to extended annual mileage and debris exposure on interstate corridors.
Passenger Vehicles holds the largest share; Electric Vehicles is gaining share fastest.
Technology:
Manufacturing sophistication and embedded functionality create margin stratification.
- Smart Glass:Electrochromic glazing digitizes cabin climate control by enabling real-time tint adjustment without mechanical assemblies. The technology compresses premium sunroof supplier margins as integrated roof panels displace mechanical shade systems in luxury electric SUV segments.
- Low-E Glass:Infrared-reflective coatings reduce thermal load in climate-extreme markets, particularly in Arizona and Nevada where summer cabin temperatures drive specification.
- Automated Production:Robotic handling and optical inspection systems enable wedge-angle precision required for head-up display compatibility.
- Tinted Glass:Absorptive colorants provide cost-effective solar control in price-sensitive vehicle segments.
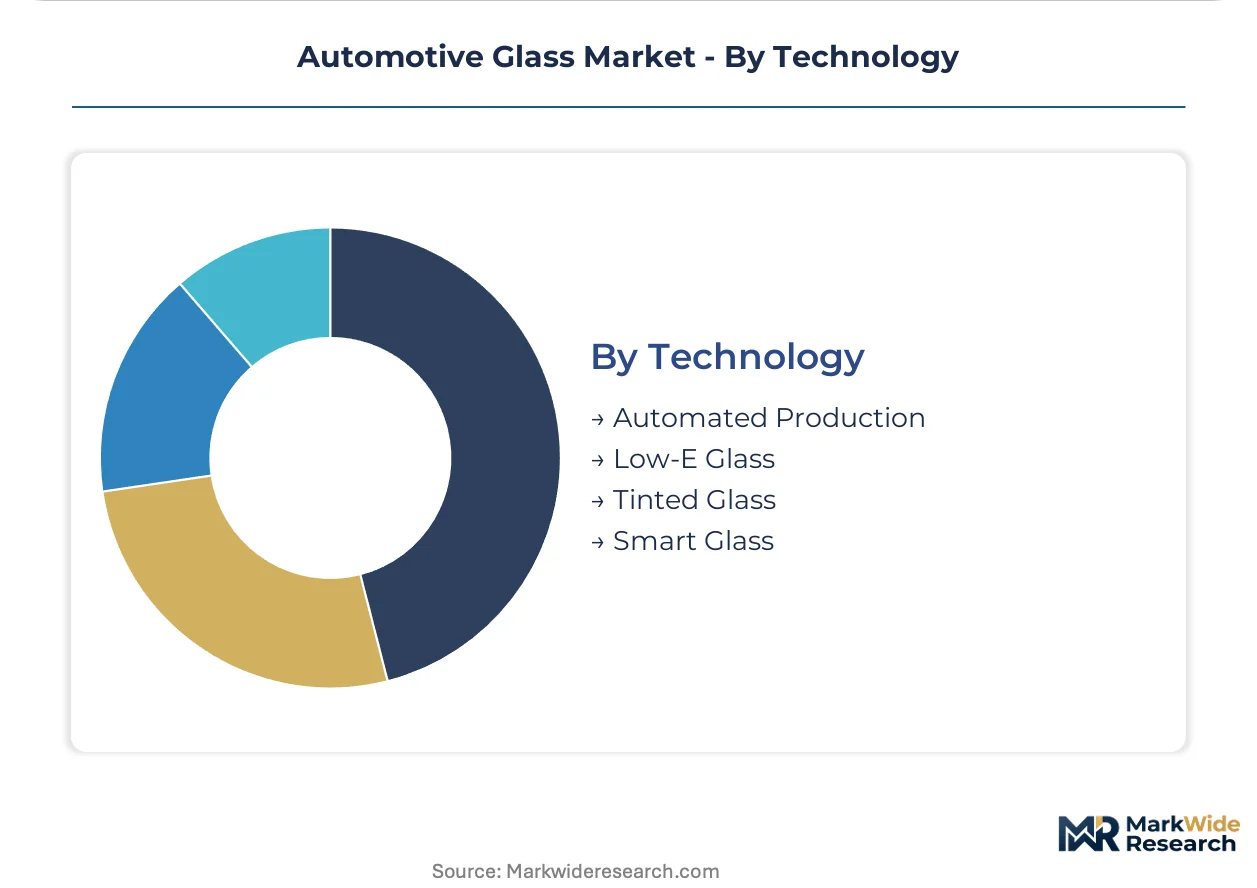
Automated Production holds the largest share; Smart Glass shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German OEM procurement programs exceeds that available to suppliers serving Texas fleet operators by a substantial margin. This asymmetry reflects regulatory stringency divergence and carbon documentation requirements. Market access protocols vary dramatically across certification regimes.
China
BYD and NIO specifications for integrated glass roof modules are pulling capacity investments toward low-carbon float furnaces. GB 9656 national standards govern optical properties and fragmentation behavior for domestic certification. Fuyao Glass anchors supply chains across Fujian and Jilin provinces where furnace-to-fabrication integration dominates.
Germany
Mercedes-Benz and BMW flagship electric sedan programs mandate electrochromic glazing for cabin thermal management. ECE R43 regulations enforce laminated windshield construction with strict wedge-angle tolerances for head-up display compatibility. KBA type-approval processes in Stuttgart extend homologation timelines for Chinese suppliers targeting European OEM procurement.
United States
Fleet operators in Texas and Florida are unbundling glass replacement from comprehensive maintenance contracts, creating direct procurement channels. FMVSS 205 fragmentation standards lock laminated construction for forward apertures. High-purity silica sand extraction in Wisconsin and Illinois faces permitting delays that constrain float glass output expansion.
India
Maruti Suzuki and Tata Motors NEV platforms are attracting laminated glass fabrication investments through PLI scheme incentives. BIS certification requirements align with evolving GB 9656 benchmarks for optical clarity. Industrial clusters in Maharashtra and Gujarat host emerging furnace operations serving domestic electric vehicle assembly.
Japan
Specialized thin-glass formulations for weight reduction anchor supply relationships with domestic OEM platforms. METI industrial standards govern material specifications for advanced driver assistance system compatibility. AGC Inc. maintains fabrication presence in regional clusters supporting precision optical-grade production.
Automotive Glass Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with furnace and interlayer chemistry capabilities. The vendor base concentrates around three strategic archetypes: integrated furnace-to-fabrication operators, premium interlayer compounders, and smart glass technology licensors. Competitive moves center on capacity expansion for laminated glass and strategic partnerships for electrochromic device integration.
Among integrated operators, Fuyao Glass Industry Group and Saint-Gobain exemplify divergent geographic anchoring strategies. AGC Inc. occupies a position within the precision optical-grade segment. Chinese furnace operators represent capital-efficient entrants leveraging asset-light leasing models. Premium interlayer chemistry capabilities concentrate with European compounders navigating REACH SVHC reformulation pressures. Smart glass technology licensure is consolidating around electrochromic-suspended particle device convergence plays.
| Leading Market Players |
|---|
| Saint-Gobain |
| Fuyao Glass Industry Group |
| AGC Inc. |
| Nippon Sheet Glass |
| Xinyi Glass Holdings |
| Guardian Industries |
| Webasto |
| Corning Incorporated |
| Magna International |
| Others |
Supply Flow & Price Mechanics
Polyvinyl butyral interlayer cost volatility compresses both premium tier spreads and laminated glass supply chain configuration, forcing fabricators to choose between long-term offtake contracts with petrochemical suppliers or backward integration into captive interlayer production.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing that stratifies across premium, standard, and economy tiers based on optical-grade certification and head-up display compatibility. Price differentiation stems from ECE R43 compliance tier and wedge-angle precision tolerances. Cost compression in mid-tier laminated windshields is intensifying because annual OEM supply agreements lock producers into fixed pricing while crude oil derivative input costs fluctuate. Fleet operators in commercial vehicle segments demonstrate highest price sensitivity, while German luxury OEM procurement shows lowest sensitivity due to specification stringency.
Supply Chain Analysis
Fuyao Glass and Saint-Gobain hold dominant furnace-to-fabrication capacity across China, Germany, and the United States. Float glass production draws from high-purity silica sand deposits in Wisconsin, Illinois, and Fujian province, plus polyvinyl butyral interlayers from European petrochemical compounders. Single-source vulnerability concentrates in specialized optical-grade laminated capacity for head-up display compatibility. Distribution runs through tier-one fabricator direct relationships with OEM platform engineering teams, bypassing traditional tier-two distributors in NEV segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment through ECE R43 and GB 9656 dual certification creates switching costs that protect incumbent positions.
For Market Incumbents: Harden laminated glass capacity positions in low-carbon float furnace corridors serving BYD and NIO platform specifications. Deepen backward integration into polyvinyl butyral interlayer production to offset petrochemical cost volatility threatening margin stability. Prioritize KBA type-approval pipeline investments to preempt Chinese supplier European market entry. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial clusters present underpenetrated laminated glass fabrication capacity gaps ahead of Maruti Suzuki and Tata Motors NEV platform ramps. Target PLI scheme incentive windows for furnace investments. Pursue direct-to-OEM digital specification platform partnerships to bypass entrenched tier-two distribution channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated furnace-to-fabrication operators with demonstrated dual-certification capabilities. Long-term viability rests on carbon documentation systems aligned with EU Green Deal procurement preferences. Watch hydrogen-enriched natural gas blend furnace adoption rates as inflection signal for low-carbon glass cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Float Furnace Investment | GB 9656-ECE R43 dual certification enables preferential access to German OEM procurement programs. |
| Electrochromic Device Partnership | Mercedes-Benz and BMW flagship electric sedan specifications create premium pricing pools in luxury segments. |
| Backward Integration into Interlayer Production | Captive polyvinyl butyral supply hedges crude oil derivative volatility compressing laminated windshield margins. |
| Direct-to-OEM Digital Platform Launch | CAD-compatible windshield embedding bypasses tier-two distributors in NEV platform development cycles. |
| India PLI Scheme Capacity Expansion | Maruti Suzuki and Tata Motors NEV platform demand attracts furnace investments to Maharashtra clusters. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-one glass fabricator procurement directors, aftermarket distributor network managers, and float furnace operations specialists. Secondary validation incorporated vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed glass manufacturers, and customs trade records for silica sand and interlayer chemical imports. Bottom-up unit economics modeling triangulated against top-down market sizing from automotive glass consumption per vehicle metrics.
Calibration across the analysis window applied segment-specific CAGRs derived from electric vehicle platform penetration curves, panoramic sunroof adoption rates, and head-up display specification diffusion patterns. Modeled dimensions spanned vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. Forecast inputs incorporated float furnace fuel blend transitions and REACH SVHC candidate list expansion timelines affecting interlayer formulation costs.
Practitioners should monitor hydrogen-enriched natural gas furnace adoption rates and REACH authorization timelines for early signals of cost structure inflection. Quarterly review of KBA type-approval queue lengths and PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Plastic Components Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Automotive Key Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive Skid Plate Market