
 Electric Vehicle Motor Communication Controller Market | 2026-2036
Electric Vehicle Motor Communication Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Motor Communication Controller Market Foresight
Software-defined motor calibration is hardening into a recurring revenue layer that reshapes how suppliers monetize hardware deployments. Robert Bosch GmbH leverages its embedded software stack to bundle controller firmware with long-term service agreements. Infineon Technologies AG anchors its position through silicon-level security integration for automotive Ethernet protocols. Denso Corporation competes by extending its thermal management controller expertise into unified powertrain communication platforms.
An electric vehicle motor communication controller coordinates real-time data exchange between the inverter, motor, and vehicle network using protocols such as CAN FD at 2-5 Mbps or automotive Ethernet at 100-1000 Mbps to enable torque vectoring, thermal protection, and predictive maintenance. Integrated Controllers capture the dominant margin pool by combining gate drivers, microcontrollers, and network transceivers in single-package designs that reduce wiring harness weight. Ethernet-based technology segments expand fastest as 800V architectures and multi-motor drivetrains demand higher bandwidth for synchronous control loops. Modular Controllers sustain niche adoption among Tier-1 Suppliers seeking platform flexibility across OEM programs.
The EPA enforces OBD-II and emerging heavy-duty emissions monitoring rules that mandate granular motor performance logging, while the EU AI Act and UNECE WP.29 cybersecurity regulations impose firmware validation and over-the-air update standards on networked controllers. China's MIIT enforces GB/T protocol compliance for domestic EV communication stacks, creating a bifurcated certification landscape for multinational suppliers. Stakeholders must monitor how regional cybersecurity mandates reshape firmware architecture roadmaps and supplier qualification timelines.
Market Dynamics
The transition from 400V to 800V electrical architectures is forcing a wholesale redesign of motor communication controller specifications, as higher voltage platforms demand faster data throughput and more robust isolation barriers to maintain synchronous multi-motor control.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal's powertrain efficiency targets require real-time motor performance telemetry that only advanced communication controllers can deliver, pushing OEMs toward Ethernet-based architectures.
- Electric bus fleet procurement:Municipal and private fleet operators in Germany, China, and the United States are specifying integrated motor communication controllers as standard equipment for new electric bus platforms.
- Automotive Ethernet protocol adoption:The shift to 100-1000 Mbps data rates enables torque vectoring algorithms that legacy CAN FD infrastructure cannot support, creating replacement demand across premium EV segments.
Market Restraints
- Silicon carbide supply concentration:Gate driver integration depends on silicon carbide substrates concentrated among a limited supplier base, exposing controller manufacturers to input cost volatility and allocation risk.
- UNECE WP.29 cybersecurity compliance:Firmware validation and over-the-air update certification requirements impose extended qualification timelines that compress product launch windows for multinational suppliers.
- Legacy CAN FD infrastructure:Existing vehicle network investments in 2-5 Mbps CAN FD architectures create technical debt that slows Ethernet migration in cost-sensitive vehicle segments.
Strategic Opportunities
- Unified thermal-powertrain platforms:Convergence of motor communication controllers with battery thermal management systems creates white space for suppliers with cross-domain firmware expertise.
- EPA heavy-duty emissions monitoring:Emerging OBD-II extensions for commercial vehicles mandate granular motor logging that expands addressable controller volume in the United States truck and bus segments.
- India PLI scheme for automotive electronics:India's production-linked incentive scheme for advanced automotive electronics attracts controller assembly investment targeting domestic EV manufacturing.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification expertise remains concentrated among a limited pool of firmware architects, constraining supplier scaling.
- Multi-protocol firmware architecture:Supporting simultaneous CAN FD, automotive Ethernet, and legacy LIN bus stacks within unified controller designs multiplies validation complexity and defect surface area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Motor Communication Controller Market |
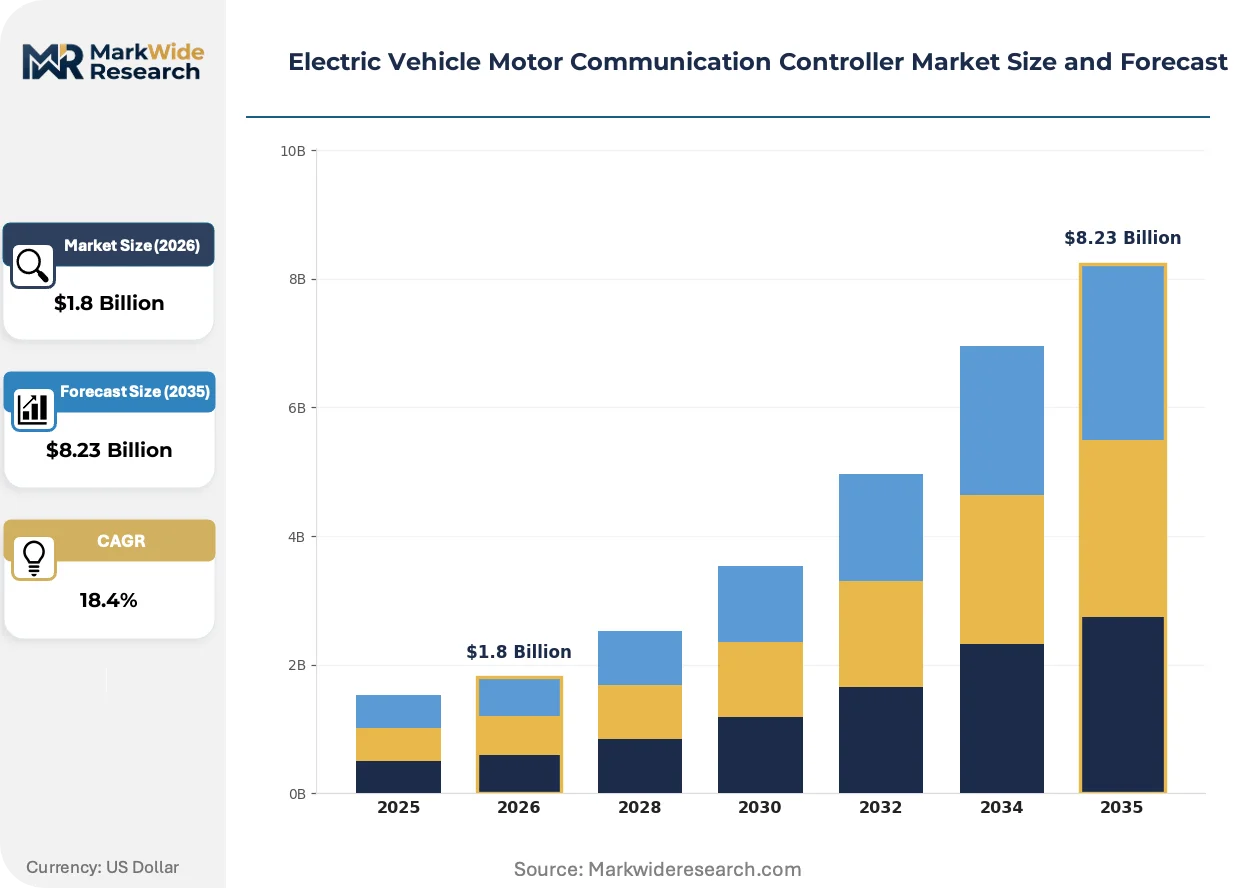
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Battery Management System, Electric Drive Unit, Thermal Management, Fleet Monitoring Technology: CAN Bus, LIN Bus, Ethernet, Wireless Communication End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Charging Station Operators Product Type: Integrated Controllers, Standalone Controllers, Modular Controllers, Hybrid Controllers |
| Companies Covered | LG Innotek, Robert Bosch GmbH, Vitesco Technologies Group AG, Infineon Technologies AG, Denso Corporation, Mitsubishi Electric Corporation, Siemens AG, Vector Informatik GmbH, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Motor Communication Controller Market Shifts & Advancements
Controller hardware is commoditizing faster than suppliers can differentiate through silicon alone, pushing competitive advantage toward firmware-defined feature sets and recurring service revenue models.
Automotive Ethernet at 100-1000 Mbps is absorbing the bandwidth requirements of 800V multi-motor drivetrains that demand sub-millisecond control loop synchronization. Premium EV platforms from German and Chinese OEMs now specify Ethernet-native motor controllers as baseline architecture. This protocol migration is compressing margins for suppliers locked into legacy CAN FD product lines while rewarding early Ethernet adopters with platform exclusivity.
The EU AI Act's firmware validation requirements are reshaping controller development workflows by mandating documented algorithmic transparency for machine-learning-based predictive maintenance functions. Suppliers must now maintain auditable model training pipelines alongside traditional hardware qualification. This regulatory layer most affects integrated controller suppliers targeting European OEM programs, who are responding by embedding dedicated security cores from semiconductor partners.
Fleet operators are consolidating procurement authority for motor communication controllers away from individual vehicle purchasing departments toward centralized technical specifications teams. This buyer concentration forces suppliers to engage directly with fleet technical staff rather than traditional Tier-1 distribution channels. The shift is most visible in United States electric bus procurement, where municipal transit authorities now issue unified controller specifications across multi-year vehicle contracts.
Electric Vehicle Motor Communication Controller Market Segmentation
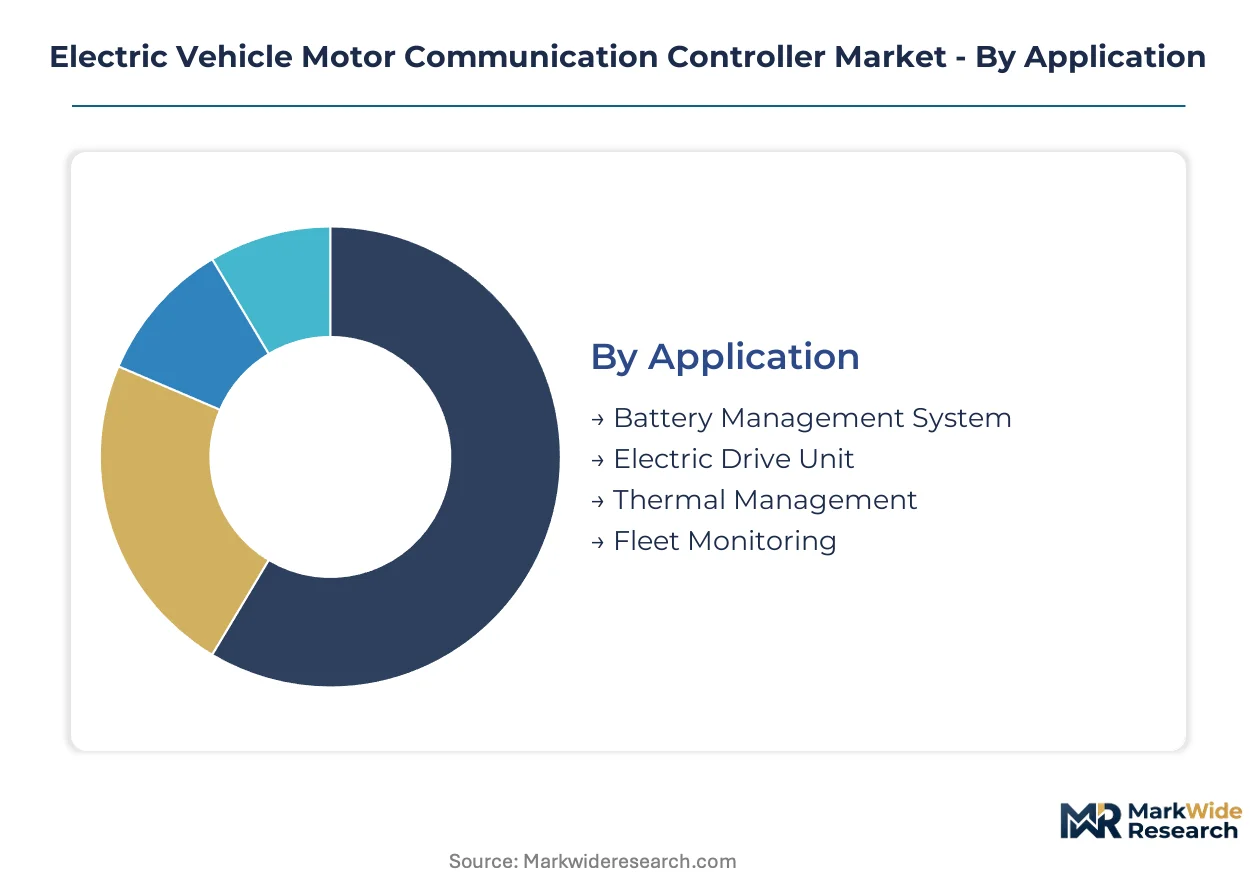
Motor communication controller architectures fragment sharply across voltage platforms and protocol requirements, forcing suppliers to maintain parallel qualification tracks for each segment. OEM procurement teams weight segment selection against 800V migration timelines and regional cybersecurity mandates, creating divergent demand curves within the same vehicle program.
Application:
Supply concentration for application-specific controllers tilts toward integrated powertrain platforms where gate driver and network transceiver sourcing pools overlap most densely.
- Battery Management System:Controllers in this segment coordinate cell-level voltage monitoring with motor torque requests through isolated CAN FD or Ethernet links. Demand clusters in Germany and China where 800V platform launches require synchronized battery-motor communication loops. The EU Green Deal's efficiency telemetry mandates elevate controller complexity for European OEM programs.
- Electric Drive Unit:This segment commands the densest engineering resources, integrating inverter gate drivers with sub-millisecond torque control algorithms. China's MIIT enforces GB/T protocol compliance that bifurcates firmware architectures for domestic versus export programs. Silicon carbide gate driver supply constraints compress margins for multi-motor drivetrain controllers.
- Thermal Management:Controllers bridge battery cooling circuits with motor thermal protection thresholds, typically operating over legacy CAN FD at lower bandwidth requirements.
- Fleet Monitoring:Municipal transit authorities in the United States specify these controllers for predictive maintenance telemetry across electric bus deployments.
Today's leader: Electric Drive Unit. Tomorrow's challenger: Fleet Monitoring.
Technology:
Cost tier differentiation separates premium Ethernet architectures from legacy protocol implementations that sustain volume in price-sensitive vehicle segments.
- Ethernet:100-1000 Mbps data rates enable torque vectoring and multi-motor synchronization that 800V platforms demand. German and Chinese OEMs specify Ethernet-native controllers as baseline for premium EV architectures, rewarding early adopters with platform exclusivity. UNECE WP.29 cybersecurity certification extends qualification timelines for Ethernet stack suppliers.
- CAN Bus:CAN FD at 2-5 Mbps retains dominance in commercial vehicle segments where infrastructure replacement cycles lag passenger EV adoption. EPA OBD-II mandates for heavy-duty emissions monitoring sustain demand for CAN-based logging controllers in United States truck and bus applications. Technical debt in existing vehicle networks slows migration timelines.
- LIN Bus:Low-cost body domain applications employ LIN for non-critical motor auxiliary functions.
- Wireless Communication:Over-the-air firmware update channels drive niche adoption for fleet-managed vehicle populations.
Ethernet architectures are climbing the fastest; CAN Bus maintains installed base defense.
End User:
Volume concentration among OEM direct procurement teams is displacing traditional Tier-1 distribution channels for integrated controller platforms.
- OEMs:German, Chinese, and United States manufacturers specify integrated controllers directly, bundling long-term service agreements with hardware procurement. Robert Bosch GmbH leverages embedded software stacks to capture recurring revenue through firmware-defined feature sets. OEM technical teams now dominate specification authority previously held by Tier-1 suppliers.
- Tier-1 Suppliers:These stakeholders sustain procurement share for modular controller designs that require platform flexibility across multiple OEM programs.
- Aftermarket Providers:Service replacement demand concentrates in legacy CAN FD controller categories.
- Charging Station Operators:Fleet charging infrastructure operators specify communication controllers for vehicle-to-grid coordination.
OEMs hold specification authority; Tier-1 Suppliers retain modular niche defense.
Product Type:
Margin structure favors single-package designs that reduce wiring harness weight and assembly complexity for high-volume EV platforms.
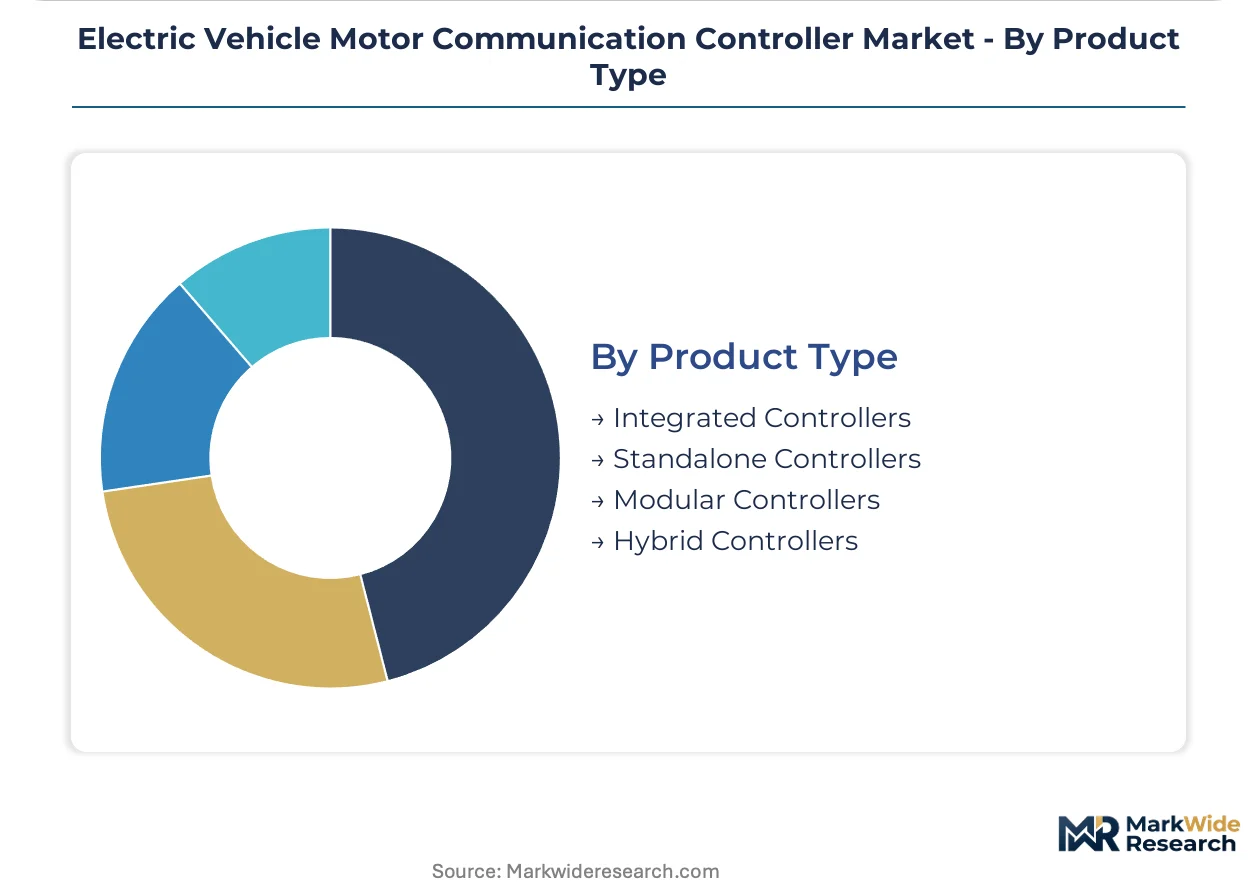
- Integrated Controllers:Gate drivers, microcontrollers, and network transceivers in unified packages capture the dominant margin pool by eliminating inter-component wiring. Infineon Technologies AG anchors position through silicon-level security integration for automotive Ethernet protocols. ISO 26262 ASIL-D certification scarcity constrains supplier scaling.
- Modular Controllers:Tier-1 Suppliers specify these designs where program flexibility outweighs unit cost optimization across low-volume OEM engagements.
- Standalone Controllers:Legacy replacement demand and retrofit applications sustain this category.
- Hybrid Controllers:Transitional architectures bridge CAN FD and Ethernet protocol requirements during platform migration windows.
Integrated Controllers dominate margin capture; Modular Controllers defend flexibility positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing controller manufacturing capacity as suppliers seek jurisdictions with streamlined certification pathways and concentrated EV engineering ecosystems. Cost-of-compliance gaps between cybersecurity regimes are accelerating facility placement decisions.
China
MIIT enforces GB/T protocol compliance that bifurcates firmware architectures for domestic versus export programs. The country's dual carbon goals mandate real-time motor efficiency telemetry across NEV platforms. Engineering clusters in Shanghai and Shenzhen host the densest concentrations of integrated controller R&D for 800V multi-motor drivetrains.
Germany
KBA type-approval requirements and EU Green Deal powertrain efficiency targets elevate controller complexity for European OEM programs. The EU AI Act imposes firmware validation standards on machine-learning-based predictive maintenance functions. Bavaria and Baden-Württemberg anchor Continental Europe's automotive Ethernet engineering corridor.
United States
EPA OBD-II extensions and emerging heavy-duty emissions monitoring rules mandate granular motor performance logging for commercial vehicles. NHTSA cybersecurity guidance shapes firmware architecture requirements for networked controllers. Michigan and California engineering centers concentrate Tier-1 supplier technical specifications authority.
India
The PLI scheme for advanced automotive electronics attracts controller assembly investment targeting domestic EV manufacturing. BIS certification requirements for automotive components create qualification timelines that favor early entrants. Tamil Nadu and Maharashtra industrial corridors host emerging powertrain controller packaging facilities.
Japan
METI carbon neutrality roadmaps accelerate 800V platform development requiring Ethernet-native motor controllers. JIS standards for automotive electrical systems shape domestic procurement specifications. Nagoya and Tokyo metropolitan areas sustain legacy precision manufacturing expertise transitioning to silicon carbide gate driver integration.
Electric Vehicle Motor Communication Controller Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform suppliers capturing margin pools while modular designers defend flexibility positioning. The vendor base concentrates among semiconductor-anchored system houses and Tier-1 powertrain specialists with cross-domain firmware expertise. Three archetypes dominate: silicon-level security integrators, unified thermal-powertrain platform builders, and embedded software stack bundlers. Competitive moves center on strategic partnerships for cybersecurity certification acceleration and capacity expansion targeting 800V architecture qualification pipelines.
Among Germany-based industrial conglomerates, Robert Bosch GmbH and Siemens AG exemplify the integrated platform archetype through embedded software monetization models. Infineon Technologies AG anchors the semiconductor-native tier with silicon-level security integration for automotive Ethernet protocols. Denso Corporation represents Japanese precision manufacturing heritage extending into unified powertrain communication platforms.
| Leading Market Players |
|---|
| LG Innotek |
| Robert Bosch GmbH |
| Vitesco Technologies Group AG |
| Infineon Technologies AG |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Vector Informatik GmbH |
| ABB Ltd. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ASIL-D qualified integrated controllers and uncertified modular alternatives manifests in both pricing premiums and supply chain sourcing patterns. Ethernet-native architectures command hardware-plus-software bundled pricing from direct OEM procurement teams, while CAN FD legacy controllers flow through Tier-1 distribution channels with compressed margins. This bifurcation concentrates margin capture among semiconductor-anchored suppliers with captive firmware stacks while pushing commodity assemblers toward volume-dependent contract structures.
Pricing Analysis
Distributor margins for modular controllers range from 15 to 22 percent, whereas direct-to-OEM integrated platforms bypass channel markups entirely. Three-tier pricing structure across premium Ethernet-native, standard CAN FD, and economy LIN bus tiers reflects certification overhead and bandwidth performance. Cost compression in the CAN FD tier is intensifying because silicon carbide gate driver allocation constraints force suppliers to absorb input volatility. Fleet procurement teams exhibit the highest price sensitivity, while premium EV platform engineers prioritize performance specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States operate hub-and-spoke patterns feeding Tier-1 assembly plants and OEM powertrain facilities. Controller manufacturing draws from silicon carbide substrate suppliers concentrated in Japan and the United States, microcontroller fabrication anchored in Taiwan and South Korea, and automotive Ethernet transceiver production centered in Germany. Single-source vulnerability for silicon carbide gate drivers exposes the supply chain to allocation shocks during 800V platform ramp-ups. Distribution runs through authorized semiconductor distributors serving Tier-1 powertrain integrators, with direct fulfillment emerging for high-volume OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where cybersecurity mandates and emissions telemetry rules generate recurring controller refresh cycles. The EU AI Act's firmware validation requirements and EPA heavy-duty OBD-II extensions collectively expand addressable volume across European and North American commercial vehicle segments.
For Market Incumbents: Acquire ISO 26262 ASIL-D certification expertise through targeted hiring or specialist firm acquisition to defend against firmware architect scarcity. Build captive silicon carbide gate driver relationships with Japanese and United States substrate suppliers to mitigate allocation risk from emerging SiC-dependent entrants. Expand Ethernet-native controller capacity in Baden-Württemberg and Shanghai engineering corridors to capture 800V platform exclusivity windows.
For New Entrants and Emerging Players: Capture fleet monitoring controller specifications from municipal transit authorities in the United States and Germany where centralized procurement authority has displaced traditional Tier-1 channels. Target India's PLI scheme for automotive electronics assembly investment, leveraging BIS certification timelines that favor early entrants over established multinational qualification backlogs. Lead with over-the-air firmware update capabilities as the primary go-to-market wedge against legacy suppliers lacking UNECE WP.29 cybersecurity compliance.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 26262 ASIL-D certification expertise concentrates among a limited pool of firmware architects and functional safety engineering teams. Long-term viability favors integrated platform suppliers with recurring software revenue models over hardware-only assemblers facing margin compression. Watch for silicon carbide substrate allocation shocks as the inflection indicator signaling which controller suppliers have secured upstream supply commitments versus those exposed to spot market volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Ethernet Protocol Migration | 800V multi-motor drivetrains from German and Chinese OEMs demand 100-1000 Mbps bandwidth for sub-millisecond control loops. |
| Silicon Carbide Gate Driver Integration | Single-package designs combining SiC substrates with network transceivers capture dominant margin pools in high-volume EV platforms. |
| Firmware-Defined Service Bundling | Embedded software stacks with long-term service agreements transform hardware deployments into recurring revenue streams. |
| UNECE WP.29 Cybersecurity Certification | Validated over-the-air update capabilities unlock European OEM program eligibility and fleet operator procurement specifications. |
| Unified Thermal-Powertrain Platform Convergence | Cross-domain expertise spanning battery cooling circuits and motor protection thresholds creates white space for integrated suppliers. |
Research Methodology
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each region's engineering clusters and regulatory environments. The analysis combines structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, semiconductor distribution channel managers, and fleet technical specification teams with secondary validation from MIIT GB/T protocol filings, EPA OBD-II regulatory dockets, EU AI Act implementation guidance, and vehicle production databases. Bottom-up segment sizing triangulates against top-down powertrain controller content-per-vehicle estimates across passenger and commercial EV platforms.
Granularity-level modeling disaggregates volume and value outputs by application, technology protocol, end-user procurement channel, and product type architecture across the projection horizon. The analytical framework derives CAGRs from segment-specific adoption curves for 800V electrical architectures, automotive Ethernet penetration rates, and fleet electrification timelines. Industry-specific forecast inputs include silicon carbide substrate supply allocation forecasts, UNECE WP.29 cybersecurity certification pipeline data, and regional EV production cluster capacity expansion announcements.
Supply allocation shocks, cybersecurity certification delays, and regional protocol fragmentation are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions regarding 800V platform ramp schedules, semiconductor foundry capacity commitments, and regulatory enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market