
 Global Automotive Fifth Wheel Coupling Market | 2026-2036
Global Automotive Fifth Wheel Coupling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Fifth Wheel Coupling Market Intelligence
The integration of sensor-based automatic locking mechanisms is rewriting the safety and operational standards for heavy-duty vehicle articulation. JOST Werke AG leverages its extensive R&D in this area to offer advanced, sensor-equipped systems. SAF-Holland competes through its global distribution network and a focus on lightweight forged aluminum components. Meanwhile, Fontaine Fifth Wheel differentiates with its specialized no-slack designs for severe-duty applications in North America.
An automotive fifth wheel coupling is a mechanical linkage used to connect a semi-trailer to a tractor unit. These components, often made from cast steel or forged aluminum, must withstand significant kingpin load and dynamic forces. Cast steel variants continue to dominate the market for heavy-duty hauling due to their durability. The automatic locking technology segment, however, represents the fastest-growing category, driven by fleet operators' focus on safety.
Product design and market access are heavily influenced by safety regulations such as the Federal Motor Carrier Safety Administration (FMCSA) standards in the United States and the Economic Commission for Europe (ECE) Regulation 55. Chinese GB standards also dictate specific performance and material criteria for components sold within its large domestic market. Component selection will increasingly hinge on the ability to integrate with vehicle telematics and emerging autonomous driving systems.
Market Dynamics
The fundamental market dynamic is the tension between the established demand for high-durability cast steel components and the regulatory-driven imperative to integrate advanced, sensor-based safety technologies, a shift reshaping product development and fleet procurement criteria.
Growth Catalysts
- Regulatory Mandates:Stricter safety standards, including the FMCSA regulations in the US and ECE Regulation 55 in Europe, compel fleet operators to adopt fifth wheels with enhanced locking and safety features, driving both new equipment sales and retrofitting.
- Freight Network Expansion:The build-out of logistics and freight distribution infrastructure, particularly across China, fuels demand for new tractor-trailer units, with local GB standards dictating component specifications and boosting domestic production volume.
- Telematics Integration:The push for data-driven fleet management creates demand for fifth wheels equipped with sensors that can integrate with vehicle telematics systems to provide real-time coupling status, reducing accidents and improving operational oversight.
Market Restraints
- Raw Material Volatility:Component manufacturers face margin pressure from the fluctuating costs of key inputs, primarily cast steel and forged aluminum, making long-term pricing and cost control difficult.
- Long Replacement Cycles:The exceptional durability and long service life of traditional cast steel fifth wheels, especially in heavy-duty applications, restrain the market's overall growth rate by slowing the pace of replacement and technology adoption.
- Fragmented Global Standards:The lack of harmonization between major regulatory regimes like US FMCSA, European ECE, and Chinese GB standards forces manufacturers to engineer and certify distinct product variants, increasing R&D and compliance costs.
Strategic Opportunities
- Autonomous Trucking Integration:The development of autonomous driving systems for heavy-duty trucks creates a significant opportunity for intelligent fifth wheel couplings that can automate the coupling process and provide critical data to the vehicle's control unit.
- Aftermarket Upgrades:A substantial opportunity exists in the aftermarket, particularly in emerging economies, to supply fleets with modern, safer coupling systems to replace aging, non-compliant components on existing trucks.
- Lightweight Material Development:Continued innovation in high-strength, lightweight composites or advanced aluminum alloys that can match the load-bearing capacity of steel offers a path to creating a new premium product tier focused on fuel efficiency.
Industry Challenges
- Systems Integration Complexity:A primary operational challenge is ensuring seamless interoperability between new sensor-equipped fifth wheels and the wide array of proprietary fleet management software and vehicle telematics platforms used by customers.
- Certification Delays:The extensive and time-consuming testing required to achieve certifications, such as ECE R55, for new designs incorporating electronic components can create significant delays in bringing innovative products to market.
- Skilled Technician Scarcity:The growing complexity of fifth wheel systems, combining advanced mechanical engineering with electronics, creates a shortage of maintenance technicians who possess the dual skill set required for proper diagnosis and repair.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Fifth Wheel Coupling Market |
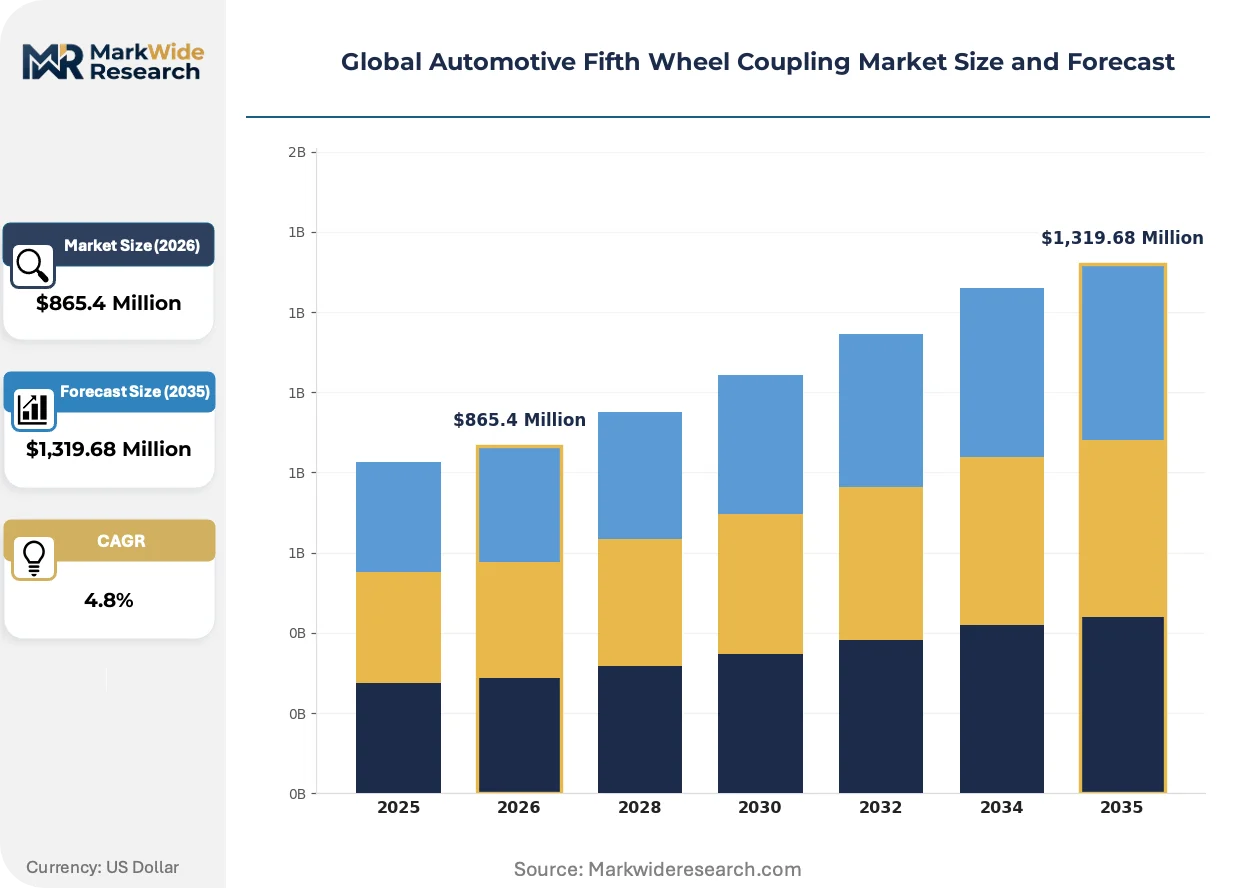
| Market Size in 2026 | $865.4 Million |
| Market Size in 2035 | $1,319.68 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Steel, Forged Aluminum, Composite, Steel Alloy, Cast Iron Technology: Manual Locking, Automatic Locking, Semi-Automatic Locking, Hydraulic Assist, Pneumatic Assist Application: Long-Haul Transport, Heavy-Duty Hauling, Trailer Manufacturing, Freight Distribution End User: Logistics Companies, Transportation Service Providers, Fleet Operators, Truck Assemblers |
| Companies Covered | JOST Werke AG, SAF-Holland, Fontaine Fifth Wheel, Guangdong Fuwa Engineering Group, RSB Group, Tulga Fifth Wheel, Zhenjiang Baohua Semi-Trailer Parts, TITGEMEYER, Hunger Hydraulics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Fifth Wheel Coupling Market Strategic Shifts & Innovations
The evolution from a purely mechanical component to an intelligent, data-generating node within the vehicle's safety and telematics ecosystem defines the market's current trajectory. This transformation is driven by a convergence of regulatory pressure for greater road safety and operational demands for improved fleet efficiency.
Sensor-Equipped Systems: Automatic locking mechanisms with integrated sensors provide fleets with electronic confirmation of a secure kingpin connection, directly addressing a common source of human error. Large logistics operators in North America and Europe are leading the adoption to mitigate accident risk and document safety compliance. The component's value proposition is migrating from a focus on mechanical strength to one where electronic verification and data logging capabilities are becoming essential.
Regulatory Enforcement: Germany's Kraftfahrt-Bundesamt (KBA), enforcing ECE Regulation 55, imposes stringent performance and failure-mode testing on all fifth wheel components sold in the region. This forces manufacturers to invest heavily in material science and fatigue analysis to guarantee component integrity under extreme stress. The dominant cast steel product segment, in particular, must continuously validate its designs through rigorous testing to maintain market access across Europe.
Total Cost of Ownership: Fleet procurement decisions are increasingly guided by total cost of ownership calculations that weigh initial price against maintenance requirements and potential downtime. This shift moves the purchase criteria away from the cheapest available component and toward systems offering extended service life or reduced maintenance, such as those with specialized no-slack locking technologies. This behavior is most pronounced within the highly competitive long-haul freight sectors of the United States and Canada.
Global Automotive Fifth Wheel Coupling Market Segmentation
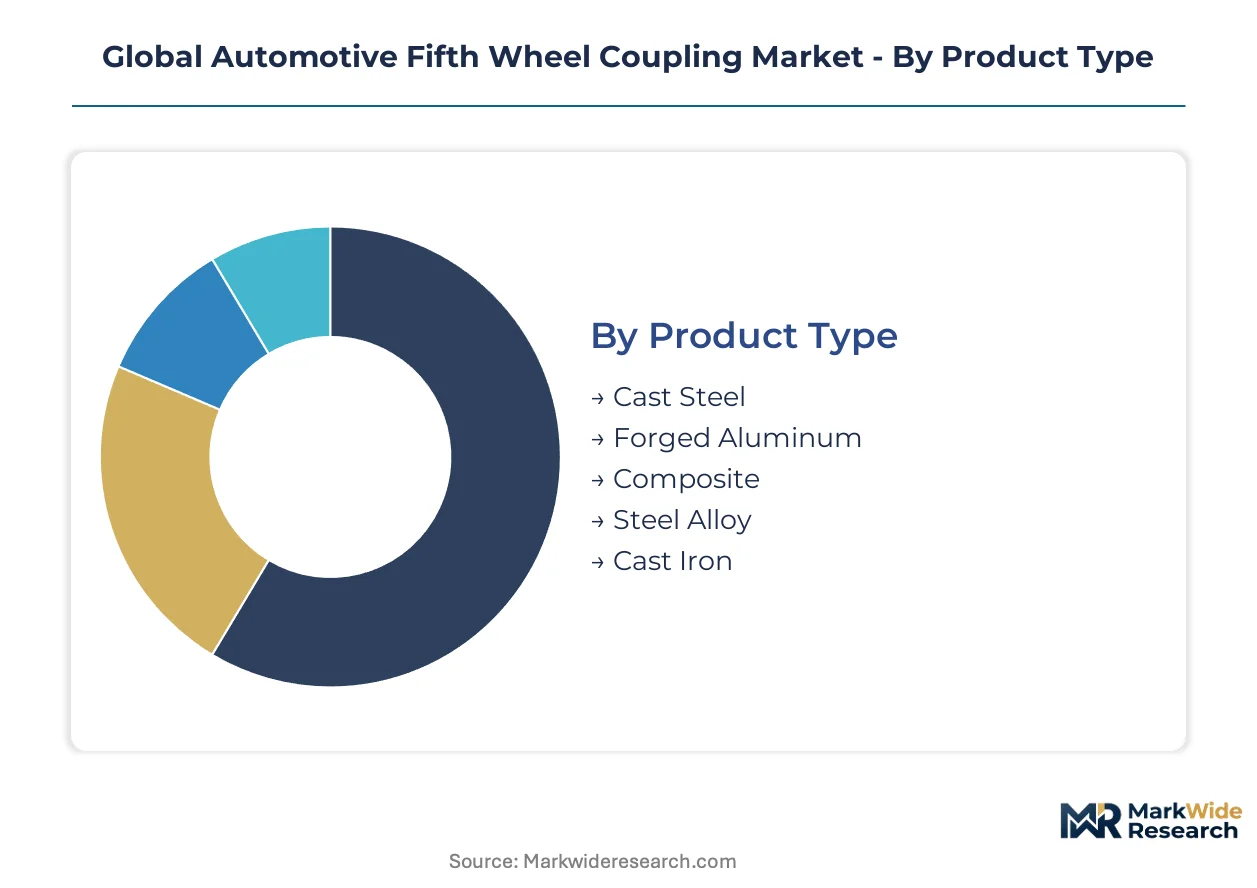
Segmenting the global automotive fifth wheel coupling market reveals varied operational demands and technological preferences across the heavy-duty transport sector. Distinct product types and coupling technologies cater to specific application needs and end-user requirements, influencing design and procurement decisions within the global freight ecosystem.
Product Type:
Fifth wheel product types exhibit varying replacement cycles, influencing procurement decisions from initial purchase to long-term operational costs for fleet owners.
- Cast Steel:These robust components are primarily used for heavy-duty hauling due to their exceptional durability and load-bearing capacity. Demand concentrates in regions with extensive heavy-duty transport infrastructure like North America, driven by the need for longevity and reliability under extreme conditions.
- Forged Aluminum:Offering significant weight savings and corrosion resistance, these couplings contribute to improved fuel efficiency and payload capacity. Adoption is accelerating in Europe and for specialized applications where weight reduction is critical for operational economics.
- Composite:Advanced material solutions providing a balance of lightweight properties and strength for niche applications demanding specific performance characteristics.
- Steel Alloy:Engineered with enhanced strength-to-weight ratios compared to standard steel, these products are utilized for balanced performance and durability requirements.
- Cast Iron:A traditional and cost-effective material choice, often found in less demanding applications or specific regional markets where initial cost is a primary driver.
Cast Steel dominates the installed base. Forged Aluminum is where expansion concentrates.
Technology:
Different fifth wheel technologies present distinct cost tiers, impacting both initial investment and long-term operational expenses for fleet managers.
- Automatic Locking:These systems integrate sensors to provide electronic confirmation of a secure kingpin connection, significantly reducing human error and enhancing safety. Logistics companies in North America prioritize these advanced systems for compliance and operational efficiency.
- Manual Locking:Relying on physical inspection and operator engagement for kingpin connection, this technology represents the traditional and most cost-effective solution. It is widely used across emerging markets due to lower upfront costs and simpler maintenance.
- Semi-Automatic Locking:This category offers partial automation, balancing manual control with some enhanced safety features to meet diverse fleet operational needs.
- Hydraulic Assist:Utilizes hydraulic power to facilitate the coupling and uncoupling processes, easing operator effort, particularly in scenarios requiring frequent trailer changes.
- Pneumatic Assist:Leverages air pressure for coupling assistance, often integrated with existing vehicle air systems for convenience and reduced physical strain on operators.
Automatic Locking technology is gaining significant market share. Manual Locking technology retains a substantial volume presence in global fleets.
Application:
The distribution of fifth wheel coupling applications influences where manufacturing and service capabilities are concentrated globally.
- Long-Haul Transport:Involves sustained highway operations over vast distances, requiring highly durable and reliable couplings that minimize downtime and withstand continuous stress. Demand for these robust components is strong in China due to its expansive freight distribution network.
- Heavy-Duty Hauling:Focuses on moving exceptionally heavy or oversized loads, necessitating fifth wheels with maximum kingpin load capacity and structural integrity. North American and European industries demand specialized products for these demanding tasks.
- Trailer Manufacturing:Integrates fifth wheels as original equipment during the production of new semi-trailers, driving bulk procurement and standardized component specifications.
- Freight Distribution:Involves shorter routes and more frequent coupling/uncoupling cycles, emphasizing ease of operation and durability for urban and regional logistics operations.
Long-Haul Transport drives continuous product innovation. Trailer Manufacturing faces pressure from OEM cost optimization strategies.
End User:
End-user segmentation highlights distinct purchasing behaviors and service expectations that shape product development and distribution strategies.
- Logistics Companies:These entities manage extensive vehicle fleets and prioritize total cost of ownership, integrating advanced telematics-compatible fifth wheels for operational oversight. Major players in Europe and the United States influence product feature sets significantly.
- Fleet Operators:Ranging from small to large enterprises, these customers focus on reliability, safety compliance, and ease of maintenance for their diverse truck populations. Their procurement decisions are influenced by regional safety standards like FMCSA regulations.
- Transportation Service Providers:Offer specialized hauling services, often requiring customized fifth wheel solutions for unique cargo requirements and operational environments.
- Truck Assemblers:Purchase fifth wheels as original equipment for new heavy-duty truck production lines, driving demand for high-volume, standardized components directly from manufacturers.
Logistics Companies are increasingly demanding integrated sensor technology. Truck Assemblers maintain a focus on supply chain efficiency and component standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The movement of goods from manufacturing hubs in China to consumer markets in Europe and North America drives significant demand for robust fifth wheel couplings. This global freight corridor necessitates durable components capable of handling continuous long-haul operations. Regulatory compliance and fleet efficiency are paramount considerations for operators along these routes.
China
Expanding freight distribution networks across China fuel demand for new tractor-trailer units. Chinese GB standards dictate specific performance and material criteria for components sold within its large domestic market. Key manufacturing hubs across China, such as those in Shandong Province, are critical for local production volume.
United States
Logistics companies and long-haul transport fleets in the United States prioritize advanced fifth wheel couplings for safety and operational efficiency. The Federal Motor Carrier Safety Administration (FMCSA) standards compel fleets to adopt enhanced locking and safety features. Major freight corridors originating from industrial centers like Atlanta drive significant component upgrades.
Germany
Stricter safety standards and a strong heavy-duty hauling sector in Germany compel fleets to adopt fifth wheels with enhanced features. Germany's Kraftfahrt-Bundesamt (KBA) enforces stringent performance and failure-mode testing under ECE Regulation 55. Advanced manufacturing facilities in regions like Baden-Württemberg focus on developing high-integrity components.
India
Infrastructure expansion and economic growth in India generate a growing demand for new heavy-duty vehicles. The Bureau of Indian Standards (BIS) sets national requirements for automotive components, influencing local procurement. Automotive manufacturing clusters in Chennai and Pune are key centers for fifth wheel coupling integration.
Global Automotive Fifth Wheel Coupling Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure within the automotive fifth wheel coupling industry. The landscape features a mix of large, diversified component manufacturers and niche innovators focused on specific technologies like automatic locking mechanisms. Strategic partnerships and technology licensing are common competitive moves to accelerate product development. Geographic expansion into emerging markets also represents a significant strategic maneuver for many participants seeking new demand.
Leaders in advanced coupling solutions include JOST Werke AG, a German company leveraging extensive R&D for sensor-equipped systems. SAF-Holland, a global supplier with headquarters in Luxembourg, competes through its wide distribution network and focus on lightweight forged aluminum components. Meanwhile, Fontaine Fifth Wheel, a US-based manufacturer, differentiates its offerings with specialized no-slack designs for severe-duty applications in North America. These entities exemplify the diverse strategic approaches to product innovation and market access.
| Leading Market Players |
|---|
| JOST Werke AG |
| SAF-Holland |
| Fontaine Fifth Wheel |
| Guangdong Fuwa Engineering Group |
| RSB Group |
| Tulga Fifth Wheel |
| Zhenjiang Baohua Semi-Trailer Parts |
| TITGEMEYER |
| Hunger Hydraulics Group |
| Others |
Cost & Logistics Intelligence
Under-capacity in specialized sensor component manufacturing influences supplier pricing power. This dynamic drives material procurement strategies and impacts the cost structure for advanced fifth wheel systems.
Pricing Analysis
The technology-generation pricing gap between advanced automatic locking systems and traditional manual couplings affects procurement decisions. A per-unit transactional model dominates, with price differentiation stemming from ECE R55 certification levels and the use of lightweight forged aluminum materials. Raw material volatility for steel and aluminum places continuous pricing pressure on manufacturers. Logistics companies prioritize total cost of ownership, while fleets in emerging markets remain highly price-sensitive.
Supply Chain Analysis
Commodity price volatility for cast steel and forged aluminum dominates the supply chain risk profile for fifth wheel coupling manufacturers. Geographic supply concentrates in key manufacturing hubs across China and advanced facilities in Germany, drawing heavily from global raw material markets. Component sourcing relies on a network extending from these production centers. Distribution runs through direct channels to truck assemblers and via established aftermarket distributors for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among major logistics companies shifts buyer power within the automotive fifth wheel coupling market. This trend emphasizes reliability and advanced features over initial component cost.
For Market Incumbents: Harden core product lines by deepening telematics integration and investing in advanced material R&D to counter the regulatory-driven shift towards sensor-equipped systems. Secure market access through continuous investment in ECE R55 and FMCSA certification processes, mitigating the threat from new entrants focused solely on cost. Maintain strong OEM relationships through proactive engineering support.
For New Entrants and Emerging Players: Underpenetration in emerging economies for modern, safer coupling systems presents a clear entry point. Target aftermarket upgrades in regions like India, where fleets seek to modernize aging equipment to meet evolving safety standards. Another white-space opportunity exists in specialized heavy-duty applications in North America, leveraging niche design expertise. A focused go-to-market angle involves offering cost-effective, easily retrofittable semi-automatic solutions.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven safety upgrade play because persistent regulatory pressure and fleet efficiency demands will drive continuous innovation. Acquisition targets should focus on niche innovators specializing in sensor-equipped systems or advanced lightweight materials. The market favors entities capable of integrating complex electronics with robust mechanical engineering. A key signal to watch is the pace of autonomous trucking integration into mainstream logistics operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Sensor R&D | Integrates automatic locking with telematics for enhanced safety and operational oversight. |
| Lightweight Material Investment | Improves fuel efficiency and payload capacity for long-haul transport operators. |
| Aftermarket Channel Expansion | Captures demand for modern coupling system upgrades in emerging economies. |
| Regulatory Compliance Acceleration | Ensures market access and reduces certification delays for innovative product designs. |
| Autonomous System Partnership | Positions fifth wheels for critical data exchange with future vehicle control units. |
Research Approach
Findings reconcile primary fieldwork against secondary review of NHTSA reports, ECE R55 documentation, and GB standards. This approach integrated insights from interviews with fleet operators, logistics company procurement managers, and OEM engineers. Bottom-up data collection from component manufacturers was triangulated with top-down market assessments.
Forecast inputs consider freight network expansion, regulatory mandates, and raw material cost projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, coupling technology, application, and end user. Compound annual growth rates were derived from historical data analysis and projected future market dynamics.
Practitioners should monitor autonomous trucking adoption rates and global trade policy shifts for early signals impacting long-term forecasts. Forecasts reflect assumptions regarding technological evolution and regulatory enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Push Rods Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Global Automotive Composite Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Automotive Pedals Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Axle Market