
 Global Automotive Lead Acid Batteries Market | 2026-2036
Global Automotive Lead Acid Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Lead Acid Batteries Market Intelligence
The unbundling of battery sales from long-term service contracts is realigning choices for large fleet operators and aftermarket distributors. Clarios leverages its extensive distribution network to serve both OEM and aftermarket channels effectively. GS Yuasa International Ltd. specializes in advanced battery technologies for specific vehicle applications, including motorcycles and industrial vehicles. EnerSys competes by offering a broad portfolio that spans automotive, industrial, and defense sectors.
An automotive lead-acid battery is an electrochemical storage device that generates power through a reaction between lead plates and a sulfuric acid electrolyte. These units typically provide a nominal 12-volt output and are engineered primarily for starting, lighting, and ignition (SLI) functions in vehicles. While conventional flooded batteries dominate the aftermarket for older passenger vehicles, Absorbent Glass Mat (AGM) types are gaining share in new models with start-stop systems. The passenger vehicles application constitutes the largest volume segment, whereas commercial vehicles often require more durable, higher-margin battery solutions.
The market operates within a strict regulatory environment focused on lead management and recycling. Mandates from the US Environmental Protection Agency (EPA) and Europe's ECHA under REACH govern material handling and disposal protocols. China's Ministry of Ecology and Environment (MEE) also imposes stringent rules on battery production and collection to meet its environmental targets. Future investment decisions will pivot on balancing production capacity for cost-effective flooded batteries against the rising demand for advanced AGM and EFB technologies.
Market Dynamics
The market's central dynamic is the tension between sustained aftermarket demand for traditional flooded batteries and the capital-intensive manufacturing shift toward Absorbent Glass Mat technologies required by modern vehicles with start-stop and advanced electronics systems.
Growth Catalysts
- Aftermarket Expansion:The large and aging global vehicle parc, particularly in China and Southeast Asia, ensures a consistent, high-volume demand stream for replacement SLI batteries, underpinning market stability regardless of new vehicle sales cycles.
- Start-Stop System Adoption:OEM integration of start-stop functionality to meet fuel economy standards in North America and Europe directly drives the specification of higher-margin AGM and EFB batteries in new passenger vehicles.
- Commercial Vehicle Electrification:Growing electrical loads in commercial trucks for telematics, auxiliary power units, and liftgates necessitate more robust and durable battery solutions, creating a premium segment for heavy-duty lead-acid products.
Market Restraints
- Lead Price Volatility:As the primary raw material, fluctuations in global lead prices on exchanges like the London Metal Exchange directly impact manufacturer cost structures and create margin pressure that is difficult to pass through in competitive aftermarket channels.
- Lithium-Ion Substitution Threat:While not yet cost-competitive for most SLI applications, lithium-ion starter batteries are emerging in high-performance and luxury vehicle segments, representing a long-term technological substitution risk for lead-acid chemistry.
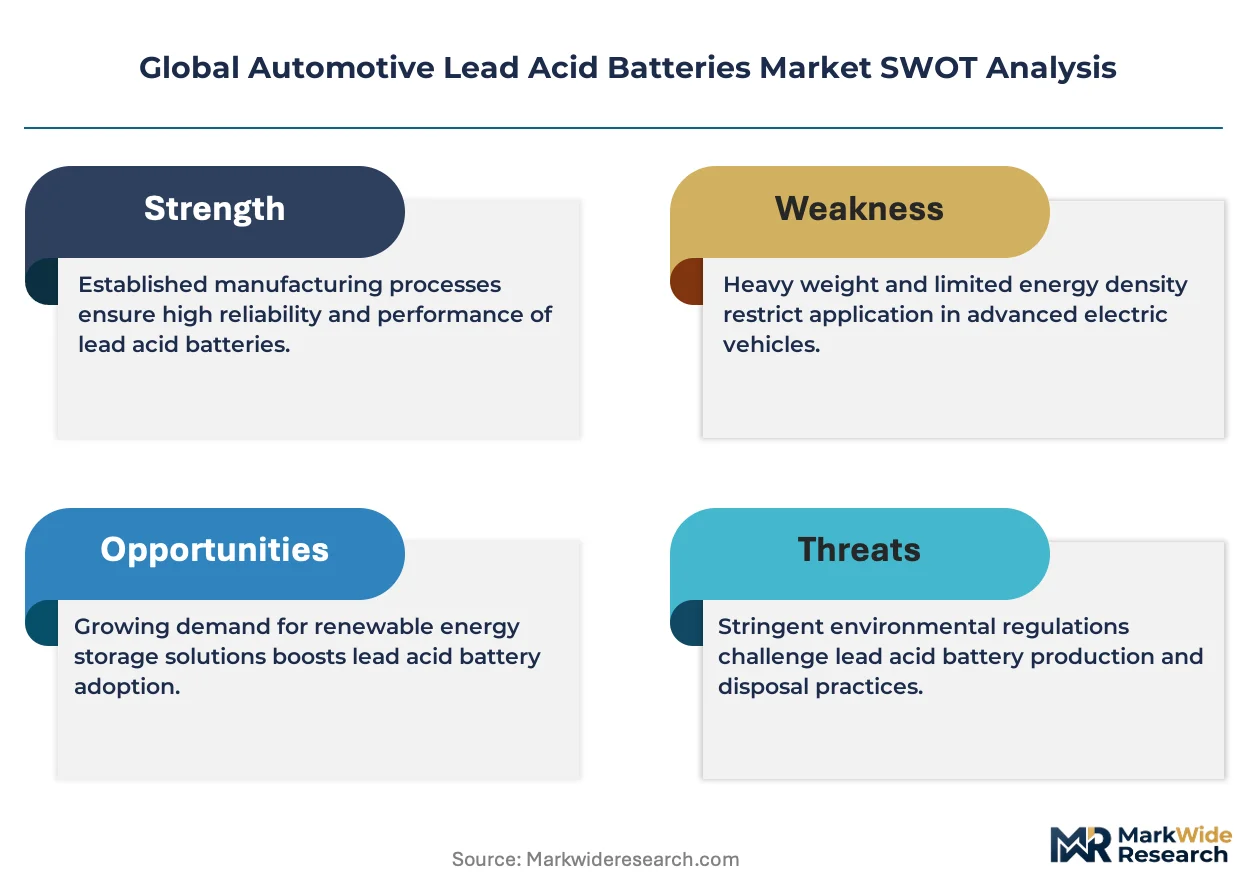
- Stringent Environmental Regulations:Compliance with lead disposal and recycling mandates, such as the EPA's rules in the United States and the EU's REACH framework, imposes significant operational and capital costs on battery manufacturing and collection networks.
Strategic Opportunities
- Enhanced Flooded Battery (EFB) Niche:EFB technology offers a performance upgrade over conventional flooded batteries for entry-level start-stop systems, creating a valuable mid-tier product opportunity between low-cost flooded and premium AGM options.
- Closed-Loop Recycling in Emerging Markets:Investing in modern, environmentally compliant recycling infrastructure in high-growth regions like India and Brazil can secure a stable supply of recycled lead and create a significant competitive advantage.
- Marine and Powersports Applications:Adapting automotive battery designs for adjacent markets, such as marine deep-cycle and powersports SLI applications, allows manufacturers to leverage existing production technologies to enter new, profitable segments.
Industry Challenges
- Dual Production Line Management:Manufacturers face the capital and operational complexity of running parallel production lines for legacy flooded batteries and advanced AGM/EFB types, straining investment budgets and factory floor space.
- Reverse Logistics for Recycling:Establishing and managing efficient, compliant reverse logistics networks for collecting spent batteries from millions of service points is a significant operational hurdle, especially in geographically vast or fragmented markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Lead Acid Batteries Market |
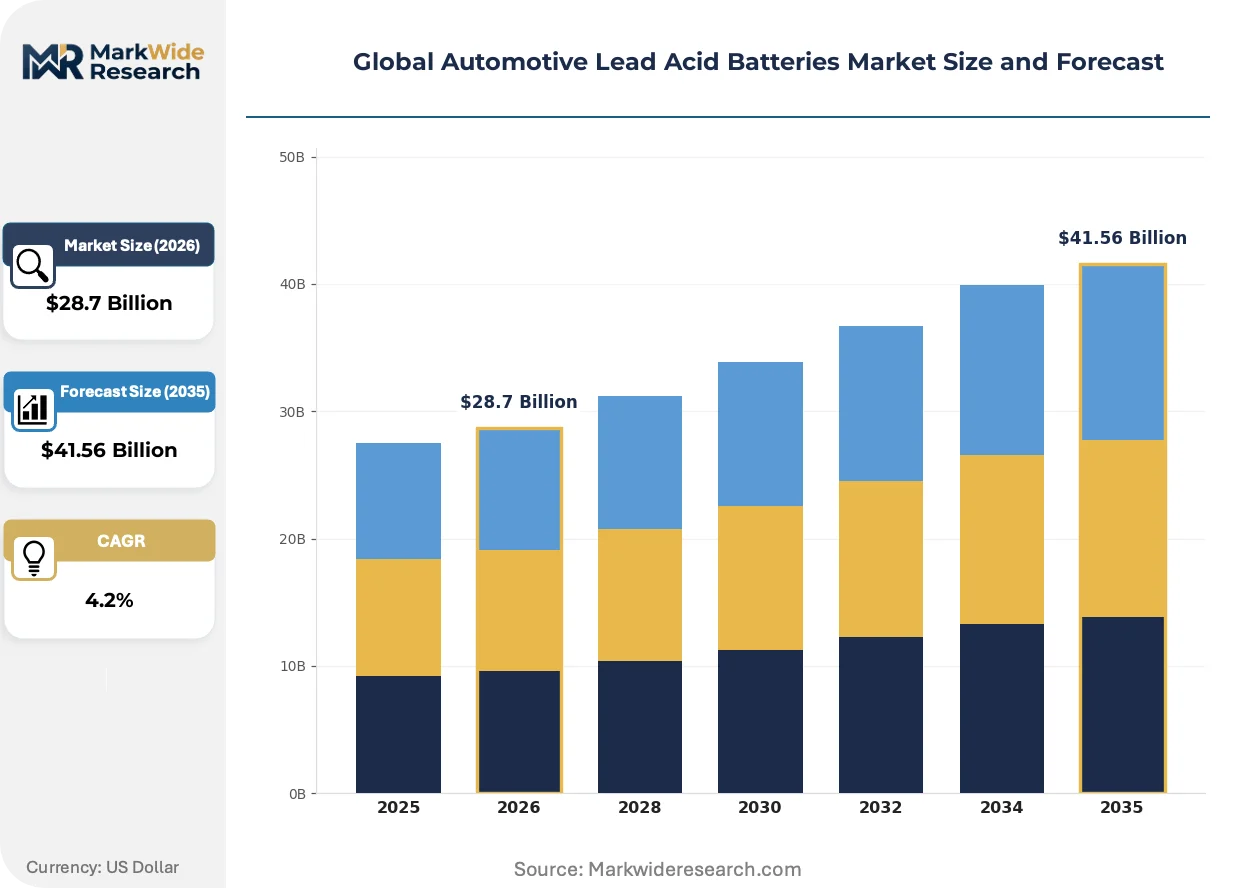
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $41.56 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Flooded, Absorbent Glass Mat, Gel, Enhanced Flooded, Spiral Wound Technology: Conventional, Valve Regulated, Calcium-Calcium, Silver-Calcium, Hybrid Application: Passenger Vehicles, Commercial Vehicles, Off-road Equipment, Marine Vessels, Agricultural Machinery End User: OEMs, Aftermarket Distributors, Auto Repair Shops, Battery Recyclers, Fleet Operators |
| Companies Covered | EnerSys, Clarios, Exide Industries Ltd., GS Yuasa International Ltd., East Penn Manufacturing Company, Johnson Controls, Exide Technologies, C&D Technologies Inc., Camel Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Lead Acid Batteries Market Strategic Shifts & Innovations
The market is bifurcating between a technology-driven original equipment segment focused on advanced battery performance for new vehicle electronics and a cost-sensitive aftermarket segment dominated by replacement demand for conventional passenger and commercial vehicles.
Advanced Battery Management Systems (BMS) are increasingly integrated with AGM and EFB batteries. These electronics monitor the battery's state of charge, health, and temperature to optimize performance. OEMs are the primary adopters for new vehicles with high electrical loads. This integration is automating the diagnostic feedback loop, enabling predictive maintenance and extending battery lifespan in complex start-stop environments.
Europe's updated Battery Regulation is influencing global battery design and supply chain management. The regulation mandates stricter collection targets, minimum levels of recycled content, and a digital "battery passport" to track materials from sourcing to end-of-life. Global battery manufacturers selling into the EU are most affected, forcing them to re-engineer products and invest in transparent, circular supply chains.
Unbundling of battery supply from long-term service contracts is altering purchasing behavior for large fleet operators. Instead of relying on OEM-branded replacements, fleet managers are sourcing batteries directly from aftermarket distributors to lower total cost of ownership. This shift is most prominent within the North American commercial trucking sector, where battery replacement is a frequent and significant operational expense.
Global Automotive Lead Acid Batteries Market Segmentation
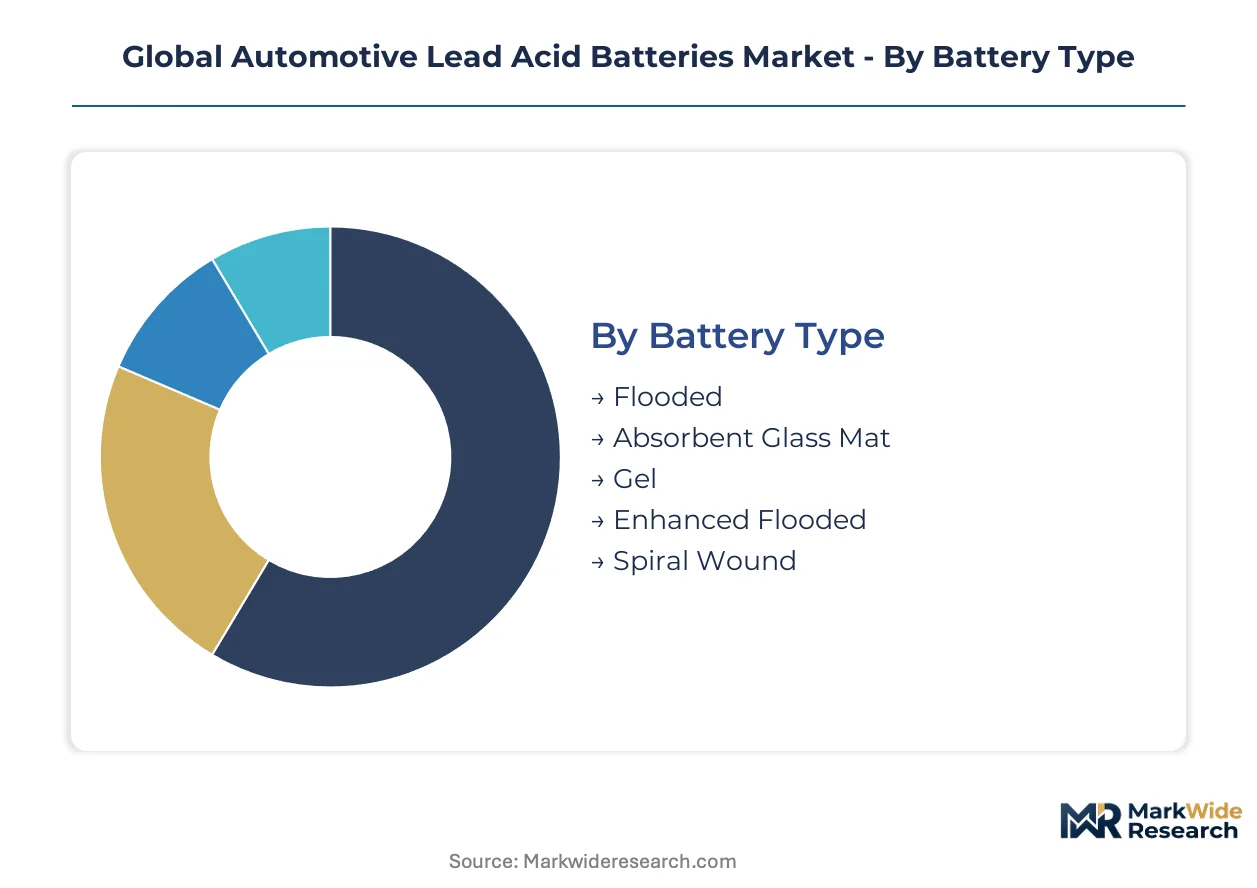
The Global Automotive Lead Acid Batteries Market is analyzed through distinct segments, providing a granular view of product types, technologies, applications, and end-user dynamics. Understanding these divisions helps stakeholders identify areas of concentrated demand and emerging opportunities. This detailed segmentation reveals the specific drivers influencing each market component.
Battery Type:
The supply concentration for automotive lead-acid batteries largely dictates the availability and cost structures across different battery types.
- Flooded:These conventional batteries use liquid sulfuric acid electrolyte, requiring periodic maintenance. Demand concentrates in the aftermarket for older passenger vehicles and cost-sensitive commercial applications.
- Absorbent Glass Mat:AGM batteries feature an electrolyte absorbed in fiberglass mats, offering superior vibration resistance and deep-cycle capabilities. New models with start-stop systems in North America primarily specify AGM.
- Gel:Gel batteries employ a silica-based gelled electrolyte, providing spill-proof operation and improved deep-cycle performance for niche applications.
- Enhanced Flooded:EFB batteries are upgraded flooded cells for entry-level start-stop systems and higher electrical loads in modern passenger cars.
- Spiral Wound:These batteries use spirally wound plates for high cranking power and vibration resistance, found in performance and marine applications.
Flooded batteries absorb the bulk of installed capacity; Absorbent Glass Mat is expanding most quickly.
Technology:
Technology choices in automotive lead-acid batteries are driven by specific vehicle application requirements and performance expectations.
- Conventional:These basic lead-acid designs are simple and lower cost, predominantly serving the replacement market for older vehicle models. Demand remains consistent in price-sensitive regions like Southeast Asia.
- Valve Regulated:VRLA batteries are sealed units preventing electrolyte leakage, suitable for sensitive electronic systems. Adoption is concentrated in new passenger vehicles with advanced start-stop functionality in Europe.
- Calcium-Calcium:These batteries utilize calcium alloys in both positive and negative plates, reducing water loss and improving cold cranking amperage.
- Silver-Calcium:Incorporating silver enhances corrosion resistance and electrical conductivity, extending battery life in premium vehicle segments.
- Hybrid:Hybrid batteries combine features of flooded and VRLA types, balancing performance and cost for diverse automotive applications.
Conventional technology underpins a significant market portion, while Valve Regulated technologies gain share due to evolving vehicle designs.
Application:
Volume dynamics for automotive lead-acid batteries are heavily influenced by the specific application, with passenger vehicles dominating unit sales.
- Passenger Vehicles:This segment includes batteries for cars, SUVs, and light trucks, primarily for SLI functions. It represents the largest volume segment globally, with replacement demand from China being a significant driver.
- Commercial Vehicles:Batteries for heavy-duty trucks, buses, and vans require robust construction and higher capacity due to demanding operational cycles. The North American commercial trucking sector drives demand for durable solutions.
- Off-road Equipment:Batteries for construction, mining, and forestry machinery, demanding high vibration resistance and deep-cycle capabilities.
- Marine Vessels:Batteries for boats and yachts must withstand harsh marine environments and often provide deep-cycle power for auxiliary systems.
- Agricultural Machinery:Batteries for tractors and farm equipment require robust cold cranking power and durability for seasonal and heavy-duty use.
Passenger Vehicles remain the primary consumption segment, with Commercial Vehicles showing strong growth for specialized products.
End User:
Purchasing behavior and technical specifications for automotive lead-acid batteries vary significantly across different end-user customer types.
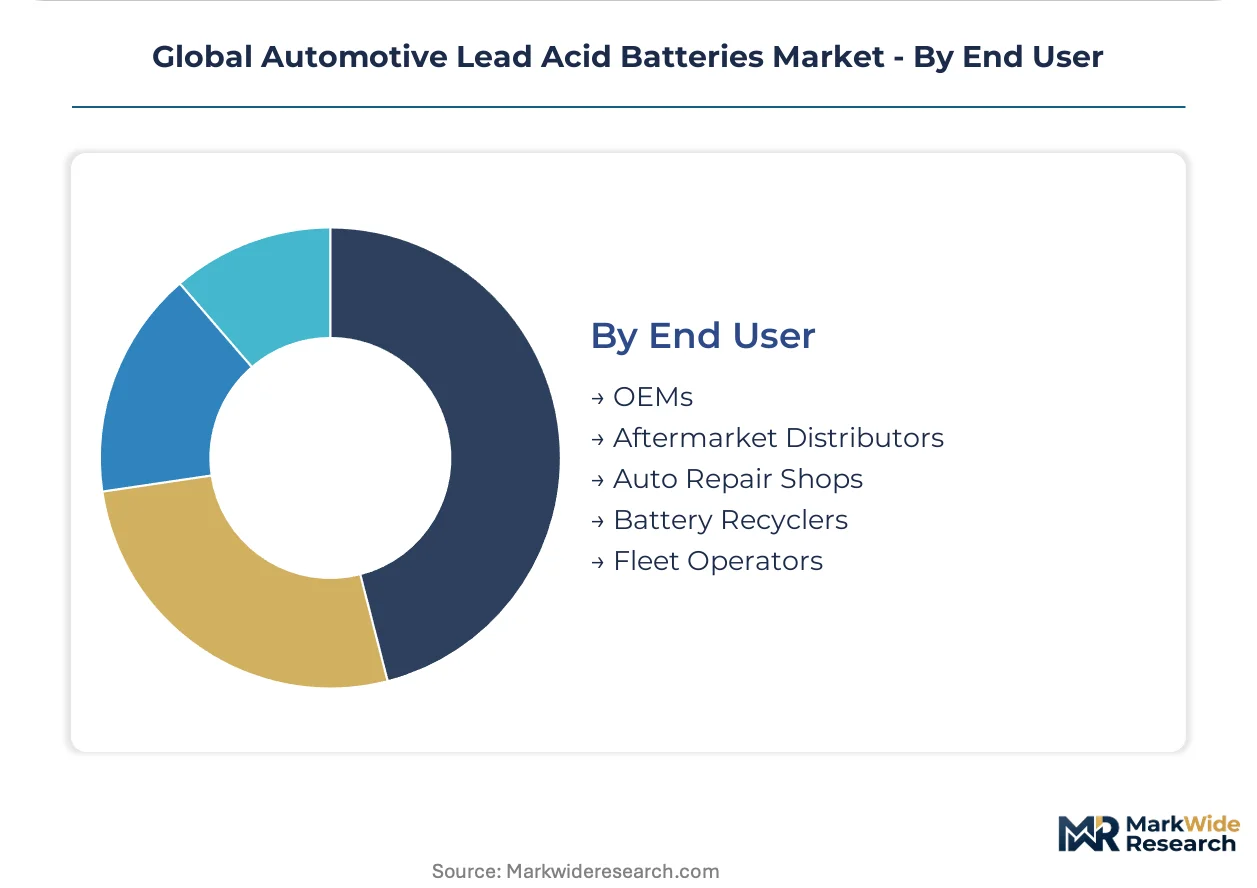
- OEMs:Original Equipment Manufacturers integrate batteries into new vehicles, demanding stringent quality control and specific performance. Their specifications increasingly favor advanced AGM and EFB technologies in Europe.
- Aftermarket Distributors:These entities supply replacement batteries through retailers and service centers, serving the vast installed vehicle base. Demand in this channel is driven by cost-effectiveness for conventional flooded batteries in China.
- Auto Repair Shops:These local service providers purchase batteries for direct installation in customer vehicles, relying on distributor networks.
- Battery Recyclers:These specialized facilities process spent lead-acid batteries, recovering lead and other materials for reuse, crucial for circular economy initiatives.
- Fleet Operators:Large commercial fleets procure batteries in bulk for vehicle maintenance, prioritizing durability and total cost of ownership.
Aftermarket Distributors constitute the largest sales channel, while Fleet Operators increasingly influence procurement for commercial-grade solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's various economic development zones, such as those in the Yangtze River Delta, are concentrating battery production and recycling investments. This strategic focus aims to secure domestic supply chains and meet stringent environmental targets. Market dynamics are influenced by diverse regulatory frameworks and vehicle parc characteristics across key global economies.
China
Aftermarket demand in China for replacement SLI batteries remains a significant volume driver, particularly for older passenger vehicles. The Ministry of Ecology and Environment (MEE) imposes stringent rules on battery production and collection to meet its environmental targets. Industrial clusters in Guangdong and Jiangsu provinces are central to both manufacturing and recycling operations, supporting the large domestic vehicle market.
United States
The United States market is driven by the adoption of start-stop systems in new passenger vehicles and the robust commercial trucking sector. The US Environmental Protection Agency (EPA) mandates strict lead disposal and recycling protocols, influencing manufacturing processes. Automotive hubs in Michigan and the Southeast are seeing increased demand for advanced AGM and EFB technologies for new vehicle integration.
Germany
Germany's automotive sector specifies higher-margin AGM and EFB batteries for new passenger vehicles with advanced start-stop functionality. The EU's REACH framework and updated Battery Regulation influence battery design and supply chain management within the country. Bavaria and Baden-Württemberg, key automotive manufacturing regions, are critical for OEM adoption of advanced battery solutions.
India
India presents sustained aftermarket expansion for traditional flooded batteries due to its large and aging vehicle parc. The Bureau of Indian Standards (BIS) sets quality and safety standards for automotive batteries. Manufacturing facilities in the Chennai-Bengaluru industrial corridor are expanding to cater to both domestic replacement demand and the growing commercial vehicle segment.
Brazil
Brazil's market is characterized by consistent demand for replacement SLI batteries, particularly in the cost-sensitive passenger vehicle segment. The country's environmental regulations, enforced by agencies like IBAMA, govern lead management and recycling. São Paulo and Minas Gerais states host significant automotive manufacturing and aftermarket distribution networks, driving regional consumption.
Global Automotive Lead Acid Batteries Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure for automotive lead-acid batteries. The competitive landscape balances the economies of scale offered by large manufacturers against the specialized offerings of niche players. Companies are increasingly engaging in strategic partnerships and capacity expansion to secure raw material supply and broaden their product portfolios.
Global manufacturers such as Clarios and EnerSys exemplify the industry's drive for broad market coverage and technological leadership. Clarios leverages its extensive distribution network to serve both OEM and aftermarket channels effectively across various geographies. EnerSys occupies a strong position by offering a broad portfolio that spans automotive, industrial, and defense sectors, reflecting a diversified business model. GS Yuasa International Ltd. represents a specialist approach, focusing on advanced battery technologies for specific vehicle applications like motorcycles and industrial vehicles, anchoring a segment requiring tailored solutions.
| Leading Market Players |
|---|
| EnerSys |
| Clarios |
| Exide Industries Ltd. |
| GS Yuasa International Ltd. |
| East Penn Manufacturing Company |
| Johnson Controls |
| Exide Technologies |
| C&D Technologies Inc. |
| Camel Group Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Skilled manufacturing labor concentrations in industrial clusters across China and Southeast Asia generate labor-cost differentials that contribute to varied pricing tiers for automotive lead-acid batteries. These regional cost structures influence global market competitiveness.
Pricing Analysis
Short lead times for advanced AGM and EFB batteries command a premium, while spot inventory of conventional flooded batteries often trades at a discount. The dominant pricing model is per-unit transactional, supplemented by long-term OEM contracts. Price differentiation stems from quality grade, brand premium, and volume scale for fleet operators. Margin softness arises from lead price volatility, which is difficult for manufacturers to pass through in competitive aftermarket channels.
Supply Chain Analysis
Lead supply for automotive batteries centers on mining operations in Australia, China, and the United States, along with secondary recycling sources. Key dependencies include sulfuric acid and specialized fiberglass mats for AGM production. A structural risk involves managing reverse logistics for spent batteries across fragmented markets to meet stringent environmental regulations. Distribution runs through a dual channel of OEM integration and extensive aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive lead-acid battery market is fundamentally a cost-of-compliance story. Europe's updated Battery Regulation, mandating stricter collection targets and recycled content, creates a significant barrier-to-entry moat for non-compliant players.
For Market Incumbents: Anchor existing market share by investing in dual production lines for both traditional flooded and advanced AGM/EFB technologies. This strategy mitigates the threat of lithium-ion substitution while addressing evolving OEM demands. Strengthen backward integration into lead recycling, particularly in emerging markets, to stabilize raw material costs and ensure regulatory adherence.
For New Entrants and Emerging Players: Online direct-to-consumer platforms offer a viable go-to-market angle for specialized battery solutions. Target the underpenetrated marine and powersports segments, or entry-level start-stop systems in price-sensitive regions like India. Focus on differentiated EFB products that offer performance upgrades without the full cost of AGM technology.
For Investors and Strategic Acquirers: Re-rating potential sits with companies demonstrating robust closed-loop recycling capabilities given increasing environmental regulations. The long-term viability of lead-acid batteries for SLI applications remains strong, especially in commercial and aftermarket segments. Target acquisition profiles include firms with established advanced battery R&D or extensive distribution networks in growth regions. A consistent increase in global lead prices warrants ongoing watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for AGM and EFB | Secures supply for automotive OEMs adopting start-stop systems in new vehicle models. |
| Investment in Closed-Loop Recycling | Mitigates lead price volatility and ensures compliance with stringent environmental regulations like REACH. |
| Optimization of Aftermarket Distribution Networks | Enhances reach for replacement batteries, particularly in high-volume markets such as China. |
| Integration of Advanced Battery Management Systems | Differentiates AGM products for high-electrical-load commercial vehicles requiring optimized performance. |
| Portfolio Diversification into Marine/Powersports | Leverages existing SLI technology into adjacent profitable segments with specific performance requirements. |
Research Approach
Trade association data, regulatory filings from the EPA and ECHA, and customs records anchored secondary inputs for this study. Primary research involved interviews with OEM procurement managers, aftermarket distributors, battery recyclers, and fleet operators. This approach ensures a comprehensive market view through both bottom-up and top-down triangulation.
Data-stream reconciliation across multiple sources allowed for robust market sizing and forecasting across the analysis window. The analytical framework modeled segmentation dimensions including battery type, technology, application, end-user, and regional regulatory impacts. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included global vehicle parc growth and start-stop system adoption rates.
Inputs from regulatory bodies, industry associations, and company reports were available through the study window; gaps in real-time raw material pricing data introduce uncertainty bands. Forecasts reflect assumptions regarding technological evolution and market adoption. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Anode Materials Market
Batteries
Wood-Based Batteries Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
PERC Battery Market
Batteries
Industrial Battery Charger Market
Batteries
Custom Battery Pack Market
Batteries
Wide Temperature Battery Market
Batteries
Bio Based Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
UAV Battery Pack Market
Batteries
South America Micro Battery Market
Batteries
Hybrid Flow Battery Market
Batteries
Asia-Pacific Primary Battery Market