
 Asia-Pacific Primary Battery Market | 2026-2036
Asia-Pacific Primary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Primary Battery Market Outlook
Asset-light leasing models for battery procurement are reshaping competitive entry in the Asia-Pacific primary battery sector. Panasonic Corporation leverages its captive material sourcing to sustain cost advantages across Japanese industrial channels. Energizer Holdings Inc. competes through brand-controlled retail shelf positioning in Australian and Southeast Asian supermarkets. GP Batteries International Limited anchors its volume through OEM supply contracts with consumer electronics assemblers in southern China.
Primary batteries are non-rechargeable electrochemical cells delivering single-use power through irreversible redox reactions, typically operating at 1.5V for alkaline systems and 3.0V for lithium manganese dioxide configurations, designed for applications where recharging infrastructure is unavailable or cost-prohibitive. The alkaline product type dominates unit volume across consumer-facing applications due to established manufacturing scale and price accessibility, while lithium batteries command premium positioning in medical devices and industrial sensors where shelf life and energy density determine total cost of ownership. Zinc-carbon batteries retain residual share in price-sensitive rural markets though face structural displacement as alkaline production costs compress.
China's SAMR enforces GB standards governing heavy metal content and labeling, while Japan's METI oversees circular economy directives affecting battery disposal chains across the region. India's BIS certification requirements for imported cells create compliance friction that favors localized assembly operations. Stakeholders must monitor evolving mercury restriction timelines and cross-border waste handling protocols to secure uninterrupted market access.
Market Dynamics
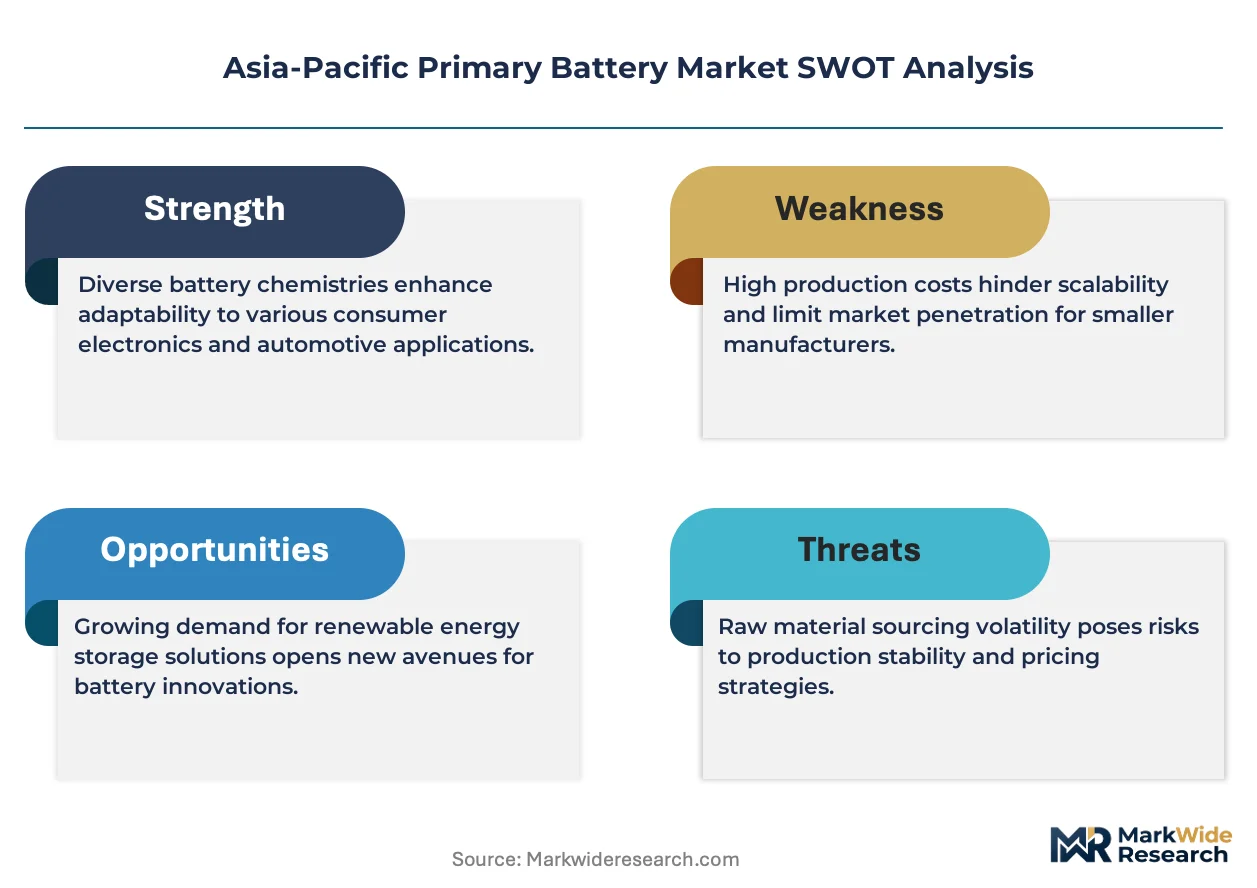
China's GB standards for battery safety and mercury limits are tightening product compliance requirements across the Asia-Pacific primary battery market, forcing manufacturers to reconfigure material sourcing and labeling protocols.
Growth Catalysts
- Medical device electrification:India's medical device segment is scaling orders for lithium primary cells to power portable diagnostic equipment and implantable monitors.
- Rural electrification mandates:India's rural electrification programs are driving alkaline battery demand for off-grid lighting and communication devices in unconnected villages.
- GB 24427-2021 mercury limits:China's SAMR enforcement of stricter heavy metal content standards is accelerating the phase-out of mercury-containing chemistries, favoring compliant alkaline and lithium alternatives.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings for lithium compounds compress margin predictability for premium cell producers serving medical and industrial segments.
- Supply concentration in Japanese material processing:Cathode active material refinement capacity clusters disproportionately in Japan, creating geographic vulnerability for non-integrated assemblers.
- Zinc-carbon residual demand lock-in:Price-sensitive rural markets across Southeast Asia continue purchasing zinc-carbon cells, delaying alkaline conversion despite total cost advantages.
Strategic Opportunities
- Vietnam manufacturing corridor expansion:Industrial equipment buyers across Vietnamese electronics and automotive sensor clusters represent underpenetrated demand for high-drain lithium primary solutions.
- Asset-light leasing models:Battery procurement through operational lease structures rather than capital purchase is opening competitive entry for service-integrated suppliers.
- Japan METI circular economy directives:Extended producer responsibility frameworks for battery collection and recycling create first-mover advantages for compliance-integrated manufacturers.
Industry Challenges
- Cross-border waste handling protocol fragmentation:Inconsistent regulations for spent battery transport between ASEAN member states complicate reverse logistics network design.
- BIS certification timeline compression:India's Bureau of Indian Standards testing queues for imported cells extend lead times, requiring localized assembly investments to maintain delivery commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Primary Battery Market |
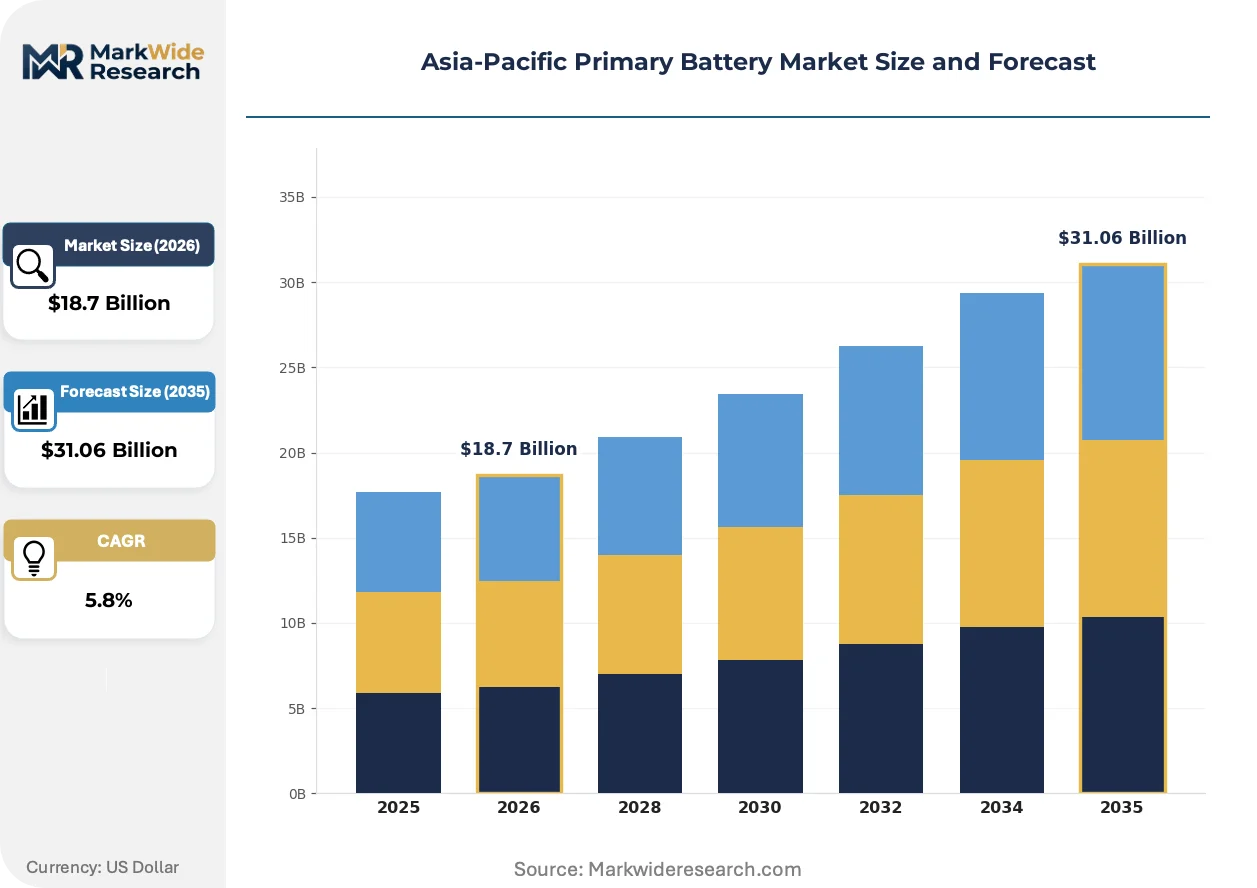
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Batteries, Lithium Batteries, Zinc-Carbon Batteries, Lithium Iron Phosphate Batteries End User: Consumer Electronics, Industrial Equipment, Medical Devices, Automotive Applications Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Application: Emergency Lighting, Toys, Remote Controls, Flashlights |
| Companies Covered | Camelion Battery Co. Ltd, Duracell Inc., Energizer Holdings Inc., FDK Corporation, Panasonic Corporation, Maxell Holdings Ltd., Toshiba Corporation, GP Batteries International Limited, EVE Energy Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Primary Battery Market Strategic Shifts
Electrochemical architecture refinements and procurement model experiments are compressing traditional competitive boundaries across the Asia-Pacific primary battery sector.
Thin-film solid-state lithium primary cells are collapsing the form factor constraints that previously limited power density in micro-medical devices and industrial sensors. Cardiac monitor manufacturers in Japan and South Korea are adopting these configurations at accelerating rates. The technology is collapsing the distinction between implantable and external power solutions, enabling single-cell designs where stacked conventional cells previously dominated.
China's SAMR has tightened enforcement timelines for GB 24427-2021 mercury content limits and GB 31241-2022 safety labeling requirements. Industrial consequence includes mandatory third-party testing for all imported cells and domestic production batches. Medical device assemblers in Shanghai and Shenzhen are responding by qualifying alternative lithium manganese dioxide suppliers ahead of full compliance deadlines.
Industrial equipment buyers across Southeast Asian manufacturing corridors are consolidating procurement through integrated supply contracts rather than spot market purchases. Distributors serving Thai and Indonesian automotive sensor clusters face margin compression as OEMs negotiate direct volume agreements with cell manufacturers. This pattern is most visible in Vietnam's electronics export zones, where contract manufacturers now specify primary battery suppliers in finished product export specifications.
Asia-Pacific Primary Battery Market Segmentation
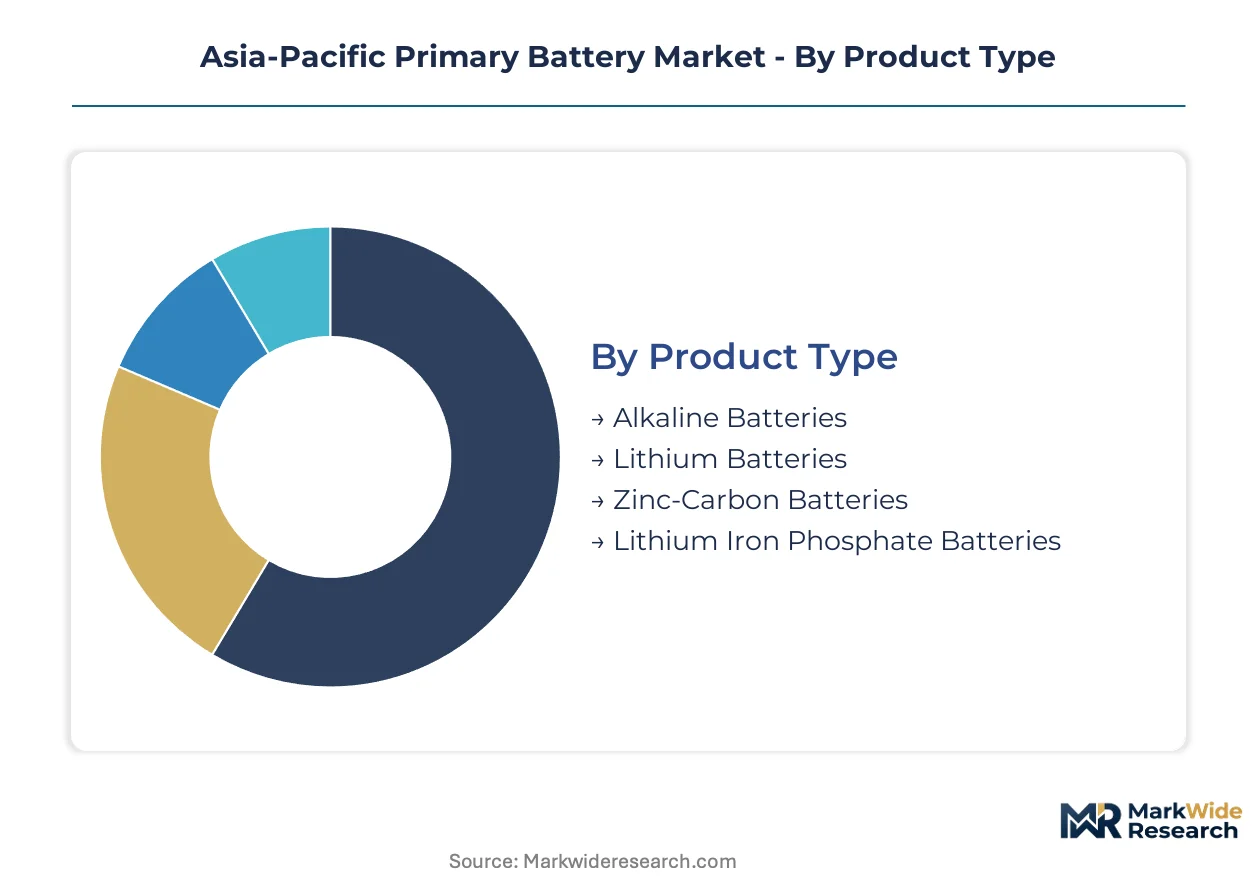
Segmentation in the Asia-Pacific primary battery market reveals divergent replacement cycles and margin structures. Product chemistry determines shelf-life economics, while end-use application dictates volume velocity and regulatory exposure.
Product Type:
Cycle times range from months in high-drain consumer applications to years in long-life industrial deployments. Alkaline and zinc-carbon products turn inventory fastest; lithium configurations sit longest in distribution channels.
- Alkaline Batteries:Manganese dioxide cathode paired with zinc anode delivers 1.5V nominal output through aqueous alkaline electrolyte. Demand concentrates in India's rural electrification programs and Southeast Asian household applications where unit cost accessibility determines procurement decisions. Shelf stability and established manufacturing scale sustain volume leadership across price-sensitive channels.
- Lithium Batteries:Lithium manganese dioxide chemistry achieves 3.0V output with 10-year shelf life and superior energy density. Medical device manufacturers in Japan and South Korea specify these cells for implantable monitors and portable diagnostic equipment where replacement access is limited. Premium positioning reflects total cost advantages in inaccessible deployment scenarios.
- Zinc-Carbon Batteries:Leclanché cell construction with ammonium chloride electrolyte retains residual share in rural Vietnamese and Indonesian markets where absolute price minimization overrides performance metrics.
- Lithium Iron Phosphate Batteries:Olivine cathode structure provides thermal stability and extended cycle tolerance in specialized industrial sensor applications across Chinese manufacturing corridors.
Alkaline dominates installed base. Lithium is where expansion concentrates.
End User:
Cost tier separation is pronounced between consumer-facing commoditized supply and certified medical-industrial procurement. Volume concentrates at the bottom; margin pools at the top.
- Consumer Electronics:OEM supply contracts with southern Chinese assemblers drive alkaline volume through specification control in remote control, toy, and portable audio device manufacturing. Panasonic leverages captive material sourcing to defend position in Japanese consumer channels.
- Medical Devices:Cardiac monitors, implantable sensors, and portable diagnostic equipment in Indian hospitals and Japanese clinics demand lithium primary cells with validated 10-year shelf life and traceable supply chains. BIS certification requirements in India create compliance friction favoring localized assembly investments.
- Industrial Equipment:Vietnamese electronics and automotive sensor clusters represent underpenetrated demand for high-drain lithium solutions in manufacturing automation and predictive maintenance systems.
- Automotive Applications:Tire pressure monitoring systems and keyless entry transmitters in Thai and Indonesian vehicle assembly integrate specified primary cell suppliers into export documentation.
Consumer electronics commands unit volume. Medical devices capture margin expansion.
Distribution Channel:
Customer type determines channel selection—institutional buyers consolidate through direct contracts while household procurement fragments across retail formats.
- Online Retail:E-commerce platforms in Australia and urban India aggregate price-transparent comparison shopping for bulk alkaline purchases, compressing distributor margins through direct manufacturer relationships.
- Supermarkets:Energizer competes through brand-controlled shelf positioning in Australian and Southeast Asian supermarket chains where impulse purchase behavior sustains premium pricing.
- Specialty Stores:Electronics component retailers in Tokyo, Seoul, and Shenzhen serve professional and enthusiast segments with technical specification support and certified product lines.
- Wholesalers:Industrial supply distributors in Bangkok and Jakarta face consolidation pressure as OEMs negotiate direct volume agreements with cell manufacturers for automotive sensor clusters.
Supermarkets dominate household procurement. Online retail is climbing the fastest.
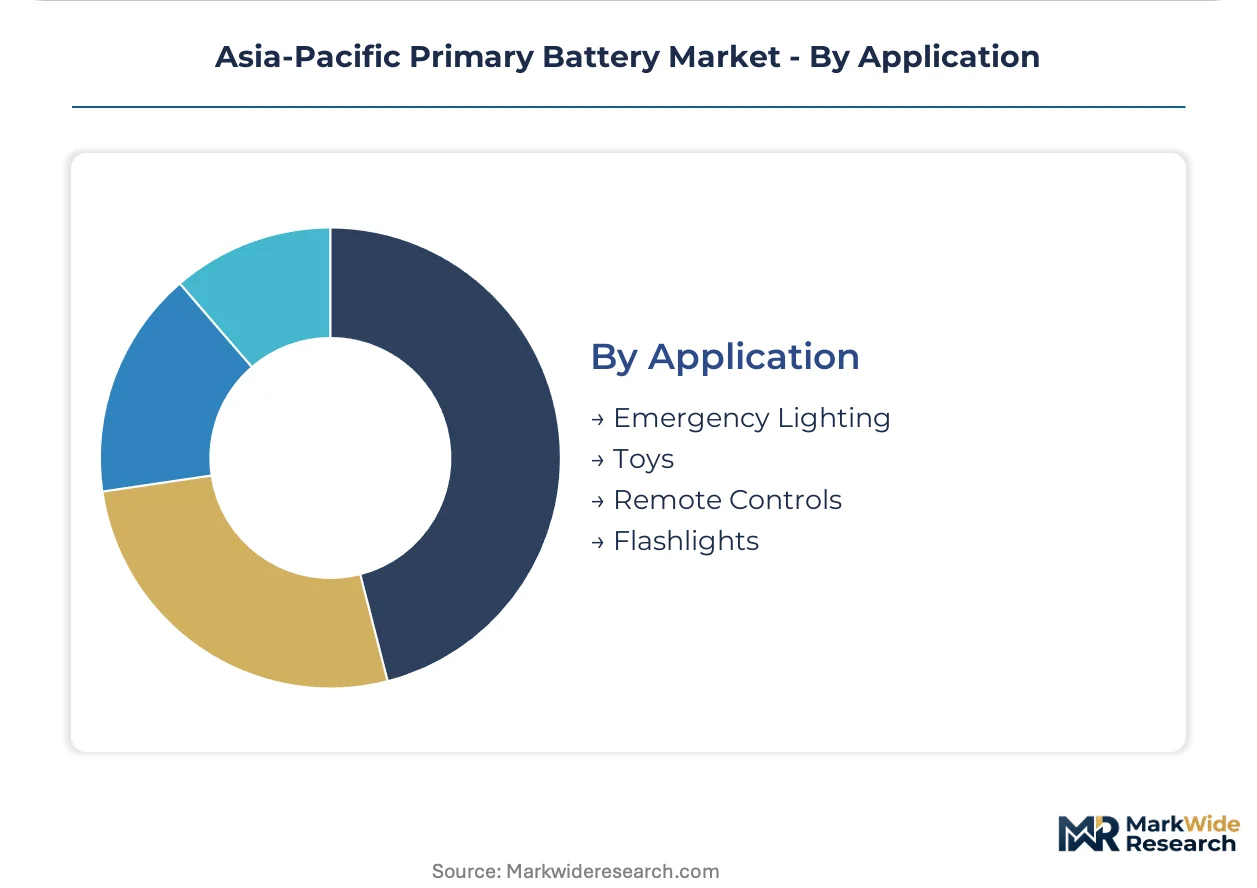
Application:
Maturity varies from saturated toy and remote control segments to expanding emergency preparedness and industrial lighting categories.
- Emergency Lighting:Off-grid backup systems in Indian rural electrification programs and Japanese disaster preparedness mandates specify long-shelf-life lithium configurations with guaranteed activation reliability.
- Flashlights:Industrial safety compliance in Chinese manufacturing facilities and Australian mining operations drives specification-grade alkaline procurement with documented performance certification.
- Toys:Mass-market alkaline consumption in Southeast Asian households experiences seasonal volume spikes tied to festival and holiday purchasing patterns.
- Remote Controls:Low-drain alkaline deployment in consumer electronics experiences gradual displacement as rechargeable alternatives penetrate premium device categories.
Toys and remote controls dominate installed base. Emergency lighting is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial equipment buyers concentrate procurement decisions in four national manufacturing corridors where regulatory frameworks and demand profiles diverge sharply.
China
Medical device assemblers in Shanghai and Shenzhen are qualifying alternative lithium manganese dioxide suppliers ahead of SAMR's GB 24427-2021 mercury limit deadlines. The Yangtze River Delta hosts the region's densest concentration of battery component fabrication, with local firms reconfiguring material sourcing to meet tightened heavy metal content standards.
India
Rural electrification programs in Maharashtra and Gujarat are driving alkaline battery orders for off-grid lighting systems, while cardiac monitor manufacturers in Karnataka specify lithium primary cells for implantable devices. BIS certification queues for imported cells are compressing delivery timelines, prompting localized assembly investments in Tamil Nadu.
Japan
Cardiac monitor and industrial sensor manufacturers in Tokyo and Osaka are adopting thin-film solid-state lithium configurations at accelerating rates. METI circular economy directives for extended producer responsibility are reshaping collection and recycling network economics across the Kanto and Kansai industrial belts.
Vietnam
Electronics export zones in Ho Chi Minh City and Hanoi are consolidating procurement through integrated supply contracts for high-drain lithium solutions. Contract manufacturers now specify primary battery suppliers directly in finished product export documentation, bypassing traditional distributor channels.
Australia
Industrial safety compliance mandates in Western Australian mining operations and Queensland manufacturing facilities are driving specification-grade alkaline procurement. Supermarket chains in Sydney and Melbourne sustain premium pricing through brand-controlled shelf positioning for household battery purchases.
Asia-Pacific Primary Battery Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The structure fragments between scale-driven alkaline producers serving consumer electronics OEMs and premium lithium specialists targeting medical device certification requirements. Three archetypes dominate: captive material integrators, brand-positioned retailers, and contract-manufacturing suppliers. Capacity expansion and compliance-integrated recycling partnerships represent the dominant competitive moves reshaping positioning.
Within the captive material tier, Panasonic Corporation and FDK Corporation exemplify upstream-integrated specialists. Among brand-positioned retailers, Energizer Holdings Inc. occupies a position anchored in supermarket channel control. GP Batteries International Limited represents the contract-manufacturing archetype, sitting within OEM supply relationship networks across southern Chinese electronics clusters.
| Leading Market Players |
|---|
| Camelion Battery Co. Ltd |
| Duracell Inc. |
| Energizer Holdings Inc. |
| FDK Corporation |
| Panasonic Corporation |
| Maxell Holdings Ltd. |
| Toshiba Corporation |
| GP Batteries International Limited |
| EVE Energy Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo container corridor freight rates fluctuate with lithium carbonate spot volatility, compressing margin buffers for non-integrated assemblers while amplifying price differentiation between Japanese cathode material suppliers and Chinese alkaline producers serving rural Indian electrification programs.
Pricing Analysis
Cost-plus contracts with London Metal Exchange zinc indexation dominate alkaline procurement for Indian rural electrification programs, while lithium manganese dioxide supply to Japanese cardiac monitor manufacturers runs through fixed-price annual agreements with volume tier breaks. Price differentiation rests on BIS certification tier and cathode active material provenance. Pricing pressure intensifies in zinc-carbon replacement segments as alkaline production scale economies compress unit economics. Consumer electronics OEMs in southern China exhibit highest price sensitivity; implantable medical device assemblers in Tokyo and Osaka prioritize shelf-life validation over unit cost.
Supply Chain Analysis
Export-control regimes limiting cathode active material processing technology transfer constrain non-Japanese firms from replicating FDK Corporation's material refinement capabilities. Supply concentrates in Japan for high-purity manganese dioxide, China for zinc anode processing and cell assembly, and Australia for spodumene concentrate. Raw material dependencies include lithium carbonate from South American brine operations, electrolytic manganese dioxide from Japanese coastal refineries, and zinc metal from Chinese smelters. Single-source vulnerability clusters in Japanese cathode material refinement. Distribution runs through direct OEM contracts in Vietnamese electronics export zones and supermarket retail chains in Australian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified lithium manganese dioxide supply chains for medical device certification represent the scarcest capability layer, with fewer than six firms globally meeting Japan PMDA traceability requirements for implantable applications.
For Market Incumbents: Build captive cathode material processing moats through backward integration into manganese dioxide refinement or binding offtake agreements with Japanese refiners. Secure BIS pre-certified assembly capacity in Tamil Nadu before India's import testing queues extend further. Defend against emerging solid-state thin-film entrants by accelerating qualification timelines with cardiac monitor OEMs in Tokyo and Seoul. For New Entrants and Emerging Players: Build out asset-light leasing service capabilities targeting Vietnamese automotive sensor clusters where integrated procurement contracts bypass established distributor relationships. Penetrate the underdeveloped high-drain lithium segment for industrial predictive maintenance systems in Ho Chi Minh City electronics zones. Lead with operational expenditure models rather than capital sales to circumvent incumbent specification control. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Japanese industrial conglomerates' battery divisions where non-core positioning and METI compliance investment burdens create divestment pressure. Frame long-term viability around medical device electrification trajectories rather than consumer alkaline volume. Watch for lithium carbonate price stabilization as inflection signal for premium cell margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Material Refinement | Panasonic's captive manganese dioxide sourcing sustains cost advantages against contract assemblers in Japanese industrial channels. |
| BIS-Certified Localized Assembly Investment | Tamil Nadu assembly operations circumvent India's Bureau of Indian Standards testing queues for imported cells. |
| Thin-Film Solid-State Product Qualification | Cardiac monitor manufacturers in Tokyo adopt these configurations to collapse form factor constraints in implantable devices. |
| Asset-Light Leasing Model Deployment | Operational lease structures open competitive entry in Vietnamese electronics export zones where OEMs consolidate procurement. |
| METI Circular Economy Compliance Integration | Extended producer responsibility frameworks for battery collection create first-mover advantages in Kanto industrial belt recycling networks. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with battery procurement managers at Thai automotive sensor OEMs, biomedical engineers at Japanese cardiac device manufacturers, and distribution heads at Australian supermarket chains; and secondary validation through SAMR GB standard filings, Indian BIS certification registries, METI circular economy directive documentation, and trade flow records from Japan Customs. Bottom-up cell shipment estimates by chemistry and end-use triangulated against top-down market value reconstruction.
Forecast inputs span product chemistry evolution, regulatory compliance timeline acceleration, and OEM procurement consolidation patterns across the projection horizon. Segmentation dimensions modeled include cell chemistry tier, end-use certification grade, distribution channel structure, and national regulatory cluster. CAGRs derive from slope analysis of indexed shipment volumes against normalized price trajectories, with medical device electrification rates and rural electrification program execution serving as primary demand-side variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese lithium cell specialists or accelerated solid-state technology commercialization would shift outcomes. Material shifts in SAMR enforcement timelines for GB 24427-2021 mercury limits or lithium carbonate supply contract renegotiation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
48 Volt Battery System Market
Batteries
Iron Flow Battery Market
Batteries
3D-Printed Battery Market
Batteries
Italy Rechargeable Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Rear Rack Battery Market
Batteries
North America Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Nickel Cadmium Battery Market
Batteries
Mobile Battery Market
Batteries
Marine Low-Voltage Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Asia Power Tool Batteries Market
Batteries
Disposable Batteries Market