
 Wide Temperature Battery Market | 2026-2036
Wide Temperature Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Wide Temperature Battery Market Insights
Modular battery pack architectures is restructuring procurement decisions across industrial and mobility buyers, shifting purchasing from standalone cells toward integrated thermal-management systems. Panasonic Corporation leverages its cylindrical cell expertise to anchor premium automotive contracts in cold-climate regions. Saft Group specializes in primary lithium-thionyl chloride designs that dominate aerospace and defense applications requiring operational reliability from minus 60 to plus 150 degrees Celsius.
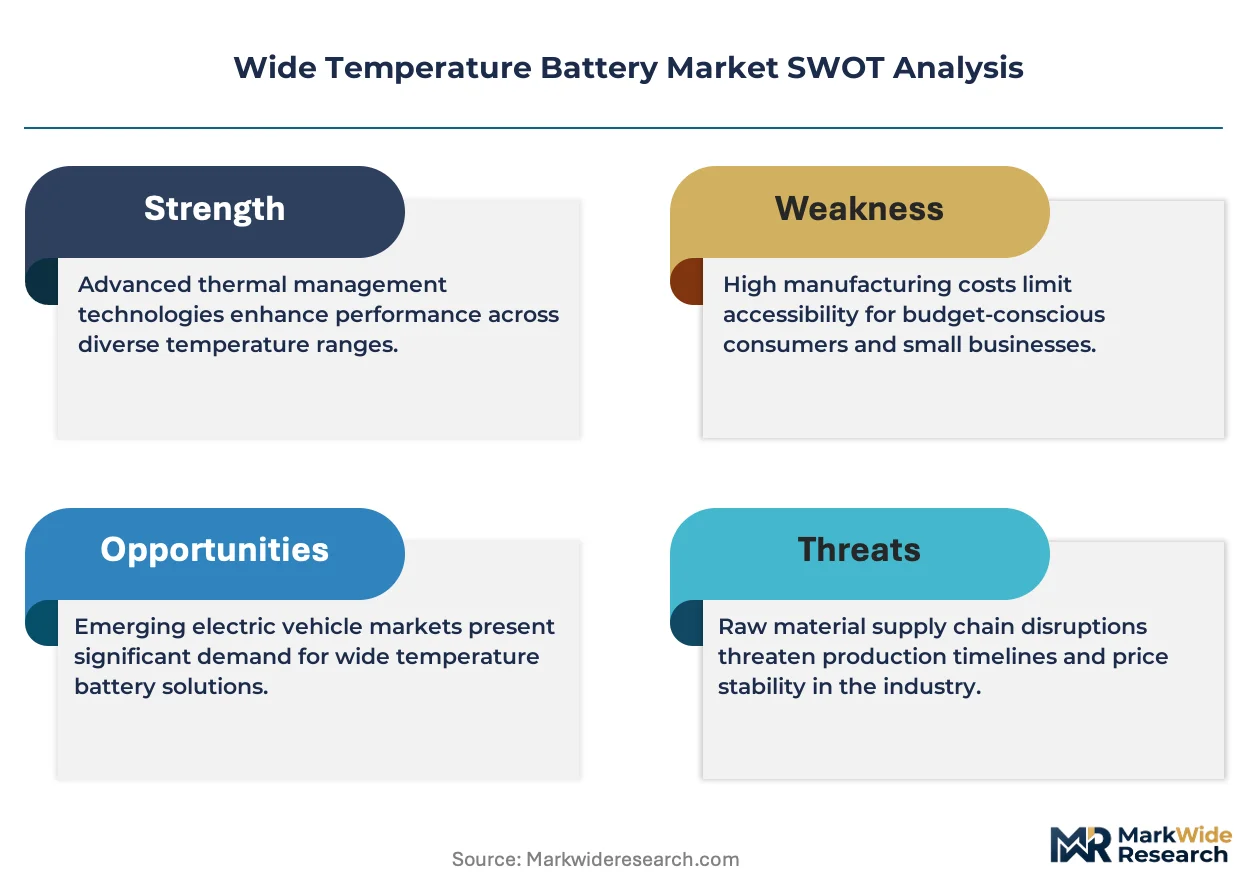
Wide temperature batteries are electrochemical storage devices engineered with specialized electrolyte formulations, advanced separator materials, and thermal management interfaces to maintain stable ionic conductivity and structural integrity across extreme thermal envelopes, typically spanning minus 40 degrees Celsius to plus 85 degrees Celsius or broader. These systems serve mission-critical functions in aerospace telemetry, Arctic logistics fleets, remote renewable microgrids, and industrial automation where standard lithium-ion chemistries experience capacity fade, lithium plating, or electrolyte decomposition. Lithium-ion variants occupy the dominant revenue share due to energy density advantages and declining cell costs, though sodium-sulfur configurations are gaining traction in grid-scale renewable storage for their high-temperature tolerance and raw material abundance. The automotive application segment commands the largest absolute volume as electric vehicle OEMs prioritize cold-weather range retention, while aerospace represents the highest margin pool given certification barriers and low-volume, high-reliability procurement norms.
The EU Battery Regulation and REACH compliance frameworks in Europe mandate carbon footprint disclosure and responsible material sourcing, directly elevating compliance costs for non-integrated suppliers while favoring producers with verified supply chain transparency. In the United States, NHTSA safety standards and FAA certification requirements for aviation batteries impose rigorous thermal runaway propagation testing that limits market entry to established manufacturers with dedicated qualification facilities. Stakeholders must monitor evolving solid-state electrolyte patent landscapes and regional subsidy structures for domestic battery manufacturing to anticipate which chemistries and form factors will secure long-term procurement contracts.
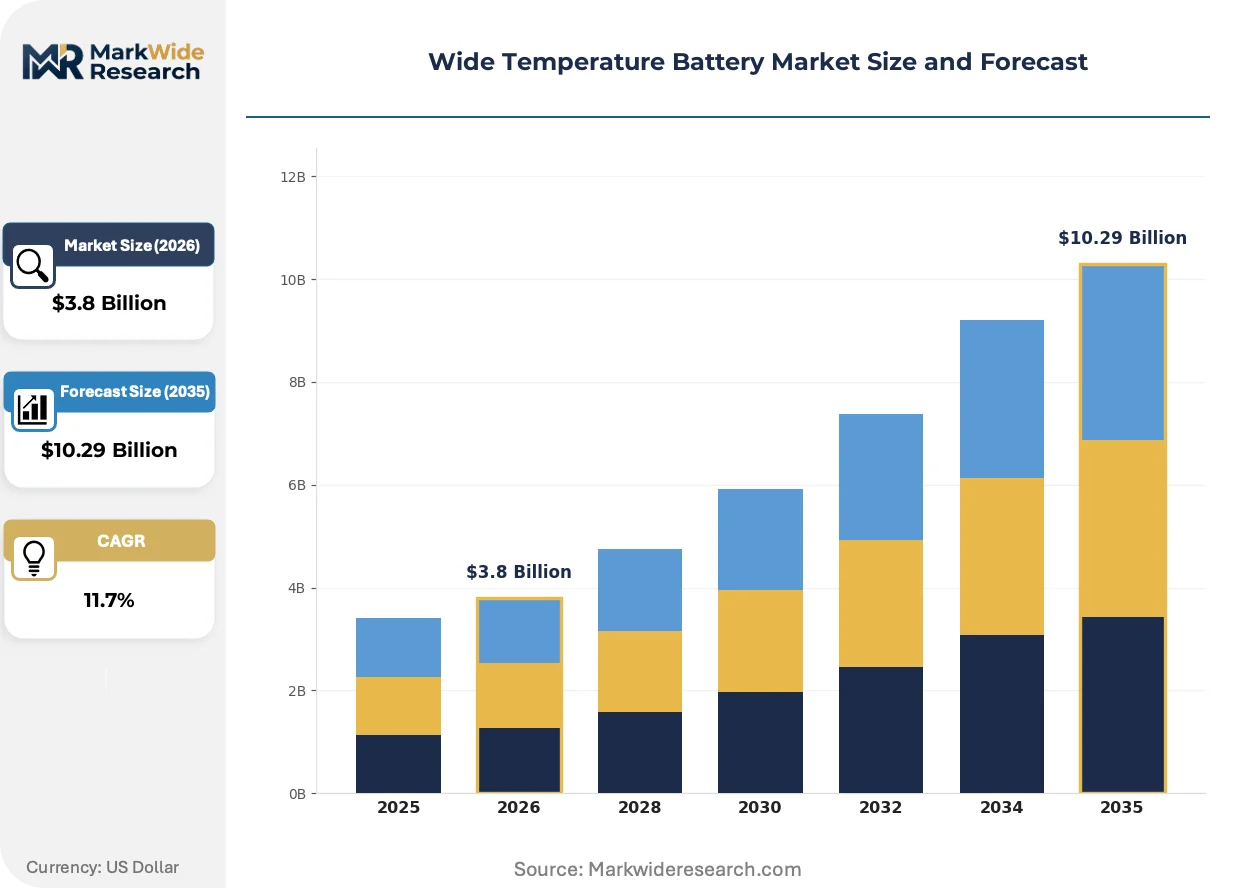
Market Dynamics
Solid-state electrolyte research is restructuring material roadmaps for extreme-temperature tolerance, forcing incumbent lithium-ion suppliers to accelerate qualification timelines or risk displacement in aerospace and Arctic logistics procurement cycles.
Growth Catalysts
- Arctic Fleet Electrification:Electric vehicle OEMs in Norway and Sweden now mandate sub-zero range retention specifications, pulling advanced thermal-management pack designs into series production contracts.
- EU Battery Regulation:Carbon footprint disclosure mandates and responsible material sourcing requirements favor producers with verified supply chain transparency, accelerating consolidation among compliant suppliers.
- Sodium-Sulfur Chemistry:Grid-scale renewable storage developers are piloting high-temperature tolerant configurations for remote microgrids, leveraging raw material abundance to offset lithium supply concentration risks.
Market Restraints
- Lithium Feedstock Volatility:Spodumene and brine supply concentration in Australia and Chile creates input cost instability that compresses margins for non-integrated cell manufacturers.
- FAA Certification Barriers:Aviation battery thermal runaway propagation testing requirements limit market entry to established manufacturers with dedicated qualification facilities, freezing out emerging suppliers.
- Primary Cell Substitution:Lithium-thionyl chloride designs from Saft Group dominate aerospace telemetry applications with operational envelopes spanning minus 60 to plus 150 degrees Celsius, constraining rechargeable lithium-ion penetration in high-reliability niches.
Strategic Opportunities
- Nordic Microgrid Expansion:Norway and Sweden's renewable energy clusters require batteries rated below minus 40 degrees Celsius for off-grid Arctic installations, creating premium procurement channels for qualified suppliers.
- Modular Pack Architectures:Industrial and mobility buyers are shifting from standalone cells toward integrated thermal-management systems, opening design partnerships for subsystem specialists.
- US IRA Domestic Manufacturing Incentives:Production tax credits for domestic battery manufacturing are restructuring investment location decisions, favoring North American facility development for suppliers serving cold-climate automotive fleets.
Industry Challenges
- Solid-State Electrolyte Talent Scarcity:Polymer and ceramic electrolyte formulation expertise resides in limited academic and national laboratory clusters, constraining R&D velocity for commercial scale-up.
- REACH Compliance Timeline Compression:European chemical registration and carbon footprint verification requirements demand documentation systems that many Asian suppliers lack, extending qualification cycles by 12-18 months.
- Patent Landscape Fragmentation:Dispersed solid-state electrolyte IP holdings across Japanese, Korean, and US research institutions complicates freedom-to-operate analysis and licensing negotiations for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wide Temperature Battery Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-cadmium, Sodium-sulfur Application: Automotive, Aerospace, Industrial Equipment, Renewable Energy Storage End User: OEMs, Utilities, Logistics, Consumer Electronics Installation: Fixed, Portable, Modular, Backup |
| Companies Covered | Panasonic Corporation, Tadiran Batteries, Saft Group, EVE Energy, EaglePicher Technologies, NGK Insulators, LG Energy Solution, Ultralife Corporation, XALT Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wide Temperature Battery Market Trends and Innovations
Material science advances and regulatory pressure on carbon intensity are converging to accelerate chemistry diversification beyond conventional lithium-ion architectures, reshaping competitive positioning across temperature-extreme applications.
Solid-state electrolyte technology is converging with silicon-anode architectures to enable energy density gains without thermal runaway risks in sub-zero environments. Automotive OEMs in cold-climate regions are integrating these hybrid configurations into next-generation pack designs. The structural consequence is compression of liquid electrolyte supplier margins as buyers prioritize solid-state qualification partnerships.
REACH compliance frameworks in Europe now mandate full supply chain carbon disclosure for battery cells placed on the market, elevating documentation burdens for non-integrated suppliers. Industrial buyers are screening procurement lists against verified transparency databases, redirecting volume toward producers with captive raw material streams. Grid-scale storage developers face the steepest compliance cost escalation, accelerating preference for vertically integrated European suppliers.
Integrated thermal-management pack procurement is displacing standalone cell purchasing across industrial automation and Arctic logistics fleets. System integrators are capturing margin that previously accrued to cell manufacturers by offering warranty-backed performance guarantees across temperature extremes. This pattern is most visible in Swedish mining equipment electrification programs, where end-users now contract directly for complete energy storage subsystems rather than specifying cell chemistry independently.
Wide Temperature Battery Market Segmentation
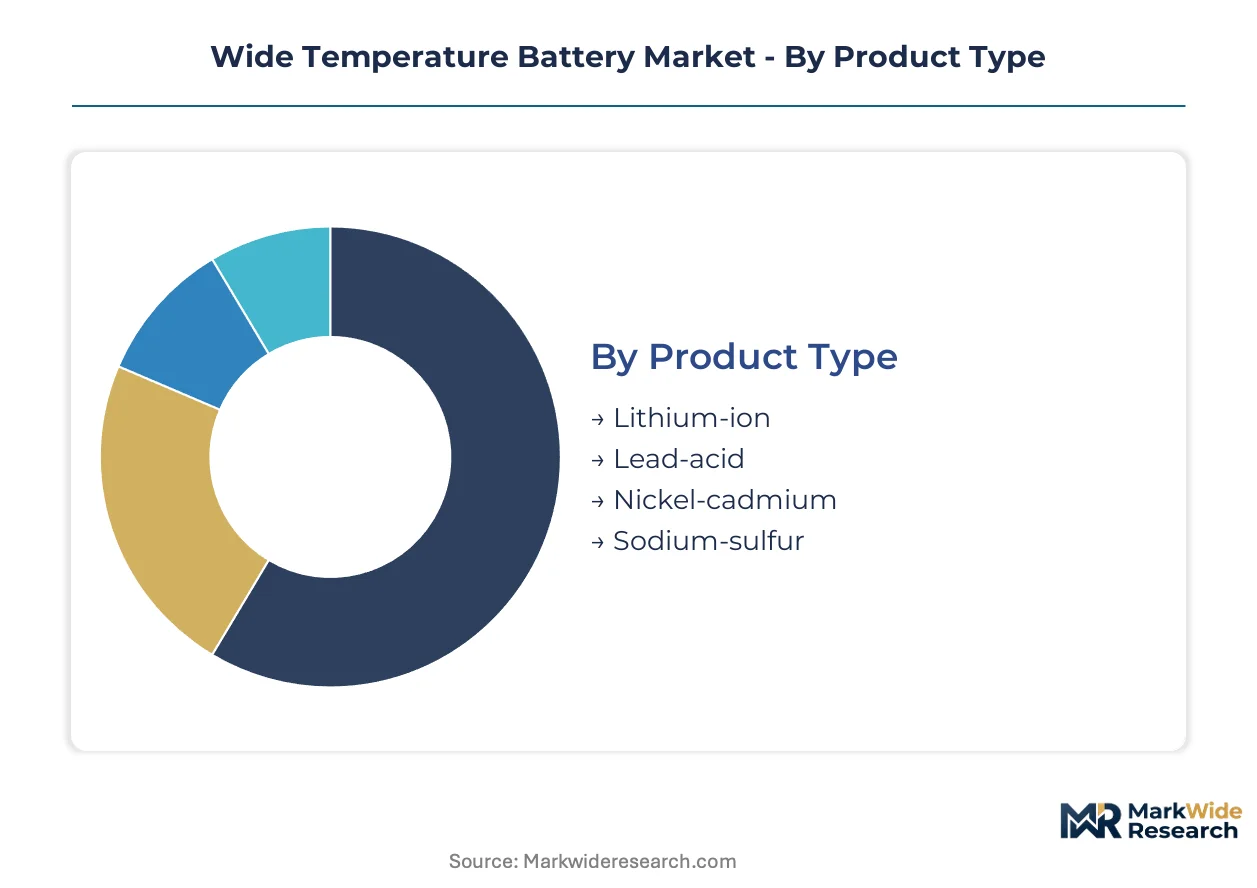
Wide temperature battery procurement splits sharply between high-volume automotive contracts and premium-margin aerospace certifications. Understanding where volume concentrates versus where margins accumulate determines supplier positioning across chemistry and form factor decisions.
Product Type:
Lithium-ion dominates absolute shipment volumes while sodium-sulfur captures expanding grid-scale interest for raw material security.
- Lithium-ion:Electrochemical systems employing lithium cobalt oxide or lithium iron phosphate cathodes with carbonate-based electrolytes modified for sub-zero ionic conductivity. Demand concentrates in Norwegian and Swedish electric vehicle fleets where OEMs mandate minus 40 degrees Celsius cold-cranking performance. Solid-state electrolyte research threatens incumbent liquid electrolyte suppliers with displacement risk.
- Sodium-sulfur:High-temperature molten salt configurations operating at 300 degrees Celsius with beta-alumina solid electrolyte barriers. Remote renewable microgrid developers in Arctic Canada and Alaska pilot these systems for multi-day storage duration, leveraging sodium abundance to hedge lithium supply concentration in Chile and Australia.
- Lead-acid:Mature flooded and valve-regulated designs with limited minus 20 degrees Celsius operational envelopes, serving backup power niches where capital cost sensitivity outweighs energy density requirements.
- Nickel-cadmium:Sintered plate constructions tolerating minus 50 degrees Celsius discharge, retaining position in Russian and Canadian rail signaling infrastructure where legacy certification paths resist chemistry substitution.
Today's leader: Lithium-ion. Tomorrow's challenger: Sodium-sulfur.
Application:
Automotive contracts drive cell volume while aerospace procurement sustains the highest qualification barriers and margin premiums.
- Automotive:Battery electric and hybrid electric vehicle traction packs with integrated thermal management for cold-climate range retention. Swedish mining truck electrification programs and Norwegian bus fleet conversions pull advanced pack designs into series production, compressing qualification timelines for solid-state candidates.
- Aerospace:Primary and secondary power systems for telemetry, actuation, and emergency power spanning minus 60 to plus 150 degrees Celsius operational envelopes. FAA thermal runaway propagation testing limits supplier base to established manufacturers with dedicated aviation qualification facilities.
- Industrial Equipment:Automated guided vehicles and robotic systems in sub-zero warehousing and Arctic construction, where standard lithium-ion capacity fade accelerates replacement cycles.
- Renewable Energy Storage:Grid-tied and off-grid battery installations pairing solar or wind generation with multi-day discharge requirements in Nordic and Alaskan remote communities.
Automotive commands volume scale. Aerospace defends margin premiums through certification moats.
End User:
OEMs specify cell chemistry directly while utilities and logistics operators increasingly procure complete energy storage subsystems.
- OEMs:Electric vehicle and industrial equipment manufacturers with in-house pack integration capabilities, driving lithium-ion qualification roadmaps and solid-state electrolyte partnership decisions.
- Utilities:Grid operators and rural electrification cooperatives in Alaska, Norway, and Sweden sourcing turnkey storage systems for renewable integration and peak shaving applications.
- Logistics:Cold-chain fleet operators and Arctic shipping companies contracting for warranty-backed performance across temperature extremes rather than specifying cell chemistry independently.
- Consumer Electronics:Niche outdoor equipment and satellite communication device manufacturers requiring minus 40 degrees Celsius operational reliability in portable form factors.
Direct cell procurement persists with OEMs. Integrated subsystem purchasing is accelerating among logistics and utility buyers.
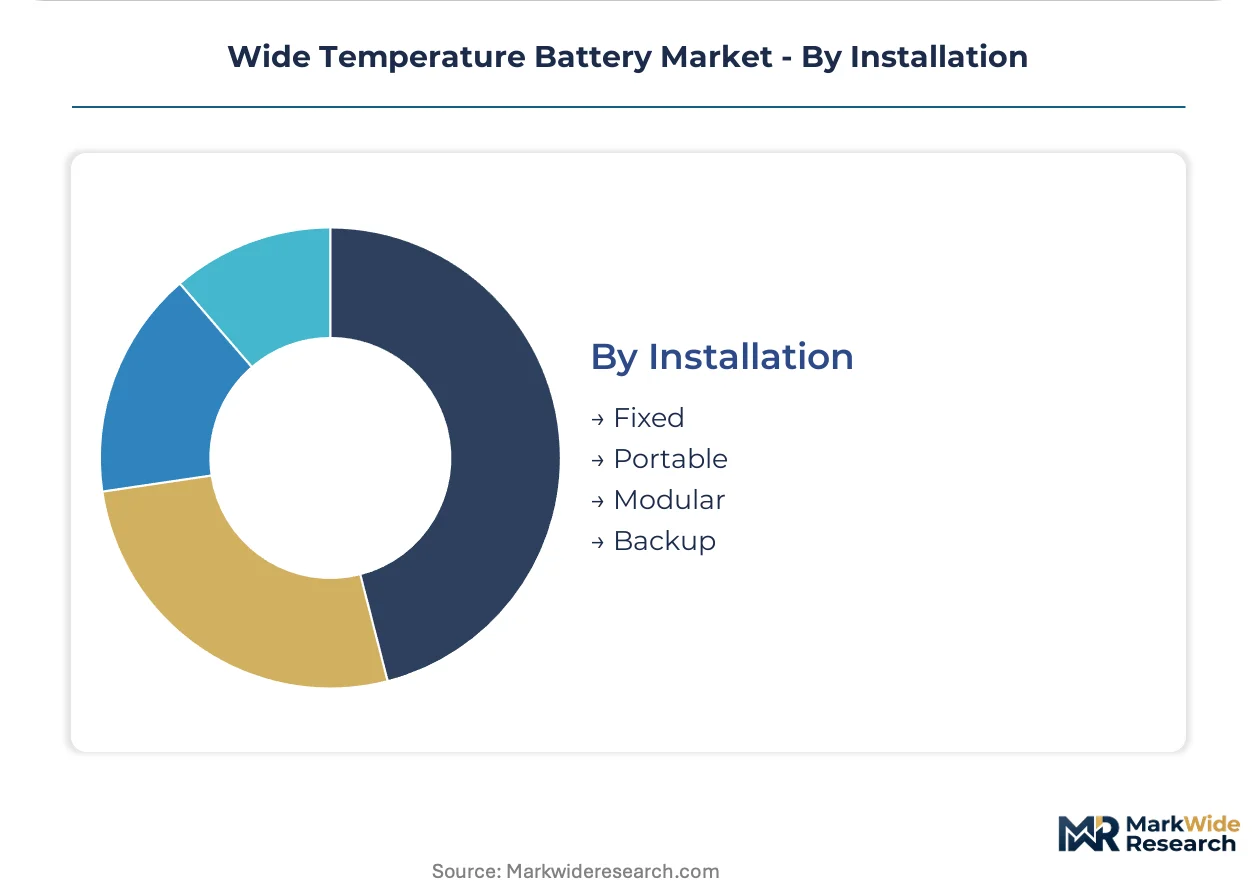
Installation:
Fixed installations anchor grid-scale revenue while modular architectures capture industrial and mobility growth.
- Fixed:Permanently sited battery banks in substations, renewable generation facilities, and remote microgrids, optimized for decades-long service life with minimal maintenance access.
- Portable:Man-transportable power systems for scientific field research, military forward operating bases, and emergency response in extreme temperature environments.
- Modular:Containerized or rack-mounted configurations enabling capacity scaling and hot-swappable maintenance, dominating Swedish mining equipment electrification and Norwegian marine hybrid retrofits.
- Backup:Uninterruptible power supply installations for critical infrastructure in Arctic telecommunications and healthcare facilities, where failure tolerance approaches zero.
Fixed installations retain revenue concentration. Modular configurations are climbing fastest as industrial buyers prioritize operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wide temperature battery development traces its industrial lineage to Nordic electrification programs and Arctic defense logistics, where sub-zero operational requirements first drove specialized electrolyte research and thermal management engineering.
Norway
Arctic bus fleet electrification and marine hybrid retrofits pull advanced pack designs into procurement contracts. The country's sovereign wealth fund channels capital toward domestic battery manufacturing capacity. Tromsø and Kirkenes anchor cold-climate testing infrastructure where OEMs validate minus 40 degrees Celsius performance specifications.
Sweden
Mining truck electrification programs and renewable microgrid installations concentrate demand for modular thermal-management systems. REACH compliance timelines compress qualification cycles for Asian suppliers lacking carbon footprint documentation. Skellefteå hosts Northvolt's gigafactory complex producing cells qualified for Arctic logistics applications.
United States
Alaskan remote community microgrids and cold-climate defense logistics drive procurement for primary and secondary battery systems. NHTSA safety standards and FAA certification requirements limit aviation battery qualification to established manufacturers with dedicated testing facilities. Michigan and California anchor automotive OEM solid-state electrolyte partnership programs.
Japan
Solid-state electrolyte patent holdings concentrate in national laboratory and corporate research clusters, complicating freedom-to-operate analysis for new market entrants. METI funding programs accelerate ceramic and polymer electrolyte commercialization timelines. Nagoya and Tsukuba host the primary academic-industry research partnerships shaping next-generation extreme-temperature chemistries.
Germany
Automotive supplier integration capabilities and industrial automation demand pull wide temperature cells into automated guided vehicle and robotic systems. KBA type-approval processes and EU Battery Regulation carbon disclosure mandates favor producers with verified supply chain transparency. Stuttgart and Munich anchor OEM pack integration engineering centers qualifying solid-state candidates for series production.
Wide Temperature Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification barriers and thermal envelope specifications, with aviation and aerospace procurement sustaining the highest qualification moats. The vendor base organizes into three tiers: established manufacturers with dedicated aviation qualification facilities, automotive-anchored cell producers with cylindrical expertise, and emerging solid-state specialists racing to compress commercialization timelines. Consolidation pressures intensify as REACH compliance costs and carbon footprint disclosure requirements extend qualification cycles for non-integrated suppliers. Dominant competitive moves include strategic partnerships for solid-state electrolyte access and geographic relocation to capture US IRA domestic manufacturing incentives.
Among Japanese and Korean industrial conglomerates, Panasonic Corporation and LG Energy Solution occupy positions spanning automotive and consumer electronics qualification paths. Saft Group represents the specialized primary cell archetype with established aerospace and defense procurement relationships. These three anchors exemplify how historical certification investments and captive raw material streams defend margin position against emerging solid-state challengers.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Tadiran Batteries |
| Saft Group |
| EVE Energy |
| EaglePicher Technologies |
| NGK Insulators |
| LG Energy Solution |
| Ultralife Corporation |
| XALT Energy |
| Others |
Pricing and Supply Chain Analysis
Captive electrolyte production in Japan and South Korea anchors both supply security and premium pricing power for established cell manufacturers, insulating them from lithium carbonate volatility that erodes margins for non-integrated competitors serving Nordic automotive contracts.
Pricing Analysis
Three-tier pricing structure across aviation-certified, automotive-qualified, and industrial-grade levels stratifies the vendor base. Price differentiation rests on FAA thermal runaway certification and REACH carbon disclosure verification. Cost compression in the industrial tier is intensifying because Asian suppliers lacking documentation systems face extended qualification cycles. Logistics operators and utility buyers exhibit the highest price sensitivity, while aerospace procurement sustains inelastic demand.
Supply Chain Analysis
Single-source vulnerability sits with Australian spodumene and Chilean brine operations that feed cathode precursor production. Cell manufacturing draws from China, South Korea, and Japan for electrode coating and formation. Tariff exposure on processed lithium materials threatens margin stability for European pack integrators. Distribution runs through Tier 1 automotive suppliers and specialized aerospace qualification facilities rather than open commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's carbon footprint disclosure mandates compound procurement complexity, transforming compliance infrastructure into a demand driver that rewards producers with verified supply chain transparency.
For Market Incumbents: Hedge lithium feedstock exposure through offtake agreements with Australian and Chilean mining operations. Accelerate solid-state electrolyte partnership timelines to defend against ceramic and polymer chemistry displacement in aerospace procurement cycles.
For New Entrants and Emerging Players: Solid-state electrolyte pilot production offers a technology-first wedge into Nordic microgrid installations requiring minus 40 degrees Celsius performance. Target Alaskan and Canadian remote community utilities with modular thermal-management systems rather than standalone cells. Pursue design partnerships with Swedish mining equipment OEMs seeking warranty-backed subsystem procurement.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and carbon footprint verification requirements extend qualification cycles for non-integrated Asian suppliers. Long-term viability favors vertically integrated producers with captive raw material streams and established aviation qualification facilities. Watch solid-state electrolyte patent licensing negotiations as an inflection indicator for chemistry transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Partnership | Panasonic and Saft Group anchor premium contracts through ceramic and polymer chemistry access. |
| Backward Integration into Lithium Feedstock | Northvolt's Skellefteå complex secures spodumene supply for Arctic-qualified cell production. |
| Aviation Qualification Facility Investment | FAA thermal runaway testing capability limits supplier base to established manufacturers with dedicated infrastructure. |
| Modular Pack Architecture Development | Swedish mining truck electrification programs pull integrated thermal-management designs into series production. |
| REACH Compliance Infrastructure Buildout | Carbon disclosure documentation systems redirect volume toward producers with verified supply chain transparency. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell engineering directors, automotive OEM procurement leads, aerospace qualification specialists, and Arctic logistics fleet operators with secondary validation against customs filings, ECHA registration databases, FAA certification records, and vehicle production data. Bottom-up cell shipment modeling and top-down energy storage system revenue estimates were cross-referenced for triangulation.
Segment-weighting approaches applied product type, application, end user, and installation configuration dimensions across the projection horizon. CAGRs were derived from fitted growth curves incorporating electrolyte chemistry transition probabilities, regulatory compliance timeline compression, and Nordic fleet electrification program commitments. Solid-state commercialization timelines and lithium carbonate price scenarios served as sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state electrolyte scale-up velocity, lithium feedstock supply disruptions, and EU Battery Regulation enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
India Lead-Acid Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Denmark Rechargeable Battery Market
Batteries
Breathing Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Micro Mobility Battery PACK Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
America SLI Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
North Africa Battery Market
Batteries
Vanadium Redox Batteries Market