
 Lithium-Ion Polymer Batteries Market | 2026-2036
Lithium-Ion Polymer Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Polymer Batteries Market Insights
Software-defined battery management is restructuring how value gets captured in lithium-ion polymer sales. CATL leverages its integrated BMS platform to lock in automotive OEM contracts across multiple continents. Samsung SDI Co., Ltd. differentiates through high-nickel cathode chemistry leadership in premium consumer electronics cells. BYD Company Ltd anchors its position through backward integration into lithium iron phosphate materials and captive electric vehicle demand.
Lithium-ion polymer batteries use a gel electrolyte and laminated aluminum-polymer pouch construction, enabling form factors from sub-millimeter wearable cells to kilowatt-hour automotive modules with gravimetric energy densities exceeding 250 Wh/kg. Their primary purpose centers on applications demanding weight reduction and design flexibility absent in cylindrical or prismatic alternatives. Consumer electronics remains the largest product type segment by installed capacity, though electric vehicles generates the fastest capacity expansion as pouch formats penetrate premium EV architectures. Energy storage systems application demand concentrates in utility-scale deployments where large format cells reduce pack-level connection complexity. Thin film technology occupies the highest margin tier, serving medical devices and specialized wearable devices with strict thickness constraints.
FCC certification governs RF-integrated smart battery packs in US consumer electronics, while the EU Battery Regulation mandates recycled content disclosure and carbon footprint declarations for cells placed on the European market. China's GB standards enforce nail penetration and thermal runaway propagation tests that determine market access for domestic and imported cells alike. Japan's METI circular economy directives shape end-of-life collection obligations for industrial equipment applications. Stakeholders must monitor how divergent national testing protocols affect cross-border pack certification costs and supplier qualification timelines.
Market Dynamics
Automotive OEMs are consolidating procurement around software-defined battery management platforms, compressing supplier margins while elevating systems integrators who control firmware and thermal algorithms. This platform consolidation is redistributing value capture away from pure cell manufacturers toward vertically integrated subsystem providers.
Growth Catalysts
- EU Battery Regulation:Mandated recycled content thresholds and carbon footprint declarations are accelerating closed-loop material recovery investments across European cell assembly facilities.
- High-nickel cathode chemistry:NCM 811 and beyond formulations are extending gravimetric energy density ceilings for premium electric vehicle architectures demanding maximum range per kilogram.
- South Korea's cathode material cluster:Concentrated precursor refining and active material production around Gwangyang and Onsan is shortening supply lead times for pouch cell manufacturers.
Market Restraints
- Lithium carbonate price volatility:Spodumene concentrate contract pricing swings are transmitting directly into cell cost structures, destabilizing long-term automotive supply agreements.
- Single-source separator supply:Wet-process ceramic-coated polyethylene membrane production concentrates among Japanese and South Korean specialty film manufacturers, creating chokepoint vulnerability.
- Solid-state substitution timeline:Oxide and sulfide electrolyte cell architectures are threatening pouch format dominance in premium applications beyond 2030.
Strategic Opportunities
- India's PLI scheme for ACC:Production-linked incentives for advanced chemistry cell manufacturing are attracting greenfield assembly investments targeting domestic electric two-wheeler and three-wheeler demand.
- Medical device wearables:Sub-millimeter thin film cells for continuous glucose monitors and cardiac patches represent margin premiums unavailable in commoditized consumer electronics.
- Grid-scale energy storage:Large format pouch modules are displacing cylindrical alternatives in utility battery installations where pack-level connection simplification reduces installation labor.
Industry Challenges
- Electrolyte formulation chemist scarcity:Gel polymer electrolyte R&D expertise concentrates among a narrow cohort of specialists with experience in fluorinated solvent systems and ceramic filler dispersion.
- UN 38.3 certification backlog:Lithium cell transport testing queue delays at certified laboratories are extending product launch timelines for consumer electronics brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Polymer Batteries Market |
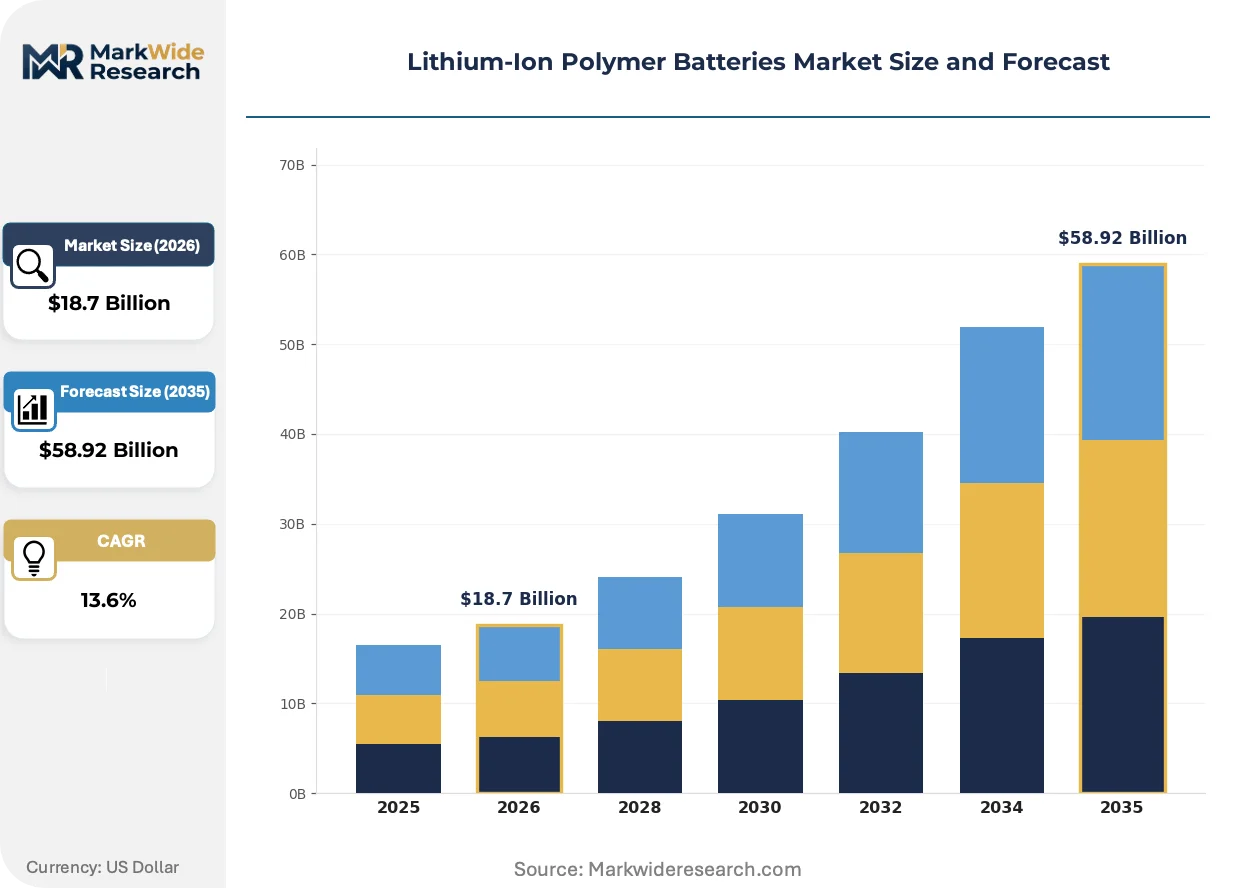
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Industrial Equipment, Medical Devices Application: Energy Storage Systems, Power Tools, Electric Bikes, Wearable Devices End User: Retail Consumers, Manufacturers, Healthcare Providers, Automotive OEMs Technology: Thin Film, Large Format, Custom Cells, High Energy Density |
| Companies Covered | CATL, LG Chem Ltd, Panasonic Corporation, Samsung SDI Co., Ltd., BYD Company Ltd, Mitsubishi Electric Corporation, Beijing Pride Power Battery Technology Co Ltd, Tianneng Power International Limited, Wanxiang Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Polymer Batteries Market Trends and Innovations
Cell architecture standardization is colliding with application-specific customization demands, forcing manufacturers to develop platformized module designs that accommodate voltage and thermal requirements across divergent end-use verticals without full redesign.
Large-format pouch cell designs are modularizing around standardized module footprints that accommodate multiple series-parallel configurations. Automotive OEMs are adopting these flexible building blocks for platform-spanning battery packs. This architecture is modularizing pack assembly lines, enabling single facilities to serve sedan, SUV, and commercial vehicle programs without retooling.
China's GB 38031-2020 electric vehicle battery safety standard is mandating nail penetration and thermal runaway propagation tests that exceed UN ECE R100 requirements. Cell manufacturers are redesigning separator materials and electrode stacking geometries to satisfy these protocols. Premium passenger vehicle programs targeting the Chinese market are absorbing the compliance cost premium.
Direct OEM engagement is displacing tiered distributor networks for automotive and energy storage procurement. Cell manufacturers are establishing dedicated account engineering teams for Volkswagen, Tesla, and CATL partnerships. This channel compression is most visible in Germany's automotive corridor and China's Guangdong manufacturing belt.
Lithium-Ion Polymer Batteries Market Segmentation
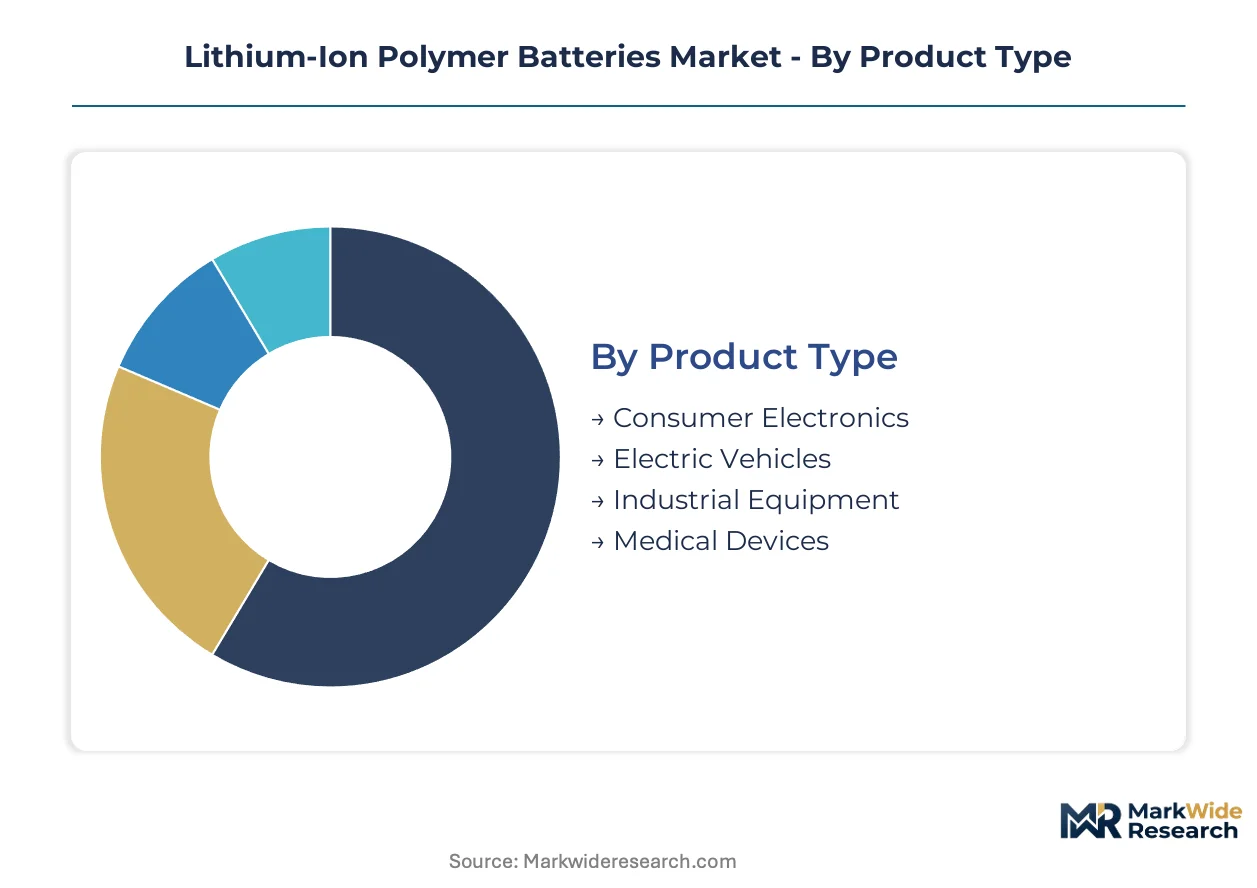
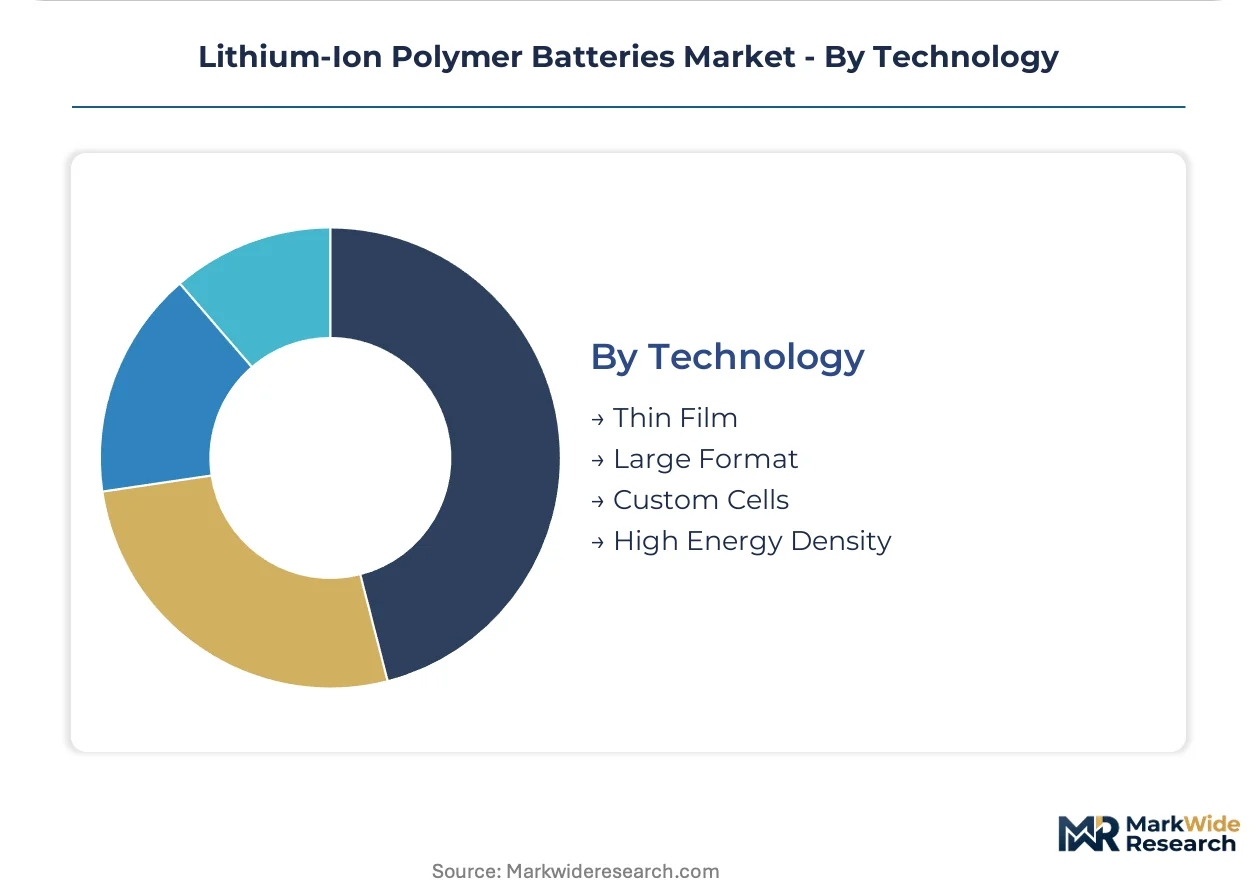
Lithium-ion polymer battery segmentation reveals how form factor flexibility and energy density requirements fragment procurement patterns across end-use verticals. Cell manufacturers must balance platform standardization against application-specific thermal and voltage demands.
Product Type:
The customization-vs-standardization spectrum stretches from mass-produced cylindrical alternatives to pouch formats engineered for specific weight and dimensional constraints.
- Consumer Electronics:High-volume production of sub-5mm cells for smartphones and tablets dominates procurement tonnage. Demand concentrates in China's Guangdong manufacturing corridor where pouch cell assembly lines feed integrated device factories.
- Electric Vehicles:Kilowatt-hour scale modules with gravimetric densities exceeding 250 Wh/kg serve premium automotive architectures. South Korean cathode material clusters supply NCM 811 formulations to pouch cell manufacturers targeting European OEM qualification programs.
- Industrial Equipment:Ruggedized cells with extended cycle life serve automated guided vehicles and warehouse robotics. UN 38.3 transport certification requirements extend supplier qualification timelines.
- Medical Devices:Sterilization-compatible pouch formats with traceable manufacturing records serve implantable and portable diagnostic equipment. FDA 21 CFR Part 820 quality system compliance elevates vendor selection criteria.
Most installed capacity flows through Consumer Electronics. Expansion is steepest in Electric Vehicles.
Application:
Cost tier differentiation separates utility-scale deployments from consumer-facing products where unit economics tolerate premium cell pricing.
- Energy Storage Systems:Large format pouch modules reduce pack-level connection complexity in grid-scale battery installations. Utility procurement favors cells with 6000+ cycle life warranties.
- Power Tools:High discharge rate cells with reinforced tab welding serve cordless construction equipment. Milwaukee and DeWalt branded battery platforms drive form factor standardization.
- Electric Bikes:Mid-format pouch packs balance energy density against theft-resistant mounting constraints. European pedelec regulations mandate specific safety certifications.
- Wearable Devices:Sub-millimeter thin film technology occupies the highest margin tier in continuous glucose monitors and cardiac patches. Medical device OEMs absorb 40-60% cell cost premiums for thickness below 0.5mm.
Revenue concentrates in Energy Storage Systems. Margin expansion is most pronounced in Wearable Devices.
End User:
Customer type determines contract structure, with automotive OEMs demanding multi-year supply agreements and healthcare providers requiring lot-level traceability.
- Retail Consumers:Replacement battery purchases for personal electronics and e-mobility products flow through e-commerce channels and aftermarket retailers. Price sensitivity limits brand loyalty.
- Manufacturers:Original equipment manufacturers in consumer electronics and power tools specify cell dimensions and performance curves during product development phases. Early supplier involvement locks in multi-year procurement commitments.
- Healthcare Providers:Hospital systems and diagnostic device manufacturers enforce ISO 13485 quality management requirements on cell suppliers. Sterilization validation protocols extend qualification cycles.
- Automotive OEMs:Volkswagen, Tesla, and CATL partnerships demonstrate direct OEM engagement displacing tiered distributor networks. Dedicated account engineering teams manage platform-spanning battery pack programs.
Procurement volume aggregates with Automotive OEMs. Contract value growth is fastest among Healthcare Providers.
Technology:
Volume and margin diverge across technology tiers, with commodity large-format cells competing on scale and thin film formats capturing design-constrained premiums.
- Thin Film:Solid-state electrolyte deposition and vacuum-sealed polymer substrates enable sub-millimeter constructions. Medical device and specialized wearable applications absorb manufacturing cost premiums unavailable in commoditized segments.
- Large Format:Laminated aluminum-polymer pouch constructions exceeding 50Ah capacity serve electric vehicle and grid storage modules. China's GB 38031-2020 safety standard mandates nail penetration and thermal runaway propagation testing.
- Custom Cells:Bespoke dimensions and terminal configurations serve industrial equipment with non-standard battery compartment geometries. Low volume production elevates per-unit pricing.
- High Energy Density:NCM 811 and silicon-anode formulations push gravimetric performance boundaries. South Korean precursor refining clusters supply cathode active materials.
Production volume concentrates in Large Format. Value capture is highest in Thin Film.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate assembly capacity to jurisdictions with lower compliance burdens while maintaining cell qualification for premium markets. Cost-of-compliance gaps between certification regimes drive greenfield investment decisions across three continents.
China
Guangdong Province hosts the densest concentration of pouch cell assembly lines feeding integrated consumer electronics factories. NMPA battery safety certification and GB 38031-2020 nail penetration mandates exceed UN ECE R100 requirements, forcing separator material redesigns for market access. Shenzhen and Dongguan manufacturing corridors absorb these compliance premiums to maintain automotive OEM qualification pipelines.
South Korea
Gwangyang and Onsan cathode precursor clusters shorten supply lead times for high-nickel NCM 811 formulations targeting European electric vehicle programs. MFDS pharmaceutical-grade cell regulations and METI circular economy alignment shape export documentation burdens. Busan-Ulsan industrial complexes concentrate wet-process separator finishing capacity vulnerable to single-source chokepoints.
Germany
Automotive OEM direct engagement compresses traditional distributor networks across Baden-Württemberg and Bavaria manufacturing corridors. EU Battery Regulation recycled content thresholds and carbon footprint declarations accelerate closed-loop material recovery investments. KBA vehicle type approval integration with cell-level UN 38.3 transport certification extends supplier qualification timelines.
United States
FCC RF-integrated smart battery pack certification governs consumer electronics procurement specifications for California and Texas device assembly hubs. IRA production tax credits attract cathode active material refining investments to offset spodumene concentrate price volatility transmission. NHTSA battery safety investigation precedents shape automotive OEM liability frameworks.
India
Gujarat and Tamil Nadu production-linked incentive zones for advanced chemistry cell manufacturing target domestic electric two-wheeler and three-wheeler demand absorption. BIS adoption of GB standard thermal runaway test protocols creates harmonized qualification pathways for Chinese equipment imports. DGFT lithium carbonate import tariff structures influence cell cost competitiveness against ASEAN assembly alternatives.
Lithium-Ion Polymer Batteries Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive procurement consolidating around direct OEM relationships while consumer electronics tolerates tiered supplier networks. Three to five integrated cell-BMS platforms capture disproportionate automotive contract value. Strategic archetypes separate chemistry-focused material innovators, scale-driven assembly operators, and captive-demand verticals. Competitive moves concentrate on cathode precursor backward integration and solid-state electrolyte patent positioning.
Among China-based fabricators, CATL and BYD Company Ltd occupy positions reflecting integrated platform strategies, while South Korean specialists Samsung SDI Co., Ltd. and LG Chem Ltd exemplify high-nickel cathode chemistry leadership. Panasonic Corporation anchors Japanese-origin premium cell supply for consumer electronics and automotive qualification programs. These named entities represent geographic clustering patterns visible across regulatory filing concentrations rather than definitive market share claims.
| Leading Market Players |
|---|
| CATL |
| LG Chem Ltd |
| Panasonic Corporation |
| Samsung SDI Co., Ltd. |
| BYD Company Ltd |
| Mitsubishi Electric Corporation |
| Beijing Pride Power Battery Technology Co Ltd |
| Tianneng Power International Limited |
| Wanxiang Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Spodumene concentrate contract pricing cascades through cathode precursor refining costs into three distinct procurement tiers: automotive OEM long-term offtakes absorbing volatility premiums, consumer electronics spot purchases facing quarterly repricing, and medical device contracts with fixed-price sterilization-grade specifications.
Pricing Analysis
Distributor margin compression is accelerating direct-to-OEM channel migration, with Volkswagen and Tesla procurement teams extracting volume discounts that eliminate tiered intermediaries. Price differentiation hinges on GB 38031-2020 certification tier and automotive qualification status, with nail-penetration-tested cells commanding substantial premiums over consumer-grade alternatives. Cost compression in standard-format cells is intensifying because Chinese assembly capacity expansion outpaces cathode material supply growth. Retail consumers exhibit highest price sensitivity, while healthcare providers absorb premiums for FDA 21 CFR Part 820 traceability.
Supply Chain Analysis
Dual-sourcing mandates from European automotive OEMs are forcing qualification of secondary separator suppliers beyond Japanese and South Korean ceramic-coated polyethylene specialists. Geographic supply concentration centers on China's Guangdong cell assembly corridor, South Korea's Gwangyang cathode cluster, and Japan's wet-process membrane finishing facilities. Raw material dependencies draw from Australian spodumene concentrate, Chilean lithium carbonate, and Indonesian nickel laterite. Single-source vulnerability in ceramic-coated separator supply creates structural risk. Distribution runs through direct OEM account engineering teams for automotive and energy storage verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI scheme for advanced chemistry cells offers cost advantages against EU Battery Regulation compliance burdens, enabling margin capture for manufacturers relocating assembly capacity while maintaining premium-market qualification.
For Market Incumbents: Lock in cathode precursor backward integration through offtake agreements with Gwangyang refining clusters, insulating margin structures against spodumene volatility. Secure solid-state electrolyte patent positioning to defend against oxide and sulfide substitution threats beyond 2030. Expand dedicated account engineering teams for direct OEM engagement, compressing distributor networks that erode pricing power.
For New Entrants and Emerging Players: E-commerce aftermarket channels for replacement consumer electronics batteries offer lowest qualification barriers and fastest revenue ramp. Target India's electric two-wheeler and three-wheeler segments, where PLI incentives and domestic demand absorption create white-space opportunity. Pursue medical device wearable specialization, where sub-millimeter thin film margins exceed commoditized segments by substantial premiums.
For Investors and Strategic Acquirers: Asymmetric upside sits with gel polymer electrolyte R&D specialists possessing fluorinated solvent system expertise, a capability cohort concentrated among narrow technical talent pools. Long-term viability hinges on qualification timelines for automotive OEM direct contracts rather than distributor-dependent revenue. Watch solid-state cell pilot production announcements as inflection indicator for pouch format substitution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Secures NCM 811 supply from South Korean refining clusters against lithium carbonate volatility. |
| GB 38031-2020 Certification Investment | Unlocks premium automotive OEM qualification pipelines targeting Chinese passenger vehicle programs. |
| Direct OEM Account Engineering Deployment | Compresses tiered distributor networks across Germany's automotive corridor and Guangdong manufacturing belt. |
| Solid-State Electrolyte Patent Positioning | Defends against oxide and sulfide cell architecture substitution threatening pouch format dominance. |
| Medical Device Wearable Specialization | Captures 40-60% cell cost premiums for sub-0.5mm thin film continuous glucose monitor applications. |
Research Methodology
Bottom-up electric vehicle and consumer electronics modeling reconciled against top-down cathode material and cell assembly capacity tracking forms the analytical core. Primary interviews with automotive OEM platform engineers, Tier 1 battery pack procurement leads, cathode active material plant managers, and medical device OEM supply chain directors combined with secondary validation from SEC 10-K filings, customs trade databases, NMPA certification registries, and EU Battery Regulation implementation guidance. Top-down and bottom-up estimates triangulate through cross-referencing production capacity announcements against end-use demand absorption.
Historical trendline analysis of installed capacity expansion, chemistry migration patterns, and procurement contract structures informed projection modeling across the analysis window. Segmentation dimensions include product type, application vertical, end-user contract structure, and technology tier. CAGRs derive from curve-fitting capacity deployment trajectories against automotive OEM platform launch schedules and energy storage utility procurement pipelines. Forecast inputs incorporate spodumene concentrate contract pricing volatility and separator supply concentration risk.
The model assumes a particular technology adoption path; alternative pathways for solid-state oxide and sulfide electrolyte cells would alter the outlook substantially. Forecasts reflect assumptions regarding NCM 811 chemistry penetration rates, GB standard harmonization timelines, and automotive OEM direct procurement consolidation. Deviation in solid-state cell pilot production scale-up or EU Battery Regulation recycled content threshold enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market