
 Custom Battery Pack Market | 2026-2036
Custom Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Battery Pack Market Intelligence
Demand from specialized OEM clients in electric mobility and grid storage is bifurcating the market away from traditional industrial equipment manufacturers. This shift favors suppliers with deep application-specific engineering capabilities. LG Energy Solution leverages its massive scale in cell production to offer customized solutions for automotive partners. Microvast Holdings specializes in fast-charging battery systems for commercial vehicles, while EnerSys sustains its position in industrial motive power applications.
A custom battery pack is an engineered assembly of cells, a battery management system (BMS), and housing, designed for a specific device's voltage, capacity, and form factor requirements. Its primary purpose is to provide an optimized, integrated power source for applications where off-the-shelf batteries are unsuitable. Lithium-ion chemistries dominate new designs, particularly for high-energy-density needs in electric vehicles and consumer electronics. While cylindrical and prismatic form factors are common, pouch cells offer greater design flexibility for space-constrained devices.
Safety and transport regulations, such as the UN 38.3 testing standards, are critical for market access. The EU's Battery Passport and the US EPA's rules on battery recycling and disposal influence material selection and end-of-life management. These compliance frameworks create significant design and documentation overhead for manufacturers. Stakeholders must now decide whether to build in-house compliance expertise or rely on specialized third-party partners to navigate the complex regulatory environment.
Market Dynamics
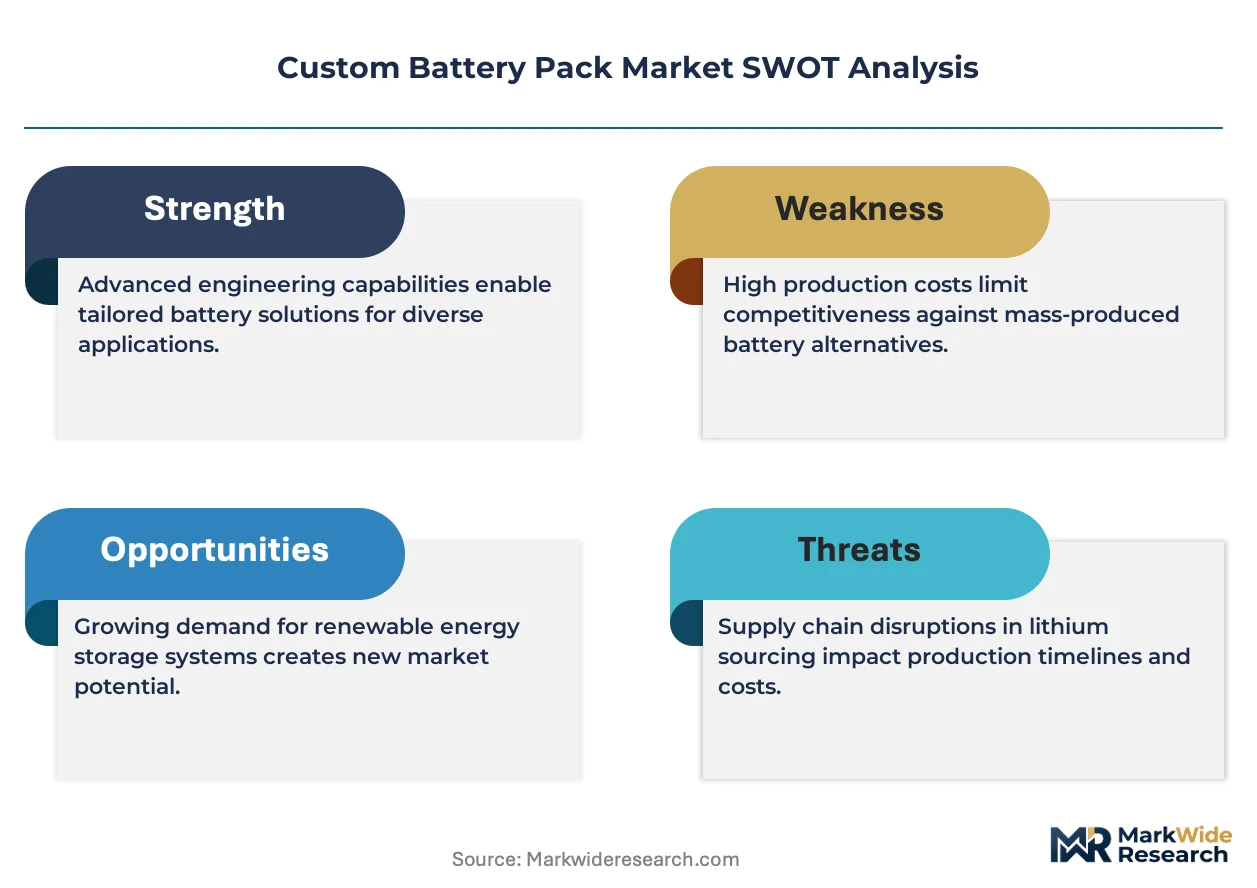
The central dynamic shaping the custom battery pack market is the tension between the need for application-specific engineering for niche devices and the drive for modular, scalable platforms to serve high-volume sectors like electric mobility. This bifurcation forces manufacturers to choose between focusing on deep, low-volume specialization or developing configurable architectures that balance customization with production efficiency.
Growth Catalysts
- EU Battery Passport:This regulation mandates digital records for battery composition, origin, and carbon footprint, creating demand for sophisticated pack designers who can manage complex data and traceability requirements.
- Micromobility Expansion:The proliferation of electric scooters, e-bikes, and delivery drones requires novel, lightweight, and durable battery packs with unique form factors, moving beyond standard cylindrical cell configurations.
- Pouch Cell Adoption:The increasing use of flexible pouch cells allows for greater design freedom in space-constrained applications like wearable medical devices and consumer electronics, enabling thinner and more ergonomic product designs.
Market Restraints
- Raw Material Volatility:Unpredictable pricing and supply chain disruptions for critical materials like lithium, cobalt, and nickel create significant costing challenges for pack manufacturers, complicating long-term contracts.
- Transportation Regulations:The stringent testing and documentation required by UN 38.3 standards for shipping lithium-ion batteries add significant cost, complexity, and lead time, acting as a barrier for new entrants.
- Cell Supply Concentration:The geographic concentration of high-performance battery cell production in China creates geopolitical risks and logistical challenges for pack assemblers in North America and Europe.
Strategic Opportunities
- Grid Energy Storage:The expansion of renewable energy sources creates a massive opportunity for large-scale, modular battery energy storage systems (BESS) that require custom integration, thermal management, and BMS solutions.
- Domestic Production Incentives:Policies like the US Inflation Reduction Act (IRA) provide tax credits and grants for onshore battery manufacturing, creating a compelling business case for localizing pack assembly and sourcing.
- Second-Life Applications:Developing certified processes to repurpose used electric vehicle battery packs for less demanding stationary storage applications opens a new revenue stream and addresses end-of-life challenges.
Industry Challenges
- Engineering Talent Scarcity:A persistent shortage of engineers with multidisciplinary skills in electrochemistry, thermal management, and embedded software for battery management systems hampers product development.
- Compliance Overhead:Navigating a fragmented global landscape of safety and environmental standards, including CE, UL, and RoHS, requires significant investment in testing and documentation for each target market.
- Interoperability Issues:The lack of standardization in communication protocols between battery management systems and host devices complicates system integration and limits plug-and-play compatibility for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Battery Pack Market |
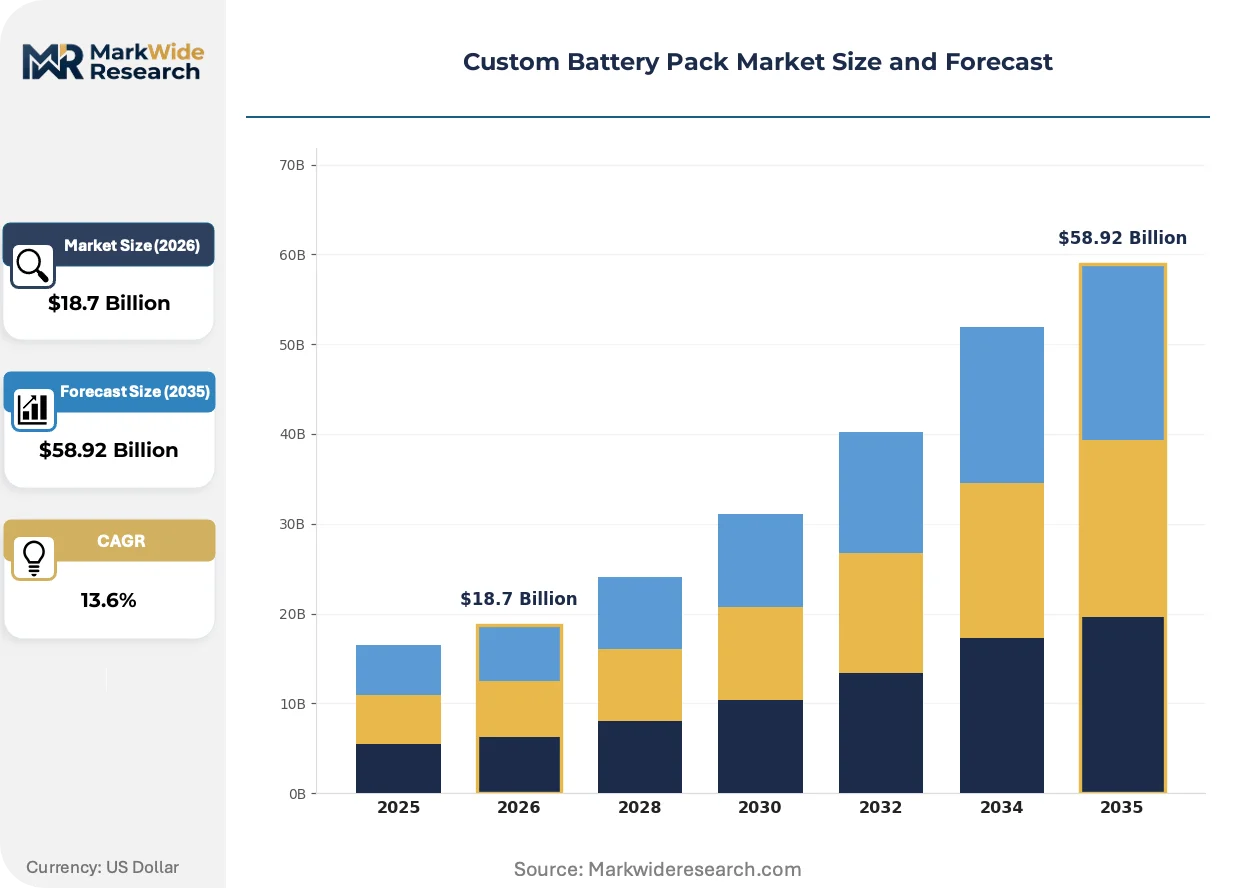
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer, Zinc-Air Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Aerospace, Marine End User: OEMs, Aftermarket Suppliers, Industrial Equipment Manufacturers, Telecom Providers, Defense Contractors Form Factor: Prismatic, Cylindrical, Pouch, Button, Rectangular |
| Companies Covered | EnerSys, Tesla Energy, Copow, Sunwoda, LG Energy Solution, Emerging Power, Microvast Holdings, Delongtop, A123 Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Battery Pack Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of digital technologies, turning battery packs from passive power sources into intelligent, data-generating assets. This shift enables predictive maintenance, performance optimization, and new service models. The focus is now on the pack's entire lifecycle, from sustainable design to end-of-life management.
Solid-state battery technology introduces a non-flammable, solid electrolyte, promising significant improvements in energy density and safety over conventional lithium-ion cells. Aerospace, defense, and premium automotive clients are the primary adopters, driving initial development for applications where failure is not an option. This next-generation chemistry is supplanting traditional liquid-electrolyte designs in high-value, performance-critical systems where its benefits justify the higher initial cost.
Europe's updated Battery Regulation is a significant driver of design innovation, establishing mandatory minimums for recycled content and strict collection targets. This forces manufacturers to embed circular economy principles into the product development process, emphasizing design-for-disassembly and material traceability. The consumer electronics and power tool segments are most directly impacted, spurring innovation in modular pack construction and non-destructive serviceability.
A transition toward Battery-as-a-Service (BaaS) models is reconfiguring how industrial equipment is powered and sold. This model separates the battery ownership cost from the vehicle or device, lowering the initial purchase barrier for customers in logistics and material handling. The disruption is most acute in the commercial electric vehicle sector, particularly in China, where standardized swappable battery packs facilitate this usage-based subscription service.
Custom Battery Pack Market Segmentation
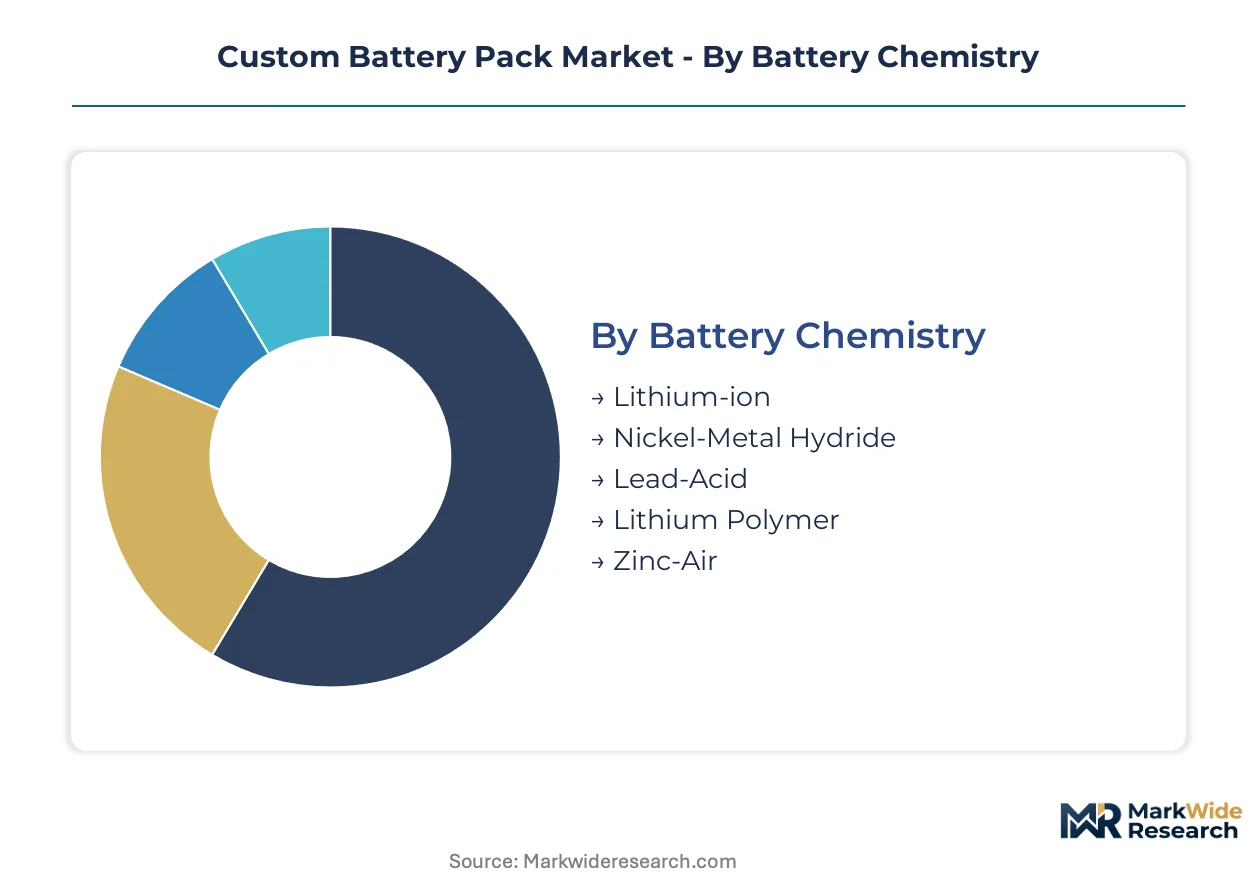
Market segmentation for custom battery packs reveals distinct demand patterns driven by specific technical requirements and end-use applications. Understanding these segments allows manufacturers to tailor their product development, sales strategies, and supply chain management to effectively serve specialized client needs.
Battery Chemistry:
Custom battery pack chemistries exhibit varied adoption rates across different global regions, reflecting local manufacturing capabilities and regulatory incentives for specific material sourcing.
- Lithium-ion:Lithium-ion cells feature high energy density and a long cycle life, making them ideal for demanding applications. Demand concentrates in China and Germany, driven by the extensive electric vehicle manufacturing base and grid storage projects requiring powerful, reliable solutions.
- Lithium Polymer:Lithium Polymer cells offer flexible form factors and high power density due to their gel-like electrolyte, enabling thin and light designs. Adoption is strong in Japan and South Korea for advanced consumer electronics and wearable medical devices, where space constraints are paramount.
- Nickel-Metal Hydride:Nickel-Metal Hydride batteries serve niche applications requiring robust performance in extreme temperatures, primarily in industrial and medical devices.
- Lead-Acid:Lead-Acid batteries remain cost-effective for stationary backup power and certain motive applications, particularly in developing economies.
- Zinc-Air:Zinc-Air batteries provide very high energy density for single-use, long-duration applications like hearing aids and remote sensors.
Lead-Acid commands the established base. The steepest expansion runs through Lithium-ion.
Application:
Volume of specific applications drives tailored pack development, differentiating between mass-market needs and specialized, low-volume requirements across various industrial sectors.
- Electric Vehicles:Custom packs for electric vehicles optimize power delivery, thermal management, and energy density for propulsion systems. Global demand for these solutions is concentrated in China and Germany, reflecting the rapid growth of EV manufacturing and adoption.
- Renewable Energy Storage:Battery packs for renewable energy storage systems require high cycle life, robust thermal stability, and modular designs for grid-scale integration. These systems see significant deployment in the United States and Australia, supporting large-scale solar and wind projects.
- Consumer Electronics:Custom battery packs for consumer electronics prioritize miniaturization and specific form factors for devices like smartphones and laptops.
- Aerospace:Aerospace applications demand ultra-reliable, lightweight battery packs with stringent safety certifications for critical flight systems.
- Marine:Marine battery solutions withstand harsh environments and provide sustained power for electric propulsion and onboard systems.
Electric Vehicles represent the fastest-growing segment, while Consumer Electronics provide consistent volume.
End User:
The specific needs of distinct customer types influence design complexity and procurement strategies for custom battery packs, ranging from high-volume production to specialized, low-quantity orders.
- OEMs:Original Equipment Manufacturers require highly integrated, application-specific battery packs that align with their product development cycles and performance benchmarks. Major automotive and electronics OEMs in Germany and Japan drive significant volume, seeking tailored solutions for new product launches.
- Industrial Equipment Manufacturers:These manufacturers demand rugged, long-lasting battery packs optimized for harsh operating conditions and continuous duty cycles in machinery. Growth is pronounced in the United States and China, supporting sectors like material handling and construction equipment.
- Aftermarket Suppliers:Aftermarket suppliers focus on replacement battery packs that meet or exceed original specifications for existing devices and vehicles.
- Telecom Providers:Telecom providers utilize custom battery solutions for reliable backup power in critical infrastructure, ensuring network uptime.
- Defense Contractors:Defense contractors require highly specialized, secure battery packs meeting military specifications for power and reliability in extreme environments.
OEMs drive innovation and large-scale orders. Aftermarket Suppliers cater to replacement cycles.
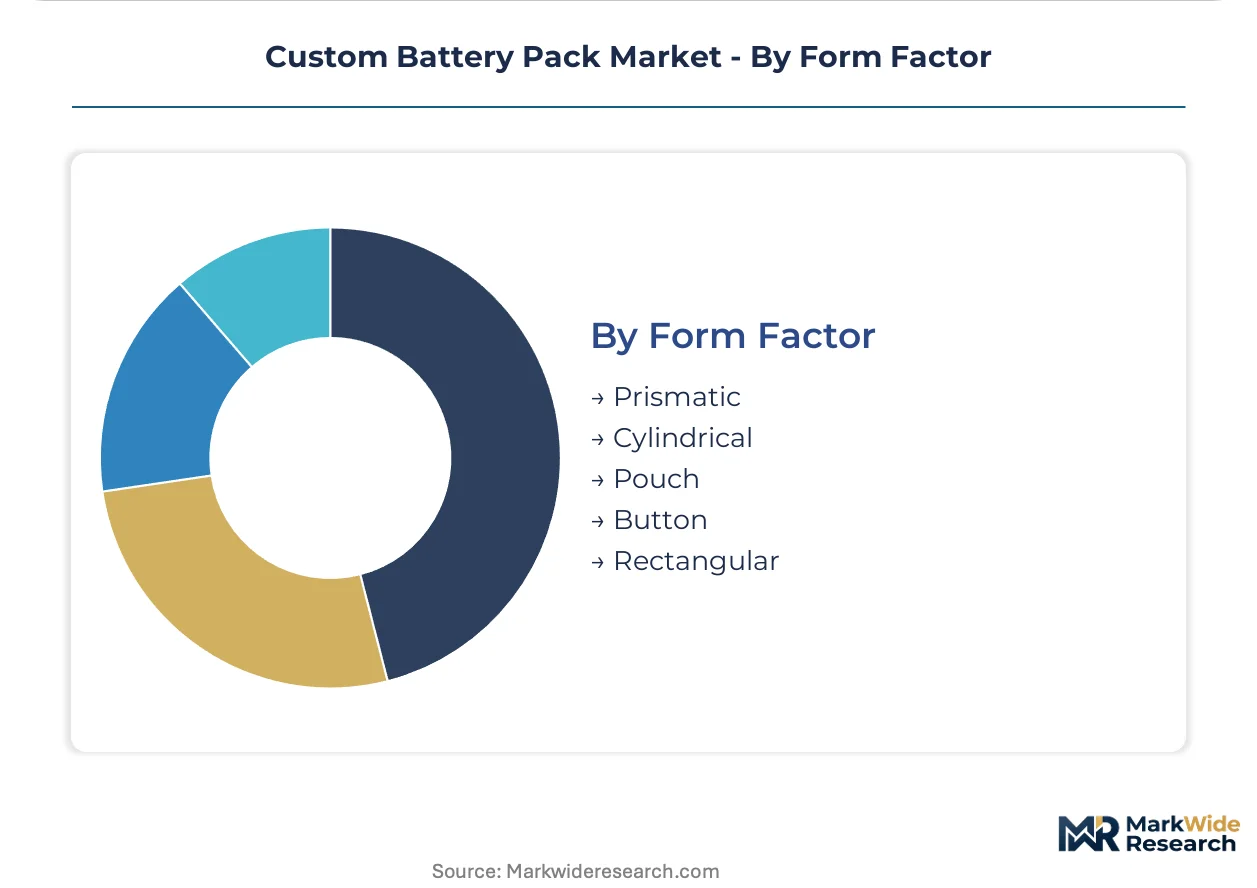
Form Factor:
Design flexibility and space optimization are paramount considerations influencing the selection of battery pack form factors across diverse applications, from consumer devices to industrial machinery.
- Pouch:Pouch cells offer superior design flexibility, allowing manufacturers to create ultra-thin and custom-shaped battery packs for space-constrained devices. This form factor is gaining traction in South Korea and China for consumer electronics and wearable technology, where compact designs are critical.
- Cylindrical:Cylindrical cells provide robust mechanical stability and excellent thermal management, making them suitable for high-power applications. The electric vehicle sector in the United States and Germany heavily relies on cylindrical cells for their reliability and performance characteristics.
- Prismatic:Prismatic cells offer a balance of energy density and efficient space utilization, commonly found in larger battery modules for EVs and energy storage.
- Button:Button cells are miniature, low-power batteries used in small electronic devices, medical implants, and watches due to their compact size.
- Rectangular:Rectangular form factors are often custom-designed for specific industrial equipment, providing a balance of capacity and fit.
Pouch cells are gaining rapid adoption for their adaptability. Cylindrical cells maintain a dominant position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery cell components from Asian suppliers often flow into European and North American assembly hubs for custom pack integration. This global supply chain supports diverse applications from electric vehicles to grid storage solutions. Demand for custom battery packs is geographically concentrated in regions with robust automotive, electronics, and renewable energy sectors.
China
China's extensive electric vehicle manufacturing base drives substantial demand for custom battery packs. The MIIT's policies support domestic battery production and technological innovation. Major EV and electronics manufacturing clusters in the Yangtze River Delta concentrate significant pack assembly operations.
Germany
German automotive OEMs and industrial equipment manufacturers require specialized custom battery solutions. The EU's Battery Regulation mandates traceability and sustainable material sourcing for packs. Bavaria and Baden-Württemberg host key automotive research and development centers for advanced battery integration.
United States
The United States sees strong demand for grid energy storage and specialized EV applications. The Inflation Reduction Act (IRA) provides significant incentives for domestic battery manufacturing. California and Texas are emerging hubs for large-scale energy storage projects and EV battery pack assembly.
Japan
Japanese consumer electronics and automotive sectors consistently require high-performance custom battery packs. METI's industrial policies encourage advanced battery material research and development. The Kanto region, including Tokyo, remains a center for electronics innovation and battery pack design.
South Korea
South Korea's leadership in consumer electronics and wearable medical devices fuels custom lithium polymer pack demand. The country's national regulators promote battery safety standards and recycling initiatives. Seoul and Gyeonggi Province house major R&D facilities for advanced battery cell and pack technologies.
Custom Battery Pack Market Key Industry Players
Player mix skews toward specialized engineering firms and large-scale cell manufacturers offering customized solutions. The market exhibits a tiered structure, with a few integrated giants and numerous niche players dominating distinct segments. Strategic archetypes include high-volume automotive suppliers, application-specific industrial specialists, and emerging technology innovators. Companies are pursuing both capacity expansion and strategic partnerships to secure raw materials and integrate advanced battery management systems.
Within the high-volume automotive and energy storage segments, LG Energy Solution and Microvast Holdings exemplify global scale and specialized technology offerings. LG Energy Solution leverages its cell production capabilities for automotive partners, while Microvast Holdings focuses on fast-charging systems for commercial vehicles. EnerSys occupies a position as a long-standing industrial motive power specialist, demonstrating resilience in traditional applications. These companies represent distinct approaches to market penetration and technology leadership in custom battery pack solutions.
| Leading Market Players |
|---|
| EnerSys |
| Tesla Energy |
| Copow |
| Sunwoda |
| LG Energy Solution |
| Emerging Power |
| Microvast Holdings |
| Delongtop |
| A123 Systems |
| Others |
Cost & Logistics Intelligence
The EU Battery Passport regulation gates both supply qualification and price differentiation for custom battery packs. This framework mandates material traceability and recycled content, influencing sourcing costs and market access for compliant manufacturers across Europe.
Pricing Analysis
Solid-state battery technology commands a significant price premium over conventional lithium-ion designs, reflecting its enhanced safety and energy density. Project-based pricing dominates the custom battery pack market, with value-based models for highly specialized applications. Customization level and stringent UN 38.3 certification drive price differentiation across various tiers. Pricing softness stems from intense competition in high-volume EV segments, while aerospace clients exhibit low price sensitivity for critical systems.
Supply Chain Analysis
The geographic concentration of high-performance battery cell production in China creates a significant chokepoint for global pack assemblers. Supply chains for custom battery packs draw from critical materials like lithium, cobalt, and nickel, primarily sourced from China, South Korea, and Japan. Commodity price volatility for these inputs represents a structural supply chain risk, impacting long-term contract stability. Distribution runs through direct OEM supply channels and specialized integrators for niche applications like medical devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing an early-cycle expansion, driven by the rapid penetration of electric vehicles into global transportation. This dynamic creates significant opportunities and strategic imperatives for various market participants.
For Market Incumbents: Consolidate application-specific engineering expertise by acquiring specialized design firms. Incumbents must also invest in onshore battery cell production capacity within North America and Europe to mitigate raw material volatility and geopolitical risks. Deep R&D into next-generation chemistries like solid-state batteries provides a hedge against emerging technology threats. Prioritizing UN 38.3 and CE certification across diverse product lines defends market access.
For New Entrants and Emerging Players: A service-layer gap exists in standardized communication protocols between BMS and host devices. Target micromobility applications in Europe, where demand for lightweight, durable packs with unique form factors is high. Focus on modular pack designs for grid energy storage, offering flexible integration solutions. Leverage Battery-as-a-Service models to lower initial customer purchase barriers in commercial fleets.
For Investors and Strategic Acquirers: The EU's Battery Regulation reshapes the acquisition landscape, favoring companies with strong material traceability and circular economy capabilities. This market offers long-term viability, driven by its essential role in electric mobility and grid decarbonization over the next decade. Seek specialized engineering firms proficient in thermal management and embedded BMS software. The uptake of domestic production incentives, like the US IRA, signals regional market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced BMS software development | Enhances pack intelligence and predictive maintenance capabilities for fleet operators. |
| Expand pouch cell manufacturing capacity | Supports design flexibility for consumer electronics and wearable medical devices. |
| Form partnerships for raw material sourcing | Secures supply chains for lithium and cobalt, mitigating commodity price volatility. |
| Develop second-life battery repurposing programs | Creates new revenue streams and addresses end-of-life management under EU regulations. |
| Localize pack assembly in North America | Leverages US Inflation Reduction Act incentives for domestic production. |
Research Approach
The analysis maps custom battery pack sub-sectors including electric vehicles, grid storage, and consumer electronics, each validated through primary interviews with electrochemistry engineers and OEM procurement leads. Secondary research integrated national energy agency reports, automotive industry association data, and corporate financial filings. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data coverage.
Forecast outputs were validated against external benchmarks from leading industry consortia and government energy projections across the analysis window. The analytical framework modeled key segmentation dimensions including battery chemistry, application, end-user, and form factor. Compound Annual Growth Rates were derived from historical trends and projected future demand, informed by EV production forecasts and renewable energy deployment targets.
Underlying assumptions cover stable raw material supply and consistent regulatory enforcement. Deviation risk concentrates in geopolitical shifts affecting critical mineral access or sudden policy changes. Revision becomes warranted when raw material supply stability or major regulatory frameworks cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
3D-Printed Battery Market
Batteries
Silicon Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Portable Battery Station Market
Batteries
India Alkaline Battery Market
Batteries
Secondary Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
Solid Electrolyte Market
Batteries
Atomic Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
South America Primary Battery Market
Batteries
Drone Power Sources Market