
 Drone Lithium Battery Charger Market | 2026-2036
Drone Lithium Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Lithium Battery Charger Market Insights
A shortage of power electronics engineers with lithium-polymer safety certification is redrawing competitive boundaries across the charger supply base. Shenzhen Grepow Battery leverages its captive cell production to control charger-to-pack compatibility and shorten development cycles. Panasonic Corporation sustains technology leadership through its proprietary battery management algorithms that extend cycle life under fast-charge conditions. Samsung SDI anchors high-volume manufacturing for enterprise drone fleets with standardized thermal architectures.
Drone lithium battery chargers are power conversion systems that transform AC or DC input into controlled charge profiles—typically CC-CV (constant current-constant voltage) with 0.5C to 5C rate capability—matched to lithium-polymer or lithium-ion cell chemistries, serving the primary purpose of minimizing charge time while preventing thermal runaway in airborne battery packs. Fast chargers occupy the dominant revenue position due to commercial operators prioritizing fleet utilization over hardware cost, though wireless chargers are gaining structural momentum as inspection drones adopt contactless docking for automated hangar workflows. Smart charging technology concentrates margin pools because firmware-enabled cell balancing and predictive degradation analytics command premium pricing from enterprise operators managing large battery inventories.
The FAA mandates UN 38.3 lithium battery transport compliance that cascades into charger design requirements for thermal monitoring and fail-safe cutoff thresholds, while EASA's drone-specific airworthiness directives impose documentation burdens on non-EU charger suppliers seeking market access. China's GB standards for lithium-ion battery safety, enforced by SAMR, create a parallel compliance track that domestic manufacturers navigate more efficiently than foreign competitors. Stakeholders must monitor how evolving inductive charging efficiency standards reshape hardware form factors and whether regulatory divergence between aviation authorities fragments certification costs for multi-region product portfolios.
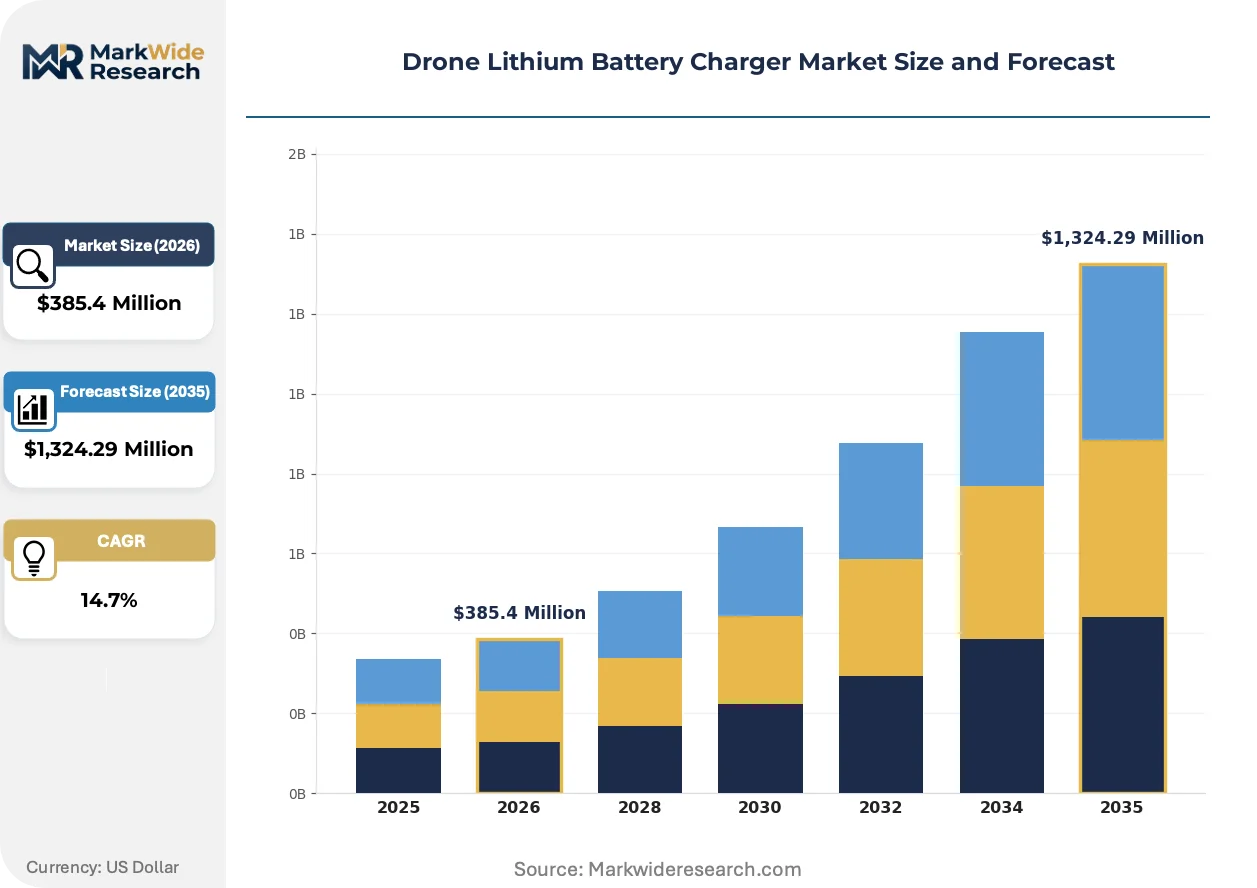
Market Dynamics
Commercial drone operators in precision agriculture are intensifying flight-hour requirements, forcing charger procurement cycles to compress from annual to quarterly replenishment schedules.
Growth Catalysts
- Precision agriculture flight-hour mandates:Commercial operators in crop monitoring and spraying applications now require continuous battery rotation, creating sustained hardware procurement velocity.
- FAA thermal-management standards:UN 38.3 lithium battery transport compliance cascades into charger design specifications that prioritize safety-certified equipment over uncertified alternatives.
- Shenzhen manufacturing cluster density:Proximity between cell production and charger assembly shortens development cycles and enables rapid specification adjustments for UAV OEMs.
Market Restraints
- Power electronics engineer scarcity:Lithium-polymer safety certification requirements exceed available qualified personnel, constraining supplier expansion.
- Inductive charging efficiency limitations:Contactless power transfer losses of 10-15% versus wired alternatives deter adoption in battery-intensive applications.
- Regulatory fragmentation costs:Divergent FAA, EASA, and SAMR certification tracks force multi-region suppliers to maintain parallel compliance infrastructures.
Strategic Opportunities
- Automated hangar workflows:Inspection drones adopting contactless docking create structural momentum for wireless charger integration.
- Predictive degradation analytics:Firmware-enabled cell balancing commands premium pricing from enterprise operators managing large battery inventories.
- GB standards navigation efficiency:Domestic Chinese manufacturers leverage SAMR regulatory familiarity to accelerate product launches versus foreign competitors.
Industry Challenges
- CC-CV algorithm specialization:Fast-charge cycle life extension requires proprietary battery management expertise that concentrates among established suppliers.
- Multi-authority certification timelines:EASA drone-specific airworthiness directives impose documentation burdens that delay market entry for non-EU hardware suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Lithium Battery Charger Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,324.29 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: Fast Charger, Standard Charger, Wireless Charger, Solar Charger, Multi-Port Charger Technology: Smart Charging, Pulse Charging, CCCV Charging, Inductive Charging, USB Type-C Charging Application: Commercial Drones, Agricultural UAVs, Mapping Drones, Inspection Drones, Delivery UAVs End User: Enterprise Operators, Research Institutions, Government Agencies, Video Production, Surveillance Firms |
| Companies Covered | EaglePicher Technologies, RRC Power Solutions GmbH, LG Chem, Shenzhen Grepow Battery, Plug Power Inc., Intelligent Energy Limited, Doosan Mobility Innovation, Panasonic Corporation, Samsung SDI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Lithium Battery Charger Market Trends and Innovations
Charger architecture is splitting between high-rate wired systems for commercial fleets and contactless platforms for automated infrastructure, with firmware capabilities determining margin capture.
Silicon carbide power semiconductors are replacing silicon MOSFETs in high-rate charger designs, enabling 5C charge rates without thermal derating. Agricultural drone fleet operators in the United States and Brazil are adopting these platforms fastest, compressing turnaround times below fifteen minutes per battery pack. The technology is bifurcating the supplier base between premium fast-charge specialists and cost-optimized standard-rate manufacturers.
EASA's forthcoming drone-specific airworthiness directives will mandate documented thermal runaway propagation testing for all charging hardware sold within the European Union. This industrial consequence forces non-EU suppliers to establish EU-based testing partnerships or cede market position. Enterprise fleet operators with cross-border deployment needs are consolidating procurement around suppliers with pre-certified multi-region product portfolios.
Enterprise buyers are unbundling charger procurement from battery pack purchases, treating charging infrastructure as a separate capital category with independent vendor evaluation. This pattern disrupts traditional OEM-captive supply arrangements and opens direct procurement channels for specialized charger manufacturers. The shift is most visible in China, where Shenzhen-based UAV operators now source chargers independently from cell suppliers to optimize total cost of ownership across mixed fleet deployments.
Drone Lithium Battery Charger Market Segmentation
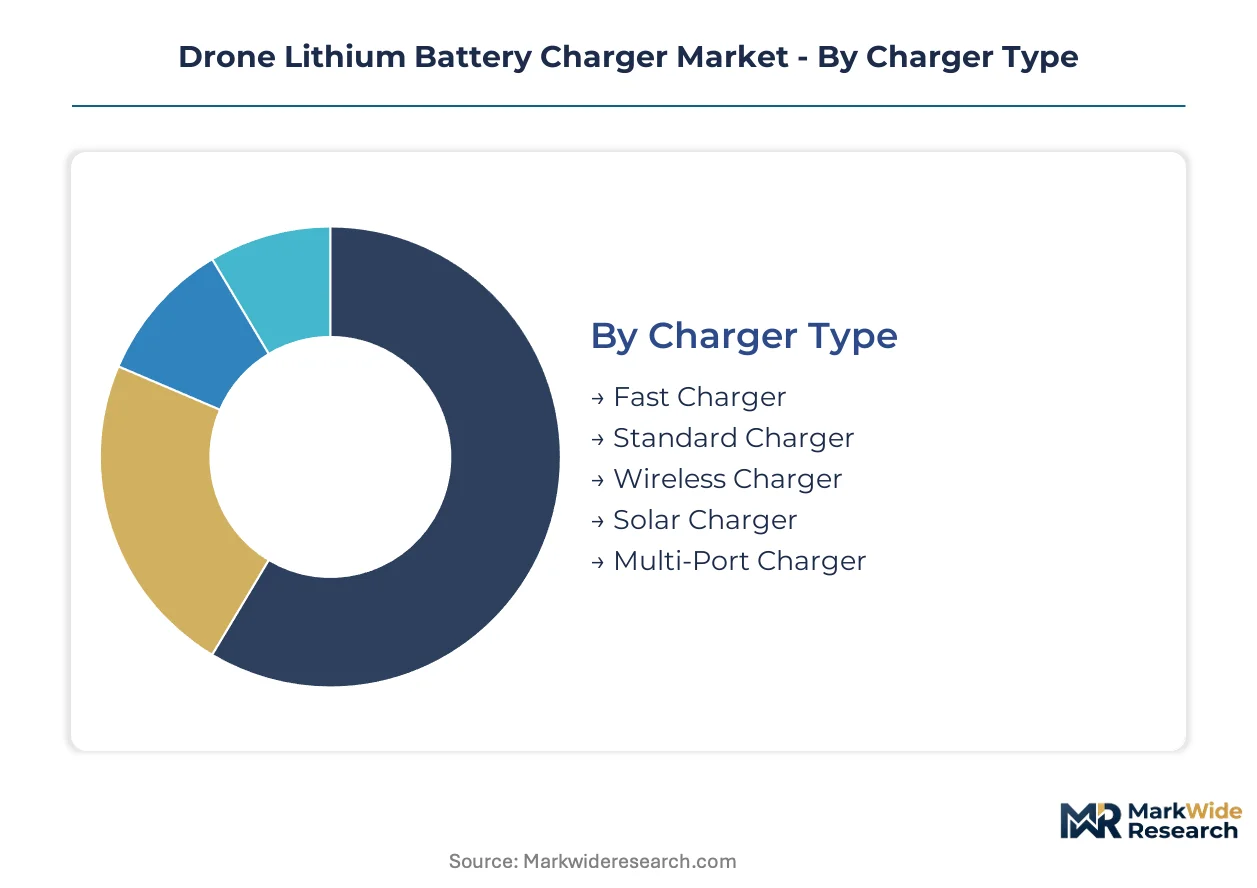
Segmentation in the drone lithium battery charger market reveals how procurement patterns split between fleet operators prioritizing turnaround velocity and infrastructure planners optimizing for automation. Understanding these divides exposes where suppliers can command premium pricing versus competing on hardware cost.
Charger Type:
Margin pools concentrate in high-rate charging systems where thermal management complexity creates barriers to commoditization.
- Fast Charger:These systems deliver 3C to 5C charge rates using silicon carbide power semiconductors that minimize thermal derating. Agricultural UAV operators in Brazil and the United States are adopting these platforms fastest to compress battery rotation below fifteen minutes.
- Wireless Charger:Contactless power transfer systems enable automated hangar workflows for inspection drones, though 10-15% efficiency losses versus wired alternatives constrain deployment in battery-intensive commercial fleets.
- Standard Charger:0.5C to 1C rate systems serve cost-sensitive hobbyist and light commercial segments with simplified thermal architectures.
- Solar Charger:Field-deployable photovoltaic systems support remote agricultural monitoring operations where grid access is limited.
- Multi-Port Charger:Parallel charging bays accommodate enterprise battery inventories, with firmware-enabled cell balancing commanding premium pricing from fleet operators.
The dominant share belongs to Fast Charger systems, while Wireless Charger adoption is expanding most quickly in automated infrastructure deployments.
Technology:
Technology differentiation determines whether suppliers capture value through hardware performance or recurring firmware revenue streams.
- Smart Charging:Battery management algorithms with predictive degradation analytics extend cycle life under aggressive charge profiles. Enterprise operators managing large battery inventories pay substantial premiums for these firmware-enabled capabilities.
- CCCV Charging:Constant current-constant voltage protocols remain the foundational architecture across most commercial applications, with optimization focused on transition point precision and thermal cutoff reliability.
- Pulse Charging:Intermittent current delivery methods reduce lithium plating in high-rate scenarios, though implementation complexity limits adoption to specialized aerospace applications.
- Inductive Charging:Resonant magnetic coupling systems eliminate physical connectors for docking-based workflows, with efficiency improvements narrowing the performance gap versus conductive alternatives.
- USB Type-C Charging:Standardized power delivery protocols penetrate consumer and prosumer drone segments where interoperability reduces accessory complexity.
Smart Charging commands the highest margin per unit, while Inductive Charging is gaining share fastest in inspection and logistics automation.
Application:
Application segmentation tracks how flight-hour intensity and operational tempo reshape procurement specifications across drone mission profiles.
- Agricultural UAVs:Crop spraying and monitoring operations demand continuous battery rotation across extended daily flight windows. Operators in precision agriculture now replenish charger hardware on quarterly rather than annual cycles.
- Inspection Drones:Infrastructure and energy sector deployments prioritize automated docking systems that eliminate manual battery handling. Contactless charging integration is restructuring procurement specifications for this segment.
- Commercial Drones:General enterprise fleets span mixed use cases with standardized charging infrastructure that balances rate capability against capital cost.
- Mapping Drones:Surveying operations emphasize energy density and flight endurance over rapid turnaround, accepting slower charge rates for pack longevity.
- Delivery UAVs:Last-mile logistics operators are piloting automated battery swap and charge stations, though regulatory frameworks for beyond-visual-line-of-sight operations remain unsettled.
Agricultural UAVs generate the largest hardware procurement volumes, while Inspection Drones are driving the steepest specification upgrades toward automation.
End User:
End user categories reveal divergent purchasing authority structures, from centralized fleet procurement to decentralized project-based acquisition.
- Enterprise Operators:Large-scale drone fleet managers unbundle charger procurement from battery pack purchases, treating charging infrastructure as independent capital with dedicated vendor evaluation. This pattern is most visible among Shenzhen-based UAV operators optimizing total cost of ownership.
- Government Agencies:Public sector procurement emphasizes multi-region certification portfolios and documented thermal runaway propagation testing, consolidating supplier relationships around pre-qualified vendors.
- Research Institutions:Academic and development laboratories prioritize flexible charge profile programming and open protocol access for experimental cell chemistries.
- Video Production:Media sector operators balance portability against charge speed, accepting trade-offs that commercial fleets reject.
- Surveillance Firms:Security service providers demand ruggedized field-deployable systems with minimal maintenance requirements for extended outdoor operations.
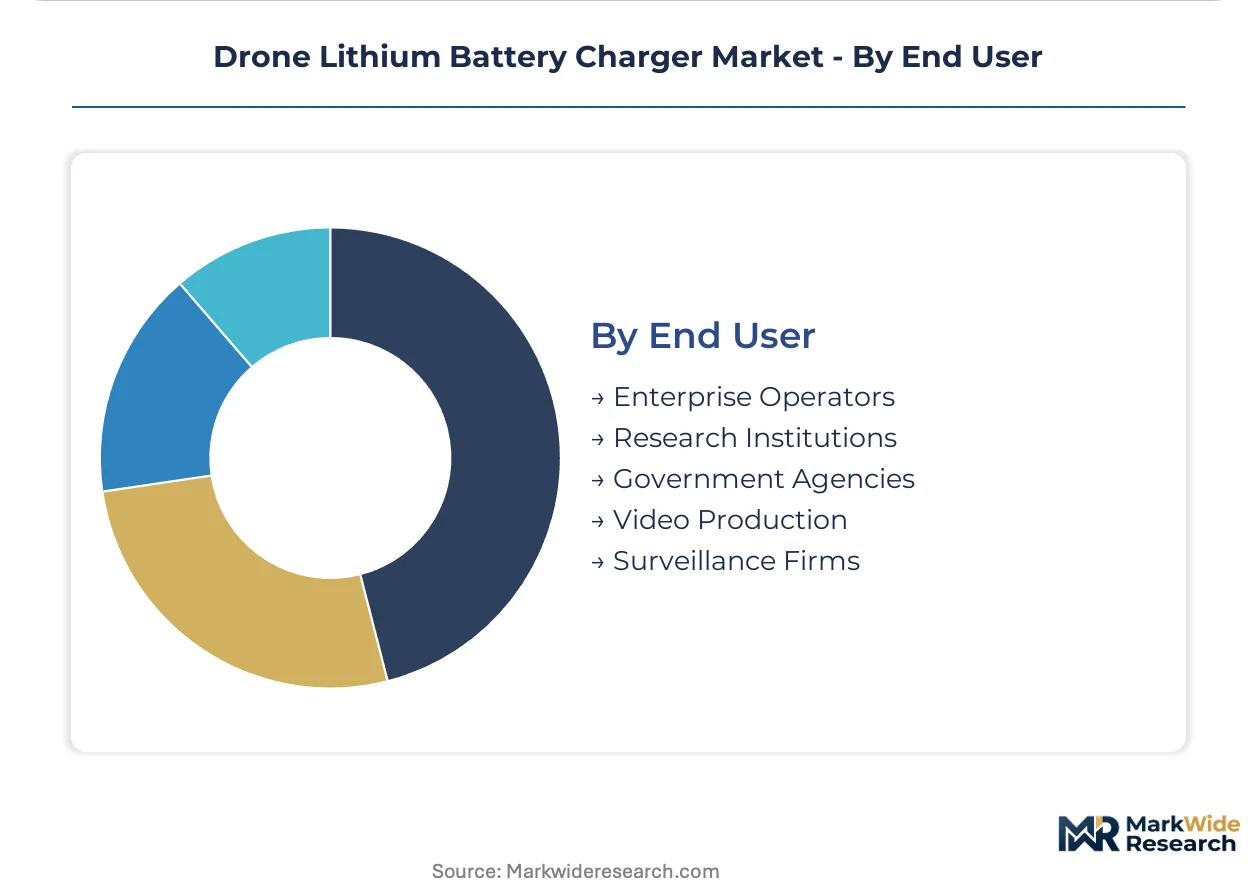
Enterprise Operators account for the dominant procurement value, with Government Agencies representing the most rapidly tightening compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA thermal-management mandates and EASA airworthiness directives are reshaping procurement specifications across the three dominant manufacturing geographies. Charger suppliers must navigate parallel certification tracks while regional manufacturing clusters exploit proximity advantages.
United States
Precision agriculture operators in California's Central Valley and the Midwest Corn Belt are compressing charger replenishment cycles to quarterly schedules. FAA UN 38.3 compliance requirements cascade into hardware specifications that prioritize safety-certified equipment. Dallas-Fort Worth anchors enterprise fleet procurement, with agricultural UAV operators unbundling charger purchases from battery pack acquisitions.
China
Shenzhen's battery manufacturing cluster feeds domestic UAV OEMs and export channels with shortened development cycles. SAMR enforces GB standards for lithium-ion battery safety that domestic manufacturers navigate more efficiently than foreign competitors. The Pearl River Delta concentration enables rapid specification adjustments as flight-hour requirements intensify across agricultural and inspection applications.
Germany
Industrial inspection drone deployments prioritize automated docking systems with contactless charging integration. EASA's forthcoming airworthiness directives mandate documented thermal runaway propagation testing for all charging hardware. Munich and Stuttgart host testing partnerships that non-EU suppliers must establish to maintain market access.
Japan
METI industrial policy supports silicon carbide power semiconductor adoption in high-rate charger designs. Enterprise fleet operators consolidate procurement around suppliers with pre-certified multi-region product portfolios. Tokyo-Osaka industrial corridors concentrate precision electronics manufacturing for aerospace-grade charging hardware.
Brazil
Agricultural UAV operators in Mato Grosso and São Paulo states are adopting silicon carbide-enabled fast chargers fastest to compress turnaround below fifteen minutes. ANVISA pharmaceutical-equipment safety protocols influence adjacent battery handling standards. Campinas anchors South American distribution for premium fast-charge systems serving soy and sugarcane monitoring fleets.
Drone Lithium Battery Charger Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling captive cell production and proprietary battery management algorithms. The middle tier competes on thermal architecture standardization and multi-port parallel charging configurations. Strategic archetypes include cell-integrated charger specialists, power electronics component suppliers, and firmware-enabled analytics providers. Competitive moves concentrate on backward integration into semiconductor sourcing and geographic expansion through EU-based testing partnerships.
Among East Asian battery conglomerates, LG Chem, Samsung SDI, and Panasonic Corporation exemplify the integrated leader archetype through upstream control over cell chemistry and downstream charger compatibility. Shenzhen Grepow Battery occupies a position within the captive production tier, leveraging geographic proximity to UAV OEMs. RRC Power Solutions GmbH and Intelligent Energy Limited represent European specialists navigating EASA certification requirements. EaglePicher Technologies and Plug Power Inc. anchor North American supply for defense and industrial applications respectively.
| Leading Market Players |
|---|
| EaglePicher Technologies |
| RRC Power Solutions GmbH |
| LG Chem |
| Shenzhen Grepow Battery |
| Plug Power Inc. |
| Intelligent Energy Limited |
| Doosan Mobility Innovation |
| Panasonic Corporation |
| Samsung SDI |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Shenzhen's silicon carbide foundries determines price floors for high-rate charger modules, concentrating margin capture among suppliers with captive semiconductor sourcing while forcing cost-optimized tiers toward commodity power MOSFETs.
Pricing Analysis
Price spreads between Shenzhen-assembled units and EU-certified alternatives span three-to-four certification tiers, with FCC and EASA thermal-runaway documentation adding substantial compliance premiums. Pricing stratifies across premium smart-charging systems, standard CC-CV architectures, and economy hobbyist tiers, with firmware-enabled predictive analytics commanding the widest spreads. Cost compression in standard-rate segments intensifies as Chinese domestic manufacturers scale GB-standard production. Agricultural fleet operators in Brazil and the United States show least price sensitivity, prioritizing fifteen-minute turnaround over hardware cost.
Supply Chain Analysis
Port congestion along the Shenzhen-Los Angeles trade lane elevates inbound logistics costs for silicon carbide wafers and lithium-polymer safety certification components. Manufacturing concentrates in China, South Korea, and Japan, with cell production anchored in the Pearl River Delta and power semiconductor fabrication centered in Hsinchu and Seoul. The supply chain draws from cobalt-free cathode chemistries, ceramic substrate materials, and FAA-compliant thermal sensors. Single-source vulnerability around silicon carbide epitaxy equipment threatens capacity expansion timelines. Distribution runs through UAV OEM direct procurement channels and independent industrial distributors serving enterprise fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward enterprise fleet operators unbundling charger procurement from battery pack purchases, consolidating vendor relationships around multi-region certified suppliers as procurement authority centralizes.
For Market Incumbents: Shield firmware-enabled margin pools by deepening proprietary battery management algorithm development against emerging analytics specialists. Prioritize EASA pre-certification investments to capture inspection drone automation demand before non-EU competitors establish Munich or Stuttgart testing partnerships. Backward integration into silicon carbide sourcing secures cost positioning for 5C-rate product lines.
For New Entrants and Emerging Players: Anchor in wireless charging infrastructure for automated hangar workflows, where efficiency improvements and standardization gaps create penetrable white space. Target agricultural UAV operators in Brazil's Mato Grosso region with field-ruggedized fast-charge systems. Pursue direct procurement relationships with Shenzhen-based fleet operators bypassing traditional OEM-captive channels.
For Investors and Strategic Acquirers: Firmware-enabled analytics providers with predictive degradation capabilities represent the most defensible acquisition archetype as enterprise operators prioritize battery inventory management software. Long-term viability hinges on regulatory divergence between FAA, EASA, and SAMR certification tracks persisting. Watch for EASA airworthiness directive implementation timelines as inflection signals for EU market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Semiconductor Integration | Enables 5C fast-charge rates without thermal derating for agricultural UAV fleets. |
| EASA Pre-Certification Investment | Secures market access before thermal runaway propagation testing mandates take effect. |
| Firmware-Enabled Predictive Analytics Development | Commands premium pricing from enterprise operators managing large battery inventories. |
| Wireless Charging Infrastructure Partnership | Captures inspection drone automation demand as contactless docking standardizes. |
| Backward Integration into Cell Production | Controls charger-to-pack compatibility and compresses development cycles for UAV OEMs. |
Research Methodology
Operator-level perspectives from commercial drone fleet managers, agricultural UAV procurement leads, power electronics engineers with lithium-polymer safety certification, and EASA regulatory affairs specialists anchored the qualitative base. Primary interview findings triangulated against FAA UN 38.3 compliance documentation, SAMR GB standard filings, silicon carbide supply chain disclosures from major foundries, and customs data tracking charger hardware trade flows. Bottom-up unit economics from enterprise deployment models reconciled with top-down market sizing across charger type, technology, and application segments.
Sensitivity analysis tested forecast robustness against variables including inductive charging efficiency improvements, EASA certification timeline acceleration, and silicon carbide capacity expansion rates. The analytical framework modeled segmentation across charger architecture, firmware capability tier, flight-hour intensity application, and buyer procurement structure throughout the projection horizon. CAGRs derived from regression analysis of historical procurement velocity against flight-hour mandate intensification and regulatory compliance cost trajectories. Forecast inputs incorporated lithium-polymer cell chemistry evolution and thermal management semiconductor cost curves.
Material uncertainties — regulatory divergence between aviation authorities, silicon carbide supply bottlenecks, and wireless charging standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions around continued enterprise fleet operator procurement unbundling and sustained precision agriculture flight-hour expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
East Asia Battery Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Japan Battery Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
N-Type Battery Market
Batteries
Battery Cases Market
Batteries
Wide Temperature Battery Market
Batteries
South Africa Battery Market
Batteries
North America Lead Acid Battery Market
Batteries
Battery Light Towers Market
Batteries
Zinc-Manganese Oxide Batteries Market