
 Automotive Start-Stop Battery Market | 2026-2036
Automotive Start-Stop Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Start-Stop Battery Market Outlook
Aftermarket service revenue is fragmenting across battery recycling, diagnostic testing, and warranty management as vehicle electrification reshapes profit pools. Exide leverages its recycling infrastructure to capture spent battery value streams. Bosch competes through integrated start-stop system engineering that bundles battery management with powertrain controls. Varta specializes in absorbent glass mat technology for premium cycling endurance.
Automotive start-stop batteries are rechargeable energy storage devices engineered for high-cycle durability, typically featuring enhanced lead-calcium or lithium-iron-phosphate chemistries capable of sustaining thousands of shallow discharge events per year. Their primary purpose is to power vehicle electrical loads during engine-off intervals and restart combustion engines seamlessly, reducing idle fuel consumption and tailpipe emissions. Lead acid products occupy the volume tier due to cost parity with conventional batteries, while lithium-ion chemistries represent the fastest-expanding segment as micro-hybrid architectures demand deeper cycling capability. OEM channel concentration anchors margin stability, whereas aftermarket providers face pricing pressure from commoditized replacement demand.
EPA tailpipe standards in the United States, EU Green Deal vehicle emissions frameworks, and China's MIIT fuel consumption regulations collectively mandate CO2 reductions that OEMs achieve partly through start-stop proliferation. ECE R100 and UN 38.3 testing protocols govern lithium-ion battery safety certification, creating compliance barriers for new entrants. Stakeholders must monitor how solid-state prototyping and sodium-ion alternatives disrupt incumbent chemistry roadmaps before next-generation platform commitments lock in.
Market Dynamics
The EU F-Gas Regulation and parallel emissions mandates across multiple geographies are forcing OEMs to specify batteries capable of sustaining 10,000-plus shallow discharge cycles annually, compressing replacement intervals and reshaping supplier qualification criteria.
Growth Catalysts
- EU Green Deal vehicle emissions frameworks:The framework mandates CO2 reductions that OEMs achieve through start-stop proliferation, directly expanding battery procurement volumes for new vehicle platforms.
- Micro-hybrid architecture penetration:48V mild-hybrid systems require deeper cycling capability than conventional 12V start-stop, pulling lithium-iron-phosphate chemistries into volume production.
- Urban traffic congestion patterns:Stop-and-go driving in megacities like São Paulo and Jakarta maximizes start-stop activation frequency, accelerating wear rates and shortening replacement cycles in aftermarket channels.
Market Restraints
- Lead price volatility:Lead acid batteries occupy the volume tier, making producers vulnerable to London Metal Exchange price swings that compress margin buffers on contracted OEM supply.
- Recycling infrastructure concentration:Spent battery collection and smelting capacity clusters in China and Germany, creating geographic single-points-of-failure for closed-loop material recovery.
- Lithium-ion thermal runaway risk:ECE R100 testing protocols impose certification timelines and engineering costs that deter mid-tier suppliers from entering the premium cycling segment.
Strategic Opportunities
- India's MIIT-aligned fuel efficiency norms:The country's tightening corporate average fuel consumption standards create regulatory pull for start-stop adoption in domestic passenger vehicle production.
- Sodium-ion chemistry maturation:Emerging alternatives to lithium-iron-phosphate offer raw material cost advantages and temperature stability for price-sensitive fleet applications.
- Diagnostic-enabled aftermarket channels:Battery health monitoring via telematics platforms enables predictive replacement scheduling, shifting aftermarket capture from emergency breakdown toward planned maintenance.
Industry Challenges
- Electrochemical engineering talent scarcity:Deep cycling expertise specific to automotive start-stop duty profiles concentrates at a handful of research institutions and incumbent suppliers.
- UN 38.3 certification complexity:Lithium-ion variants require extensive safety testing documentation that extends product development cycles and strains smaller producers' technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Start-Stop Battery Market |
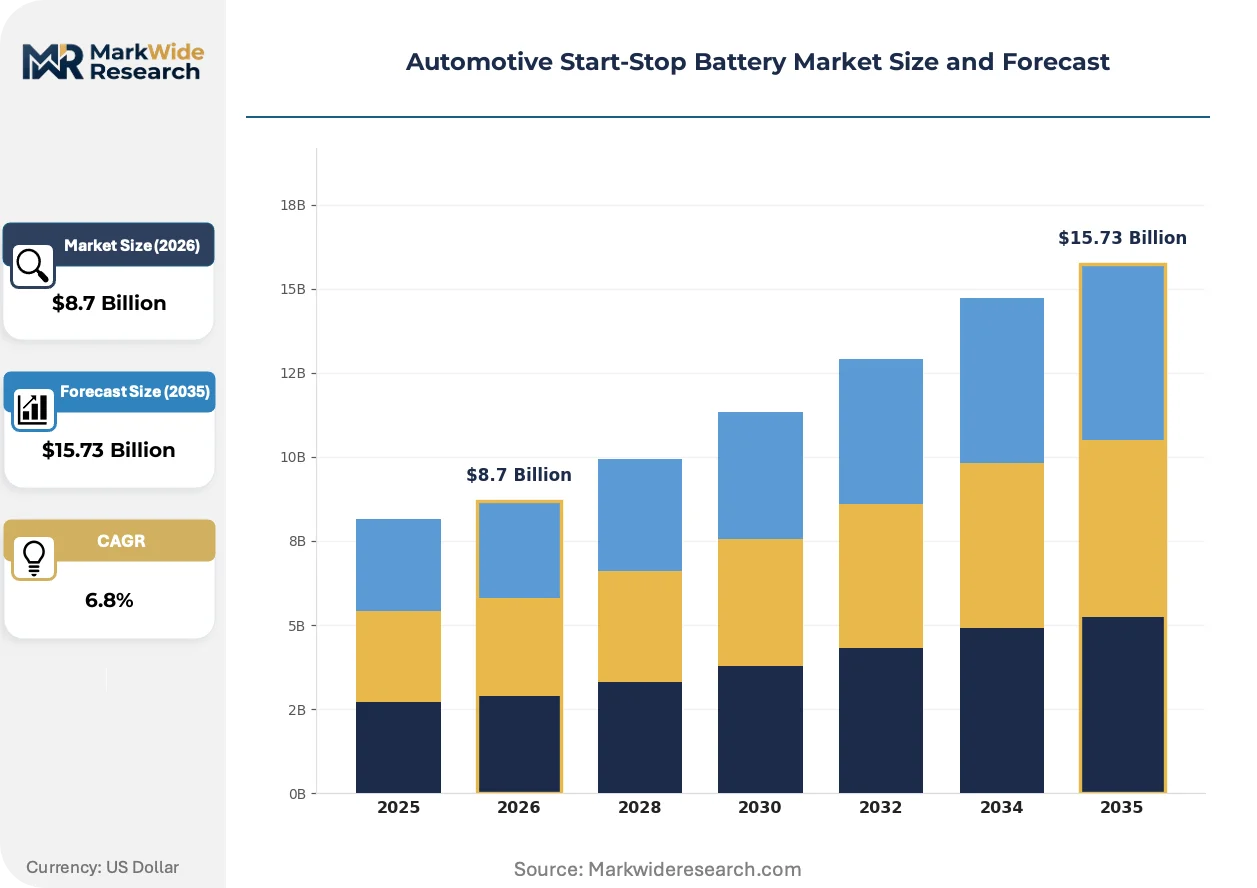
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-ion, Nickel Metal Hydride, Others End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: Hybrid, Regenerative, Micro Hybrid, Full Hybrid Application: Passenger Vehicles, Light Commercial Vehicles, Heavy-duty Vehicles, Trucks |
| Companies Covered | Exide, SK Battery America, Bosch, Amaron, East Penn Manufacturing, Varta, Panasonic, Yuasa, Clarios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Start-Stop Battery Market Strategic Shifts
Active materials engineering and intelligent battery management systems are converging to extend cycle life while reducing pack mass, compressing the performance gap between established lead acid architectures and emerging electrochemical alternatives.
Absorbent glass mat technology is hybridizing with carbon additives to enhance dynamic charge acceptance during regenerative braking events. German luxury OEMs specify these enhanced AGM variants for 48V mild-hybrid platforms. The chemistry is hybridizing conventional lead acid cost structures with lithium-ion cycling performance benchmarks, forcing suppliers to recalibrate R&D allocation between incremental improvement and platform replacement.
EPA tailpipe standards in the United States are tightening idle emissions thresholds that OEMs address through expanded start-stop deployment across light truck and SUV segments. The regulatory pressure cascades into battery supplier qualification requirements that emphasize cold-cranking reliability alongside cycling endurance. Domestic producers are responding by vertically integrating separator manufacturing to secure supply continuity for high-volume platform awards.
Fleet operators are unbundling battery procurement from vehicle acquisition, separating capital expenditure into lease structures with performance-guaranteed service contracts. Commercial vehicle lessors in North America now specify cycle-count warranties rather than calendar-life coverage. This reconfiguration shifts technical risk onto suppliers while compressing pricing transparency across OEM-direct and aftermarket channels.
Automotive Start-Stop Battery Market Segmentation
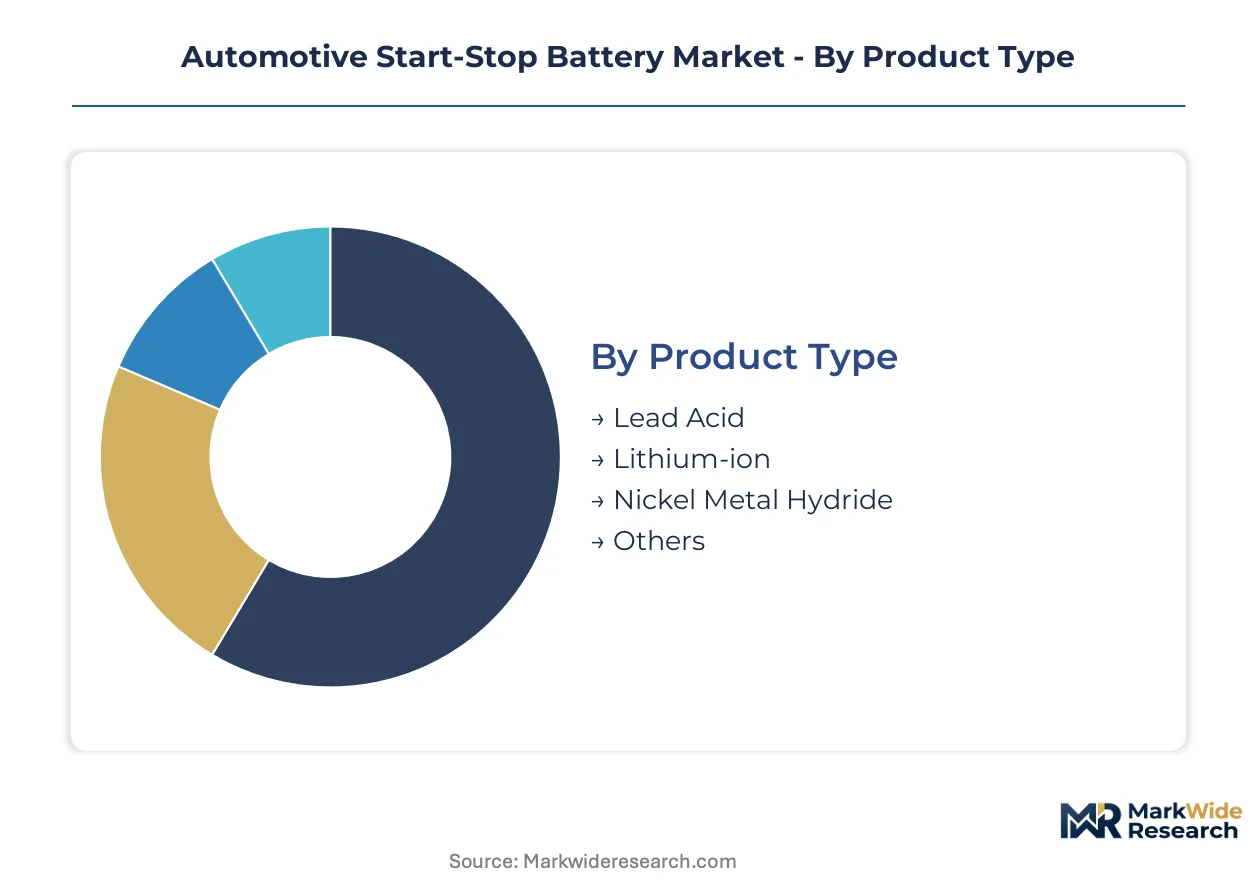
Automotive start-stop battery procurement patterns diverge sharply across chemistry types, customer channels, and vehicle electrification tiers. Understanding these fault lines reveals where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
Cost tier stratification separates mature lead acid architectures from emerging premium chemistries competing on cycle endurance.
- Lead Acid:Enhanced lead-calcium and absorbent glass mat formulations dominate 12V start-stop applications due to manufacturing scale and recycling infrastructure maturity. German OEMs specify AGM variants for entry-level platforms where cost parity with conventional batteries matters most.
- Lithium-ion:Lithium-iron-phosphate cells deliver deeper cycling capability for 48V mild-hybrid architectures. Chinese battery producers are scaling LFP capacity fastest as MIIT fuel consumption regulations pull micro-hybrid penetration upward.
- Nickel Metal Hydride:Legacy chemistry retains niche presence in Toyota hybrid platforms with established thermal management systems.
- Others:Sodium-ion prototypes target fleet price sensitivity with temperature stability advantages.
Lead acid commands the established base. The steepest expansion runs through lithium-ion.
End User:
Customer type determines contract structure, technical specification depth, and replacement cycle predictability.
- OEMs:Direct platform integration contracts span 5-7 year model cycles with stringent cold-cranking and cycling endurance specifications. Battery management system integration responsibilities often bundle with cell supply agreements.
- Aftermarket Providers:Emergency replacement demand concentrates in urban corridors with stop-and-go traffic patterns. São Paulo and Jakarta service networks report accelerated wear rates driving shorter replacement intervals.
- Tier-1 Suppliers:System-level procurement bundles battery hardware with powertrain control modules, compressing standalone cell supplier margins.
- Dealerships:Warranty administration and diagnostic testing reshape profit capture as electrification extends service intervals.
OEM channel concentration anchors margin stability. Aftermarket fragmentation accelerates as telematics-enabled predictive maintenance displaces emergency breakdown capture.
Technology:
Electrification maturity tiers segment duty profiles from shallow cycling to deep discharge regeneration events.
- Micro Hybrid:12V start-stop systems activate 10,000-plus shallow cycles annually under EU F-Gas Regulation pressure. German luxury OEMs specify enhanced AGM variants for idle emissions compliance.
- Full Hybrid:High-voltage architectures demand thermal runaway mitigation under ECE R100 protocols, extending supplier qualification timelines.
- Hybrid:Intermediate voltage platforms bridge conventional and full electrification with blended cycling requirements.
- Regenerative:Brake energy recovery imposes dynamic charge acceptance demands that carbon-additive AGM formulations address.
Micro hybrid commands the established base. Full hybrid architectures gain share fastest as EPA tailpipe standards tighten.
Application:
Vehicle weight class and duty cycle intensity segment performance requirements and replacement frequency.
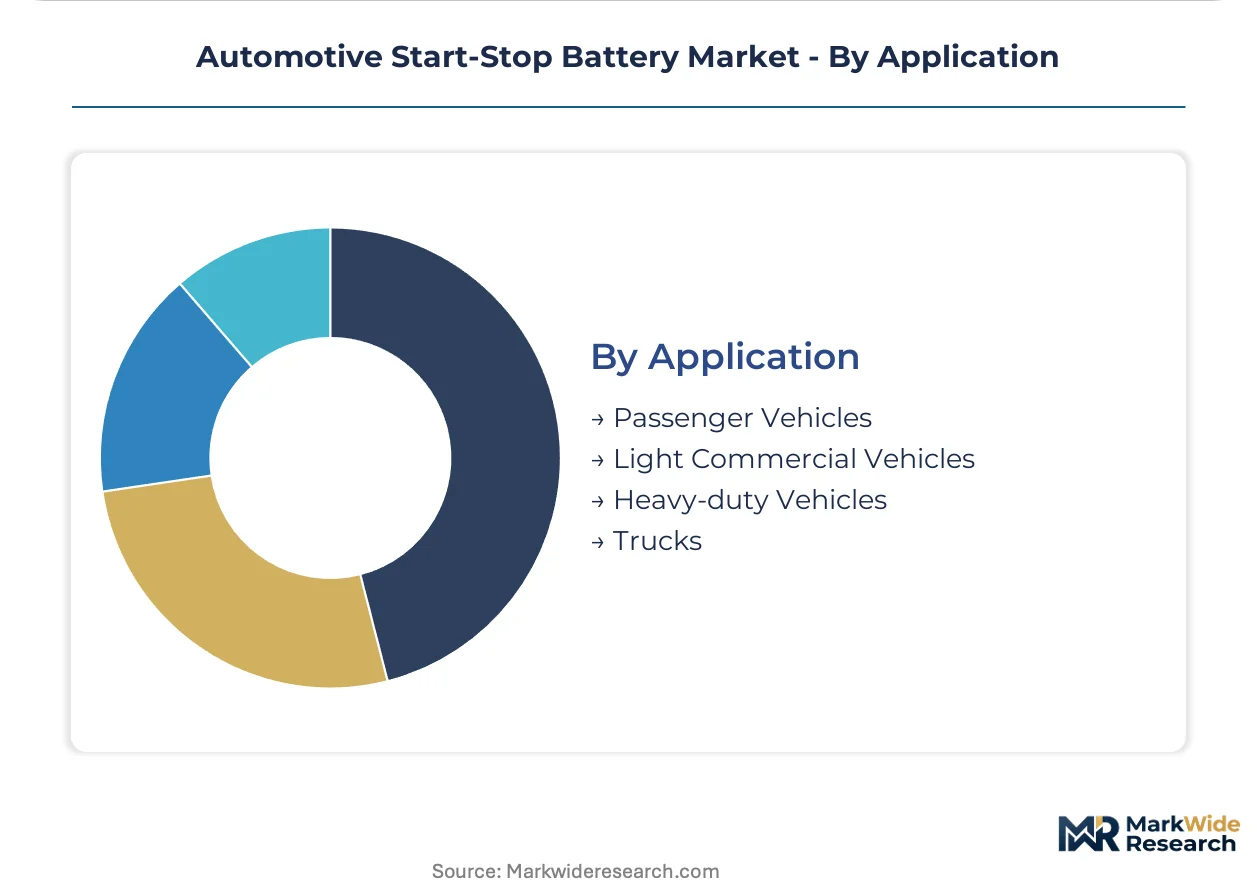
- Passenger Vehicles:Start-stop penetration deepest in European and Chinese new vehicle platforms. Fleet operators unbundle battery procurement from acquisition, shifting to performance-guaranteed service contracts.
- Light Commercial Vehicles:Urban delivery routes maximize activation frequency. North American lessors specify cycle-count warranties rather than calendar-life coverage.
- Heavy-duty Vehicles:Extended idle periods in vocational applications strain conventional cycling profiles.
- Trucks:Long-haul duty cycles limit start-stop utility; adoption concentrates in regional distribution segments.
Passenger vehicle applications command the established base. Light commercial vehicle electrification climbs the fastest as last-mile regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycling infrastructure and cell manufacturing capacity cluster in Germany and China, creating geographic chokepoints for material recovery and OEM supply qualification. Battery producers locate near vehicle assembly hubs to meet just-in-sequence delivery requirements. Regulatory divergence across major automotive markets fragments certification standards and complicates platform engineering.
United States
EPA tailpipe standards tighten idle emissions thresholds for light trucks and SUVs, forcing OEMs to expand start-stop deployment across high-margin segments. Domestic producers secure separator manufacturing through backward integration to ensure supply continuity for platform awards. Michigan and Ohio host concentrated battery engineering talent pools serving Detroit-based OEM qualification programs.
Germany
EU F-Gas Regulation mandates 10,000-plus shallow discharge cycles annually, compressing replacement intervals and elevating supplier technical barriers. Stuttgart and Wolfsburg anchor OEM platform integration contracts spanning multi-year model cycles. Enhanced AGM variants dominate specification sheets for entry-level European platforms where cost parity with conventional batteries remains decisive.
China
MIIT fuel consumption regulations pull micro-hybrid penetration upward, scaling lithium-iron-phosphate capacity fastest among global producers. Yangtze River Delta clusters house integrated cell-to-pack operations serving domestic OEM export programs. Shanghai-based engineering centers concentrate deep cycling expertise for 48V mild-hybrid architecture development.
India
Corporate average fuel consumption standards tighten under MIIT-aligned efficiency norms, creating regulatory pull for start-stop adoption in domestic passenger vehicle production. Delhi-NCR and Chennai host aftermarket service networks reporting accelerated wear rates from stop-and-go traffic patterns. Tier-1 suppliers bundle battery hardware with powertrain controls to capture system-level procurement contracts.
Japan
METI industrial policy supports next-generation battery chemistry development including solid-state prototyping for premium cycling applications. Toyota hybrid platforms sustain niche nickel metal hydride demand with established thermal management architectures. Nagoya and Tokyo engineering clusters concentrate electrochemical research talent for automotive duty profile optimization.
Automotive Start-Stop Battery Market Competitive Environment
Integrated system engineers and standalone cell specialists split the market based on OEM bundling preferences versus aftermarket replacement capture. Three strategic archetypes dominate: vertically integrated recyclers extracting value from spent battery streams, technology licensors monetizing separator formulations, and scale manufacturers competing on cost-per-watt-hour. Consolidation pressure intensifies as qualification timelines extend and R&D fixed costs concentrate among survivors.
Among diversified industrial conglomerates, Bosch and Panasonic exemplify system-level positioning that bundles powertrain intelligence with energy storage hardware. Varta occupies a specialist tier focused on premium cycling endurance through proprietary separator engineering. Exide anchors the recycling-integrated archetype, leveraging smelting infrastructure to close material loops and reduce virgin lead dependency.
| Leading Market Players |
|---|
| Exide |
| SK Battery America |
| Bosch |
| Amaron |
| East Penn Manufacturing |
| Varta |
| Panasonic |
| Yuasa |
| Clarios |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese lithium-iron-phosphate cell manufacturing is compressing pricing power across the battery tier structure while forcing European and North American suppliers into defensive cost positions. German OEM qualification timelines create a utilization buffer for incumbent AGM producers, insulating premium pricing tiers from spot-market volatility.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by mandating 10,000-plus shallow discharge cycles annually, stratifying offerings across premium AGM, standard enhanced lead-calcium, and economy flooded lead acid tiers. Price differentiation centers on certification grade under ECE R100 protocols and cold-cranking reliability specifications. Cost compression in the economy tier intensifies because lead price volatility on the London Metal Exchange erodes margin buffers. Fleet operators exhibit highest price sensitivity through unbundled procurement models, while German luxury OEMs demonstrate lowest sensitivity due to platform integration contracts spanning multi-year model cycles.
Supply Chain Analysis
Upstream lead concentrate and lithium carbonate feedstock dependencies anchor the supply chain in China, Germany, and Australia for raw material security. Cell manufacturing draws from separator films produced in Japan and South Korea, with electrolyte formulation concentrated among German chemical specialists. Single-source vulnerability in spent battery smelting capacity creates geographic chokepoints for closed-loop material recovery. Distribution runs through just-in-sequence delivery networks clustered around Stuttgart, Wolfsburg, Detroit, and Shanghai vehicle assembly hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive start-stop battery market is entering a cyclical recovery phase as EPA tailpipe standard tightening forces OEMs to expand start-stop deployment across light truck and SUV segments previously resistant to the technology.
For Market Incumbents: Pre-empt sodium-ion chemistry maturation by securing separator formulation patents for temperature-stable duty profiles before next-generation platform commitments lock in. Backward integration into lead smelting infrastructure in Germany and China closes material loops against virgin price volatility. Capture diagnostic-enabled aftermarket channels through telematics partnerships that shift replacement capture from emergency breakdown toward planned maintenance scheduling. For New Entrants and Emerging Players: Build out sodium-ion prototyping capabilities targeting Indian fleet operators under MIIT-aligned fuel efficiency norms, where price sensitivity and temperature stability requirements create white-space opportunity. India's tightening corporate average fuel consumption standards pull start-stop adoption into domestic passenger vehicle production faster than supplier qualification timelines permit. Pursue system-level procurement bundling with Tier-1 powertrain controls suppliers to bypass standalone cell supplier margin compression. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic-enabled aftermarket service providers with telematics platform integration. Long-term viability over the next decade hinges on chemistry-agnostic battery management system capabilities that port across lead-acid, lithium-ion, and emerging sodium-ion architectures. Target acquisition archetypes include separator technology licensors with ECE R100 certification track records. Monitor solid-state prototyping milestones from Japanese METI-supported research clusters as inflection indicators for next-generation platform specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | 48V mild-hybrid platform awards from German OEMs lock in multi-year cell procurement volumes. |
| Backward Integration | Captive separator manufacturing secures supply continuity against Japanese and Korean film producer bottlenecks. |
| Diagnostic Platform Integration | Telematics-enabled health monitoring shifts aftermarket capture from emergency replacement to planned maintenance. |
| Geographic Manufacturing Footprint | Yangtze River Delta proximity to Shanghai engineering centers accelerates 48V architecture development cycles. |
| Recycling Infrastructure Expansion | Closed-loop lead recovery in Germany and China reduces virgin material cost exposure to London Metal Exchange swings. |
Study Parameters
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement data anchors the qualitative findings in verifiable supply-side commitments. Primary interviews with battery management system architects, aftermarket service network operators, and OEM qualification program managers were combined with secondary validation from EPA tailpipe standard filings, EU F-Gas Regulation implementation guidance, and MIIT fuel consumption regulation updates. Bottom-up cell production capacity estimates and top-down vehicle production forecasts were triangulated to constrain demand-supply balance assumptions.
Calibration against historical replacement cycle data and regional traffic pattern intensity informs the projection framework across the analysis window. Segmentation dimensions modeled include chemistry type, vehicle electrification tier, customer channel structure, and regional regulatory cluster. CAGRs were derived from fitted adoption curves reflecting OEM platform rollout schedules and aftermarket penetration rates. Industry-specific forecast inputs incorporate stop-and-go traffic density indices for megacity corridors and cold-cranking reliability requirements under EPA idle emissions thresholds.
Stress conditions across lead price volatility bands, lithium-ion thermal runaway certification timeline extensions, and sodium-ion chemistry maturation trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and MIIT enforcement continuity. Cross-checking against IHS Markit vehicle registration data and Yangtze River Delta cell production utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
USA Forklift Battery Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
Automotive Starting Battery Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
India Alkaline Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Zinc Ion Batteries Market
Batteries
Submarine Batteries Market
Batteries
Asia Power Tool Batteries Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Wood-Based Batteries Market
Batteries
India Battery Cell Market
Batteries
Non-Rechargeable Battery Market
Batteries
West Europe Battery Market
Batteries
Elastic Battery Binders Market