
 India Electric Vehicle Battery Electrolyte Market | 2026-2036
India Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Battery Electrolyte Market Insights
Project finance tied to government-backed production-linked incentives is reconfiguring competitive entry barriers for domestic electrolyte manufacturers. Gujarat Fluorochemicals leverages its fluorinated chemistry base to anchor captive supply for lithium-ion cell projects in Gujarat. Mitsubishi Chemical Group sustains technology leadership through specialized high-purity electrolyte formulations. Neogen Chemicals competes on backward integration into lithium salts and solvent refining.
India Electric Vehicle Battery Electrolyte refers to the ion-conducting medium—typically comprising lithium hexafluorophosphate dissolved in carbonate solvents such as ethylene carbonate and dimethyl carbonate—that enables lithium-ion transport between cathode and anode during charge and discharge cycles. Its primary purpose is to maintain electrochemical stability across wide temperature ranges while preventing dendrite formation that causes thermal runaway. Liquid electrolyte formulations currently dominate installed capacity due to mature supply chains and compatibility with existing cell assembly infrastructure. Solid-state electrolyte development is attracting disproportionate R&D investment as battery chemistry roadmaps shift toward NMC and NCA cathodes demanding higher thermal tolerance. Polymer gel variants occupy niche positions in two-wheeler applications where form-factor flexibility outweighs energy density priorities.
BIS certification requirements for cell safety and the PLI scheme's domestic value-add mandates are tightening market access for imported electrolyte blends. CDSCO and the country's national chemical regulator enforce purity standards that directly determine which formulations qualify for OEM supply contracts. Stakeholders must monitor how India's evolving FAME subsidy structure and state-level EV policies reshape procurement patterns between captive producers and merchant suppliers.
Market Dynamics
India's PLI scheme for advanced chemistry cell manufacturing is redirecting capital toward domestic electrolyte production, compressing procurement timelines for gigafactory operators in Gujarat and Maharashtra while tightening purity standards enforced by BIS certification.
Growth Catalysts
- FAME subsidy structure:Central government incentives for electric two-wheelers and commercial vehicles are accelerating fleet electrification programs across last-mile logistics operators in Karnataka and Tamil Nadu.
- Domestic value-add mandates:The PLI scheme's localization requirements are compelling cell manufacturers to source electrolyte blends from captive or merchant suppliers within India's tariff jurisdiction.
- High-purity lithium hexafluorophosphate:Advances in salt synthesis and solvent refining capabilities at specialty chemical complexes in Gujarat are reducing import dependency for critical electrolyte precursors.
Market Restraints
- Fluorinated precursor concentration:Domestic manufacturers remain dependent on imported lithium fluoride and phosphorus pentachloride, exposing margins to currency volatility and shipping disruptions.
- CDSCO purity enforcement:The national chemical regulator's evolving safety standards for cell electrolytes create compliance lag for formulations validated under earlier BIS protocols.
- Solid-state substitution timeline:Long-term R&D roadmaps at OEMs and cell producers threaten demand compression for liquid electrolyte capacity commissioned under current PLI windows.
Strategic Opportunities
- Andhra Pradesh-Telangana corridor:Greenfield chemical parks near Visakhapatnam offer untapped feedstock access for electrolyte producers targeting eastern India cell manufacturing clusters.
- Polymer gel formulations:Two-wheeler OEMs seeking form-factor flexibility present niche demand for gel variants that tolerate wider temperature ranges than standard liquid blends.
- DGFT tariff calibration:Anticipated duty adjustments on electrolyte imports could widen margin capture for domestic producers meeting BIS and CDSCO certification thresholds.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell manufacturers and electrolyte blenders compete for limited specialists in ionic conductivity optimization and thermal stability modeling.
- BIS certification timeline compression:Safety validation protocols for new electrolyte formulations require 18-24 month cycles that misalign with gigafactory construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Battery Electrolyte Market |
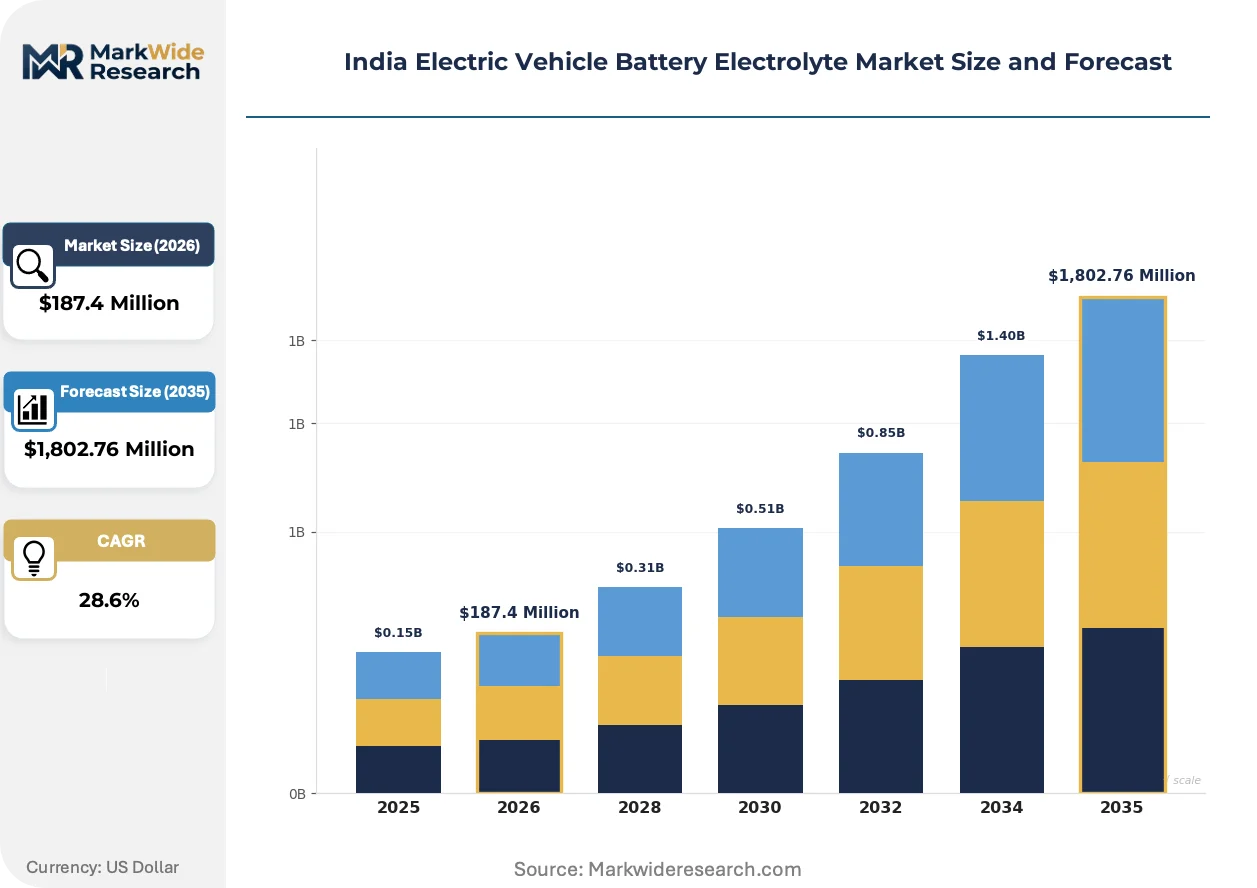
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Electrolyte Type: Liquid, Solid, Gel, Polymer Battery Chemistry: LFP, NMC, NCA, LTO Application Type: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Renewable Energy Storage End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Energy Providers |
| Companies Covered | Neogen Chemicals, Gujarat Fluorochemicals, Mitsubishi Chemical Group, Targray Technology International Inc, Aether Industries Limited, BASF SE, UBE Corporation, Umicore, Sumitomo Chemical Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte formulation roadmaps are pivoting toward higher thermal tolerance as NMC and NCA cathode chemistries penetrate India's electric passenger vehicle segment, compressing R&D cycles for domestic specialty chemical producers.
Artificial intelligence-driven molecular simulation is digitizing electrolyte additive selection for Indian cell manufacturers. Machine learning platforms trained on electrochemical degradation datasets accelerate additive screening that previously required months of wet-lab iteration. Tata Motors and Mahindra Electric's supplier development programs are adopting these tools to compress formulation validation timelines for indigenous cell projects.
India's BIS certification requirements for lithium-ion cell safety are tightening market access for imported electrolyte blends. The standards body mandates flame propagation resistance and overcharge tolerance testing that many offshore suppliers have not completed. Domestic blenders with in-house testing capabilities at Gujarat and Maharashtra facilities are capturing preferential supply positions with OEMs facing FAME subsidy compliance deadlines.
Fleet operators in Delhi-Mumbai industrial corridor logistics are consolidating electrolyte procurement through direct contracts with cell gigafactories rather than merchant chemical distributors. Large last-mile delivery platforms negotiate volume commitments that bypass traditional channel markups. This concentration is most visible in Maharashtra, where Swiggy and Zomato electrification programs drive consolidated purchasing power toward Reliance and Ola Electric cell supply chains.
India Electric Vehicle Battery Electrolyte Market Segmentation
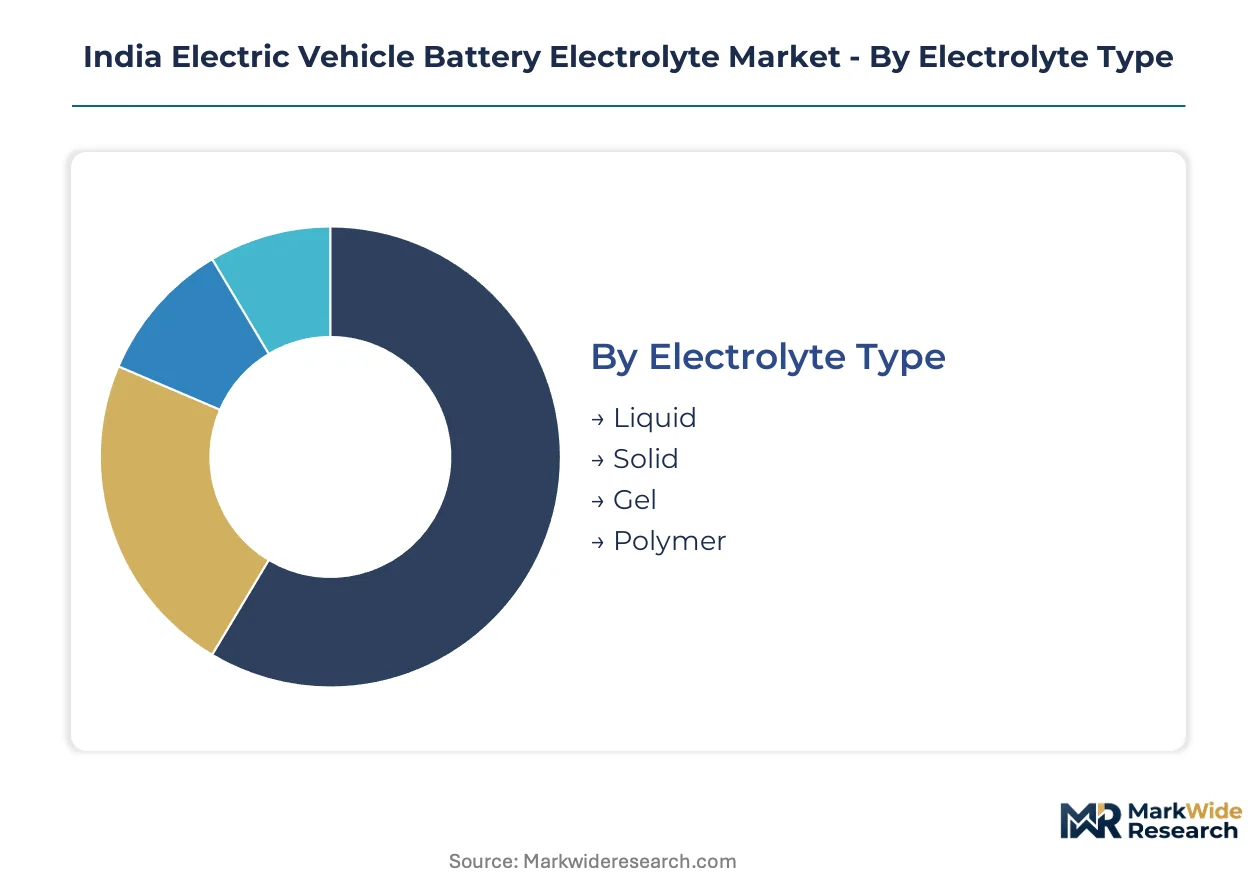
Electrolyte formulation choices in India trace directly to cathode chemistry roadmaps and thermal management requirements across vehicle categories. Segmentation reveals how PLI-linked gigafactory investments are concentrating procurement patterns around specific electrolyte types and battery chemistries.
Electrolyte Type:
The use-case spectrum spans thermal tolerance demands, with liquid formulations serving mass-market two-wheelers and solid-state variants targeting premium passenger vehicles.
- Liquid:Lithium hexafluorophosphate dissolved in ethylene carbonate and dimethyl carbonate delivers mature ionic conductivity for existing cell assembly lines. Demand concentrates across Maharashtra and Gujarat gigafactories supplying last-mile logistics fleets under FAME subsidy windows.
- Solid:Ceramic and sulfide-based ionic conductors eliminate flammability risks for NMC and NCA cathode packs. Pilot production lines in Karnataka and Tamil Nadu are validating these formulations for electric passenger vehicles targeting BIS safety certification.
- Gel:Polymer matrices immobilize liquid electrolyte for flexible form factors in two-wheeler battery packs.
- Polymer:Solid polymer electrolytes with polyethylene oxide backbones occupy niche positions where manufacturing simplicity outweighs conductivity limitations.
The dominant share belongs to Liquid, while Solid is closing the gap fastest.
Battery Chemistry:
Cost tier segmentation separates iron-phosphate dominance in commercial fleets from nickel-rich cathodes penetrating premium passenger segments.
- LFP:Lithium iron phosphate cathodes pair with standard liquid electrolytes for thermal stability in commercial vehicle and energy storage applications. Procurement concentrates with Tata Motors and Mahindra Electric commercial programs targeting state-level electrification mandates.
- NMC:Nickel-manganese-cobalt layered oxides demand high-purity electrolyte additives for voltage stability above 4.3V. Cell manufacturers in the Delhi-Mumbai corridor are qualifying these formulations for electric SUVs under tightening CDSCO safety protocols.
- NCA:Nickel-cobalt-aluminum cathodes require specialized electrolyte formulations with fluorinated additives for cycle life extension.
- LTO:Lithium titanate anode systems tolerate wider temperature ranges with modified electrolyte salt concentrations.
LFP maintains volume leadership due to commercial fleet penetration, though NMC is expanding most quickly through passenger vehicle OEM supplier development programs.
Application Type:
Customer type segmentation distinguishes fleet procurement consolidation from fragmented aftermarket patterns.
- Passenger Vehicles:Electric SUVs and sedans require electrolyte formulations with extended temperature windows for cabin climate compatibility. Demand clusters around NMC and NCA cell production lines in Gujarat and Maharashtra serving Mahindra Electric and Tata Motors vehicle platforms.
- Commercial Vehicles:Buses and light trucks prioritize cycle life and safety certification over energy density. Swiggy and Zomato last-mile electrification programs in Karnataka drive consolidated procurement toward LFP-compatible electrolyte blends.
- Two-Wheelers:Electric scooters and motorcycles dominate unit volumes with cost-optimized liquid electrolyte specifications.
- Renewable Energy Storage:Grid-scale battery installations require electrolyte formulations with decade-scale calendar life validation.
Commercial Vehicles command the largest electrolyte volume commitments, while Passenger Vehicles is gaining share fastest through premium OEM platform launches.
End User:
Supply concentration patterns separate captive electrolyte production at integrated cell manufacturers from merchant supplier relationships.
- OEMs:Tata Motors, Mahindra Electric, and Ola Electric operate supplier development programs specifying electrolyte purity thresholds directly. These stakeholders negotiate volume commitments that bypass traditional chemical distribution channels.
- Tier-1 Suppliers:Cell manufacturers like Reliance and Exide source electrolyte blends under PLI scheme domestic value-add mandates.
- Aftermarket Providers:Independent battery replacement channels source certified electrolyte formulations for warranty-compliant repairs.
- Energy Providers:Renewable energy developers procure electrolyte-validated cells through engineering-procurement-construction contractors.
Tier-1 Suppliers absorb the dominant procurement share, while OEMs are consolidating supply chain control fastest through backward integration into captive electrolyte blending facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electrolyte trade balance tilts toward import dependency for high-purity lithium salts while domestic blending capacity expands along coastal chemical corridors. The PLI scheme is compressing procurement timelines for cell manufacturers seeking localized supply chains.
Maharashtra
Swiggy and Zomato electrification programs drive consolidated electrolyte procurement toward Reliance and Ola Electric cell supply chains. FAME subsidy compliance deadlines pressure fleet operators to secure BIS-certified formulations from Gujarat-based blenders. Mumbai-Pune industrial corridor hosts the densest concentration of last-mile logistics electrification, with gigafactory operators qualifying liquid electrolyte specifications for commercial vehicle battery packs.
Gujarat
Specialty chemical complexes in Dahej and Mundra advance lithium hexafluorophosphate synthesis capabilities, reducing import dependency for critical precursors. DGFT tariff structures on electrolyte imports favor domestic producers meeting CDSCO purity thresholds. The state anchors captive supply arrangements between fluorinated chemistry producers and emerging cell manufacturing clusters.
Karnataka
Electric two-wheeler OEMs in Bengaluru specify polymer gel formulations for form-factor flexibility in scooter battery packs. State-level EV policies complement central FAME incentives, accelerating fleet operator procurement consolidation. Tamil Nadu-bordering industrial zones pilot solid-state electrolyte validation for NMC cathode systems targeting premium passenger vehicle segments.
Tamil Nadu
Cell manufacturing investments near Chennai qualify high-purity electrolyte additives for voltage stability above 4.3V in nickel-manganese-cobalt configurations. CDSCO safety protocol alignment lags behind BIS certification timelines, creating compliance windows for domestic blenders with in-house testing infrastructure. The state hosts pilot production lines validating ceramic-based ionic conductors for thermal runaway prevention.
Telangana
Greenfield chemical parks near Hyderabad offer untapped feedstock access for electrolyte producers targeting eastern India cell manufacturing clusters. Andhra Pradesh-bordering logistics corridors present procurement consolidation opportunities for renewable energy storage developers. State industrial policy frameworks support backward integration into lithium salt refining through specialty chemical joint ventures.
India Electric Vehicle Battery Electrolyte Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying high-purity formulations to captive cell manufacturing operations. The market structure fragments across three tiers: integrated chemical conglomerates with fluorinated chemistry bases, merchant electrolyte blenders with BIS certification capabilities, and technology licensors importing specialized formulations. Competitive positioning hinges on backward integration into lithium salt production and CDSCO compliance speed rather than scale alone. Capacity expansion and strategic partnerships dominate competitive moves as PLI-linked gigafactory construction accelerates procurement timelines.
Among domestic specialty chemical producers, Gujarat Fluorochemicals exemplifies the integrated archetype leveraging fluorinated precursor capabilities for captive electrolyte supply. Neogen Chemicals occupies the merchant blender tier with backward integration into lithium salt and solvent refining. Mitsubishi Chemical Group represents the technology licensor position, sustaining formulation leadership through high-purity electrolyte specialization. These three anchors illustrate how competitive advantage separates along the integration spectrum from raw material control through certification velocity.
| Leading Market Players |
|---|
| Neogen Chemicals |
| Gujarat Fluorochemicals |
| Mitsubishi Chemical Group |
| Targray Technology International Inc |
| Aether Industries Limited |
| BASF SE |
| UBE Corporation |
| Umicore |
| Sumitomo Chemical Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gujarat's fluorinated chemical complexes is compressing supplier margins while amplifying pricing leverage for cell manufacturers negotiating long-term offtake agreements. This utilization dynamic feeds directly into procurement posture across the Delhi-Mumbai industrial corridor.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for electrolyte blends, with three-tier pricing structure across premium, standard, and economy levels differentiating by CDSCO certification grade and volume scale. Price differentiation stems from BIS validation timelines and captive versus merchant supply sourcing. Cost compression in standard-grade liquid formulations is intensifying because of import parity pressure from Chinese electrolyte exporters. Fleet operators in last-mile logistics exhibit highest price sensitivity, while passenger vehicle OEMs prioritize certification velocity over unit cost.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculus for lithium hexafluorophosphate precursors. Domestic blending capacity concentrates in Gujarat, Maharashtra, and Tamil Nadu, drawing from imported lithium fluoride, phosphorus pentachloride, and carbonate solvents. Single-source vulnerability rests on Chinese lithium salt refining dominance. Distribution runs through direct contracts between cell gigafactories and captive or merchant electrolyte producers, bypassing traditional chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
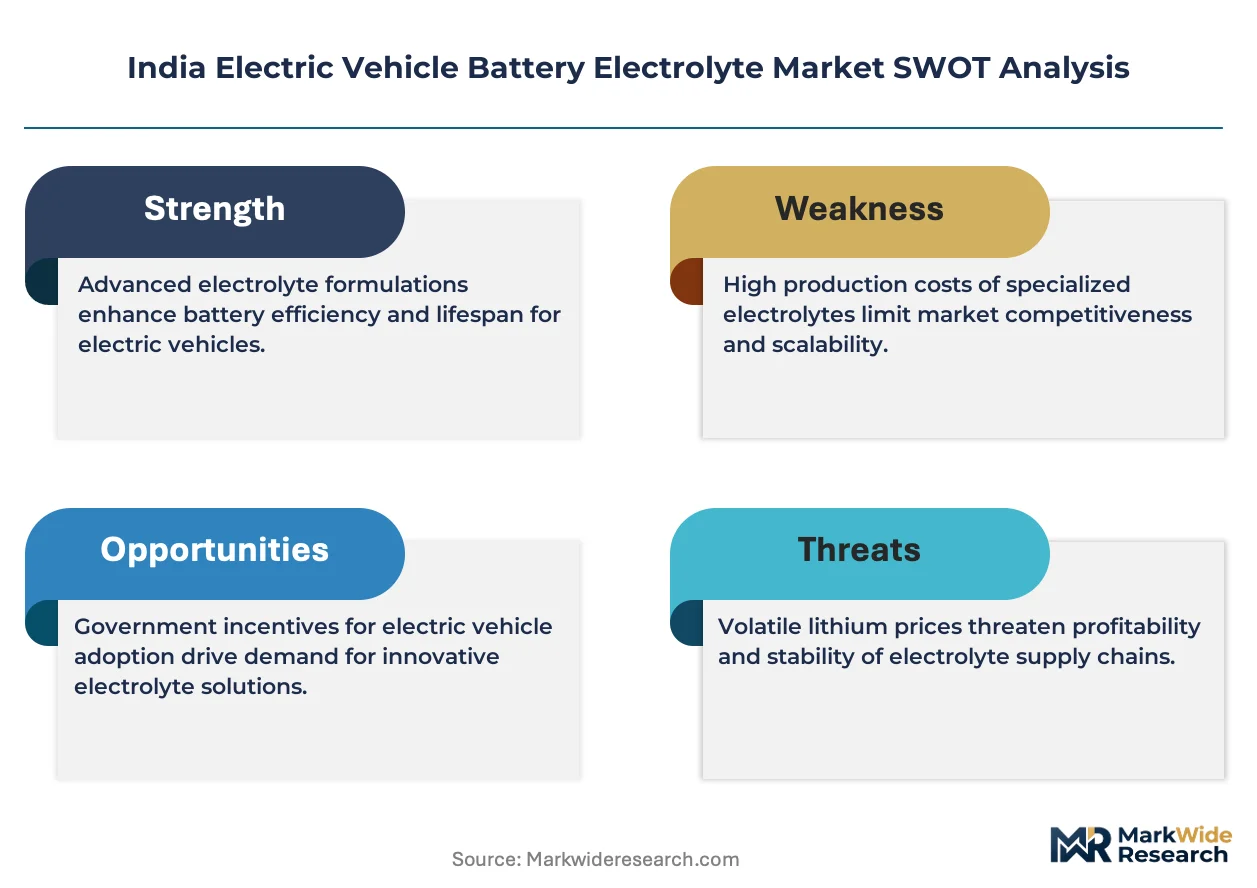
The India electrolyte market rewards players who control electrochemical engineering talent pools and BIS certification velocity. The scarcity of ionic conductivity optimization specialists creates asymmetric returns for firms with in-house formulation capabilities.
For Market Incumbents: Insulate formulation leadership by accelerating CDSCO compliance investments ahead of evolving safety protocols. Deepen backward integration into lithium salt refining at Dahej chemical complexes to reduce import dependency exposure. Solid-state substitution timelines threaten liquid electrolyte capacity returns; diversify R&D allocation toward polymer gel variants for two-wheeler applications. For New Entrants and Emerging Players: Establish a beachhead in Andhra Pradesh-Telangana corridor greenfield chemical parks, where feedstock access remains untapped by incumbent Gujarat producers. Target renewable energy storage developers seeking decade-scale calendar life validation as the most penetrable end-use segment. Pursue joint venture structures with specialty chemical partners to shortcut BIS certification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among merchant electrolyte blenders with multi-year offtake contracts to PLI-linked gigafactories. Long-term viability hinges on CDSCO certification speed rather than scale alone across the analysis window. Acquisition targets should demonstrate in-house electrochemical testing infrastructure. Watch for DGFT tariff recalibration on electrolyte imports as the inflection signal for domestic margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Refining | Gujarat Fluorochemicals anchors captive supply for Reliance and Ola Electric cell projects. |
| BIS Certification Investment | Domestic blenders with in-house testing capture preferential OEM supply positions under FAME deadlines. |
| Polymer Gel Formulation Development | Bengaluru-based two-wheeler OEMs specify gel variants for scooter battery form-factor flexibility. |
| Greenfield Chemical Park Joint Venture | Visakhapatnam feedstock access opens eastern India cell manufacturing clusters to new entrants. |
| Long-term Supply Agreement with Fleet Operators | Swiggy and Zomato electrification programs consolidate procurement toward certified domestic blenders. |
Research Methodology
A spread of perspectives from cell manufacturing procurement leads, specialty chemical plant managers, BIS certification officers, and fleet operator logistics directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, PLI scheme disbursement filings, and CDSCO safety protocol documentation. Bottom-up electrolyte volume estimates from gigafactory capacity announcements triangulated against top-down cathode chemistry deployment projections across the modeling period.
Demand-supply-balance framing anchored the forecast framework, with segmentation dimensions spanning electrolyte type, battery chemistry, application category, and end-user concentration. CAGRs derived from capacity commissioning timelines, FAME subsidy windows, and PLI localization mandates. Industry-specific inputs included BIS certification cycle durations and lithium hexafluorophosphate import dependency ratios.
Sensitivities concentrate around solid-state substitution acceleration, DGFT tariff recalibration timing, and CDSCO purity standard evolution. Forecasts reflect documented assumptions on cathode chemistry roadmaps and gigafactory construction schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Li-Ion Pouch Battery Market
Batteries
Redox Flow Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
High Temperature NiMH Battery Market
Batteries
Battery Cases Market
Batteries
UAV Battery Pack Market
Batteries
Battery Separators Market
Batteries
United States Household Battery Market
Batteries
Alkaline Secondary Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Nickel Cadmium Battery Market
Batteries
Secondary Battery Market
Batteries
Stretchable Battery Market
Batteries
AAA Battery Market
Batteries
Iron Flow Battery Market