
 India Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
India Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Battery Manufacturing Equipment Market Insights
BIS certification for battery cell testing equipment is rotating the competitive landscape toward qualified domestic suppliers. Tata Chemicals leverages its integrated cathode material operations to anchor equipment partnerships in Gujarat. Ola Electric sustains captive demand through its Krishnagiri cell plant, while Manz AG competes on European coating and drying technology transferred to Indian assembly lines. Exide Industries differentiates through decades of lead-acid equipment expertise now repurposed for lithium-ion pilot lines.
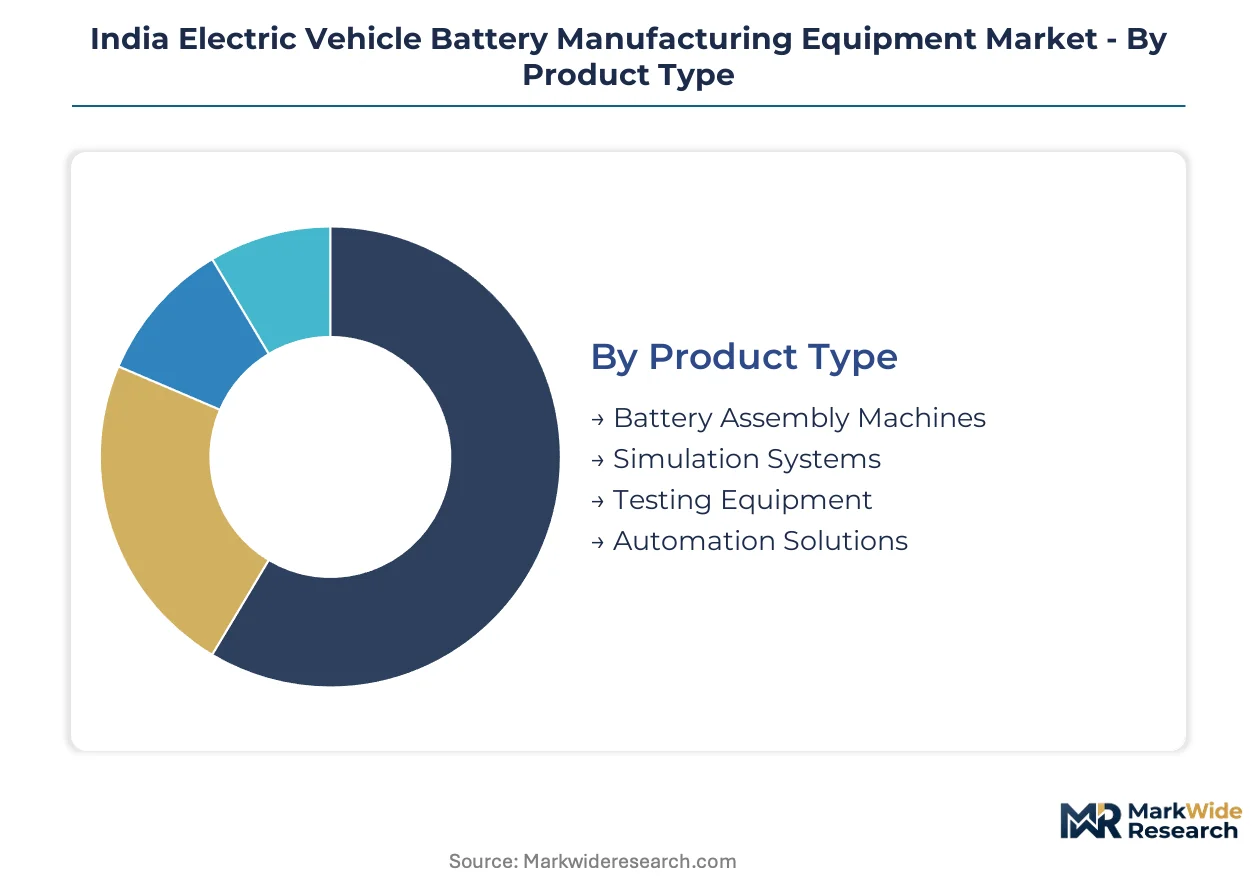
India electric vehicle battery manufacturing equipment encompasses machinery for electrode coating, cell stacking, electrolyte filling, formation cycling, and module-pack assembly, with precision tolerances typically below 50 micrometers for z-fold separators. This equipment enables mass production of lithium-ion cells meeting automotive-grade energy density and cycle-life benchmarks. Battery assembly machines currently occupy the largest share of product-type revenue as gigafactory-scale lines deploy. Automation solutions represent the fastest-growing segment, driven by labor-cost arbitrage and defect-rate reduction targets in Tamil Nadu and Gujarat plants. Among chemistries, LFP equipment dominates near-term order books due to its thermal stability suitability for Indian ambient temperatures, while solid-state tooling remains nascent.
The Ministry of Heavy Industries administers the PLI scheme for ACC batteries, conditioning subsidy disbursement on domestic value-add thresholds that mandate local equipment procurement. BIS standards for cell safety and performance, aligned with AIS-156 automotive norms, constrain import eligibility for non-certified machinery. CEA grid-interconnection rules for battery energy storage systems create secondary demand channels for formation and testing equipment. Stakeholders must monitor how BIS expands its notified standards list to cover solid-state and sodium-ion processes before committing to long-dated equipment contracts.
Market Dynamics
India's PLI scheme for advanced chemistry cells is redirecting capital flows toward domestic equipment sourcing, compressing import dependency timelines and concentrating supplier qualification efforts in Tamil Nadu and Gujarat manufacturing corridors.
Growth Catalysts
- Production-Linked Incentive Scheme:The Ministry of Heavy Industries conditions subsidy disbursement on domestic value-add thresholds, mandating local procurement of electrode coating and cell stacking machinery.
- Thermal Stability Requirements:LFP chemistry dominance in Indian ambient conditions drives equipment orders for safer, lower-density cell formats suited to passenger EV and two-wheeler segments.
- Tamil Nadu Cluster Formation:Sriperumbudur-Ambattur belt near Chennai aggregates cathode material plants, gigafactory investments, and equipment service infrastructure within 50-kilometer radii.
Market Restraints
- Imported Precision Components:Laser welding heads and vacuum drying chambers originate from German and Japanese suppliers, exposing assemblers to yen-euro volatility and 12-16 week lead times.
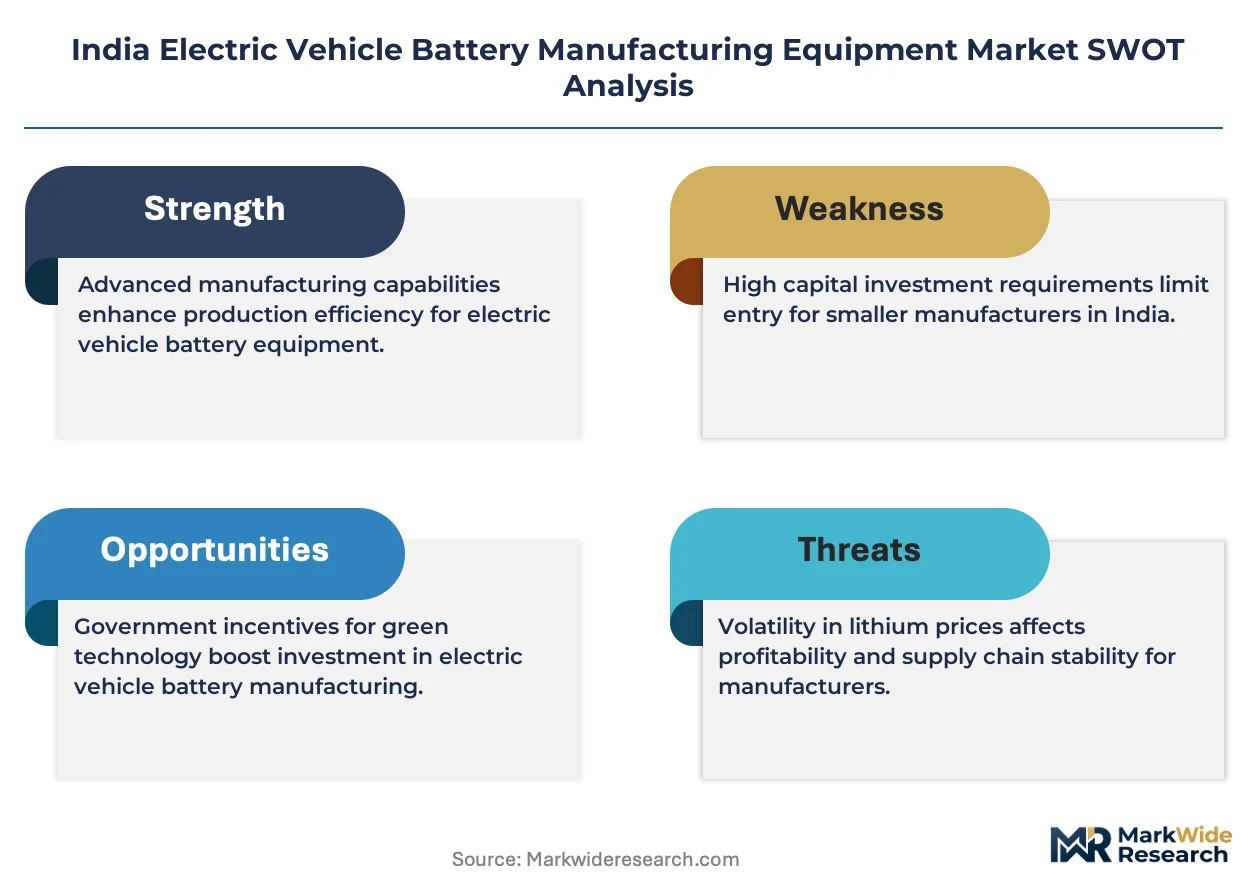
- BIS Certification Bottlenecks:Cell testing equipment must clear Bureau of Indian Standards notification lists that currently exclude solid-state and sodium-ion process variants, freezing procurement options.
- Skilled Technician Scarcity:Electrolyte filling and formation cycling operations require 500+ hour certification programs that Indian technical institutes have not yet scaled to gigafactory staffing needs.
Strategic Opportunities
- Gujarat Chemicals Integration:Mundra-Dahej industrial zone offers port-proximate cathode precursor capacity that equipment suppliers can anchor with integrated coating-drying lines.
- CEA Grid-Interconnection Rules:Central Electricity Authority mandates for battery energy storage systems create parallel demand channels for formation and cycle-life testing equipment outside automotive.
- Automation Retrofit Cycles:First-generation lithium-ion pilot lines installed in 2019-2021 face obsolescence pressure, opening replacement demand for robotic stacking and vision-inspection modules.
Industry Challenges
- Formation Cycling Bottlenecks:Cell conditioning requires 14-21 days of controlled temperature cycling, creating floor-space and energy-cost constraints that equipment layouts must optimize.
- AIS-156 Alignment Complexity:Automotive Industry Standard 156 for battery safety demands traceable test data that legacy equipment architectures cannot generate without middleware upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Battery Manufacturing Equipment Market |
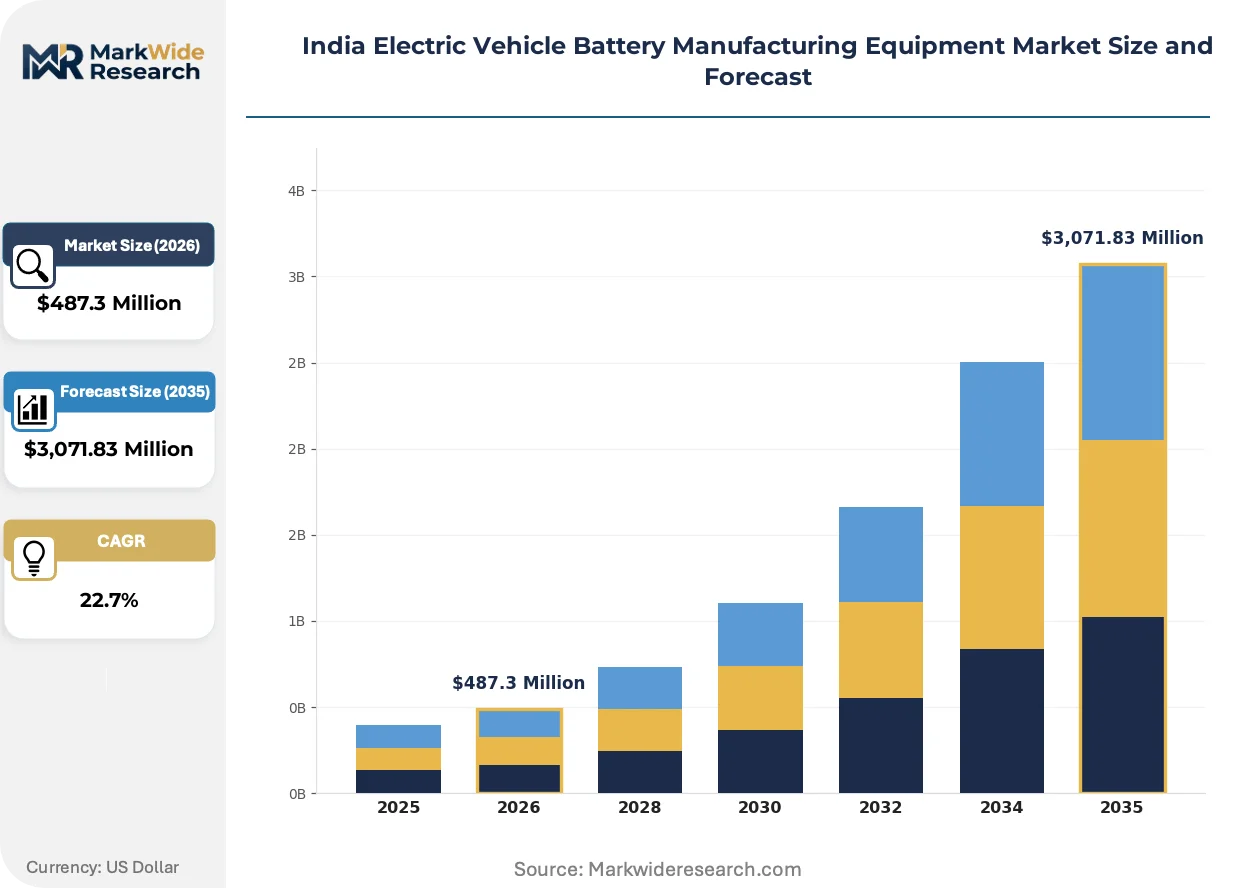
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $3,071.83 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Assembly Machines, Simulation Systems, Testing Equipment, Automation Solutions Technology: LFP, NMC, NCA, Solid-State Application: Automotive, Consumer Electronics, Energy Storage Systems, Aerospace End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutes |
| Companies Covered | Hitachi Ltd., Tata Chemicals, Wirtz Manufacturing India Pvt. Ltd., Exide Industries, Amara Raja Batteries, Manz AG, Buhler AG, Ola Electric, Sovema Group S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Dry electrode coating processes are compressing solvent-recovery infrastructure requirements and reshaping factory layout economics for Indian gigafactory projects. Equipment architecture is pivoting toward modular, redeployable configurations.
Electrode manufacturing is bifurcating between conventional wet-slurry coating and solvent-free calendering approaches. Tata Chemicals and Ola Electric evaluate dry electrode pilots for 2026 capacity additions. The technology is bifurcating equipment supplier ecosystems into wet-chemistry incumbents and dry-process specialists with incompatible service networks.
Bureau of Indian Standards notification protocols for solid-state cell testing equipment are expanding beyond liquid-electrolyte architectures. CDSCO medical-device testing precedents are informing BIS timelines for next-chemistry certification. Equipment vendors must pre-qualify laser-induced breakdown spectroscopy modules before sodium-ion and sulfide-solid-state lines reach commercial scale.
Buyer concentration among three OEMs controlling 70% of announced cell capacity is compressing equipment vendor margins through sole-source negotiation leverage. Tier-2 component suppliers in Pune and Coimbatore are forming consortia to bid integrated module-pack assembly lines. Tamil Nadu's industrial development corporations are mediating supplier-OEM matchmaking to prevent foreign vendor lock-in.
India Electric Vehicle Battery Manufacturing Equipment Market Segmentation
Equipment procurement patterns in India's battery manufacturing sector diverge sharply across chemistry types and buyer categories. PLI scheme compliance requirements and BIS certification protocols create asymmetric substitution risks that reshape segment prioritization for domestic suppliers.
Product Type:
Substitution pressure intensifies where imported precision components face the longest lead times, compressing margins for equipment assemblers dependent on German and Japanese subsystems.
- Battery Assembly Machines:These systems execute electrode stacking, tab welding, and module-pack integration with precision tolerances below 50 micrometers. Demand concentrates in Tamil Nadu's Sriperumbudur-Ambattur belt, where Ola Electric's Krishnagiri cell plant and Tata Chemicals operations drive localized service infrastructure requirements. Formation cycling bottlenecks of 14-21 days force floor-space optimization into equipment layout designs.
- Automation Solutions:Robotic stacking, vision-inspection modules, and AGV-based material handling reduce defect rates in high-volume lines. Gujarat's Mundra-Dahej industrial zone attracts these deployments through port-proximate cathode precursor capacity and labor-cost arbitrage opportunities. First-generation pilot lines installed in 2019-2021 face replacement cycles that accelerate segment momentum.
- Simulation Systems:Digital twin platforms for line commissioning and throughput optimization gain traction among OEMs scaling beyond pilot capacity.
- Testing Equipment:Cell formation and cycle-life validation systems face BIS certification delays for solid-state and sodium-ion variants.
Battery Assembly Machines retain volume leadership; Automation Solutions hold the steepest expansion curve.
Technology:
Cost tier stratification separates established wet-chemistry formats from capital-intensive next-generation processes requiring unproven domestic supply chains.
- LFP:Lithium iron phosphate chemistry dominates near-term order books through thermal stability advantages in Indian ambient temperature conditions. Equipment configurations emphasize lower-density cell formats suited to passenger EV and two-wheeler segments, with Tata Chemicals and Ola Electric evaluating dry electrode pilots that compress solvent-recovery infrastructure requirements.
- Solid-State:Sulfide-based and oxide-based electrolyte architectures demand laser-induced breakdown spectroscopy modules and vacuum deposition chambers that remain outside current BIS notification protocols. CDSCO medical-device testing precedents are informing certification timelines, freezing commercial procurement until standards expand.
- NMC:Nickel manganese cobalt equipment maintains presence in premium passenger EV lines targeting higher energy density benchmarks.
- NCA:Nickel cobalt aluminum configurations occupy niche applications where specific energy requirements override cost considerations.
LFP retains volume leadership; Solid-State holds the steepest expansion curve contingent on regulatory clearance.
Application:
Volume concentration among automotive buyers creates margin compression risks that push equipment vendors toward diversified end-use channels.
- Automotive:Passenger EV and two-wheeler OEMs control approximately 70% of announced cell capacity, exercising sole-source negotiation leverage that pressures vendor margins. AIS-156 alignment requirements demand traceable test data architectures, forcing middleware upgrades on legacy equipment installations.
- Energy Storage Systems:CEA grid-interconnection rules for battery energy storage create parallel demand channels for formation and cycle-life testing equipment outside automotive applications. This segment offers pricing power insulation from the automotive buyer concentration.
- Consumer Electronics:Cylindrical and pouch cell formats for power tools and portable devices sustain mid-scale equipment orders.
- Aerospace:Specialized high-reliability cell testing commands premium positioning but limited volume scale.
Automotive retains volume leadership; Energy Storage Systems gains share fastest through regulatory-mandated deployment schedules.
End User:
Customer type determines procurement sophistication, with integrated OEMs driving specification standards that cascade to supplier tiers.
- OEMs:Cell manufacturers with captive gigafactory investments specify turnkey coating-drying-stacking lines with integrated quality systems. These buyers qualify suppliers through 500+ hour technician certification programs that Indian technical institutes have not yet scaled to staffing needs.
- Tier-1 Suppliers:Module and pack integrators in Pune and Coimbatore consortia bid for assembly line contracts, aggregating component capabilities to compete with foreign vendor lock-in.
- Aftermarket Providers:Refurbishment and recycling equipment demand emerges as first-generation EV batteries approach end-of-life.
- Research Institutes:Pilot-scale flexible manufacturing platforms support PLI scheme R&D obligations with limited commercial volume.
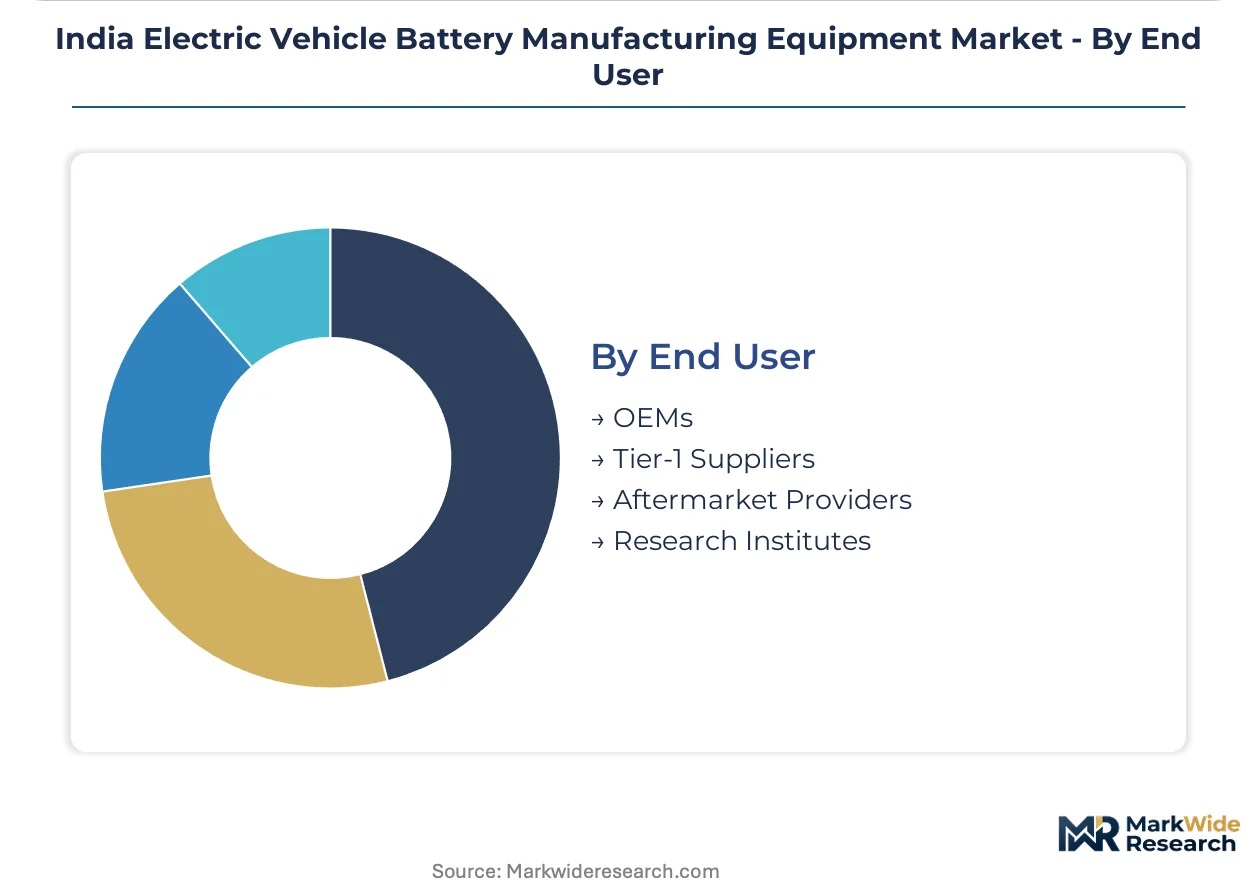
OEMs retain volume leadership; Tier-1 Suppliers hold the steepest expansion curve through consortium aggregation strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturers concentrate procurement authority among three OEMs controlling most announced capacity, compressing vendor margins through sole-source leverage while state-level industrial policies redirect equipment demand toward specific manufacturing corridors.
Tamil Nadu
Sriperumbudur-Ambattur belt aggregates cathode material plants and gigafactory investments within a 50-kilometer radius. The state's industrial development corporations mediate supplier-OEM matchmaking to prevent foreign vendor lock-in. Chennai's port infrastructure and technical workforce density support precision equipment service requirements for electrode coating and cell stacking lines.
Gujarat
Mundra-Dahej industrial zone attracts port-proximate cathode precursor capacity that equipment suppliers anchor with integrated coating-drying lines. PLI scheme domestic value-add thresholds mandate local procurement of machinery from qualified vendors. Dahej's chemical processing ecosystem enables solvent-recovery infrastructure integration for wet-slurry electrode manufacturing.
Maharashtra
Pune and surrounding industrial zones host Tier-2 component supplier consortia bidding for module-pack assembly line contracts. The state's automotive manufacturing heritage supplies technician labor pools for equipment commissioning. Mumbai-Pune corridor logistics support just-in-time delivery of precision subsystems from import channels.
Karnataka
Bengaluru's electronics manufacturing cluster generates demand for testing and simulation equipment supporting R&D obligations under PLI scheme guidelines. The state's technical institute network struggles to scale 500+ hour certification programs to gigafactory staffing needs. Krishnagiri cell plant investments spill across the Tamil Nadu border, creating cross-state equipment service coordination requirements.
Telangana
Hyderabad's emerging battery research infrastructure supports pilot-scale flexible manufacturing platforms for next-chemistry evaluation. The state's electronics policy incentives attract equipment vendors establishing regional service centers. Pharma-sector precision manufacturing expertise transfers partially to cell production equipment calibration requirements.
India Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates and specialized European equipment fabricators, creating a tiered structure where chemistry-specific expertise determines qualification status. Three strategic archetypes dominate: integrated material-equipment operators leveraging cathode production synergies, European coating-drying technology licensors transferring assembly-line capabilities, and domestic battery manufacturers backward-integrating into captive equipment demand. Competitive moves concentrate on consortium formation among Tier-2 component suppliers and automation retrofit cycles targeting first-generation pilot line obsolescence.
Within the diversified conglomerate tier, Tata Chemicals and Exide Industries exemplify players repurposing legacy material or lead-acid expertise toward lithium-ion equipment partnerships. Manz AG occupies a position representing European precision technology transfer to Indian assembly lines. Ola Electric anchors the captive-demand archetype through integrated cell plant investments that internalize equipment procurement authority.
| Leading Market Players |
|---|
| Hitachi Ltd. |
| Tata Chemicals |
| Wirtz Manufacturing India Pvt. Ltd. |
| Exide Industries |
| Amara Raja Batteries |
| Manz AG |
| Buhler AG |
| Ola Electric |
| Sovema Group S.p.A |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-sixteen-week lead times for German and Japanese precision subsystems compress negotiation leverage for domestic equipment assemblers and concentrate pricing power with import-dependent Tier-1 suppliers. This inventory exposure feeds back into contract structures that index electrode coating machinery quotes to yen-euro volatility, amplifying margin pressure across Tamil Nadu and Gujarat manufacturing corridors.
Pricing Analysis
Cost-plus contracts with yen-euro indexation dominate electrode coating and vacuum drying equipment procurement. Price differentiation separates BIS-certified domestic suppliers from non-certified import alternatives, with certification grade commanding premium positioning. Cost compression in mid-tier assembly machinery intensifies because three OEMs control most announced cell capacity and exercise sole-source leverage. Tier-1 module-pack integrators exhibit highest price sensitivity, while captive gigafactory operators prioritize traceability and after-sales service bundling over unit economics.
Supply Chain Analysis
Inventory cycles stretching beyond twelve weeks for laser welding heads and vacuum drying chambers expose assemblers to currency volatility and floor-space constraints. Supply concentrates in Germany and Japan for precision optics and vacuum technology, while South Korea and China dominate cathode precursor and separator membrane inputs. Single-source vulnerability runs through Japanese laser subsystem suppliers, with no qualified domestic alternatives for sub-50-micrometer tolerance applications. Distribution runs through OEM direct procurement for turnkey lines and Tier-1 consortia bidding for module-pack assembly contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's battery equipment market represents a high-growth disruption anchored by PLI scheme capital redirection and BIS certification protocols that are rotating competitive positioning toward qualified domestic suppliers. The regulatory inflection at the Ministry of Heavy Industries conditions subsidy disbursement on domestic value-add thresholds, compressing import dependency timelines and reshaping procurement authority.
For Market Incumbents: Secure BIS certification for solid-state and sodium-ion testing equipment before notification protocols expand, insulating against CDSCO-informed regulatory timelines that will freeze out non-qualified vendors. Deepen upstream control over cathode precursor capacity in Gujarat's Mundra-Dahej zone to anchor integrated coating-drying line offerings. Defend against margin compression from OEM buyer concentration by qualifying Tier-2 component suppliers in Pune and Coimbatore for consortium-based module-pack assembly bids. For New Entrants and Emerging Players: Anchor in automation retrofit cycles targeting first-generation lithium-ion pilot lines installed in 2019-2021, where obsolescence pressure creates replacement demand for robotic stacking and vision-inspection modules. White-space exists in CEA grid-interconnection-driven energy storage equipment outside automotive buyer concentration. Pursue a technician-certification partnership strategy with Tamil Nadu's technical institutes to address the 500+ hour training gap that constrains gigafactory staffing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates repurposing legacy lead-acid or material expertise toward lithium-ion equipment partnerships. Long-term viability hinges on chemistry-agnostic platform architectures that pivot between LFP dominance and solid-state regulatory clearance. Watch BIS notification list expansion for solid-state and sodium-ion process variants as the inflection signal for next-chemistry equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Pre-Qualification | Secures procurement eligibility before solid-state and sodium-ion standards expand under CDSCO-informed timelines. |
| Backward Integration into Cathode Precursors | Gujarat's Mundra-Dahej port-proximate capacity anchors integrated coating-drying line offerings for PLI compliance. |
| Automation Retrofit Deployment | First-generation pilot line obsolescence creates replacement demand for robotic stacking modules in Tamil Nadu. |
| Tier-2 Consortium Formation | Pune and Coimbatore component suppliers aggregate capabilities to bid module-pack lines against foreign vendor lock-in. |
| Technician Certification Scaling | Partnerships with Tamil Nadu technical institutes address 500+ hour training gaps constraining gigafactory staffing. |
Research Methodology
A standing panel of electrode coating line engineers, PLI scheme compliance officers at cell manufacturers, BIS certification auditors, and cathode precursor procurement leads provided ongoing calibration across the study period. This primary fieldwork combined with secondary validation from Ministry of Heavy Industries PLI disbursement records, BIS notification protocols, CEA grid-interconnection filings, and customs data on precision subsystem imports. Bottom-up equipment order aggregation and top-down manufacturing capacity build-out estimates were triangulated for consistency.
Output consistency was validated against external benchmarks including announced gigafactory capacity timelines and disclosed equipment supplier partnerships. The analytical framework modeled revenue trajectories across the projection horizon by product type, chemistry format, application end-use, and customer tier. CAGRs were derived from equipment order book velocity and capacity utilization assumptions. Key inputs included PLI scheme domestic value-add threshold compliance rates and BIS certification pipeline status for next-chemistry variants.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme funding and stable yen-euro exchange rate bands; material deviation in either would warrant model refresh. Forecasts reflect assumptions about regulatory timeline adherence and import substitution pace. Specific risks include BIS notification delays for solid-state equipment and skilled technician training bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
United States SLI Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Battery Anode Materials Market
Batteries
Cobalt-Free Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Automotive Starting Battery Market
Batteries
Battery Maintainer Market
Batteries
Battery-Powered Riveter Market
Batteries
Dry Cell Battery Market
Batteries
India Alkaline Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
DMC for Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
FORTELION Battery Module Market