
 Wood-Based Batteries Market | 2026-2036
Wood-Based Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Wood-Based Batteries Market Analytics
The divergence between premium lignin-purified anode feedstock and commodity wood-flour filler grades is realigning procurement strategies across the cell supply chain. Northvolt leverages its Swedish forestry partnerships to secure captive lignin streams for pilot-scale sodium-ion production. Stora Enso anchors European feedstock supply through its integrated biorefinery operations in Finland. VTT Technical Research Centre of Finland dominates laboratory-to-pilot translation, sustaining Finland's position in early-stage wood-battery commercialization.
Wood-based batteries employ processed lignin or cellulose derivatives as active anode materials or structural electrolyte scaffolds, typically achieving capacities between 300-400 mAh/g in lignin-hard carbon configurations for sodium-ion systems; their primary purpose is to displace mined graphite and synthetic polymers with renewable, low-carbon forest biomass. Biopolymer batteries and hybrid batteries lead early commercial traction where end-users prioritize lifecycle carbon intensity over energy density benchmarks. Sodium-ion technology occupies the fastest-expanding segment, as its chemistry tolerates the higher ash content inherent to biomass-derived carbons better than lithium-ion equivalents.
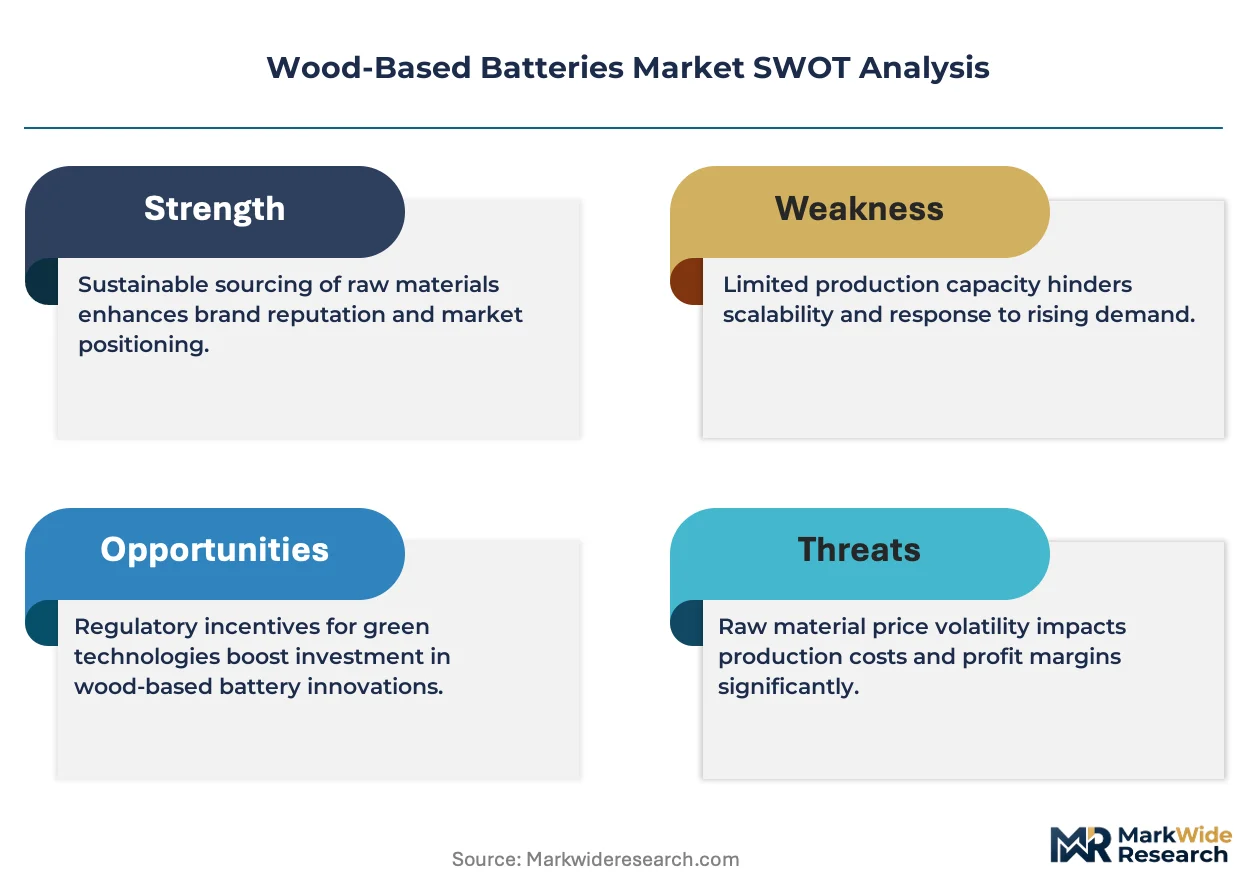
EU Battery Regulation carbon-footprint disclosure rules and REACH substance compliance are reshaping material qualification timelines for European producers, while Japan's METI green innovation fund directs public R&D investment toward certified sustainable battery supply chains. The US EPA bio-preferred program and emerging IRA domestic content provisions create parallel compliance pathways for North American entrants. Stakeholders must monitor which certification framework achieves cross-recognition first, as this will determine regional production location decisions and feedstock sourcing strategies.
Market Dynamics
The shift from graphite anodes to lignin-hard carbon architectures is restructuring procurement relationships between Nordic forestry operators and European cell manufacturers. This chemistry transition compresses qualification timelines while amplifying feedstock traceability requirements.
Growth Catalysts
- EU Battery Regulation carbon-footprint disclosure:Mandatory lifecycle reporting accelerates biomass-derived anode qualification against synthetic alternatives. Producers achieving sub-threshold carbon intensity gain preferred supplier status.
- Sodium-ion chemistry tolerance:Biomass-derived carbons with higher ash content perform adequately in sodium-ion systems where lithium-ion specifications would reject them. This technical fit expands addressable feedstock pools.
- Nordic forestry cluster proximity:Integrated pulp-to-battery pilot lines in Sweden and Finland minimize lignin degradation during transport. Shortest feedstock-to-cell distances reduce moisture reabsorption losses.
Market Restraints
- Graphite price volatility:Synthetic graphite anode cost fluctuations from Chinese electrode-grade supply create pricing uncertainty that delays lignin-hard carbon contract finalization.
- Purification yield limitations:Kraft lignin demethylation and washing steps achieve variable carbon yields, constraining unit economics at commercial scale.
- REACH substance compliance friction:Novel biomass carbon registration requirements extend material qualification timelines by twelve to eighteen months versus established anode chemistries.
Strategic Opportunities
- Japan METI green innovation fund:Certified sustainable battery supply chain investments subsidize pilot lignin anode production for domestic sodium-ion manufacturers.
- US IRA domestic content provisions:Biomass feedstock sourcing from American forestry operations qualifies cell production for tax credit stacking.
- Hybrid battery architecture penetration:Wood-derived structural electrolyte scaffolds paired with conventional cathodes create intermediate product categories between full biopolymer and conventional cells.
Industry Challenges
- Electrochemical characterization skill scarcity:Lignin-hard carbon performance validation requires expertise spanning organic chemistry and battery testing protocols that few laboratories combine.
- Cell formation protocol adaptation:Solid-electrolyte-interphase stabilization on biomass-derived carbons demands modified cycling procedures incompatible with existing graphite-optimized equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood-Based Batteries Market |
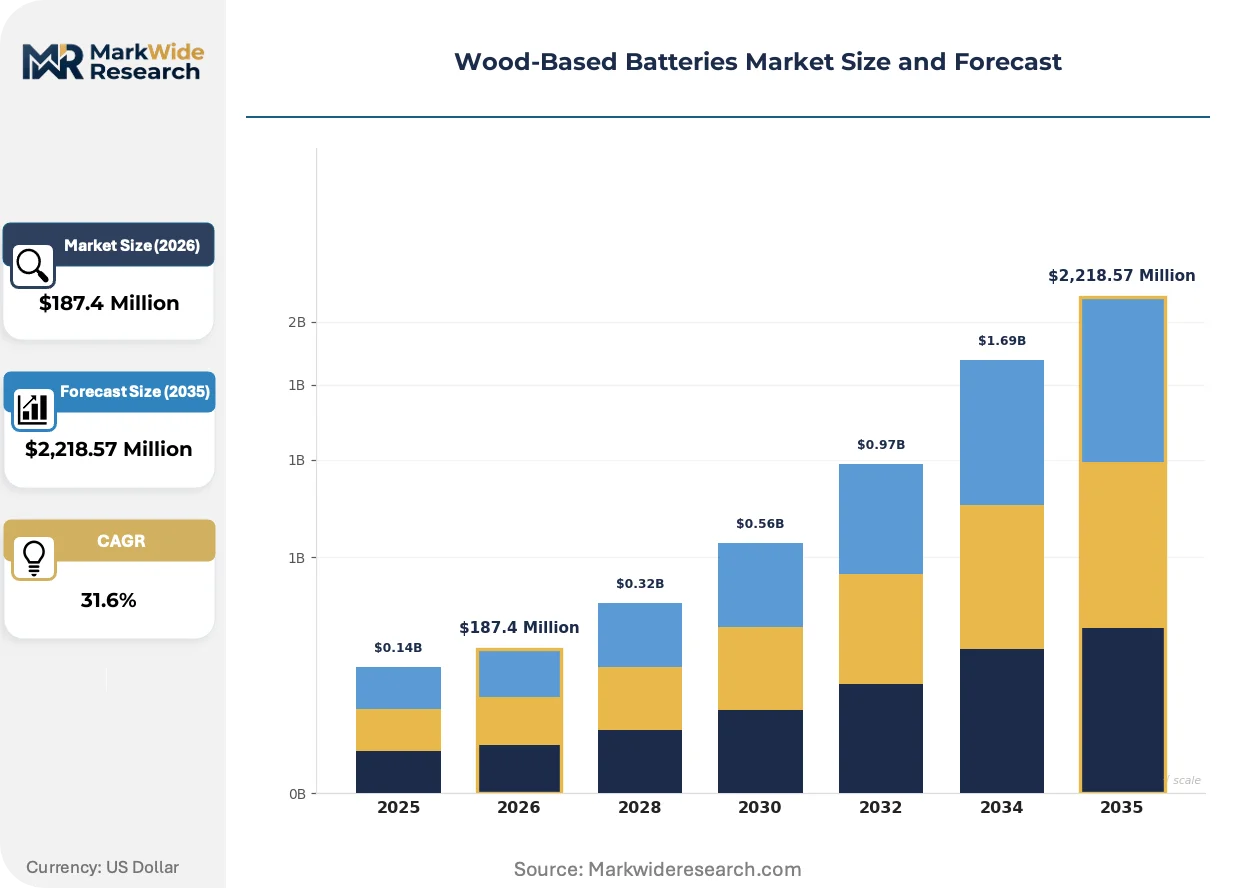
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminated Batteries, Plywood Batteries, Biopolymer Batteries, Hybrid Batteries Technology: Sodium-Ion, Lithium-Ion, Vanadium Flow, Organic Electrochemical End User: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Grid Applications Application: Energy Storage Systems, Portable Electronics, Automotive Power Sources, Industrial Backup |
| Companies Covered | Northvolt, Stora Enso, VTT Technical Research Centre of Finland, Uppsala University, Fraunhofer Institute, Northvolt AB, Volkswagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood-Based Batteries Market Evolving Landscape
Active material and structural component convergence is collapsing traditional boundaries between anode production and cell assembly. This integration pressure favors operators controlling both forestry feedstock and electrode coating capabilities.
Lignin-derived hard carbon is unifying anode active material and binder functions previously served by separate graphite and PVDF components. Electric vehicle manufacturers in Germany and France are qualifying these unified electrodes for sodium-ion modules targeting urban delivery fleets. The structural simplification is compressing electrode stack assembly steps and reducing synthetic polymer procurement volumes.
EU Battery Regulation sustainability mandates are forcing disclosure of upstream mining intensity for conventional anode materials. Cell producers serving European automotive OEMs must now document forest biomass chain-of-custody to demonstrate carbon advantage. Nordic integrated operators with FSC-certified forestry holdings capture preferential offtake negotiations against non-certified Asian graphite suppliers.
Buyer specifications now prioritize certified lifecycle carbon intensity over energy density benchmarks in stationary storage procurement. Utility-scale developers in California and Texas are inserting biomass-derived anode requirements into request-for-proposal technical criteria. This certification-driven preference shift disadvantages conventional graphite anodes lacking supply chain transparency documentation.
Wood-Based Batteries Market Segmentation
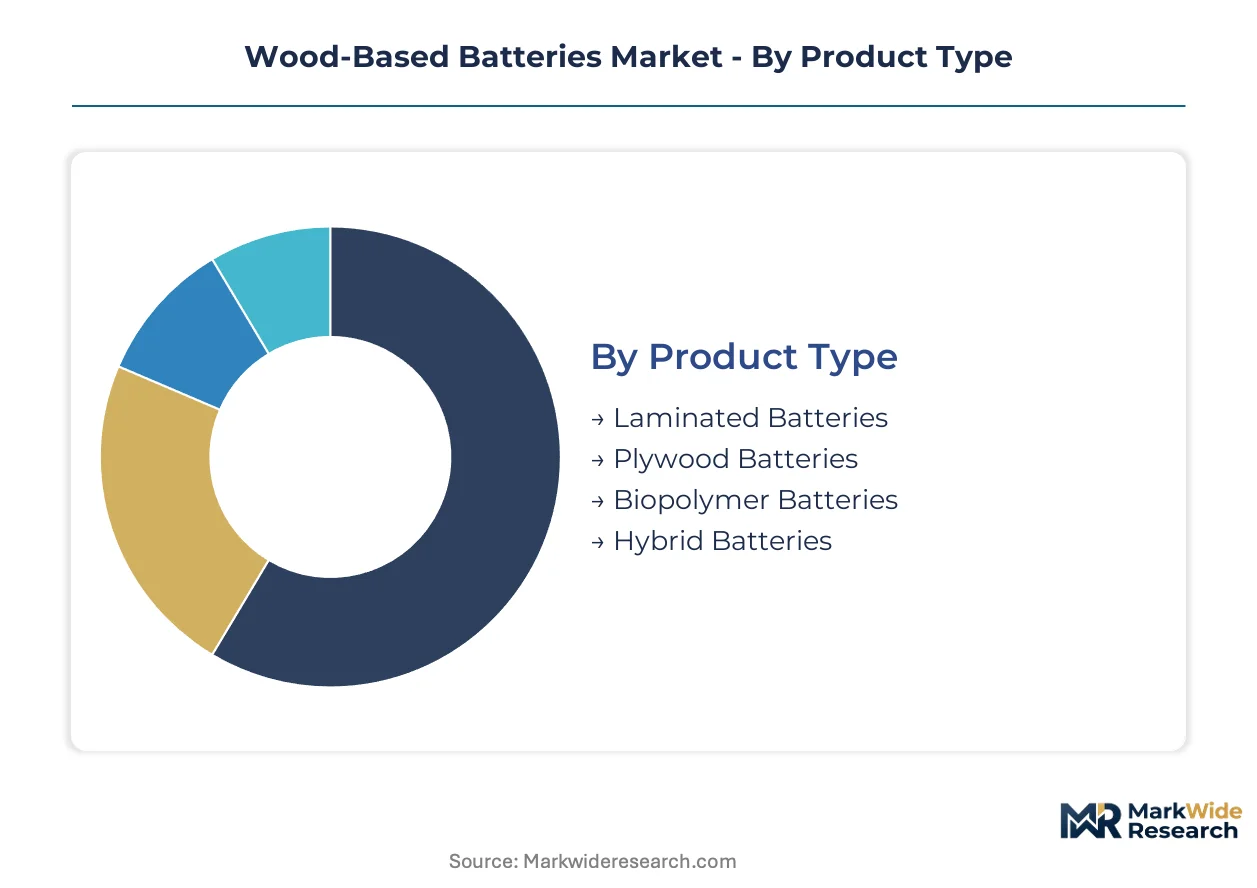
Wood-based battery architectures demand precise segment alignment between feedstock chemistry and end-use performance thresholds. Procurement decisions hinge on matching lignin-derived carbon specifications to sodium-ion tolerance levels versus lithium-ion purity requirements.
Product Type:
Customization intensity spans from rigid laminated structures to fully moldable biopolymer systems, with standardization highest in commodity plywood formats.
- Biopolymer Batteries:Fully biodegradable cell housings and electrodes employ lignin binders replacing synthetic PVDF. Electric vehicle manufacturers in Germany prioritize these for sodium-ion modules where end-of-life compostability offsets lower energy density.
- Hybrid Batteries:Wood-derived structural electrolyte scaffolds integrate with conventional cathode chemistries. Renewable energy storage developers in California specify hybrid architectures to satisfy lifecycle carbon intensity procurement criteria.
- Laminated Batteries:Layered cellulose separators achieve mechanical stability through cross-laminated fiber orientation.
- Plywood Batteries:Compressed wood fiber substrates serve as low-cost structural anode supports for stationary applications.
Leading the category by volume: Hybrid Batteries. Growing fastest: Biopolymer Batteries.
Technology:
Cost tier separation is pronounced, with sodium-ion occupying the mid-market position between premium lithium-ion and nascent organic electrochemical systems.
- Sodium-Ion:Tolerates higher ash content in biomass-derived hard carbons than lithium-ion equivalents. Nordic forestry clusters in Sweden and Finland anchor pilot production for this chemistry given favorable feedstock-to-cell proximity.
- Lithium-Ion:Demands ultra-purified lignin precursors with sub-ppm metallic contamination. Japanese METI green innovation fund recipients focus here for consumer electronics applications requiring energy density benchmarks.
- Vanadium Flow:Wood-derived carbon felt electrodes serve as low-cost redox reaction substrates.
- Organic Electrochemical:Quinone-functionalized lignin derivatives enable aqueous electrolyte compatibility.
Volume concentration: Sodium-Ion. Steepest expansion trajectory: Organic Electrochemical.
End User:
Application maturity diverges sharply, with renewable energy storage procurement ahead of automotive qualification timelines.
- Renewable Energy Storage:Utility-scale developers prioritize certified lifecycle carbon intensity over energy density. Texas and California grid operators insert biomass-derived anode requirements into request-for-proposal technical criteria.
- Electric Vehicles:Urban delivery fleet operators qualify sodium-ion modules with lignin-hard carbon anodes for last-mile logistics. EU Battery Regulation carbon-footprint disclosure mandates accelerate supplier qualification against graphite alternatives.
- Consumer Electronics:Portable device manufacturers evaluate wood-based structural components for housing applications.
- Grid Applications:Frequency regulation services tolerate lower energy density in exchange for rapid cycling stability.
Dominant demand source: Renewable Energy Storage. Fastest commercialization pace: Electric Vehicles.
Application:
Supply concentration favors energy storage systems where volume procurement justifies dedicated lignin purification investments.
- Energy Storage Systems:Stationary battery installations specify FSC-certified biomass chain-of-custody to demonstrate carbon advantage over graphite. Nordic integrated operators with certified forestry holdings capture preferential offtake negotiations.
- Automotive Power Sources:Sodium-ion cell formation protocols require modified cycling procedures for biomass-derived carbons. German OEMs lead qualification efforts for urban delivery modules.
- Portable Electronics:Low-power devices adopt wood-flour filler grades for structural battery housings.
- Industrial Backup:Uninterruptible power supply systems prioritize cost stability over energy density optimization.
Procurement volume leader: Energy Storage Systems. Fastest contract finalization: Automotive Power Sources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skellefteå anchors the world's most advanced wood-battery manufacturing corridor, where Northvolt's integrated lignin processing facility achieves shortest feedstock-to-cell distances from surrounding Swedish forestry holdings.
Sweden
Urban delivery fleet operators in Stockholm and Gothenburg qualify sodium-ion modules with lignin-hard carbon anodes for last-mile logistics contracts. The Swedish Environmental Protection Agency enforces carbon-footprint disclosure rules that accelerate biomass-derived anode procurement against graphite alternatives. Skellefteå's integrated pulp-to-battery pilot lines minimize lignin degradation during transport through direct pipeline connections to adjacent forestry operations.
Finland
Renewable energy storage developers prioritize certified lifecycle carbon intensity over energy density benchmarks in procurement decisions. Finnish Safety and Chemicals Agency REACH compliance protocols reshape material qualification timelines for domestic producers. VTT Technical Research Centre of Finland dominates laboratory-to-pilot translation in Espoo, sustaining the country's position in early-stage wood-battery commercialization through partnerships with Kotka biorefinery clusters.
Germany
German automotive OEMs lead qualification efforts for urban delivery modules incorporating lignin-hard carbon architectures. Federal Ministry for Economic Affairs and Climate Action green innovation funding subsidizes pilot lignin anode production for domestic sodium-ion manufacturers. Stuttgart and Munich engineering corridors concentrate electrochemical characterization expertise spanning organic chemistry and battery testing protocols.
Japan
Consumer electronics manufacturers evaluate ultra-purified lignin precursors with sub-ppm metallic contamination for portable device applications. METI green innovation fund directs public R&D investment toward certified sustainable battery supply chains. Osaka and Nagoya industrial zones host precision carbon purification facilities serving lithium-ion specifications demanding higher purity grades than sodium-ion equivalents tolerate.
United States
Utility-scale developers in California and Texas insert biomass-derived anode requirements into request-for-proposal technical criteria for grid-scale storage. EPA bio-preferred program and emerging IRA domestic content provisions create compliance pathways for North American entrants. Pacific Northwest forestry operations in Oregon and Washington qualify cell production for tax credit stacking through captive biomass feedstock sourcing.
Wood-Based Batteries Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the wood-based battery value chain, with integrated forestry-to-cell operators commanding feedstock security premiums over specialist electrode coaters. The structure concentrates around Nordic pulp-and-paper incumbents repurposing existing biorefinery infrastructure, European automotive-linked cell manufacturers securing captive lignin streams, and research institutes bridging laboratory-to-pilot translation. Three archetypes dominate: upstream forestry operators with captive carbonization capacity, midstream electrode specialists coating lignin-hard carbon slurries, and downstream cell assemblers qualifying biomass-derived anodes for sodium-ion modules. Competitive moves center on strategic partnerships binding forestry feedstock to cell production and geographic expansion establishing regional lignin purification hubs.
Within the integrated forestry operator archetype, Stora Enso anchors European feedstock supply through Finnish biorefinery operations. Among research institute players, VTT Technical Research Centre of Finland occupies a central position in early-stage commercialization. At the cell manufacturer tier, Northvolt exemplifies the automotive-linked producer securing captive lignin streams through Swedish forestry partnerships.
| Leading Market Players |
|---|
| Northvolt |
| Stora Enso |
| VTT Technical Research Centre of Finland |
| Uppsala University |
| Fraunhofer Institute |
| Northvolt AB |
| Volkswagen |
| Others |
Value Network & Pricing Analysis
Lignin-hard carbon anode chemistry transitions simultaneously compress unit economics and concentrate feedstock procurement power among Nordic integrated operators with captive forestry holdings. This dual effect rewards producers achieving shortest feedstock-to-cell distances while penalizing distant electrode coaters facing moisture reabsorption losses and transport degradation.
Pricing Analysis
Certified lifecycle carbon intensity anchors value-based pricing for biomass-derived anodes serving EU Battery Regulation compliance mandates. Three-tier pricing structure across FSC-certified premium, standard traceability, and economy wood-flour filler grades separates automotive OEM procurement from stationary storage buyers. Cost compression in commodity filler grades intensifies because graphite spot price volatility delays long-term lignin-hard carbon contract finalization. Renewable energy storage developers exhibit highest price sensitivity, prioritizing carbon disclosure documentation over energy density premiums.
Supply Chain Analysis
Dual-sourcing requirements from German and French automotive OEMs mandate multi-supplier qualification across Swedish, Finnish, and Japanese lignin purification operations. Kraft lignin feedstock draws from Nordic pulp-and-paper biorefineries, Japanese METI-subsidized precision carbon facilities, and emerging Pacific Northwest forestry clusters. Single-source vulnerability concentrates in electrode coating capacity controlled by integrated forestry-to-cell operators. Distribution runs through direct pipeline connections from biorefinery to pilot production facilities, bypassing conventional anode material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Purification yield limitations at commercial Kraft lignin demethylation scale prop pricing premiums, constraining supply expansion faster than sodium-ion demand materializes.
For Market Incumbents: Cement feedstock security through backward integration into FSC-certified forestry holdings before graphite price stabilization erodes carbon-based pricing premiums. Lock in multi-year offtake agreements with German automotive OEMs facing EU Battery Regulation disclosure deadlines. Prioritize electrode coating capacity expansion in Skellefteå and Kotka clusters to defend against emerging Pacific Northwest entrants qualifying for IRA domestic content provisions. For New Entrants and Emerging Players: Utility-scale developers in Texas and California represent an underserved buyer archetype prioritizing certified lifecycle carbon intensity over energy density benchmarks. Penetrate this segment through FSC chain-of-custody documentation and direct RFP response capabilities bypassing incumbent distributor relationships. Target hybrid battery architecture procurement where wood-derived structural electrolyte scaffolds face lower qualification barriers than full biopolymer systems. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated forestry-to-cell operators with captive lignin streams and existing biorefinery infrastructure repurposing. Five-to-ten year viability hinges on sodium-ion chemistry achieving cost parity with lithium-ion in urban delivery fleet applications. Monitor Japan METI green innovation fund recipient selection announcements as inflection indicator for certified sustainable battery supply chain investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Holdings | FSC-certified captive lignin streams secure preferred supplier status under EU Battery Regulation carbon disclosure mandates. |
| Multi-Supplier Qualification Programs | German OEM dual-sourcing requirements accelerate Nordic-Japanese electrode coating partnerships. |
| Pilot-Scale Sodium-Ion Production | Urban delivery fleet operators in Stockholm validate lignin-hard carbon formation protocols for last-mile logistics contracts. |
| REACH Compliance Pre-Registration | Finnish Safety and Chemicals Agency protocols compress twelve-to-eighteen month novel biomass carbon qualification timelines. |
| Hybrid Battery Architecture Development | California utility-scale developers specify wood-derived structural electrolyte scaffolds for lifecycle carbon intensity procurement criteria. |
Research Methodology
Independent corroboration across primary interviews with lignin purification plant managers, sodium-ion cell development engineers, and utility procurement officers underwrites the qualitative findings. Secondary validation draws from EU Battery Regulation implementation guidance, METI green innovation fund recipient disclosures, and Nordic pulp-and-paper industry production statistics. Bottom-up feedstock-to-cell cost modeling triangulates against top-down addressable market sizing for sodium-ion chemistry tolerance segments.
Rate-of-change decomposition across the analysis window isolates lignin-hard carbon yield improvements, EU regulatory compliance cost trajectories, and sodium-ion manufacturing scale effects. Segmentation dimensions span product type, technology chemistry, end-use application, and regional feedstock cluster proximity. CAGRs derive from installed base projections for stationary storage and urban delivery fleet electrification, cross-referenced against lignin purification capacity expansion announcements.
Revisions become necessary when graphite price volatility stabilizes below lignin-hard carbon production cost floors, or when REACH substance compliance timelines extend beyond current eighteen-month baselines. Deviation in sodium-ion chemistry adoption rates among German automotive OEMs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Europe Rechargeable Battery Market
Batteries
Portable Battery Powered Products Market
Batteries
Aluminum Based Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
48 Volt Battery System Market
Batteries
Military Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Residential Battery Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Flow Battery Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
South Europe Battery Market