
 Industrial Battery Charger Market | 2026-2036
Industrial Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Battery Charger Market Analysis
The EU Green Deal is realigning the cost-of-entry calculus for charger suppliers targeting European industrial fleets. ABB leverages its electrification portfolio to anchor grid-integrated charging infrastructure across manufacturing hubs. GS Yuasa competes through deep specialization in lead-acid systems for legacy forklift fleets. Delta extends its power-electronics expertise into high-frequency charger architectures for lithium-ion batteries.
An industrial battery charger converts alternating current to regulated direct current for replenishing motive and stationary battery banks, typically operating across voltage ranges from 24 V to 96 V with efficiency thresholds exceeding 90 percent in modern switched-mode designs. These systems serve as critical infrastructure for electric material-handling equipment, backup power installations, and off-grid industrial operations. Fast charging technology leads deployment in warehousing environments where multi-shift operations demand minimal equipment downtime. Smart charging segments are expanding fastest as fleet operators adopt telematics-linked systems that optimize charge cycles and predict maintenance intervals. Traditional charging retains volume share in construction and smaller manufacturing facilities where capital constraints limit technology upgrades.
OSHA mandates govern electrical safety in US industrial charger installations, while the EPA enforces energy-efficiency standards that shape product design requirements for domestic suppliers. CE marking under the EU Machinery Directive governs European market access, with ECHA REACH compliance adding material-disclosure obligations for imported units. Stakeholders must monitor evolving interoperability standards between charger communication protocols and battery management systems as fleet electrification scales.
Market Dynamics
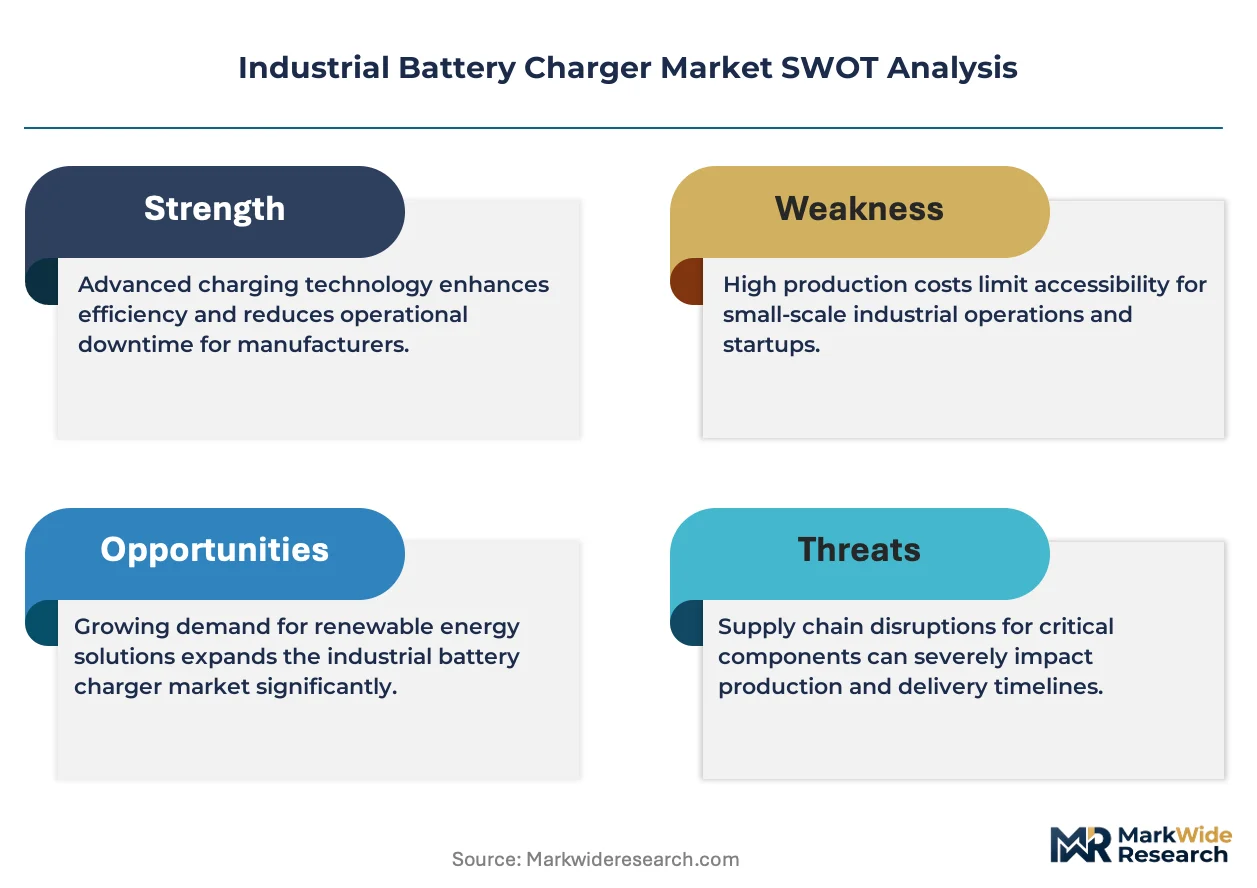
The lithium-ion transition in material-handling fleets is compressing charger replacement cycles and forcing suppliers to recalibrate power-electronics architectures for higher voltage tolerances and faster charge rates.
Growth Catalysts
- Warehouse automation scaling:E-commerce fulfillment centers in the United States and Germany are tripling charger density per square meter as autonomous mobile robot fleets expand.
- EU F-Gas Regulation:Energy-efficiency mandates are accelerating phase-out of transformer-based charger designs across European industrial parks.
- Opportunity charging protocols:Lithium-titanate battery chemistry enables 10-minute partial recharges, rewriting shift scheduling for multi-cycle operations.
Market Restraints
- Copper and silicon carbide cost volatility:Power semiconductor substrate prices fluctuate with electric vehicle demand, squeezing margin on high-frequency charger production.
- Chinese component concentration:Magnetics and thermal management subassemblies rely heavily on Shenzhen and Dongguan manufacturing clusters.
- Lead-acid infrastructure lock-in:Legacy forklift fleets with sunk capital in flooded battery systems delay charger upgrade decisions.
Strategic Opportunities
- India manufacturing electrification:PLI scheme incentives for industrial automation are creating first-mover charger deployment in Pune and Chennai automotive hubs.
- Grid-integrated bi-directional charging:Vehicle-to-facility power flow enables peak shaving for manufacturing plants with high demand charges.
- Telematics-linked predictive maintenance:Charger communication protocols converging with battery management systems enable subscription-based service models.
Industry Challenges
- Power electronics engineering scarcity:Switched-mode design expertise concentrates in automotive and renewable energy sectors, competing for industrial charger talent.
- Multi-protocol certification timelines:UL, CE, and GB standard harmonization delays product launch windows by 8-14 months.
- Legacy fleet integration complexity:Retrofitting smart chargers into 20-year-old warehouse electrical infrastructure requires site-specific engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Battery Charger Market |
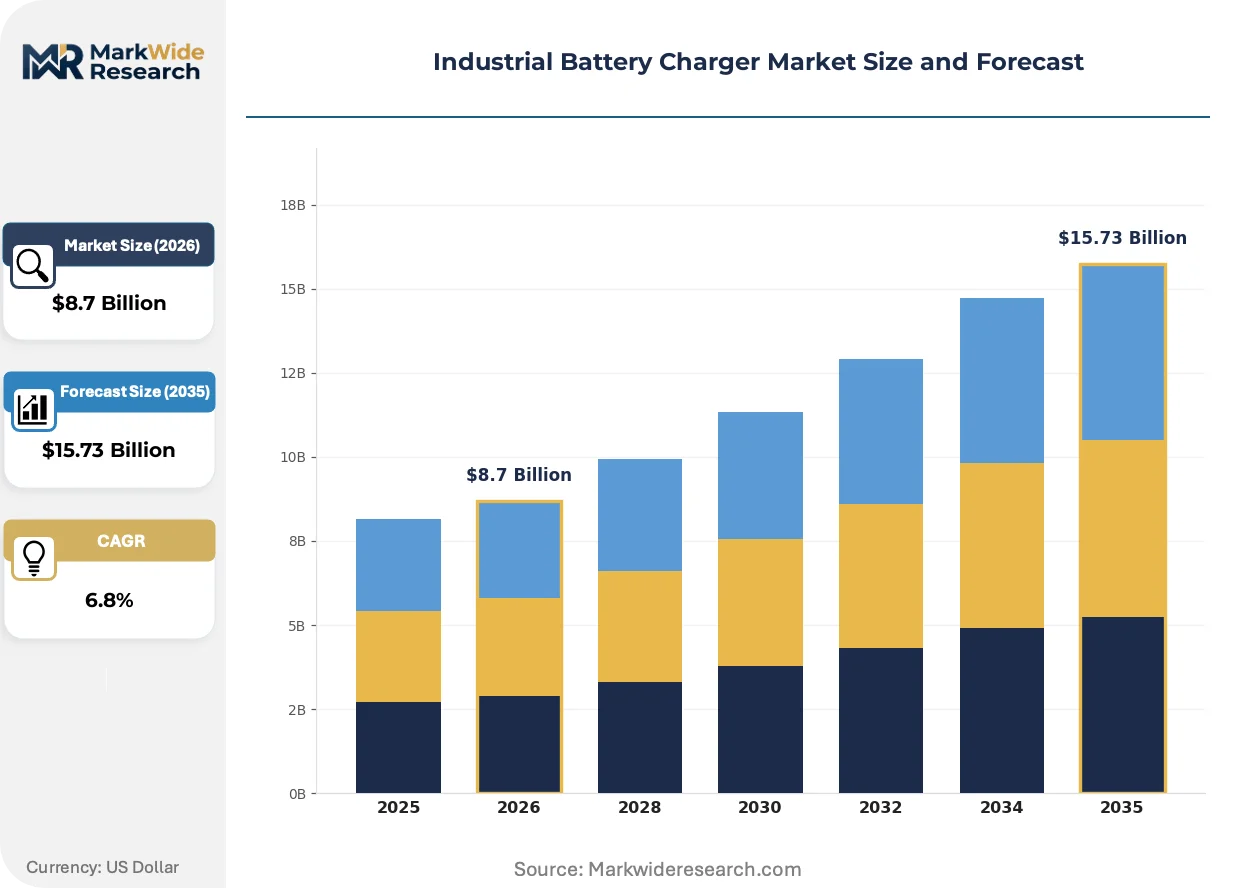
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Gel Technology: Fast Charging, Solar Charging, Smart Charging, Traditional Charging End User: Manufacturing, Warehousing, Transportation, Construction Installation: On-Site, Off-Site, Permanent, Portable |
| Companies Covered | Crown Battery, Micropower, Delta, GS Yuasa, Pro Charging Systems, ABB, Hitachi, Lester Electrical, Exide Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Battery Charger Market Emerging Trajectories
Silicon carbide power semiconductors and wireless inductive architectures are converging to eliminate conductive wear points. Fleet operators now prioritize charger-battery telematics interoperability over standalone hardware specifications.
Silicon carbide MOSFETs are rewriting thermal and efficiency benchmarks for high-frequency industrial chargers. German automotive suppliers and Amazon Robotics fulfillment networks are specifying 98% efficiency targets for new procurement cycles. This semiconductor shift is compressing the performance gap between premium and mid-tier charger tiers.
The EU Green Deal's embodied carbon disclosure requirements are reshaping supplier qualification processes. Industrial charger OEMs must now document Scope 3 emissions for magnetics, enclosures, and cable assemblies. German and Dutch fleet operators are inserting carbon intensity clauses into multi-year charger supply agreements.
Leasing and power-by-the-hour contracts are displacing capital purchase models for charger fleets. Third-party logistics providers in the United States and United Kingdom prefer operational expenditure structures that bundle hardware, installation, and maintenance. This financing pivot favors suppliers with captive service networks over pure hardware manufacturers.
Industrial Battery Charger Market Segmentation
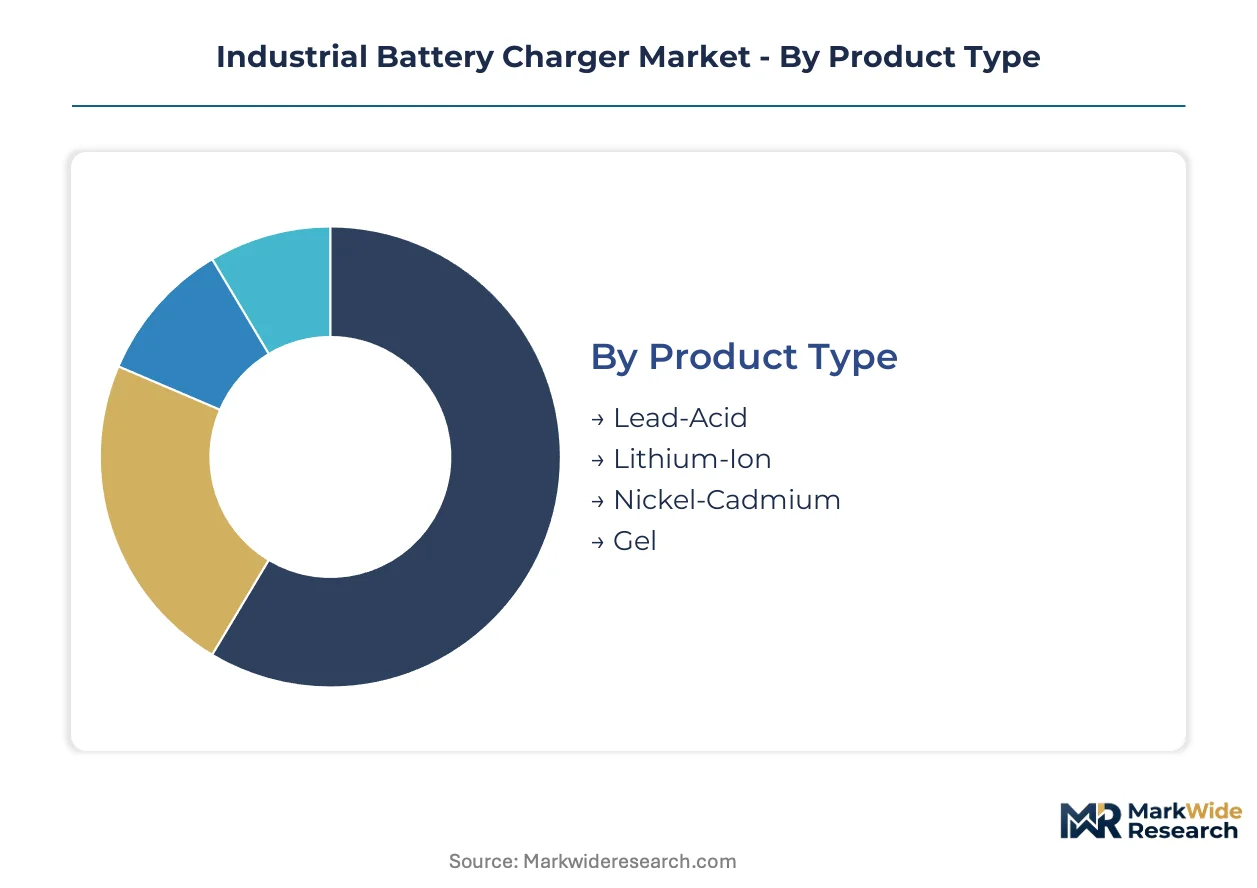
Industrial battery charger procurement decisions split across battery chemistry compatibility, charging speed requirements, and facility infrastructure constraints. Fleet operators prioritize technology segments that minimize equipment downtime while navigating legacy electrical installations.
Product Type:
Capital allocation patterns favor chemistry-specific charger architectures based on fleet replacement timelines and energy density requirements.
- Lead-Acid:Flooded and sealed AGM variants demand constant-voltage charging profiles with temperature compensation. German and US forklift fleets with sunk battery infrastructure drive replacement charger procurement despite lithium-ion migration.
- Lithium-Ion:NMC and LFP chemistries require precision battery management system communication and multi-stage CC-CV algorithms. Amazon Robotics fulfillment centers and automotive assembly lines specify these units for opportunity charging protocols.
- Nickel-Cadmium:Ruggedized chargers serve mining equipment and cold-storage applications where extreme temperature tolerance outweighs energy density tradeoffs.
- Gel:Maintenance-free designs with starved-electrolyte configurations suit remote telecom backup installations and off-grid solar arrays.
Lead-Acid leads on scale; Lithium-Ion leads on momentum.
Technology:
Operational expenditure models now prioritize charging speed and telematics integration over upfront hardware cost.
- Fast Charging:High-current architectures deliver 80% state-of-charge in under one hour through active thermal management. Multi-shift warehousing operations in the United States deploy these systems to eliminate battery swap workflows.
- Solar Charging:MPPT-enabled DC-coupled systems integrate with photovoltaic arrays for off-grid industrial sites. Remote mining camps and agricultural processing facilities in Australia and Chile adopt these configurations.
- Smart Charging:IoT-linked units optimize charge cycles through predictive algorithms and cloud-based fleet analytics. Third-party logistics providers favor subscription-based service models bundling hardware and software.
- Traditional Charging:Transformer-based ferroresonant designs persist in construction equipment yards and small manufacturing facilities with limited capital budgets.
Traditional Charging retains installed base dominance; Smart Charging climbs the fastest as fleet telematics mature.
End User:
Facility electrification timelines and shift intensity determine charger density and specification requirements.
- Manufacturing:Just-in-time assembly lines demand opportunity charging infrastructure with 15-minute partial recharge capability. German automotive suppliers specify 98% efficiency targets for new procurement cycles.
- Warehousing:E-commerce fulfillment centers triple charger density per square meter as autonomous mobile robot fleets expand. OSHA electrical safety mandates govern US installation standards.
- Transportation:Electric bus depots and port electrification projects require megawatt-scale charging infrastructure with grid-stabilization capabilities.
- Construction:Mobile equipment fleets favor portable charger configurations with ruggedized enclosures and generator compatibility.
Warehousing leads on unit volume; Manufacturing leads on specification intensity.
Installation:
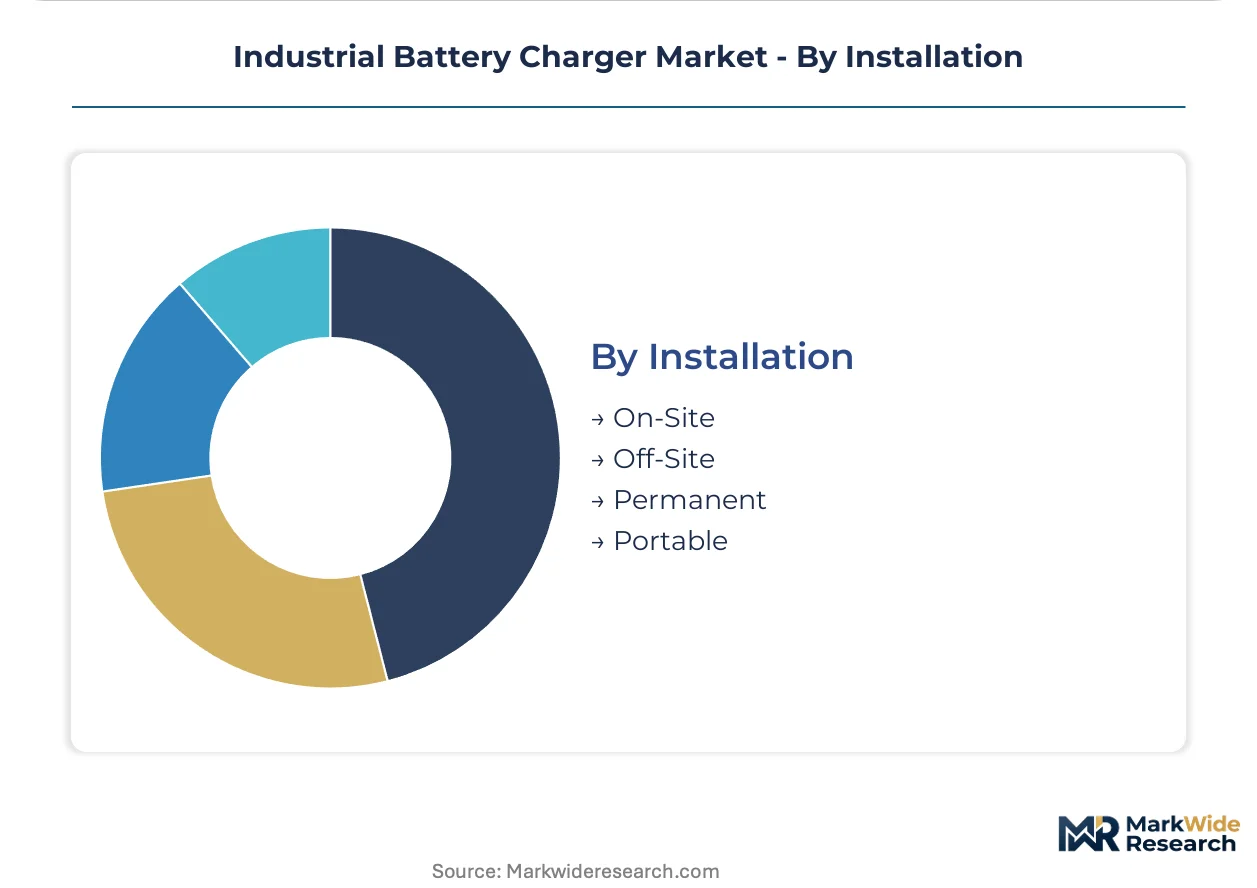
Site electrical capacity and fleet mobility requirements dictate physical deployment architecture.
- On-Site:Hardwired installations with dedicated electrical service support high-throughput operations. European industrial parks accelerate deployment under EU F-Gas Regulation efficiency mandates.
- Off-Site:Centralized charging depots serve distributed fleet operations through battery swap logistics. Mining and forestry applications favor this model for remote equipment staging.
- Permanent:Fixed infrastructure with embedded power distribution dominates manufacturing and warehousing anchor tenants.
- Portable:Wheeled or skid-mounted units enable construction site mobility and emergency backup power applications.
Permanent installations anchor revenue; Portable configurations gain share fastest in construction electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineering talent concentrates in German automotive hubs, Chinese manufacturing clusters, and US industrial corridors, anchoring regional charger development capabilities. Facility electrification timelines diverge sharply across these geographies.
Germany
Automotive assembly lines in Stuttgart and Wolfsburg demand opportunity charging infrastructure with 98% efficiency targets. The EU F-Gas Regulation accelerates phase-out of transformer-based designs across Bavarian and Baden-Württemberg industrial parks. E-commerce fulfillment centers near Leipzig triple charger density as Amazon Robotics fleets expand.
United States
Warehouse automation in Pennsylvania and Ohio drives multi-shift charging infrastructure procurement. OSHA electrical safety mandates govern installation standards across Great Lakes manufacturing corridors. Third-party logistics providers in California prefer operational expenditure models bundling hardware and maintenance.
China
GB standards compliance shapes domestic charger design requirements for lithium-ion architectures. The dual carbon goals policy tightens energy-efficiency mandates in Yangtze River Delta manufacturing hubs. Shenzhen and Dongguan clusters dominate magnetics and thermal management subassembly supply.
India
PLI scheme incentives for industrial automation create first-mover charger deployment in Pune and Chennai automotive hubs. Central Electricity Authority regulations govern grid-interconnection standards for manufacturing facility installations. Construction electrification in Gujarat favors portable charger configurations with generator compatibility.
Japan
METI efficiency standards drive high-frequency charger adoption in Nagoya and Osaka industrial zones. JIS certification requirements extend product development timelines for foreign suppliers targeting automotive supplier networks. Hitachi's electrification portfolio anchors grid-integrated infrastructure across Kanto manufacturing belts.
Industrial Battery Charger Market Vendor Landscape
The competitive structure tilts toward diversified industrial electrification conglomerates with captive power-electronics expertise. Three tiers emerge: premium-tier suppliers with integrated service networks, mid-tier specialists in chemistry-specific architectures, and regional fabricators serving legacy fleet replacement. Consolidation pressure intensifies as lithium-ion transition demands R&D scale. Strategic moves center on backward integration into semiconductor sourcing and geographic expansion through distribution partnerships.
Among diversified industrial electrification groups, ABB and Hitachi occupy positions spanning grid infrastructure through motive power systems. GS Yuasa exemplifies the chemistry-specialist archetype with deep lead-acid system heritage. Delta represents the power-electronics pure-play model, extending semiconductor expertise into high-frequency architectures. Crown Battery and Exide Group anchor North American battery-to-charger integrated supply positions. Micropower and Pro Charging Systems sit within the mid-tier specialist segment serving regional fleet operators. Lester Electrical exemplifies the legacy-focused fabricator archetype with construction and material-handling equipment relationships.
| Leading Market Players |
|---|
| Crown Battery |
| Micropower |
| Delta |
| GS Yuasa |
| Pro Charging Systems |
| ABB |
| Hitachi |
| Lester Electrical |
| Exide Group |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up charger specialists have consolidated regional service networks across the US Midwest and German industrial corridors, tightening pricing discipline while locking in captive aftermarket revenue streams through multi-year service contracts.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-light third-party logistics providers from integrated manufacturing operators. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and telematics integration depth. Cost compression in mid-tier ferroresonant designs is intensifying because silicon carbide component shortages favor high-frequency architectures. Construction equipment yards show highest price sensitivity; automotive assembly lines prioritize efficiency specifications over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon Robotics and automotive Tier 1 suppliers, while distributor networks serve fragmented construction and warehousing accounts. Magnetics and thermal management subassemblies draw from Shenzhen, Dongguan, and Taiwanese manufacturing clusters. Power semiconductor substrates hinge on South Korean and Japanese foundry capacity. Single-source vulnerability in silicon carbide wafer supply creates procurement risk for high-frequency charger tiers. Distribution runs through electrical equipment wholesalers with captive installation service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where lithium-ion transition and 98% efficiency mandates favor suppliers with semiconductor design depth over legacy transformer fabricators.
For Market Incumbents: Hedge against margin erosion in lead-acid replacement cycles by accelerating backward integration into silicon carbide sourcing partnerships. Secure captive magnetics capacity in Taiwan and Vietnam to offset Chinese component concentration risk. For New Entrants and Emerging Players: Mid-sized German automotive suppliers with mixed lithium-ion and lead-acid fleets represent an underserved buyer archetype seeking chemistry-agnostic charging infrastructure. Target opportunity charging retrofit projects in Stuttgart and Wolfsburg assembly corridors. Lead with subscription-based service models bundling hardware and predictive maintenance software. For Investors and Strategic Acquirers: Valuations sit cheapest among power-electronics pure-plays with automotive sector exposure transferable to industrial charger architectures. Five-to-ten-year viability favors suppliers with demonstrated GB standards compliance for China market access. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for transformer-based design obsolescence velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive silicon carbide supply secures margin against EV demand competition from automotive OEMs. |
| Telematics Platform Integration | Cloud-linked charge cycle optimization enables recurring revenue from third-party logistics providers. |
| GB Standards Certification Investment | China market access requires compliance with MIIT efficiency mandates in Yangtze River Delta hubs. |
| Service Network Geographic Expansion | Pune and Chennai automotive clusters under PLI scheme create first-mover charger deployment opportunity. |
| Bi-directional Charging Capability Development | Vehicle-to-facility power flow attracts manufacturing plants with high utility demand charges. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and electrical contractors grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings, customs trade data, OSHA enforcement records, and EU F-Gas Regulation implementation reports. Bottom-up and top-down triangulation cross-checked segment-level unit economics against aggregate market sizing.
Bottom-up modeling of charger deployments by facility type and battery chemistry converged with top-down industrial electrification spending analysis across the projection horizon. Segmentation dimensions included product type, charging technology, end-user industry, and installation architecture. CAGRs were derived from fitted growth curves applied to disclosed procurement volumes and announced automation capex. Forecast inputs incorporated lithium-ion fleet replacement timelines and EU energy-efficiency mandate compliance deadlines.
Inputs from OEM procurement disclosures and regulatory filing databases were available through the study window; gaps in private fleet operator maintenance expenditure data introduce uncertainty bands around aftermarket service revenue projections. Forecasts reflect assumptions about silicon carbide cost curves and warehouse automation adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Yacht Battery Market
Batteries
Seawater Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Japan Battery Market
Batteries
Portable Battery Pack Market
Batteries
Printed Batteries Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Advanced Batteries Market
Batteries
Military Battery Market
Batteries
India Lead-Acid Battery Market
Batteries
Lithium Starters Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Portable Battery Market